
 Train Reservation Software Market | 2026-2036
Train Reservation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Train Reservation Software Market Analytics
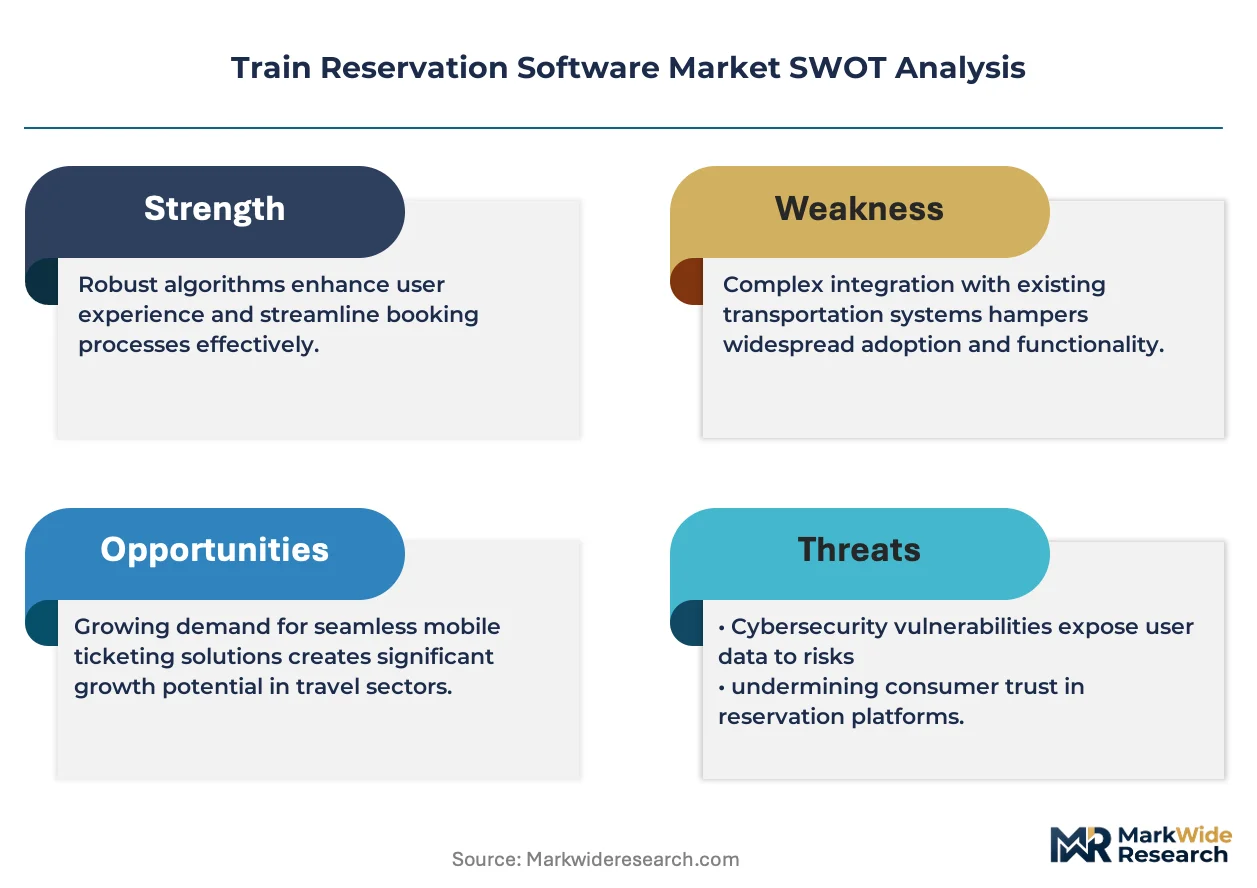
Software engineering talent with legacy mainframe expertise is rotating toward scarce supply as rail operators modernize decades-old reservation infrastructure. Sqills leverages cloud-native architecture to compete for contracts with open-access operators across multiple European networks. Siemens anchors its position through deep integration with signaling and fleet management systems. Thales specializes in cybersecurity-hardened platforms for national rail incumbents.
Train reservation software comprises modular platforms that manage seat inventory, fare construction, payment settlement, and real-time capacity optimization across distributed rail networks. Core systems process transactions through centralized passenger name record databases with sub-second response requirements for peak booking windows. Cloud-based deployment leads structural expansion as operators shed capital-intensive data center commitments. SaaS models for regional and commuter lines represent the fastest-growing revenue pool. On-premise installations persist among high-speed operators with stringent latency and sovereignty requirements, though hybrid architectures now capture the dominant share of new procurement cycles.
The EU Green Deal and F-Gas Regulation indirectly shape demand by channeling public investment toward rail modal shift, while GDPR and the EU AI Act impose data governance and algorithmic transparency obligations on automated pricing engines. National regulators in France, Germany, and Italy enforce interoperability mandates that prevent vendor lock-in and sustain competitive procurement. Stakeholders must monitor how open-access licensing reforms and digital platform regulations alter the balance between integrated incumbents and modular challengers.
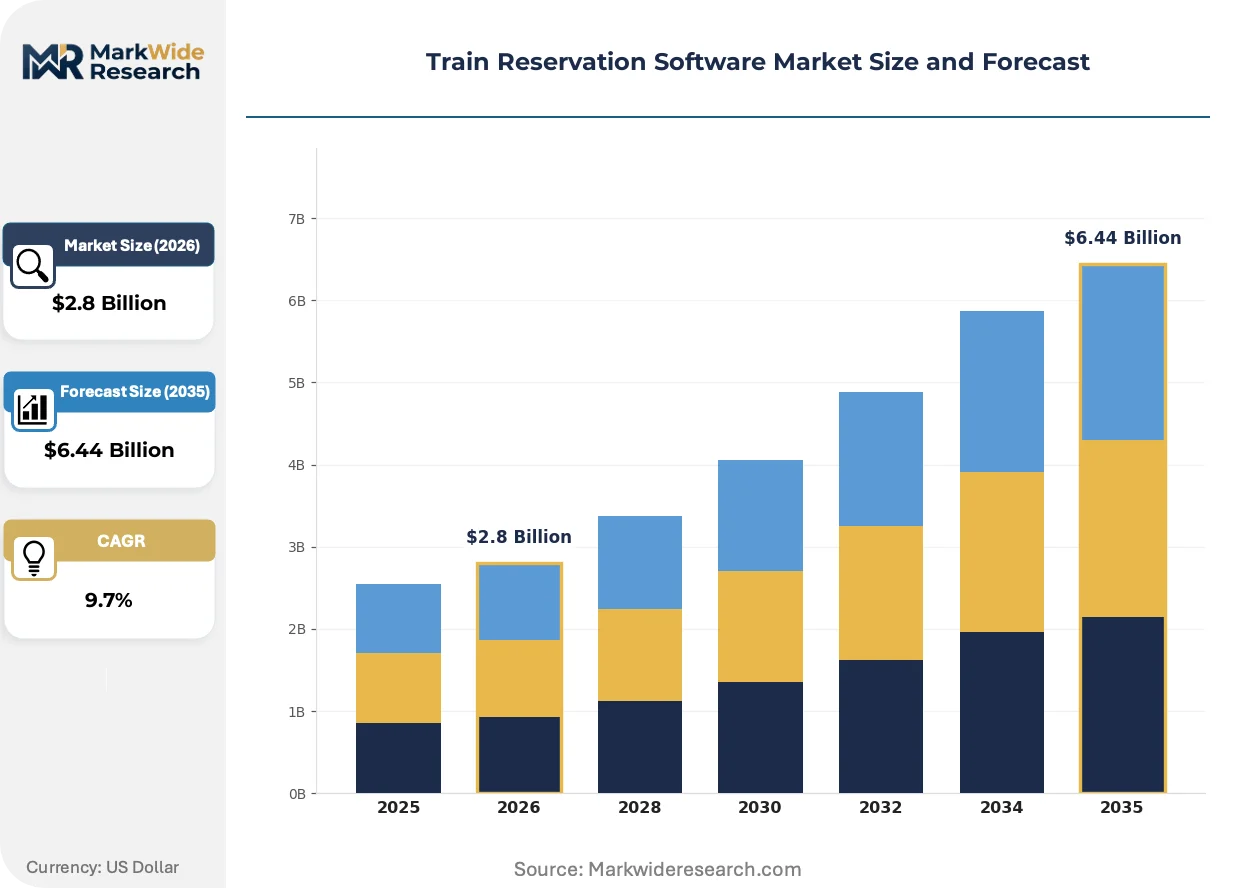
Market Dynamics
Cloud migration is decomposing monolithic reservation architectures as rail operators abandon capital-intensive data center commitments for API-first, modular platforms that interoperate across open-access networks.
Growth Catalysts
- EU Green Deal modal shift mandates:Public investment channels toward rail infrastructure expansion, requiring scalable digital ticketing platforms to handle passenger volume growth across intercity corridors.
- API-first architecture adoption:Open-access rail competition in Western Europe demands interoperable reservation systems that enable multi-operator journey planning and dynamic capacity sharing.
- Germany's open-access licensing reforms:New market entrants require cloud-native reservation infrastructure to compete against incumbent integrated operators, accelerating procurement cycles for modular software vendors.
Market Restraints
- Legacy mainframe skill scarcity:Software engineering talent with decades-old reservation system expertise is rotating toward scarce supply, constraining modernization timelines for state-owned operators.
- High-speed sovereignty requirements:Stringent latency and data residency mandates among premium rail operators perpetuate on-premise installations, limiting pure SaaS penetration in the highest-value segment.
- GDPR algorithmic transparency obligations:Automated pricing engines face compliance friction as rail operators must document decision logic for dynamic fare construction systems.
Strategic Opportunities
- Regional and commuter line SaaS penetration:Smaller operators with limited IT capital represent underserved demand for subscription-based reservation platforms with faster deployment cycles.
- France-Italy-Spain corridor integration:Cross-border high-speed services create white space for reservation systems that harmonize inventory across national booking platforms with disparate technical standards.
- EU AI Act compliance services:Algorithmic auditing and explainability tooling for automated pricing systems emerge as adjacent revenue streams for software vendors with rail domain expertise.
Industry Challenges
- Centrally-managed passenger name record integration:Sub-second response requirements for peak booking windows demand specialized database architecture that few vendors can deliver at scale.
- Interoperability certification timelines:National regulators in France, Germany, and Italy enforce vendor-agnostic standards that prolong procurement cycles and increase pre-revenue engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Reservation Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS User Type: Travel Agencies, Railway Operators, End Consumers, Corporate Clients Functionality Type: Booking Management, Payment Processing, Customer Support, Reporting Tools Integration Level: Third-Party APIs, Payment Gateways, CRM Systems, Inventory Management |
| Companies Covered | Siemens, Sqills, Alstom, Hitachi Rail, Cisco Systems, Huawei Technologies, SAP, CGI, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Reservation Software Market Evolving Landscape
Microservices architecture is fragmenting reservation software into composable components that rail operators can deploy, upgrade, and replace independently rather than accepting monolithic vendor lock-in.
Containerized deployment is decomposing legacy three-tier application stacks into Kubernetes-orchestrated services that scale elastically with booking demand. State-owned operators in Germany and the Netherlands are piloting these architectures for commuter networks. This decomposition enables operators to mix components from competing vendors rather than accepting single-source dependencies.
The EU AI Act imposes documentation and human oversight requirements on automated pricing algorithms that adjust fares based on demand forecasting. Rail operators must maintain audit trails for algorithmic decisions affecting consumer prices. High-speed operators in France and Spain are restructuring their revenue management teams to embed compliance officers alongside data scientists.
Subscription-based procurement is displacing perpetual license models as regional operators prioritize operational expenditure over capital commitments. SaaS vendors now capture multi-year contracts with automatic renewal clauses that were historically rare in public procurement. This shift concentrates most visibly among commuter rail authorities in the United Kingdom and Scandinavia where budget constraints favor predictable monthly costs.
Train Reservation Software Market Segmentation
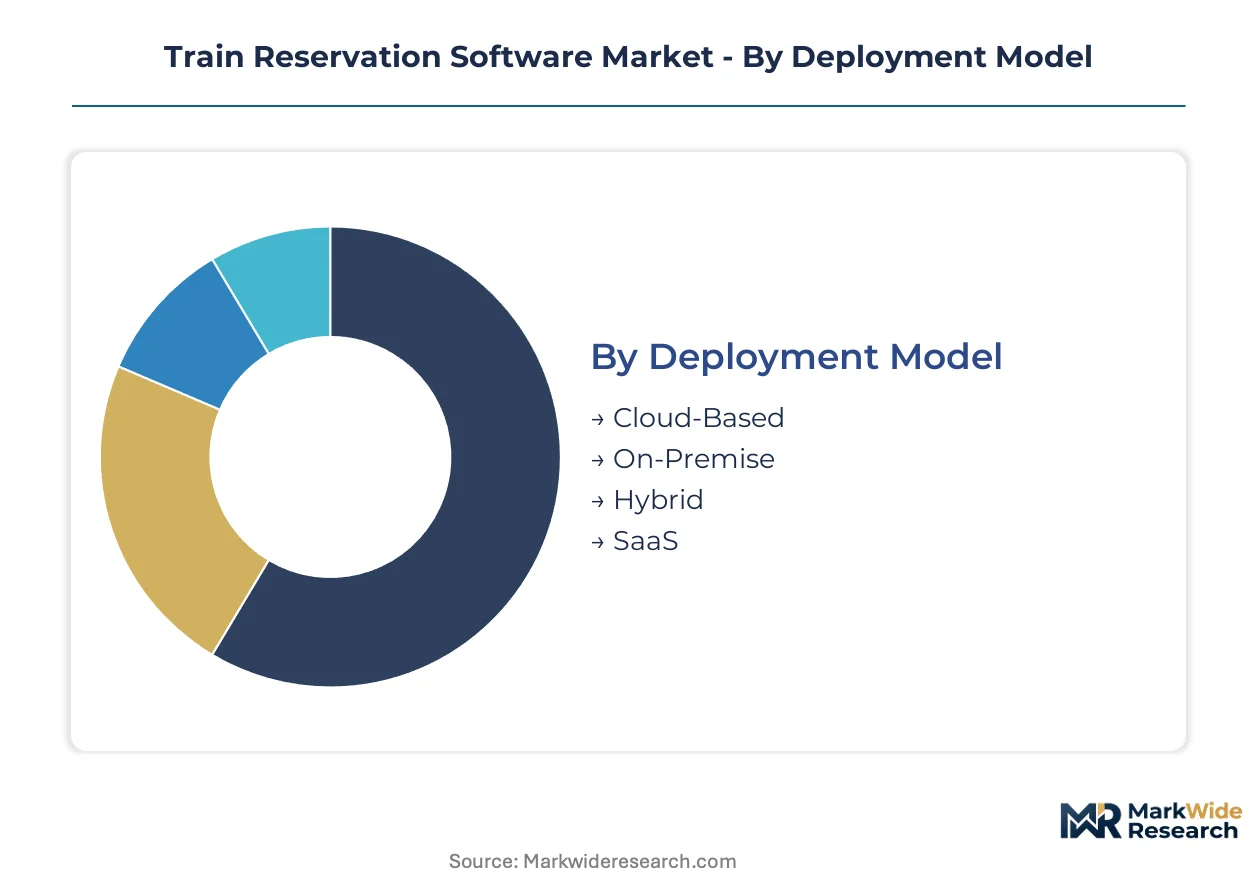
Train reservation software segments reflect divergent procurement priorities across operator types. Deployment architecture and user category determine pricing models, integration complexity, and contract duration.
Deployment Model:
Channel mix splits sharply between capital-intensive on-premise installations and subscription-driven SaaS contracts.
- Cloud-Based:Elastic compute resources scale with booking demand spikes during holiday windows. Western European open-access operators favor this architecture to avoid data center ownership. Demand concentrates among mid-sized regional carriers in the Netherlands and Scandinavia seeking predictable operational expenditure.
- On-Premise:Dedicated hardware installations within operator facilities meet sub-second latency requirements for high-speed reservation systems. French and Spanish premium rail incumbents mandate sovereign data residency. Procurement cycles extend 18-24 months due to infrastructure commissioning.
- Hybrid:Core passenger name record databases remain on-premise while customer-facing interfaces deploy to cloud edge locations. German state-owned operators pilot this architecture for commuter networks balancing latency and flexibility.
- SaaS:Multi-tenant platforms deliver reservation capabilities through monthly subscriptions without infrastructure commitment. United Kingdom regional operators and Scandinavian commuter authorities favor this model for constrained capital budgets.
By volume, SaaS leads among new procurements. By expansion pace, hybrid architectures are climbing the fastest as incumbents modernize without full cloud migration.
User Type:
End-user sophistication determines implementation complexity and support requirements across the customer base.
- Travel Agencies:Consolidated booking platforms aggregate inventory across multiple rail operators into unified interfaces. Agencies in France and Italy require deep API integration to compete with direct operator channels.
- Railway Operators:State-owned and privatized carriers constitute the core revenue pool with multi-year enterprise contracts. These users demand modular architectures permitting component replacement without system-wide overhaul.
- End Consumers:Mobile-first booking interfaces represent the fastest-growing touchpoint volume. Consumer-facing applications prioritize payment friction reduction over back-office functionality depth.
- Corporate Clients:Managed travel programs negotiate bulk pricing and centralized billing across employee rail journeys. Procurement concentrates among multinational firms with headquarters in Germany and Switzerland.
Railway operators dominate contract value. Corporate clients are gaining share fastest as business travel platforms consolidate ground transportation procurement.
Functionality Type:
Module selection reflects operator maturity and digital transformation priorities.
- Booking Management:Core seat inventory allocation with real-time capacity optimization across distributed networks. This module commands premium pricing due to specialized database architecture requirements.
- Payment Processing:Multi-currency settlement engines with PCI-DSS compliance for card-present and card-not-present transactions. Demand intensifies where open-access competition requires harmonized payment across operator boundaries.
- Customer Support:Automated rebooking, disruption management, and multi-channel inquiry handling. Post-pandemic labor shortages accelerate adoption of AI-assisted support tools.
- Reporting Tools:Revenue analytics, demand forecasting dashboards, and regulatory compliance documentation. EU AI Act transparency mandates expand this category's scope for automated pricing systems.
Booking management anchors every implementation. Payment processing is expanding most quickly as operators add digital wallet and buy-now-pay-later options.
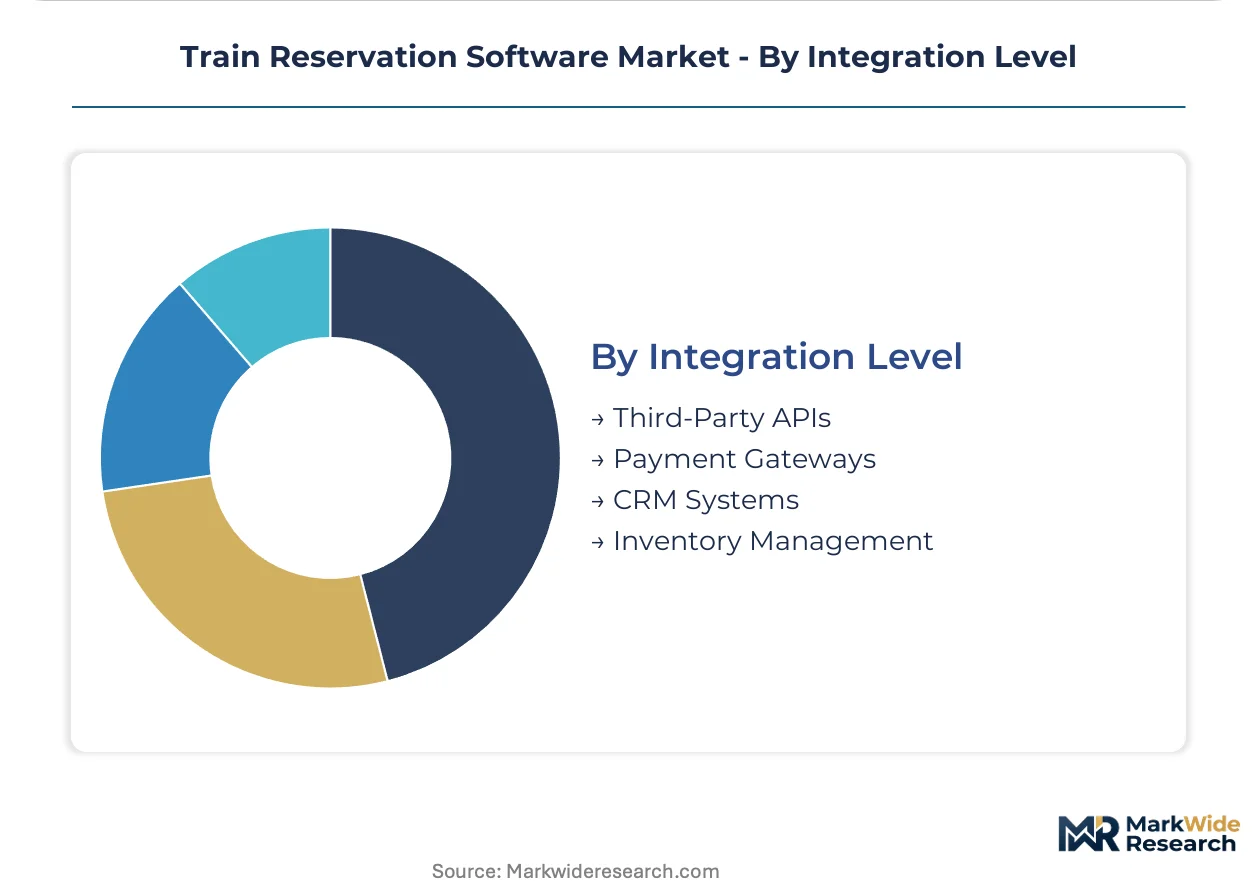
Integration Level:
Interoperability depth determines competitive positioning in fragmented European rail markets.
- Third-Party APIs:Standardized interfaces enabling multi-operator journey planning and ticket fulfillment. France-Italy-Spain corridor projects drive demand for cross-border API harmonization.
- Payment Gateways:Connections to banking networks, digital wallets, and alternative payment methods. Integration complexity rises with multi-currency requirements across Schengen borders.
- CRM Systems:Passenger profile synchronization for loyalty programs and personalized marketing. Premium operators in Spain and Germany prioritize this integration for revenue management sophistication.
- Inventory Management:Real-time seat availability feeds to external distribution channels and partner operators. Open-access licensing reforms in Germany mandate this capability for new market entrants.
Third-party APIs show the steepest adoption curve. Payment gateways maintain the largest installed base across legacy and modernized systems alike.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act shape procurement requirements across Western Europe, where open-access rail competition mandates interoperable reservation systems. Railway operators in Germany, France, Italy, Spain, and the United Kingdom drive modernization cycles as cloud migration accelerates replacement of legacy infrastructure.
Germany
Open-access licensing reforms under KBA supervision create procurement opportunities for modular software vendors competing against incumbent integrated operators. Deutsche Bahn's digital transformation programs prioritize hybrid architectures balancing latency requirements with cloud flexibility. Berlin-Brandenburg and Bavaria host pilot deployments for containerized reservation systems on commuter networks.
France
ANSM interoperability mandates prevent vendor lock-in and sustain competitive procurement for national rail incumbents. The EU Green Deal channels public investment toward high-speed corridor expansion requiring scalable ticketing platforms. SNCF's technology procurement concentrates in Île-de-France, where premium operators mandate sovereign data residency for core passenger databases.
Italy
Trenitalia's modernization investments respond to EU AI Act documentation requirements for automated pricing algorithms. Cross-border corridor integration with France and Spain creates demand for reservation systems harmonizing inventory across national booking platforms. Lombardy and Emilia-Romagna clusters concentrate regional operator procurement for SaaS-based commuter solutions.
Spain
Renfe's revenue management teams embed compliance officers alongside data scientists to meet algorithmic transparency obligations. High-speed operators restructure pricing engines to maintain audit trails for dynamic fare construction systems. Madrid and Catalonia anchor deployment of cybersecurity-hardened platforms for premium rail services.
United Kingdom
Regional commuter authorities favor subscription-based reservation platforms with predictable monthly costs over capital-intensive perpetual licenses. Department for Transport procurement guidelines accelerate SaaS adoption among budget-constrained operators. Greater London and Northern England clusters concentrate multi-year contracts with automatic renewal clauses previously rare in public procurement.
Train Reservation Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in train reservation software procurement. Siemens and Thales anchor the upper tier through deep integration with signaling and fleet management ecosystems, while Sqills occupies the modular challenger position with cloud-native architectures. Strategic differentiation concentrates on API-first interoperability for open-access networks versus cybersecurity-hardened sovereignty for national incumbents. Competitive moves emphasize vertical integration into adjacent rail infrastructure and geographic expansion through corridor integration projects.
Within the integrated systems tier, Siemens AG exemplifies the signaling-anchored archetype through its German industrial heritage, while Thales S.A. represents the defense-technology crossover with French regulatory specialization. Sqills B.V. occupies the cloud-native challenger position among Netherlands-based software vendors. These three entities collectively illustrate how procurement splits between incumbent-integrated and modular-disruptor archetypes across European rail networks.
| Leading Market Players |
|---|
| Siemens |
| Sqills |
| Alstom |
| Hitachi Rail |
| Cisco Systems |
| Huawei Technologies |
| SAP |
| CGI |
| Thales |
| Others |
Value Network & Pricing Analysis
Long-term enterprise contracts with automatic renewal clauses lock in multi-year revenue visibility for reservation software vendors while insulating state-owned operators from spot procurement volatility. German and French rail incumbents favor these structures to secure scarce engineering talent for legacy modernization programs.
Pricing Analysis
Western European procurement commands 40-60% premiums over Eastern European deployments due to GDPR compliance overhead and algorithmic transparency mandates under the EU AI Act. Pricing stratifies across sovereign-hybrid, standard cloud-native, and economy SaaS tiers based on latency requirements and data residency specifications. Cost compression in the SaaS tier intensifies as containerized deployment lowers infrastructure barriers for new entrants. Regional commuter authorities in Scandinavia exhibit highest price sensitivity, while French high-speed operators prioritize sovereign compliance over cost minimization.
Supply Chain Analysis
Legacy mainframe expertise scarcity in Germany, France, and the United Kingdom creates talent chokepoints that extend modernization timelines for state-owned operators. Cloud infrastructure draws from hyperscaler facilities in Ireland, the Netherlands, and Germany, while specialized database architecture feeds from a concentrated vendor base in France and Germany. Single-source vulnerability persists for sub-second passenger name record systems where few vendors deliver at scale. Distribution runs through direct enterprise sales teams for national incumbents, with channel partners penetrating regional and commuter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native disruption is accelerating replacement cycles as open-access rail competition mandates API-first interoperability, creating procurement windows that favor modular challengers over integrated incumbents.
For Market Incumbents: Fortify hybrid architecture offerings to retain high-speed operators with sovereign data residency requirements. Deepen integration with signaling and fleet management ecosystems to raise switching costs against Sqills and other cloud-native entrants. Invest in compliance tooling for EU AI Act algorithmic documentation to differentiate from modular competitors lacking rail domain depth. For New Entrants and Emerging Players: CE marking fast-track for cybersecurity-hardened platforms opens procurement channels with French and Spanish national incumbents. Target United Kingdom regional commuter authorities with subscription-based models that convert capital expenditure to operational expenditure. Lead with API-first demonstrations on Germany's open-access networks where interoperability mandates level the competitive field. For Investors and Strategic Acquirers: Cloud-native specialists with proven containerized deployments represent the most defensible acquisition archetype as incumbents seek modular capabilities without organic buildout. Long-term viability hinges on corridor integration projects spanning France-Italy-Spain high-speed networks. Monitor KBA open-access licensing reform velocity as the signal indicating procurement cycle acceleration or deceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Platform Migration | Kubernetes-orchestrated reservation services enable German commuter networks to scale elastically with demand spikes. |
| API-First Architecture Certification | Interoperability validation under ANSM guidelines secures procurement eligibility for France's open-access corridors. |
| Algorithmic Compliance Tooling | Audit trail automation for EU AI Act documentation differentiates vendors serving Trenitalia and Renfe pricing systems. |
| Hybrid Sovereignty Deployment | On-premise core databases with cloud edge interfaces balance SNCF latency requirements with operational flexibility. |
| SaaS Penetration in Regional Commuter Lines | Subscription models capture United Kingdom authorities seeking predictable monthly costs over capital-intensive licenses. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, operator procurement disclosures, and vendor contract announcements to establish market sizing boundaries. Primary interviews engaged rail operator CTOs, IT procurement officers, platform integration specialists, and open-access licensing regulators across Germany, France, Italy, Spain, and the United Kingdom. Secondary validation drew from KBA authorization records, ANSM interoperability certifications, EU Green Deal investment trackers, and SEC filings of listed rail technology vendors. Bottom-up deployment counts triangulate against top-down infrastructure investment flows.
Segmentation dimensions modeled include deployment architecture, operator type, functionality module, and integration complexity across the projection horizon. CAGRs derive from replacement cycle analysis of legacy mainframe systems against cloud-native adoption curves. Forecast inputs incorporate open-access licensing reform timelines, GDPR enforcement intensity, and EU AI Act implementation phasing.
Decision-makers should treat outputs as directional under assumptions of continued modal shift investment and stable interoperability regulatory frameworks; material deviation in public procurement budgets or certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as Germany's KBA licensing velocity and France's ANSM certification backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Polling Software Market
Software & Services
Tag Management Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Database Software Market
Software & Services
Mining Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Global Archiving Software Market
Software & Services
Global Localization Software Market
Software & Services
Email Marketing Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Category Management Software Market
Software & Services
Global Virtual Desktop Market