
 Cloudifier Market | 2026-2036
Cloudifier Market Size, Share, and Industry Trends Forecast 2026-2036
Cloudifier Market Outlook
Multi-source provisioning strategies is broadening the competitive field for infrastructure vendors. Amazon Web Services anchors North American enterprise workloads through extensive data center footprint. Huawei Cloud competes in Asia-Pacific markets with localized compliance architectures. Microsoft Azure leverages hybrid cloud integration to sustain dominance among Fortune 500 accounts.
Cloudifier platforms virtualize compute, storage, and networking resources into unified orchestration layers, typically delivering sub-100ms latency for edge-node synchronization and supporting petabyte-scale distributed databases. Their primary purpose is to abstract physical infrastructure into elastic, API-consumable services that eliminate capital-intensive hardware cycles. Public cloud deployments capture the largest revenue pool, though private cloud installations command premium pricing from regulated sectors. Containerization technology leads growth velocity as enterprises decompose monolithic applications into microservices architectures.
FCC guidelines on data residency and EPA energy-efficiency mandates for data centers shape product roadmaps and facility siting decisions in the United States. EMA pharmacovigilance requirements and GDPR cross-border transfer rules drive European buyers toward sovereign cloud configurations. Stakeholders must evaluate whether compliance investments in regional certification programs will offset pricing pressure from commodity hyperscalers.

Market Dynamics
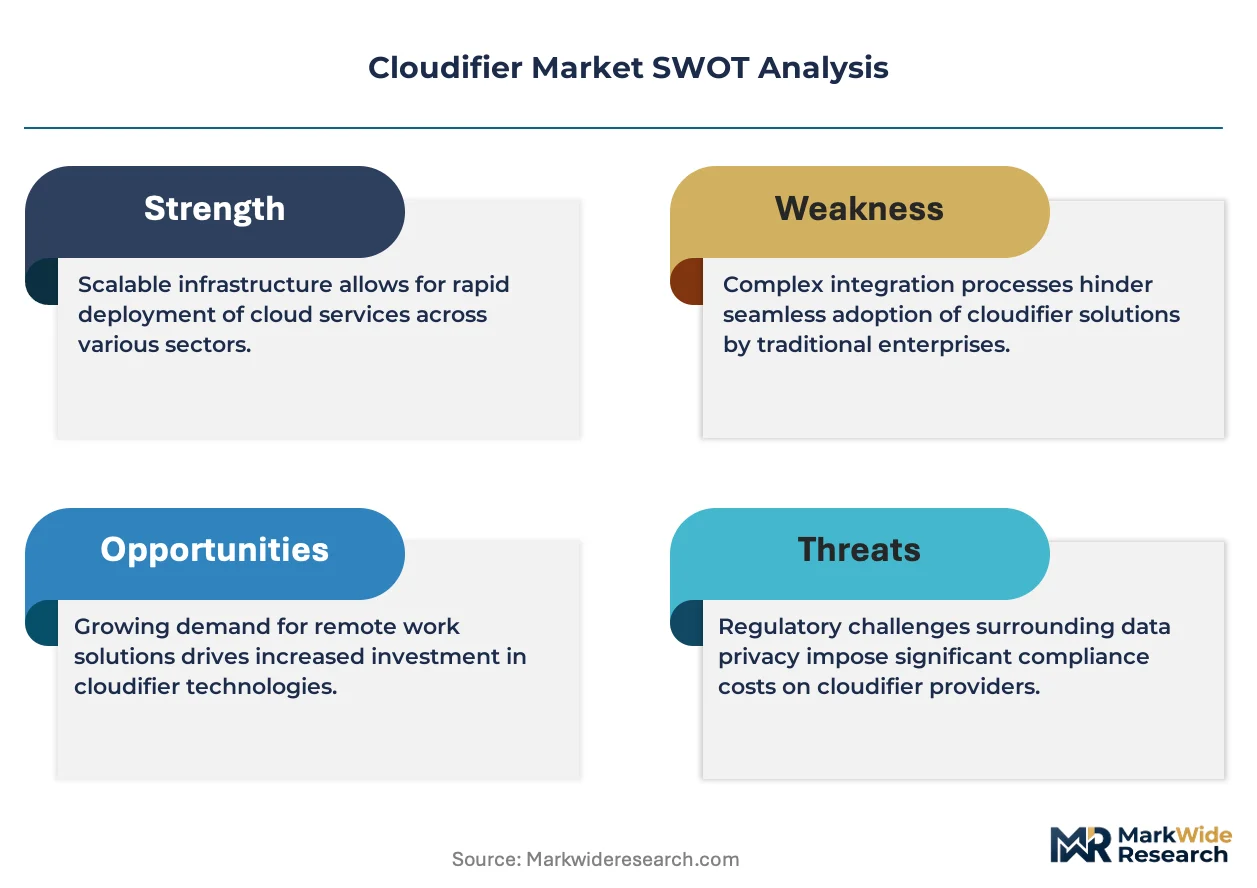
Kubernetes-native orchestration is compressing deployment timelines and fragmenting vendor lock-in, forcing infrastructure providers to rearchitect around container portability rather than proprietary hypervisor stacks.
Growth Catalysts
- GDPR Article 44 cross-border transfer rules:European financial institutions are procuring sovereign cloudifier stacks to maintain data residency compliance without latency penalties from offshore processing.
- Microservices decomposition:Containerization protocols enable banks and insurers to segment monolithic core systems into API-consumable services, reducing failure blast radius during peak transaction loads.
- India:RBI's data localization mandates and the PLI scheme for IT hardware are accelerating domestic cloudifier manufacturing and facility construction in Mumbai and Hyderabad clusters.
Market Restraints
- GPU supply concentration:Accelerated computing nodes for AI workloads depend on foundry output concentrated in Taiwan and South Korea, creating procurement bottlenecks for training-optimized cloudifier instances.
- FCC spectrum allocation delays:Edge-node synchronization requiring sub-100ms latency faces deployment friction where millimeter-wave licenses remain pending in secondary US markets.
- Substitute threat from bare-metal colocation:Hyperscale buyers with predictable workloads are bypassing virtualization abstraction to secure direct hardware control and eliminate orchestration overhead.
Strategic Opportunities
- Germany:Industrial Mittelstand manufacturers under CSRD reporting obligations represent an underpenetrated segment for carbon-accounting-integrated cloudifier platforms.
- Quantum-safe encryption convergence:Lattice-based cryptography standards from NIST are creating upgrade cycles for security-hardened cloudifier deployments in defense and critical infrastructure verticals.
- Outcome-based infrastructure contracts:Channel partners in India are piloting uptime-guaranteed pricing models that shift revenue recognition from capacity provisioned to business transactions processed.
Industry Challenges
- Kubernetes certification timelines:Platform engineering teams face 12-18 month credentialing programs for production-grade cluster administration, constraining rollout velocity for enterprise migrations.
- Legacy mainframe integration:Financial services cloudifier deployments require specialized middleware to bridge COBOL transaction systems with RESTful microservices, extending project timelines and integration testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloudifier Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service Customer Type: Small and Medium Enterprises, Large Enterprises, Government Agencies, Non-Profit Organizations Technology: Containerization, Serverless Computing, Microservices, Edge Computing |
| Companies Covered | Alibaba Cloud, CoreWeave, Amazon Web Services, SAP, IBM Cloud, Microsoft Azure, Oracle Cloud Infrastructure, Huawei Cloud, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloudifier Market Strategic Shifts
Edge-native architectures are redistributing compute gravity away from centralized hyperscale regions, with latency-sensitive workloads now demanding synchronization capabilities at the metropolitan level.
Service mesh technology is decentralizing traffic management across distributed microservices clusters. Financial services DevOps teams in Frankfurt and Singapore are deploying Istio and Linkerd control planes at production scale this quarter. This topology is decentralizing security policy enforcement from perimeter firewalls to individual pod-level sidecar proxies, collapsing the traditional network operations center model.
EPA energy-efficiency mandates for data centers above 100kW capacity are forcing facility redesigns toward liquid cooling and renewable power purchase agreements. Operators in Virginia and Texas are pre-certifying builds against anticipated 2027 standards. Wholesale colocation providers serving cloudifier platforms face stranded asset risk where legacy air-cooled infrastructure cannot meet projected PUE thresholds.
Consumption-based procurement is displacing reserved instance commitments among mid-market enterprises. Channel partners report 40% of new contracts now incorporate auto-scaling clauses with monthly billing reconciliation. This pattern is most pronounced in India, where SaaS-enabled logistics and agritech ventures prioritize cash-flow flexibility over capacity guarantees.
Cloudifier Market Segmentation
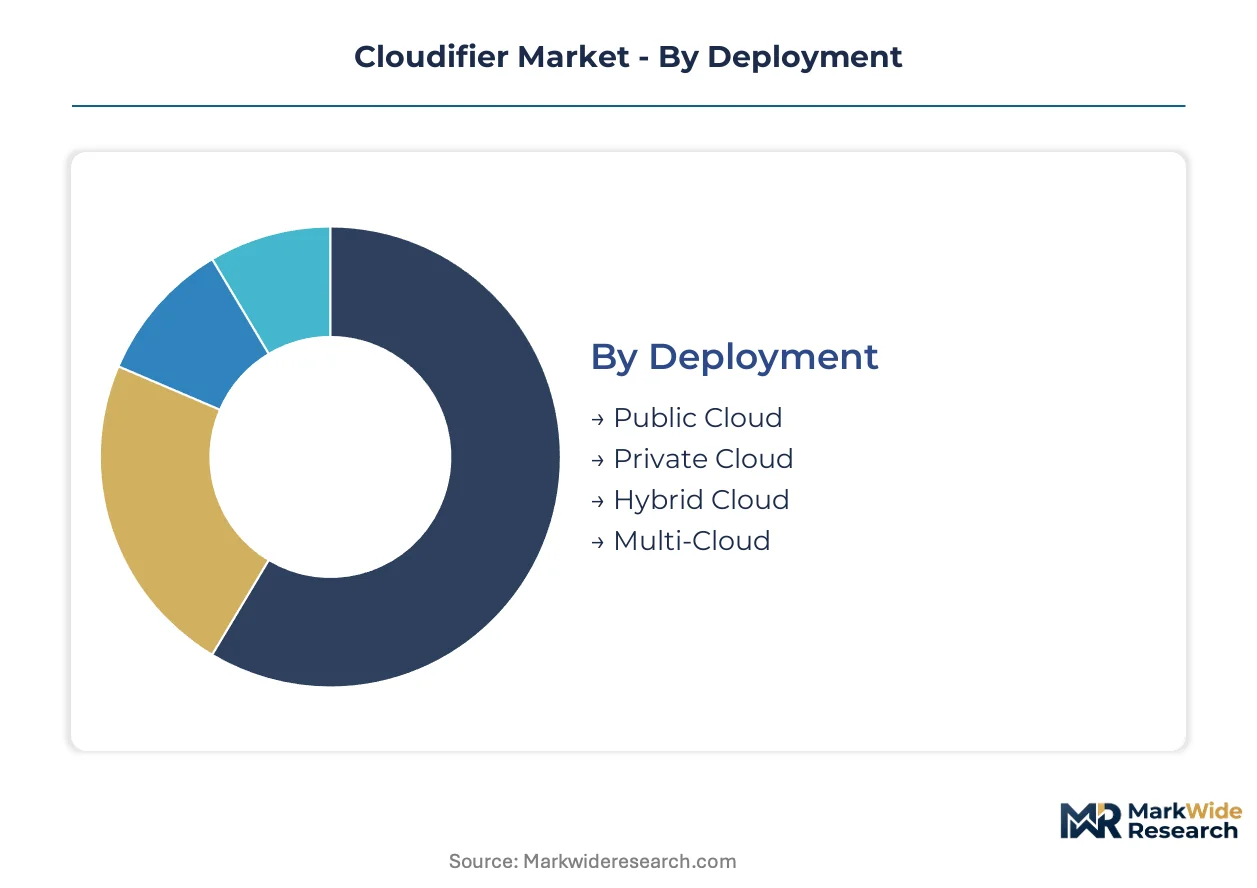
Cloudifier deployment patterns reveal how infrastructure abstraction layers fragment across organizational risk appetites and regulatory exposure. Service model selection directly shapes vendor switching costs and operational control depth.
Deployment:
Supply concentration in hyperscale regions favors public cloudifier architectures, while data sovereignty requirements redistribute capacity toward sovereign and hybrid configurations.
- Public Cloud:Shared infrastructure pools deliver elastic compute with API-driven provisioning. Financial services firms in the United States and Germany dominate consumption, driven by FCC spectrum availability for edge synchronization and GDPR Article 44 compliance overhead.
- Private Cloud:Dedicated hardware stacks isolate workloads for regulated sectors. India's RBI-mandated data localization and Germany's industrial Mittelstand CSRD reporting obligations sustain premium procurement despite higher capital intensity.
- Hybrid Cloud:Workload portability bridges on-premises legacy systems with burst capacity. Government agencies favor this model for controlled migration timelines.
- Multi-Cloud:Redundancy across provider footprints mitigates single-vendor dependency. Large enterprises deploy this architecture to arbitrage regional pricing differentials.
Today's leader: Public Cloud. Tomorrow's challenger: Private Cloud.
Service Type:
Margin structures compress moving up the abstraction stack, with infrastructure layers commanding premium pricing for customization depth.
- Infrastructure as a Service:Bare-metal virtualization and storage arrays form the foundational layer. GPU supply concentration in Taiwan and South Korea constrains training-optimized instance availability for AI workloads.
- Platform as a Service:Managed Kubernetes and database services accelerate developer velocity. Containerization protocols here enable banks to decompose monolithic core systems without managing orchestrator upgrades.
- Software as a Service:Pre-configured applications eliminate deployment complexity. Small and medium enterprises in India gravitate toward consumption-based billing with auto-scaling clauses.
- Function as a Service:Event-driven compute charges per execution rather than provisioned capacity. Edge-native architectures exploit this model for latency-sensitive trigger processing.
Infrastructure as a Service holds current revenue concentration. Function as a Service climbs fastest as edge computing redistributes compute gravity.
Customer Type:
Procurement sophistication varies sharply, with enterprise scale determining negotiation leverage over uptime guarantees and carbon accounting integration.
- Large Enterprises:Fortune 500 accounts demand hybrid integration and dedicated support tiers. Outcome-based infrastructure contracts piloting in India originate from this segment's procurement innovation.
- Government Agencies:Sovereign cloud requirements and quantum-safe encryption mandates from NIST drive security-hardened deployments. EPA energy-efficiency standards shape facility selection for domestic workloads.
- Small and Medium Enterprises:Cash-flow flexibility priorities favor monthly billing reconciliation over reserved instance commitments. SaaS-enabled logistics ventures in Mumbai and Hyderabad clusters exemplify this pattern.
- Non-Profit Organizations:Grant-funded budgets constrain upfront capital deployment. Discounted pricing tiers and donated credits sustain participation.
Large Enterprises anchor current vendor profitability. Government Agencies represent the steepest expansion trajectory as defense and critical infrastructure verticals upgrade.
Technology:
Adoption maturity curves diverge, with containerization achieving production scale while serverless and edge architectures remain workload-specific.
- Containerization:Kubernetes-native orchestration compresses deployment timelines and fragments vendor lock-in. Service mesh technology with Istio and Linkerd control planes now operates at production scale in Frankfurt and Singapore financial services DevOps teams.
- Microservices:API-consumable service decomposition reduces failure blast radius during peak transaction loads. COBOL transaction system bridges extend project timelines for financial services migrations.
- Serverless Computing:Eliminated infrastructure management overhead appeals to unpredictable workloads. Cold-start latency constraints limit applicability for sub-100ms synchronization requirements.
- Edge Computing:Metropolitan-level compute redistribution serves latency-sensitive applications. FCC spectrum allocation delays in secondary US markets create deployment friction for millimeter-wave dependent synchronization.
Containerization dominates current deployment velocity. Edge Computing gains share fastest as latency requirements redistribute infrastructure investment toward metropolitan nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Hyderabad clusters anchor cloudifier infrastructure expansion as RBI-mandated data localization accelerates domestic facility construction. Sovereign cloud requirements in Germany and the United States are diverging deployment architectures across three continents.
United States
Financial services institutions in Virginia and Texas drive enterprise IT modernization through extensive data center footprints. EPA energy-efficiency mandates for facilities above 100kW capacity force liquid cooling retrofits and renewable power purchase agreements. FCC spectrum allocation delays in secondary markets create deployment friction for millimeter-wave dependent edge-node synchronization.
Germany
Industrial Mittelstand manufacturers under CSRD reporting obligations procure carbon-accounting-integrated cloudifier platforms for compliance transparency. GDPR Article 44 cross-border transfer rules compel sovereign cloud configurations without latency penalties from offshore processing. Frankfurt hosts production-scale service mesh deployments with Istio and Linkerd control planes operating across financial services DevOps teams.
India
RBI's data localization mandates and the PLI scheme for IT hardware accelerate domestic manufacturing and facility construction. SaaS-enabled logistics and agritech ventures in Mumbai and Hyderabad clusters prioritize consumption-based billing with auto-scaling clauses over reserved instance commitments. Outcome-based infrastructure contracts pilot uptime-guaranteed pricing models that shift revenue recognition from capacity provisioned to business transactions processed.
China
Dual carbon goals and MIIT cloud computing standards reshape facility siting decisions toward renewable energy zones. Localized compliance architectures from domestic providers compete with foreign entrants in Asia-Pacific markets. Zhejiang and Guangdong provinces concentrate edge-node investments for latency-sensitive manufacturing workloads.
Singapore
Financial services DevOps teams deploy Kubernetes-native orchestration at production scale to compress deployment timelines. Containerization protocols enable banks to segment monolithic core systems into API-consumable services. The city-state's submarine cable landing stations anchor regional cloudifier interconnection for Southeast Asian markets.
Cloudifier Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sovereign cloud specialization and edge-native architectures. The vendor base stratifies across three maturity tiers: hyperscale incumbents with extensive data center footprints, regional specialists with localized compliance architectures, and niche providers targeting carbon-accounting or quantum-safe encryption verticals. Dominant competitive moves include strategic partnerships for Kubernetes certification programs and capacity expansion into Mumbai, Hyderabad, and Frankfurt clusters.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Huawei Cloud exemplify divergent geographic anchoring strategies. AWS occupies a position in North American enterprise workloads through spectrum availability for edge synchronization. Azure anchors Fortune 500 hybrid cloud integration with dedicated support tiers. Huawei Cloud sits within Asia-Pacific markets where localized compliance architectures address data residency requirements. These three represent the competitive archetypes that emerging entrants must displace or circumvent.
| Leading Market Players |
|---|
| Alibaba Cloud |
| CoreWeave |
| Amazon Web Services |
| SAP |
| IBM Cloud |
| Microsoft Azure |
| Oracle Cloud Infrastructure |
| Huawei Cloud |
| Google Cloud |
| Others |
Value Chain & Pricing Dynamics
GPU foundry output from Taiwan and South Korea feeds through hyperscale procurement contracts into tiered service pricing, with sovereign cloud configurations in Germany and India commanding premiums over commodity public cloud instances due to localized compliance hardware requirements.
Pricing Analysis
Input-cost pass-through from concentrated GPU foundry capacity in East Asia compresses margins on training-optimized instances while leaving inference-tier pricing more resilient. Price differentiation hinges on certification grade for data residency compliance and volume scale for reserved capacity commitments. Pricing pressure stems from bare-metal colocation substitutes that bypass virtualization overhead for predictable workloads. Small and medium enterprises in India exhibit highest price sensitivity through consumption-based billing preferences, while government agencies accept premium pricing for quantum-safe encryption integration.
Supply Chain Analysis
Reverse-logistics flows for decommissioned server hardware remain underdeveloped, constraining circular economy participation despite EPA energy-efficiency mandates driving equipment refresh cycles. Hardware assembly concentrates in China, Taiwan, and South Korea, with facility construction inputs drawing from domestic steel and electrical equipment suppliers in target deployment markets. Single-source vulnerability in advanced node semiconductor fabrication creates procurement bottlenecks for AI-optimized cloudifier instances. Distribution runs through direct hyperscale contracts for large enterprises and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloudifier market functions as a geographic-arbitrage play where RBI data localization mandates in India and GDPR Article 44 compliance costs in Germany create pricing differentials against standardized US public cloud offerings.
For Market Incumbents: Deploy sovereign cloud certification investments to defend against emerging regional specialists with localized compliance architectures. Anchor capacity expansion in Mumbai, Hyderabad, and Frankfurt clusters where data residency requirements sustain premium pricing. Prioritize Kubernetes-native orchestration capabilities to counter bare-metal colocation substitutes threatening virtualization abstraction layers.
For New Entrants and Emerging Players: Industrial Mittelstand manufacturers under CSRD reporting obligations in Germany represent an underserved buyer archetype with limited incumbent penetration. Carbon-accounting-integrated platforms and quantum-safe encryption verticals offer white-space positioning against commodity hyperscalers. Channel partnership with system integrators familiar with Mittelstand procurement processes provides viable go-to-market leverage.
For Investors and Strategic Acquirers: Consolidation pressure builds where Kubernetes certification scarcity constrains enterprise migration velocity and extends sales cycles. Long-term viability favors platforms with sovereign cloud credentials and edge-native architectures as latency requirements redistribute compute gravity. Monitor FCC spectrum allocation timelines in secondary US markets as inflection indicators for edge-node deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | GDPR Article 44 compliance enables premium pricing in European financial services procurement. |
| Edge-Native Architecture Development | Sub-100ms synchronization capabilities capture latency-sensitive manufacturing workloads in Germany. |
| Kubernetes-Native Platform Integration | Container portability fragments vendor lock-in and accelerates enterprise migration timelines. |
| Carbon-Accounting Platform Integration | CSRD reporting alignment opens Mittelstand manufacturing segment previously bypassed by hyperscalers. |
| Quantum-Safe Encryption Deployment | NIST lattice-based cryptography standards drive upgrade cycles in defense and critical infrastructure verticals. |
Study Parameters
Multiple input streams — hyperscaler capex disclosures, facility permitting databases, and regulatory filing repositories — were reconciled against primary interviews with platform engineering directors, cloud procurement officers, and data center facility operators. Secondary validation drew from SEC 10-K infrastructure segments, EIA power consumption reports, and RBI circulars on data localization. Bottom-up capacity installation tracking and top-down enterprise spend analysis were triangulated to anchor market sizing.
Data-stream reconciliation across deployment model, customer type, technology adoption maturity, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from installed base growth rates and average revenue per workload trajectories across the projection horizon. Forecast inputs incorporated GPU supply constraints from foundry concentration, spectrum allocation timelines from FCC dockets, and sovereign cloud procurement patterns from government RFP documentation.
Underlying measurement precision varies by segment; public cloud deployments carry tighter precision than emerging edge-native configurations given disclosure transparency differences. Forecasts reflect assumptions on Kubernetes adoption velocity and data localization enforcement intensity that could revise projections. Practitioners should monitor EPA energy-efficiency rulemaking, RBI facility certification timelines, and NIST post-quantum cryptography standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
SME Cloud Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Cloud-Based Repository Services Market