
 Warranty Management System Market | 2026-2036
Warranty Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Warranty Management System Market Outlook
The automotive sector is pivoting toward integrated warranty lifecycle platforms that connect dealer networks, suppliers, and finance operations in real time. Oracle Corporation leverages its enterprise cloud footprint to anchor warranty data across multi-tier supply chains. SAP SE sustains competitive depth through embedded ERP-native warranty modules that reduce implementation friction for industrial manufacturers. Tavant Technologies specializes in AI-driven claims analytics, differentiating its platform by automating fraud detection and reserve forecasting for insurers and OEMs.
A warranty management system orchestrates the full lifecycle of product guarantees, from registration and claims adjudication through supplier chargeback and predictive failure analysis, typically operating through API-connected modules that ingest IoT sensor streams and service event logs. Cloud-based solutions now lead deployment preferences as manufacturers seek elastic capacity for seasonal claim spikes and distributed dealer access, while on-premise systems retain footholds in defense and regulated industrial settings where data sovereignty constraints apply. The electronics vertical represents the fastest-expanding segment as semiconductor and consumer device makers confront compressed product cycles and complex international return logistics.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements on automated warranty decision systems deployed across European operations. The U.S. Magnuson-Moss Warranty Act and state-level lemon laws create fragmented compliance terrain that vendors must navigate through configurable rule engines. ISO 9001 quality management standards and sector-specific automotive IATF 16949 certifications further shape platform functionality requirements. Stakeholders must monitor evolving digital product passport mandates and cross-border data flow restrictions to align platform architecture with emerging compliance obligations.
Market Dynamics
Automotive OEMs are consolidating warranty data onto unified cloud platforms to satisfy the EU Green Deal's digital product passport mandates while compressing supplier recovery cycles from months to weeks.
Growth Catalysts
- EU Green Deal traceability mandates:Equipment manufacturers across Germany and France must maintain granular warranty records linked to product lifecycle data, forcing platform upgrades that embed IoT sensor integration and blockchain-verified claim trails.
- AI-driven fraud detection:Insurers and OEMs in the United States are deploying machine learning models that automate claims adjudication and reserve forecasting, reducing manual review overhead by flagging anomalous repair patterns in real time.
- Electronics vertical expansion:Semiconductor and consumer device makers in South Korea and Taiwan confront compressed product cycles and complex international return logistics, driving demand for warranty systems that handle multi-jurisdiction claim routing.
Market Restraints
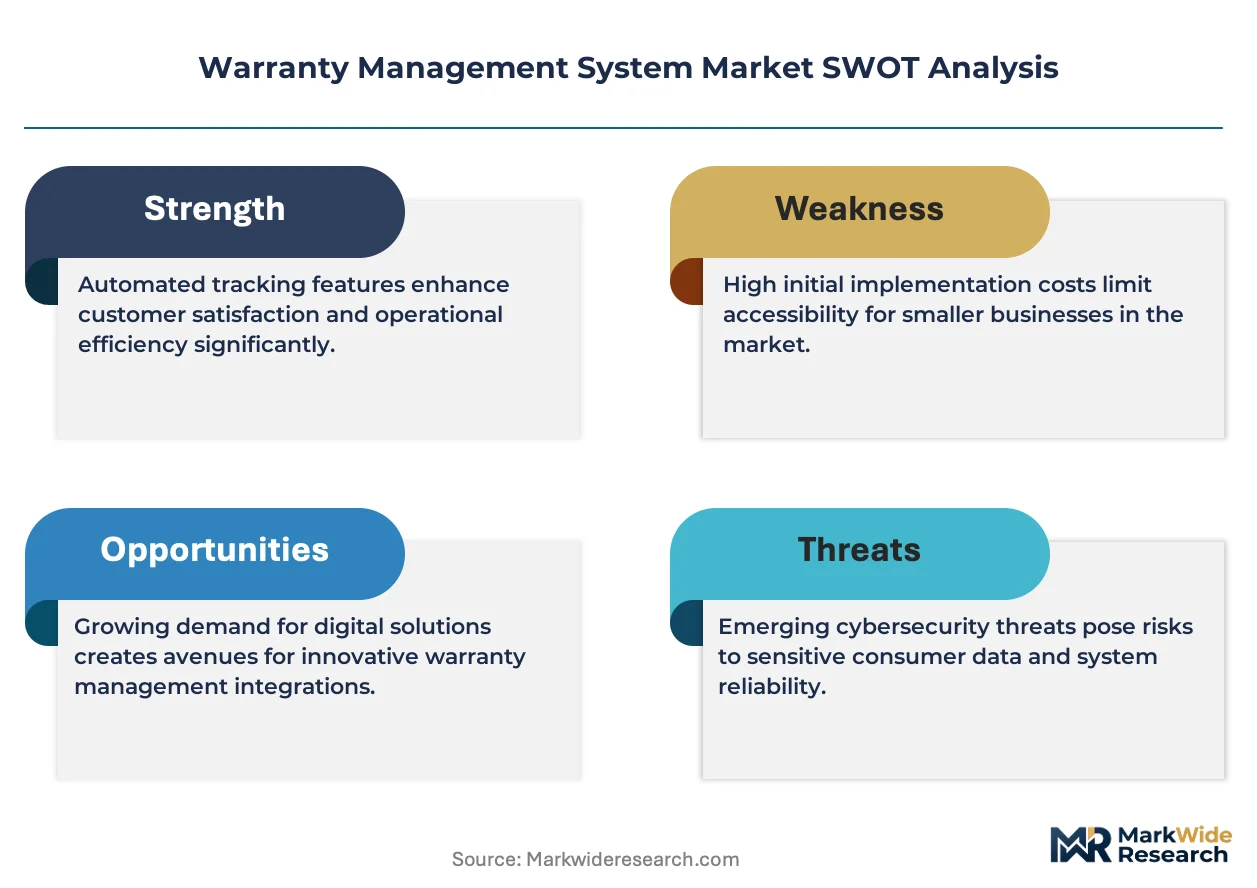
- Data sovereignty compliance costs:The EU AI Act and GDPR impose algorithmic transparency and residency requirements that force manufacturers to maintain separate infrastructure for European operations, elevating total cost of ownership.
- Legacy system integration friction:Industrial equipment makers with decades-old ERP deployments face protracted API mapping exercises to connect warranty modules, delaying cloud migration timelines.
- On-premise retention in defense:Aerospace and defense contractors in the United States maintain captive warranty systems to satisfy NIST cybersecurity frameworks and ITAR data localization rules, capping SaaS penetration in this segment.
Strategic Opportunities
- India manufacturing acceleration:PLI scheme incentives for automotive and electronics production are attracting OEMs that require warranty infrastructure scaled to distributed supplier networks across Maharashtra and Tamil Nadu.
- Predictive maintenance convergence:The intersection of warranty management with digital twin platforms allows manufacturers to shift from reactive claims to pre-emptive component replacement, capturing service revenue before failure occurs.
- Embedded insurance integration:Warranty platforms that natively underwrite extended service contracts at point of sale are penetrating consumer electronics retail channels in China, bundling protection with e-commerce checkout flows.
Industry Challenges
- Cross-functional talent scarcity:Vendors struggle to hire engineers who combine domain expertise in automotive quality systems with cloud architecture and machine learning operations.
- IATF 16949 certification timelines:Automotive suppliers face 12-18 month validation cycles to achieve quality management certification that warranty platforms must mirror, slowing deployment in new manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warranty Management System Market |
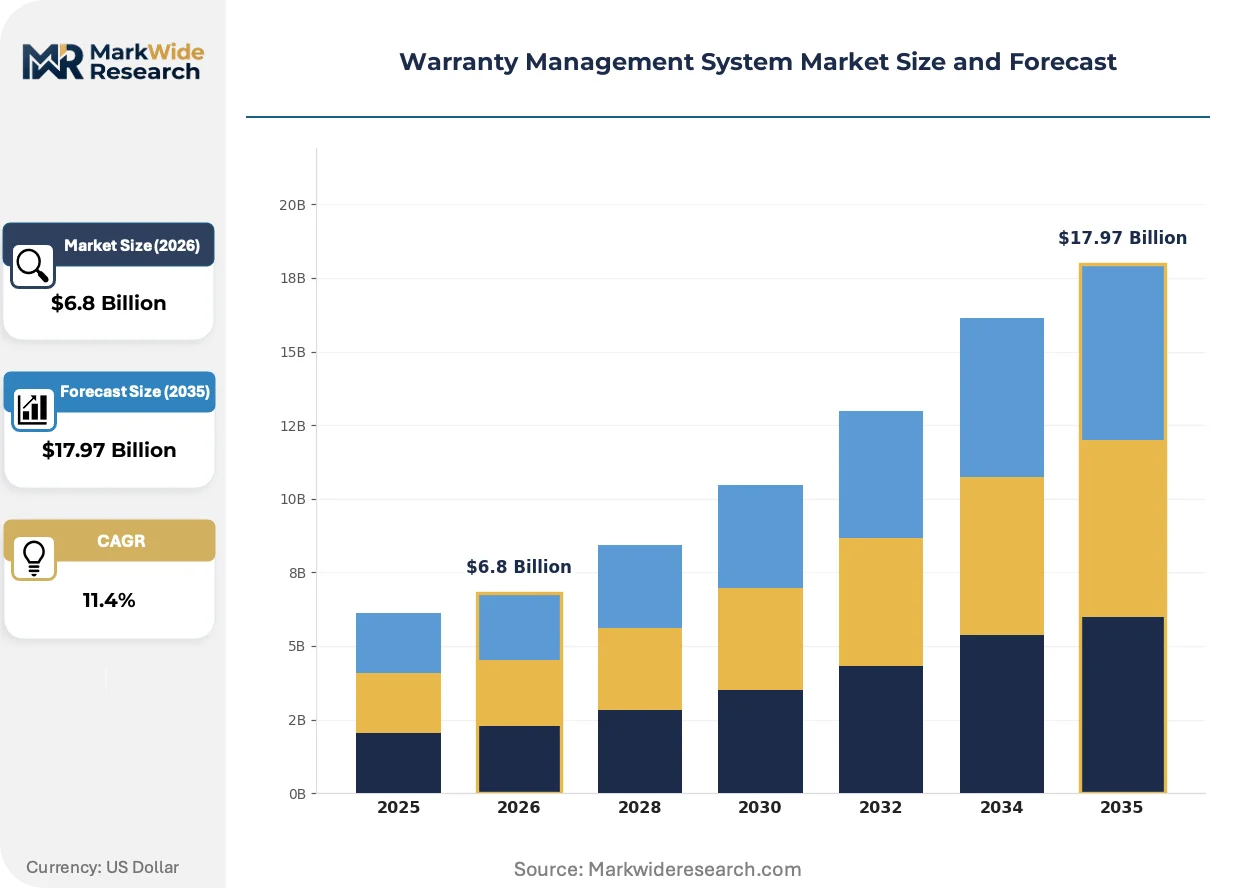
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud-based Solutions, Mobile Applications, On-premise Systems End User: Manufacturers, Retailers, Service Providers, Distributors Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premise Industry Vertical: Automotive, Electronics, Consumer Goods, Industrial Equipment |
| Companies Covered | Oracle Corporation, SAP SE, IBM Corporation, Pegasystems Inc., Wipro Limited, Tavant Technologies, Inc., Simply Warranty, Snap-On Business Solutions, Inc., PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warranty Management System Market Strategic Shifts
Real-time data streaming from connected products is collapsing the latency between failure detection and warranty response, compressing service cycles and reshaping how manufacturers reserve for future claims.
Edge computing architectures are electrifying warranty infrastructure by processing sensor data locally at dealer service bays and manufacturing plants before cloud transmission. Automotive OEMs in Germany and Japan are deploying these systems to reduce bandwidth costs and enable sub-second anomaly detection on assembly lines. This distributed processing model is compressing the time between component stress identification and supplier notification from days to minutes.
The EU AI Act's risk-based classification system is forcing warranty platform vendors to document algorithmic decision pathways for automated claim denials and fraud flags. Industrial equipment makers deploying machine learning adjudication engines must now maintain explainability logs that satisfy regulator audit requirements. Automotive suppliers in Italy and Spain are responding by embedding human-in-the-loop review stages for high-value claims that exceed automated confidence thresholds.
After-sales service unbundling is fragmenting traditional warranty bundling as fleet operators and enterprise buyers negotiate component-level coverage separate from base product guarantees. Commercial vehicle purchasers in the United States are procuring powertrain warranties from third-party insurers while accepting limited factory coverage on electronics, splitting revenue streams that OEMs previously captured whole. This disintermediation is most visible in long-haul trucking segments where total cost of ownership calculations dominate procurement decisions.
Warranty Management System Market Segmentation
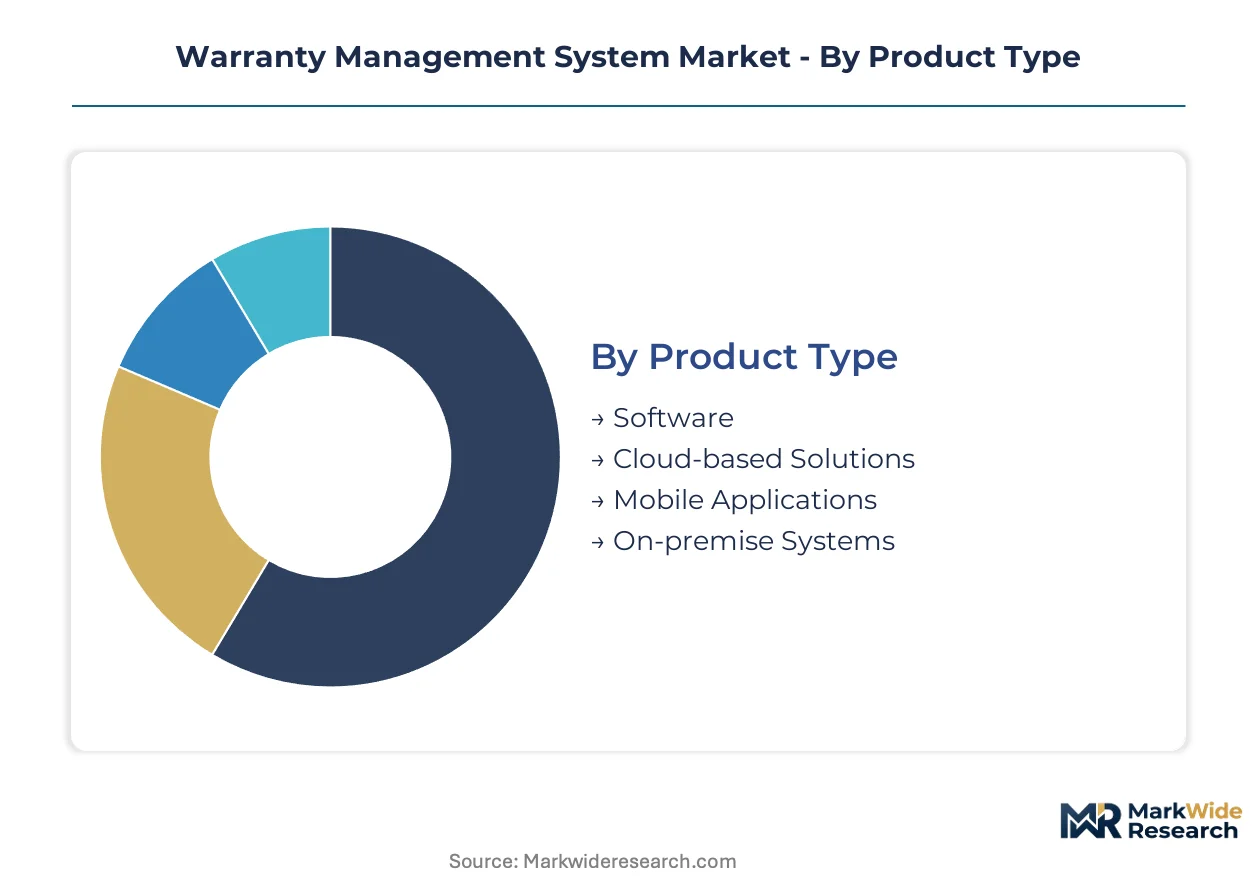
Warranty management platforms serve heterogeneous operational environments where deployment constraints, regulatory exposure, and integration complexity vary sharply across buyer profiles. Segmentation reveals which configurations command premium pricing and where vendor R&D investment is concentrating.
Product Type:
ISO 9001 and IATF 16949 certifications impose quality management documentation requirements that favor software architectures with embedded audit trails and version-controlled rule engines.
- Software:Core platforms delivering claims adjudication, supplier recovery, and predictive analytics through modular API architectures. Automotive OEMs in Germany and the United States prioritize these systems for multi-tier supply chain visibility.
- Cloud-based Solutions:Elastic infrastructure enabling seasonal capacity scaling and distributed dealer access without captive data center investment. These deployments dominate electronics manufacturing in Taiwan and South Korea where compressed product cycles demand rapid provisioning.
- Mobile Applications:Field service interfaces for claim initiation, photo documentation, and real-time parts ordering. Service technicians at dealer networks leverage these tools for sub-hour warranty registration.
- On-premise Systems:Captive installations satisfying data sovereignty constraints and air-gapped security requirements. Defense contractors and aerospace manufacturers in the United States retain these configurations to comply with NIST frameworks and ITAR localization rules.
Software sits at the top of the volume ranking, with Cloud-based Solutions climbing the fastest.
End User:
Procurement authority and implementation timelines diverge sharply based on whether the buyer operates captive manufacturing or intermediates third-party products.
- Manufacturers:OEMs and component suppliers requiring end-to-end lifecycle traceability from production through post-warranty service. These buyers drive platform roadmaps in Germany, Japan, and China.
- Retailers:Consumer electronics and appliance merchants bundling extended service contracts at point of sale. E-commerce platforms in China integrate warranty underwriting directly into checkout flows.
- Service Providers:Independent repair networks and authorized dealer chains managing claim submission and parts logistics. These operators prioritize mobile-first interfaces and real-time eligibility verification.
- Distributors:Industrial equipment intermediaries handling warranty transfers between manufacturers and end customers. Distributors in India and Brazil require multi-language claim routing across fragmented supplier bases.
Manufacturers capture the largest addressable spend, while Retailers are expanding most quickly through embedded insurance integration.
Deployment:
Data residency mandates from GDPR and the EU AI Act fragment infrastructure strategies, with European operations often requiring isolated processing environments.
- Public Cloud:Shared infrastructure delivering cost efficiency for mid-market manufacturers without dedicated security teams. These deployments dominate consumer goods sectors with standardized claim patterns.
- Private Cloud:Single-tenant environments offering controlled update cycles and custom compliance configurations. Automotive suppliers in France and Italy favor these for IATF 16949-aligned quality documentation.
- Hybrid Cloud:Architectures partitioning sensitive adjudication logic on-premise while leveraging cloud analytics for fraud detection and reserve forecasting. Industrial equipment makers adopt these to balance sovereignty with computational scale.
- On-premise:Fully captive systems retaining all data within facility perimeter. Defense and regulated industrial segments maintain these despite higher total cost of ownership.
Public Cloud leads deployment volumes, though Hybrid Cloud is gaining share fastest as manufacturers seek partitioned compliance architectures.
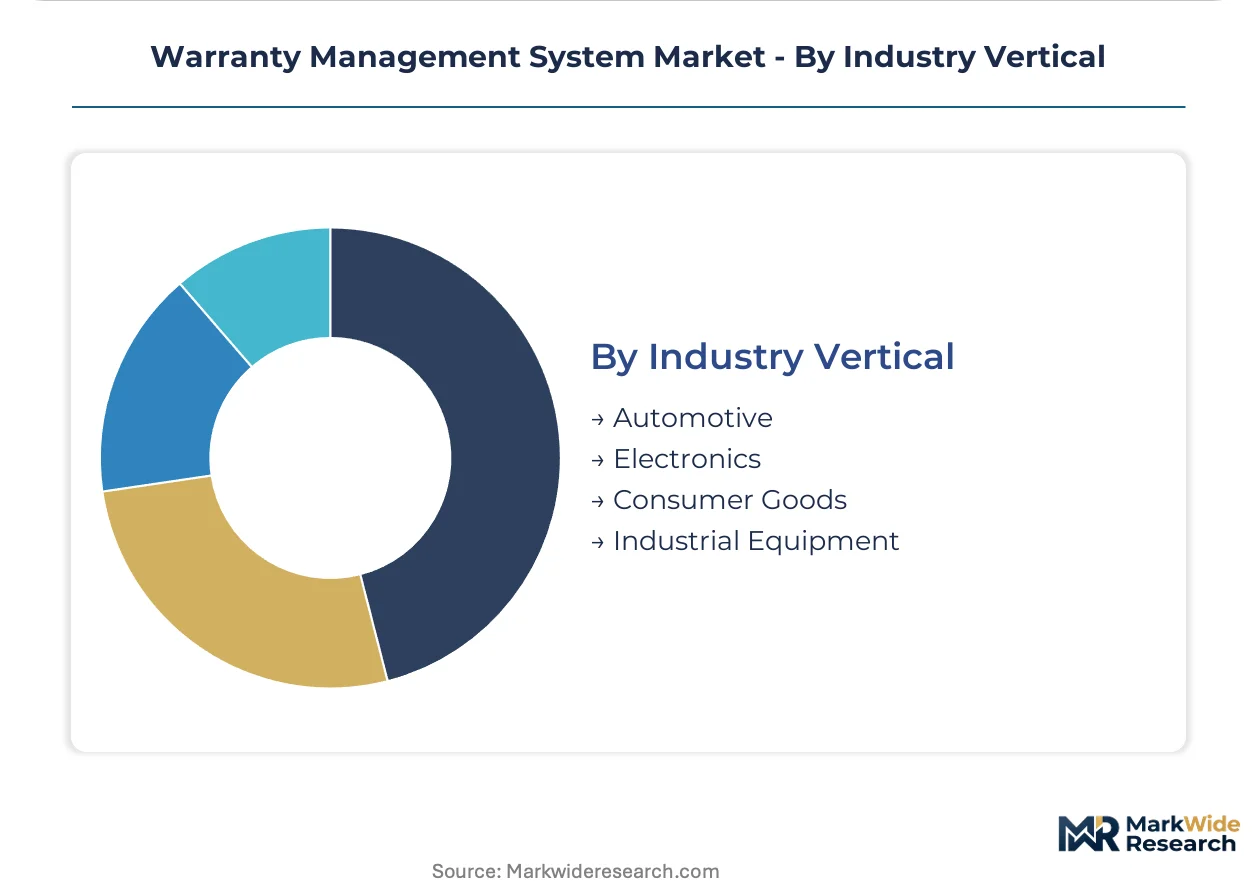
Industry Vertical:
Traceability mandates from the EU Green Deal and digital product passport requirements concentrate platform investment in sectors with complex international supply chains.
- Automotive:Warranty platforms integrating dealer networks, supplier chargeback systems, and connected vehicle telemetry. OEMs in Germany, the United States, and China anchor demand with multi-billion-unit installed bases.
- Electronics:Semiconductor and consumer device makers managing compressed product cycles, international return logistics, and component-level traceability. Manufacturers in South Korea and Taiwan drive fastest expansion.
- Consumer Goods:Appliance and home product brands handling seasonal claim spikes and retailer-managed service networks. These buyers prioritize cost-efficient cloud solutions with rapid deployment.
- Industrial Equipment:Heavy machinery and tooling manufacturers with decade-long warranty horizons and predictive maintenance integration. Long equipment lifecycles demand archival-grade data retention and supplier recovery automation.
Automotive commands the steepest expansion trajectory, while Electronics is climbing fastest on compressed product cycle pressures and international logistics complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing clusters in Bavaria and Baden-Württemberg anchor warranty platform demand as OEMs confront EU Green Deal traceability mandates and digital product passport requirements.
United States
Automotive OEMs and aerospace contractors drive warranty system procurement across Michigan, Ohio, and Texas manufacturing corridors. NHTSA defect reporting regulations and state-level lemon laws create fragmented compliance terrain that vendors address through configurable rule engines. Detroit's connected vehicle ecosystem compresses supplier recovery cycles from months to weeks through real-time telemetry integration.
Germany
IATF 16949-certified automotive suppliers dominate platform adoption in Stuttgart and Wolfsburg production zones. EU AI Act algorithmic transparency requirements force manufacturers to maintain explainability logs for automated claim denials. Munich-based industrial equipment makers deploy hybrid cloud architectures to balance GDPR data residency with computational scale for predictive analytics.
China
Electronics manufacturers in Shenzhen and semiconductor fabricators in Shanghai accelerate cloud warranty adoption for compressed product cycles. MIIT data localization rules and dual carbon goals pressure equipment makers toward granular lifecycle traceability. Hangzhou's e-commerce platforms integrate extended service contract underwriting directly into checkout flows, bundling protection with consumer electronics sales.
India
PLI scheme incentives attract automotive and electronics OEMs to Maharashtra and Tamil Nadu supplier networks requiring scalable warranty infrastructure. BIS quality certification mandates and DGFT trade documentation rules shape platform functionality for export-oriented manufacturers. Pune's expanding automotive component clusters demand multi-tier supply chain visibility as production scales.
South Korea
Semiconductor and consumer device makers in Suwon and Gyeonggi Province confront international return logistics complexity driving warranty system investment. MFDS regulatory frameworks for connected health devices intersect with warranty data requirements. Seoul Capital Area electronics manufacturers prioritize mobile-first field service interfaces for rapid claim registration across distributed repair networks.
Warranty Management System Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to embed warranty modules within broader enterprise software ecosystems. The competitive structure concentrates around three tiers: ERP-native providers with embedded quality management, cloud-native specialists offering elastic fraud detection, and industrial software firms integrating warranty with digital twin platforms. Two competitive vectors define positioning: vertical integration into predictive maintenance ecosystems and geographic expansion through localized compliance configurations.
Within the ERP-native tier, Oracle Corporation and SAP SE occupy positions that leverage existing enterprise cloud footprints to anchor warranty data across multi-tier supply chains. Tavant Technologies exemplifies the AI-specialist archetype, with its machine learning adjudication engines serving insurers and OEMs requiring automated fraud detection. IBM Corporation sits within the hybrid infrastructure segment, addressing defense and regulated industrial buyers with sovereign data requirements.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Pegasystems Inc. |
| Wipro Limited |
| Tavant Technologies, Inc. |
| Simply Warranty |
| Snap-On Business Solutions, Inc. |
| PTC Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud architecture talent concentration in Bangalore and Hyderabad creates labor-cost differentials that widen pricing-tier spreads between premium ERP-native platforms and economy SaaS offerings. European data residency mandates from GDPR and the EU AI Act add compliance premiums that tier pricing across deployment models.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and certified quality auditors shapes vendor pricing structures. A three-tier pricing structure across premium, standard, and economy levels separates Oracle and SAP's ERP-embedded modules from mid-market cloud specialists and bare-bones claim processing tools. Pricing pressure stems from open-source alternatives and hyperscaler-native warranty tools that compress margins in the standard tier. Mid-market manufacturers exhibit highest price sensitivity, while automotive OEMs with multi-billion-unit installed bases prioritize integration depth over cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for cloud infrastructure and AI model training partners, preventing captive dependence on single hyperscalers. Software development concentrates in India, the United States, and Germany, with cloud infrastructure anchored in AWS, Azure, and Google Cloud data center networks across these geographies. The supply chain draws from specialized semiconductor components for edge computing deployments, open-source machine learning frameworks, and certified quality management consultants. Single-source vulnerability in AI training data and model explainability tooling creates concentration risk. Distribution runs through direct enterprise sales teams, systems integrators, and OEM-embedded channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warranty management functions as a stable compounder where regulatory mandates for traceability and digital product passports generate recurring platform upgrade cycles. EU Green Deal compliance deadlines and IATF 16949 certification requirements sustain replacement demand regardless of macroeconomic conditions.
For Market Incumbents: Deploy embedded AI explainability logging to preempt EU AI Act audit requirements and defend against cloud-native challengers. Deepen ERP integration moats by certifying modules for automotive IATF 16949 and industrial ISO 9001 standards. Acquire edge computing specialists to capture predictive maintenance convergence opportunities before digital twin platforms absorb warranty functionality. For New Entrants and Emerging Players: The price-point gap between premium ERP-native suites and economy claim-processing tools opens white-space at the mid-market intersection. Target India's PLI-scheme automotive clusters in Maharashtra and Tamil Nadu where scaling manufacturers need warranty infrastructure without captive IT teams. Penetrate through mobile-first field service interfaces that compress dealer claim registration cycles below incumbent benchmarks. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid cloud specialists with sovereign data capabilities and automotive quality certifications. The five-to-ten-year viability window favors platforms with embedded insurance underwriting and predictive maintenance convergence. Watch for inflection where OEMs unbundle after-sales service and split warranty revenue with third-party insurers, compressing addressable spend for pure-play vendors.| Strategic Initiative | Industry Significance |
|---|---|
| AI Explainability Module Development | EU AI Act compliance mandates algorithmic transparency logs for automated claim denials. |
| Edge Computing Architecture Deployment | German and Japanese OEMs process sensor data locally to enable sub-second anomaly detection. |
| Embedded Insurance Integration | Hangzhou e-commerce platforms bundle extended service contracts with consumer electronics checkout flows. |
| Predictive Maintenance Convergence | Digital twin platforms allow manufacturers to shift from reactive claims to pre-emptive component replacement. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract OEMs to Maharashtra and Tamil Nadu requiring scalable warranty infrastructure. |
Study Parameters
Bottom-up automotive and electronics manufacturer modeling reconciled against top-down cloud infrastructure and enterprise software tracking forms the analytical core of this study. Primary interviews with warranty operations directors, automotive quality systems managers, cloud procurement officers, and aftermarket service heads informed demand-side assumptions. Secondary validation drew from SEC 10-K filings, EU regulatory compliance databases, automotive production statistics, and hyperscaler enterprise cloud revenue disclosures. Triangulation across these sources anchored market sizing and growth trajectory assessments.
Historical trendline analysis of warranty platform deployments across automotive, electronics, industrial equipment, and consumer goods verticals established baseline penetration rates. Segmentation modeling incorporated deployment architecture, organization size tier, industry vertical, integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves adjusted for technology substitution effects and compliance mandate timing. Forecast inputs included connected vehicle telemetry adoption curves, EU digital product passport implementation schedules, and PLI scheme manufacturing incentive disbursement patterns.
Caveats apply where cloud infrastructure cost volatility, AI regulatory enforcement intensity, or automotive production cycle downturns could materially shift the outlook. Deviation in EU AI Act audit frequency or IATF 16949 certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Email Marketing Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Change Management Software Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Global Workforce Productivity Systems Market