
 Global Distribution Software Market | 2026-2036
Global Distribution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distribution Software Market Foresight
Subscription-based recurring revenue models for cloud-native distribution platforms is consolidating vendor economics around lifetime value metrics rather than perpetual license recognition. Microsoft leverages its Azure infrastructure to anchor enterprise-grade supply chain modules across North American manufacturing corridors. SAP competes through deep ERP integration that sustains cross-selling momentum into wholesale distribution networks. Oracle differentiates via autonomous database capabilities that dominate high-velocity transaction processing for third-party logistics operators.
Distribution software encompasses the integrated application layer that orchestrates inventory positioning, order fulfillment routing, warehouse management execution, and transportation planning across multi-node supply networks. Core functional parameters include real-time SKU-level visibility, demand-signal propagation latency under 100 milliseconds, and API interoperability with upstream ERP and downstream carrier systems. Cloud-based solutions lead current deployment patterns as retail and e-commerce end users prioritize elastic capacity scaling over fixed infrastructure commitments. Hybrid solutions represent the fastest-growing structural segment where wholesale distributors maintain on-premises control for sensitive procurement data while bursting transactional workloads to public cloud instances. Support services capture concentrated margin pools as implementation complexity rises with multi-cloud deployment models.
FDA traceability mandates for pharmaceutical distribution, EU GDPR requirements for cross-border data residency in logistics platforms, and India's BIS cloud security standards collectively elevate compliance architecture to a competitive differentiator. The EU AI Act imposes additional algorithmic transparency obligations on automated demand-forecasting modules deployed within European distribution networks. Stakeholders must evaluate whether their current platform roadmaps accommodate emerging regulatory granularity around AI-driven inventory decisions before compliance deadlines harden procurement criteria.
Market Dynamics
Cloud-native architecture migration is compressing vendor consolidation timelines as enterprise distributors abandon perpetual license models for elastic consumption billing. The EU AI Act and India's BIS cloud security standards are forcing compliance architecture redesigns ahead of procurement renewal cycles.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated demand-forecasting modules in European distribution networks now require explainable decision trails, creating replacement demand for compliant platforms.
- India's warehousing sector BIS modernization:Third-party logistics providers in Mumbai and Delhi are accelerating cloud platform adoption to meet upgraded data residency and security certification requirements.
- Real-time SKU-level visibility requirements:Pharmaceutical distributors facing FDA traceability mandates for drug distribution are procuring systems with sub-100 millisecond latency propagation capabilities.
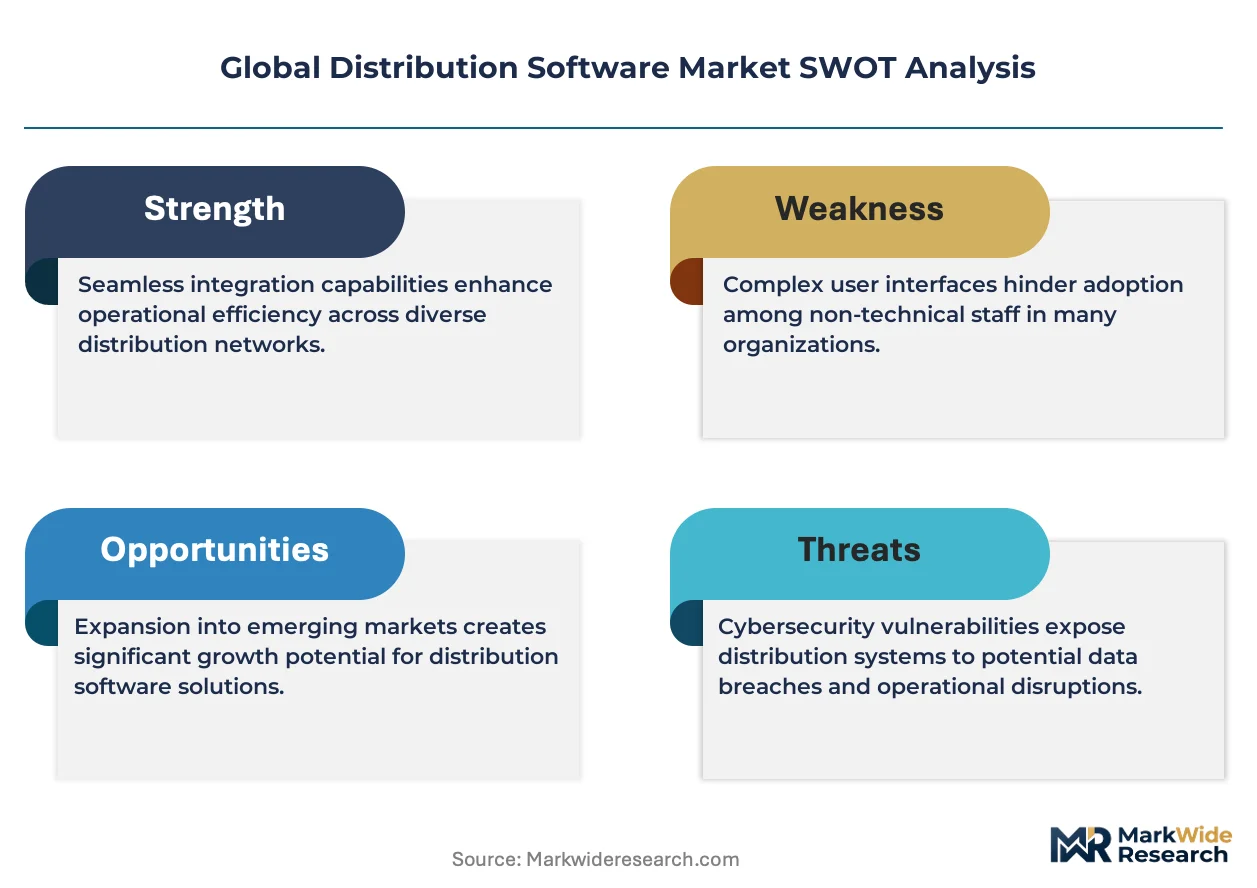
Market Restraints
- Multi-cloud implementation cost structure:Hybrid deployment models require specialized integration labor that inflates total cost of ownership by 40-60% versus single-cloud alternatives.
- Cross-border data residency friction:EU GDPR requirements for logistics platform data localization create architectural constraints that fragment vendor addressable markets.
- Legacy ERP integration technical debt:Wholesale distributors maintaining on-premises procurement data control face API interoperability failures that stall cloud migration timelines.
Strategic Opportunities
- Underpenetrated German mid-market 3PL segment:Cloud-native platform vendors can capture share from regional logistics operators still running on-premise warehouse management systems.
- EU CSRD sustainability reporting integration:Distribution software embedding carbon footprint tracking per shipment creates differentiation for European wholesale networks facing Scope 3 disclosure requirements.
- Edge computing and 5G convergence:Warehouse execution systems leveraging low-latency connectivity enable autonomous mobile robot orchestration that reduces fulfillment labor density.
Industry Challenges
- Multi-cloud DevOps talent scarcity:Implementation partners with certified expertise across Azure, AWS, and GCP simultaneously command premium rates that compress project margins.
- FDA pharmaceutical traceability certification timelines:Validation protocols for drug distribution software extend sales cycles by 8-14 months versus general merchandise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distribution Software Market |
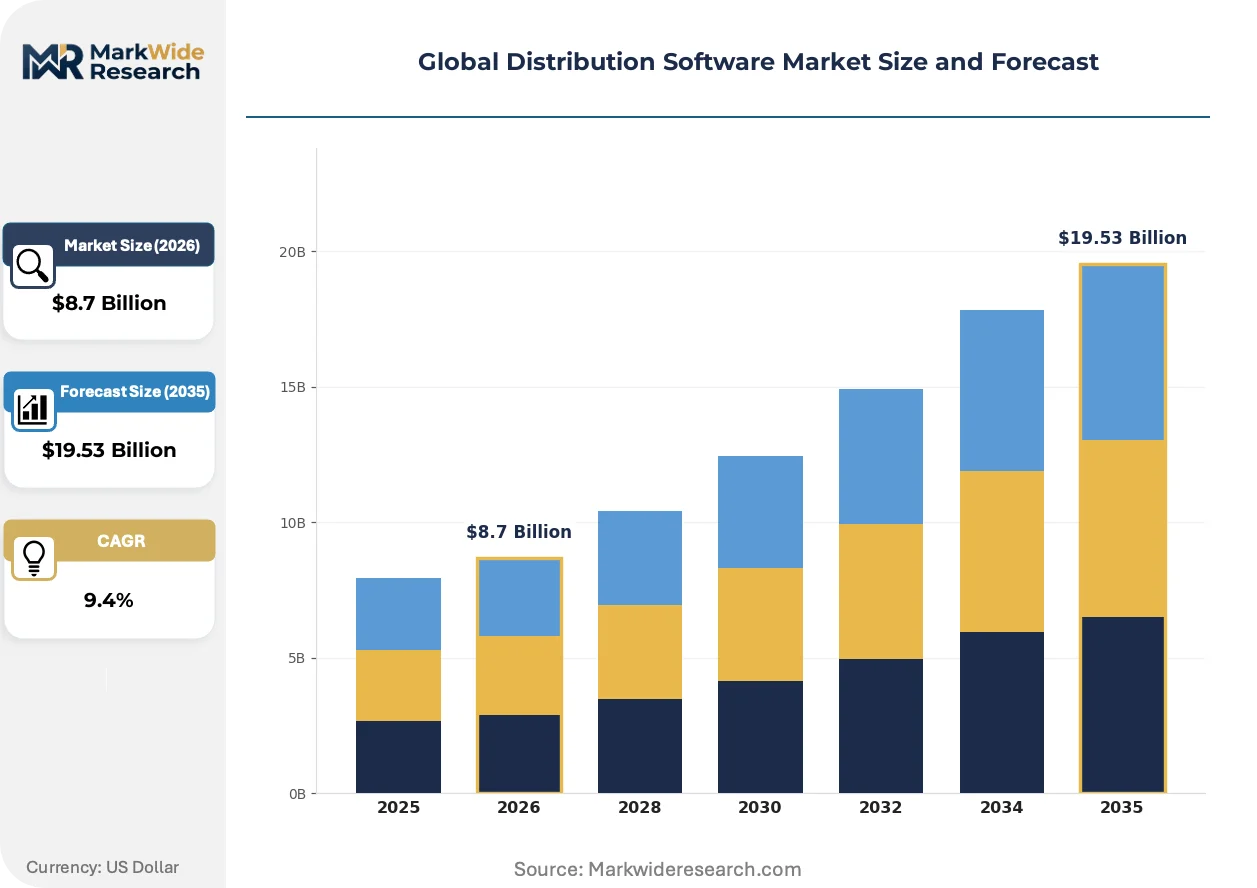
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Web-Based Platforms Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Hybrid Cloud End User: Retail, Wholesale, E-Commerce, Government Service Type: Consulting Services, Implementation Services, Support Services, Training Services |
| Companies Covered | Microsoft, SAP, Intuit, Oracle, Salesforce, Sage, WiseTech Global, Constellation Software, Epicor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distribution Software Market Shifts & Advancements
Distribution software architecture is pivoting from monolithic ERP extensions toward composable microservices that enable selective capability procurement. Vendors are repositioning around data gravity and API ecosystem density rather than functional breadth alone.
Autonomous database technology is consolidating transaction processing workloads for high-velocity third-party logistics operators. Oracle's infrastructure-dependent customers are migrating analytical queries to self-optimizing data layers that eliminate manual indexing overhead. The structural consequence is compressing database administrator headcount requirements while accelerating order-to-cash cycle visibility.
The EU AI Act imposes documentation burdens on machine learning models deployed for demand forecasting across European distribution networks. Algorithmic impact assessments now precede production deployment for automated inventory positioning systems. German pharmaceutical wholesalers are responding by segregating EU-specific model instances from global deployments to contain compliance scope.
Subscription billing for supply chain modules is displacing perpetual license recognition among North American manufacturing distributors. Finance teams now prioritize vendor lifetime value metrics over upfront revenue capture in procurement evaluations. This shift concentrates negotiating leverage with platforms demonstrating elastic scaling economics during seasonal demand spikes.
Global Distribution Software Market Segmentation
Distribution software procurement varies sharply by deployment architecture and regulatory exposure. Certification burdens from FDA, EU AI Act, and India's BIS standards fragment vendor addressable markets and reshape segment prioritization across enterprise buyers.
Product Type:
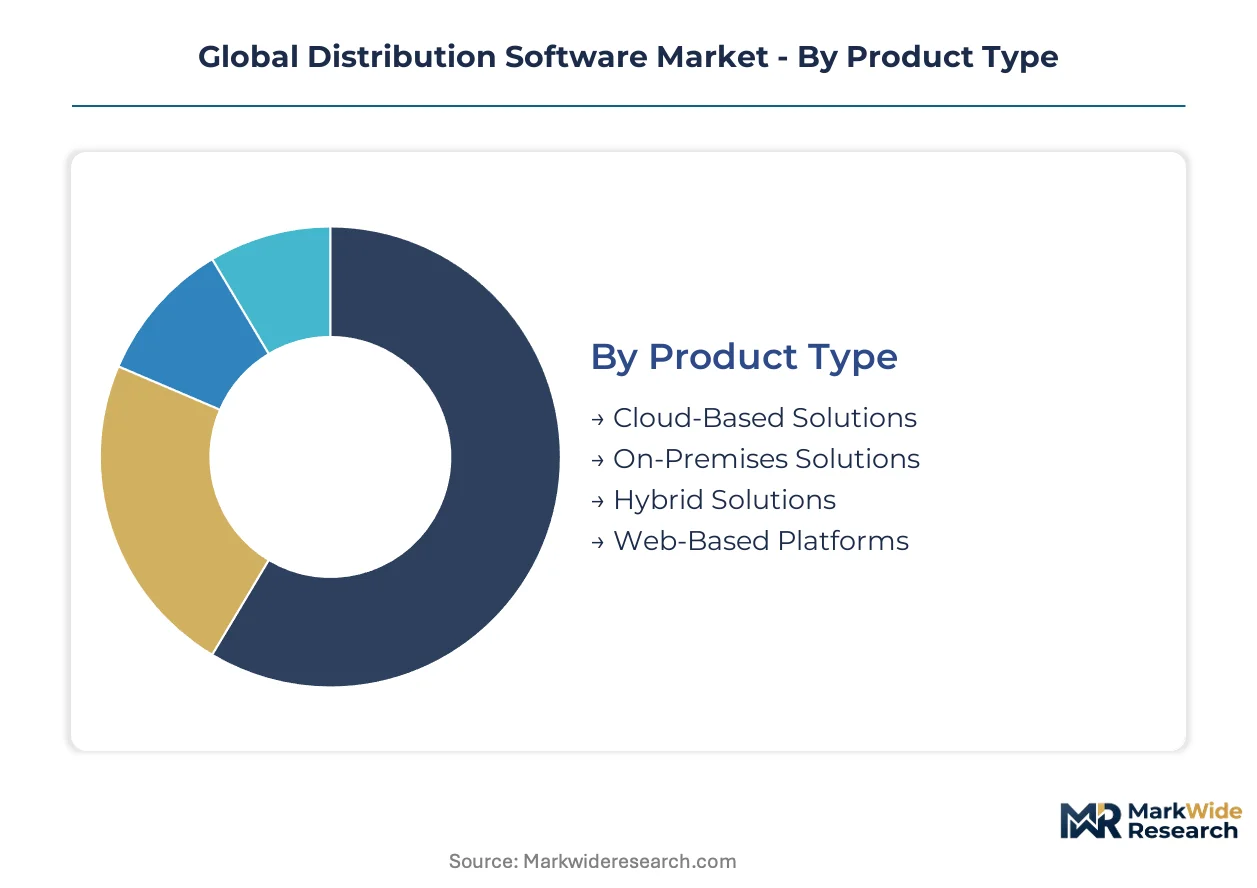
FDA pharmaceutical traceability mandates and EU GDPR data residency rules concentrate compliance investment in cloud-native architectures, while India's BIS cloud security standards accelerate hybrid platform adoption for warehousing operators.
- Cloud-Based Solutions:Elastic capacity scaling enables retail and e-commerce end users to burst transactional workloads during seasonal demand spikes without fixed infrastructure commitments. Pharmaceutical distributors in the United States prioritize these platforms for FDA drug distribution traceability mandates requiring sub-100 millisecond latency propagation.
- Hybrid Solutions:Wholesale distributors maintain on-premises control for sensitive procurement data while bursting computational workloads to public cloud instances. German third-party logistics providers are expanding adoption of this architecture to satisfy EU AI Act algorithmic transparency requirements without full cloud migration.
- On-Premises Solutions:Legacy ERP integration dependencies sustain demand among distributors with substantial technical debt in procurement data systems.
- Web-Based Platforms:Browser-accessible interfaces reduce client-side maintenance overhead for mid-market logistics operators with limited IT staffing.
Leading the category by volume: Cloud-Based Solutions. Growing fastest: Hybrid Solutions.
Deployment Model:
Cost tier differentiation separates enterprise-grade private cloud deployments from consumption-billed public alternatives, with multi-cloud architectures commanding premium integration labor rates.
- Public Cloud:Azure infrastructure anchors enterprise-grade supply chain modules across United States manufacturing corridors with elastic consumption billing. Subscription-based recurring revenue models consolidate vendor economics around lifetime value metrics.
- Multi-Cloud:Specialized integration labor inflates total cost of ownership by 40-60% versus single-cloud alternatives. Implementation partners with certified expertise across Azure, AWS, and GCP simultaneously command premium rates that compress project margins.
- Private Cloud:Dedicated infrastructure satisfies EU GDPR cross-border data residency constraints for logistics platforms handling sensitive shipment records.
- Hybrid Cloud:Segregated workload placement enables German pharmaceutical wholesalers to contain EU AI Act compliance scope by isolating European model instances.
Dominating by deployment spend: Public Cloud. Expanding most quickly: Multi-Cloud.
End User:
Application-specific functional requirements drive divergent platform selection, with pharmaceutical retail demanding traceability modules that general wholesale distribution does not require.
- Retail:Real-time SKU-level visibility requirements concentrate procurement investment in systems with demand-signal propagation latency under 100 milliseconds. United States pharmaceutical retailers face FDA validation protocols that extend sales cycles by 8-14 months versus general merchandise deployments.
- E-Commerce:Seasonal demand volatility prioritizes elastic capacity scaling over fixed infrastructure commitments. Cloud-native platform adoption concentrates in India's warehousing sector as BIS standards modernize data residency and security certification requirements.
- Wholesale:ERP integration depth sustains cross-selling momentum from incumbent vendors with established procurement data relationships.
- Government:Sovereign data localization mandates restrict vendor selection to platforms with domestic infrastructure presence and named security certifications.
Highest procurement volume: Retail. Steepest expansion trajectory: E-Commerce.
Service Type:
Margin concentration shifts toward implementation complexity as multi-cloud deployment models proliferate, with support services capturing durable recurring revenue streams.
- Support Services:Concentrated margin pools emerge as multi-cloud deployment models elevate technical complexity and sustain long-term vendor relationships. Finance teams prioritize vendor lifetime value metrics over upfront revenue capture in procurement evaluations.
- Implementation Services:Multi-cloud DevOps talent scarcity forces premium labor rates that compress project margins for systems integrators. Edge computing and 5G convergence in warehouse execution systems requires specialized deployment expertise.
- Consulting Services:EU CSRD sustainability reporting integration creates advisory demand for carbon footprint tracking per shipment across European wholesale networks.
- Training Services:Autonomous database technology migration compresses database administrator headcount requirements while elevating reskilling investment for analytical query optimization.
Greatest revenue concentration: Support Services. Gaining share fastest: Implementation Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in technology corridors of the United States and Germany, while consumption spreads across manufacturing and logistics hubs in India, China, and Brazil where warehouse automation is accelerating.
United States
FDA traceability mandates for pharmaceutical distribution drive procurement of sub-100 millisecond latency systems. Cloud-native platforms dominate deployment patterns as retail and e-commerce operators prioritize elastic capacity scaling. The Midwest manufacturing corridor anchors enterprise-grade supply chain module adoption across automotive and industrial distributors.
Germany
Third-party logistics providers are expanding cloud-native platform adoption to modernize warehouse management execution. EU AI Act algorithmic transparency requirements force compliance architecture redesigns for automated demand-forecasting modules. The Rhine-Ruhr industrial cluster concentrates mid-market 3PL platform migration from legacy on-premise systems.
India
BIS cloud security standards and data residency requirements accelerate hybrid platform adoption in Mumbai and Delhi warehousing sectors. Real-time SKU-level visibility demands from pharmaceutical distributors align with CDSCO modernization timelines. The National Capital Region hosts concentrated implementation of API-interoperable inventory systems for third-party logistics operators.
China
Domestic e-commerce giants drive demand for high-velocity transaction processing and autonomous database capabilities. NMPA pharmaceutical traceability rules elevate compliance investment in distribution software with explainable decision trails. The Yangtze River Delta logistics corridor leads deployment of edge-computing-enabled warehouse execution systems.
Brazil
ANVISA pharmaceutical distribution regulations create replacement demand for compliant traceability platforms. Wholesale distributors maintain hybrid architectures to satisfy data localization requirements while accessing cloud scalability. São Paulo's logistics hub concentrates procurement of browser-accessible warehouse management interfaces for mid-market operators.
Global Distribution Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software architects across deployment models. The vendor base organizes around three tiers: hyperscale cloud platforms with integrated supply chain modules, specialized logistics software vendors with deep warehouse execution expertise, and ERP incumbents leveraging cross-selling momentum into distribution networks. Consolidation pressures intensify as subscription billing displaces perpetual license recognition and multi-cloud expertise becomes a scarce differentiator.
Within the hyperscale tier, Microsoft and Oracle anchor enterprise-grade offerings through infrastructure-dependent database and cloud services. SAP occupies a position bridging ERP integration depth with distribution-specific functional modules. These three exemplify divergent competitive vectors: Azure-anchored elastic scaling, autonomous transaction processing optimization, and procurement data relationship leverage respectively.
| Leading Market Players |
|---|
| Microsoft |
| SAP |
| Intuit |
| Oracle |
| Salesforce |
| Sage |
| WiseTech Global |
| Constellation Software |
| Epicor |
| Others |
Supply & Pricing Matrix
Multi-cloud DevOps specialists concentrated in Bangalore and Hyderabad command 40-60% labor-cost premiums over single-cloud certified engineers, widening the pricing-tier spread between hybrid deployment quotes and standard public-cloud alternatives. Pharmaceutical distributors absorbing FDA validation timelines of 8-14 months accept premium pricing for compliance-bundled support services.
Pricing Analysis
Margin tightening in enterprise-grade deployments reflects multi-cloud implementation complexity that inflates total cost of ownership versus single-cloud alternatives. Three-tier pricing structure across premium certification-bundled, standard SaaS, and economy self-service levels separates buyers by validation burden and integration depth. Pharmaceutical distributors facing FDA traceability mandates exhibit lowest price sensitivity, while mid-market logistics operators in Brazil and India prioritize browser-accessible interfaces that minimize client-side maintenance overhead.
Supply Chain Analysis
Dual-sourcing requirements for hyperscaler infrastructure now mandate qualified deployment partners across Azure, AWS, and GCP simultaneously, fragmenting vendor consolidation timelines. Software production concentrates in the United States technology corridors and Germany's Rhine-Ruhr industrial cluster, with consumption spreading through Mumbai, Delhi, and São Paulo logistics hubs. API interoperability modules and autonomous database licensing constitute critical component dependencies. Single-source vulnerability around certified multi-cloud DevOps talent compresses project margins. Distribution runs through systems integrators with specialized edge-computing and 5G deployment expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architecture migration is displacing perpetual license recognition, compressing vendor economics around subscription billing and lifetime value metrics. Composable microservices are replacing monolithic ERP extensions as the dominant procurement paradigm.
For Market Incumbents: Lock in cross-selling momentum from established procurement data relationships by deepening ERP integration modules for wholesale distribution networks. Invest in autonomous database capabilities that eliminate manual indexing overhead for high-velocity third-party logistics operators. Defend against hyperscale cloud platforms by embedding EU CSRD sustainability reporting and FDA traceability compliance as bundled differentiators.
For New Entrants and Emerging Players: Regional logistics operators in Germany's mid-market 3PL segment present the most penetrable white-space target, with many still running legacy on-premise warehouse management systems. India's warehousing sector modernization under BIS standards creates replacement demand for API-interoperable hybrid platforms. Channel partners with certified multi-cloud expertise offer the strongest go-to-market angle, given talent scarcity that commands premium project rates.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized logistics software vendors possessing deep warehouse execution expertise and established channel density in underpenetrated European markets, given EU AI Act compliance deadlines that harden procurement criteria. Long-term viability favors platforms demonstrating elastic scaling economics during seasonal demand spikes. Watch FDA pharmaceutical traceability certification timelines as the signal for sales cycle compression or extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens ERP cross-selling momentum into wholesale procurement data relationships. |
| Acquisition of Specialist Firm | Captures scarce multi-cloud DevOps talent and edge-computing deployment expertise. |
| Geographic Expansion | Targets Germany's mid-market 3PL segment with cloud-native warehouse management modules. |
| Strategic Partnership | Secures Azure, AWS, or GCP co-sell status for enterprise manufacturing corridor access. |
| Product Launch | Introduces EU AI Act-compliant demand-forecasting with explainable decision trails. |
Research Methodology
Multi-period observation of subscription billing adoption rates, compliance certification timelines, and multi-cloud deployment patterns anchored the trend analysis, supplemented by interviews with CTOs, IT procurement officers, platform engineers, and systems integration specialists. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, EU regulatory filings under AI Act and CSRD frameworks, and BIS certification databases. Bottom-up vendor revenue triangulation against top-down enterprise IT spending estimates refined market sizing.
Segment-weighting approaches modeled deployment architecture, organization size, vertical industry, and regional regulatory exposure as primary dimensions across the projection horizon. CAGRs derived from elasticity-adjusted growth curves that account for cloud-native migration velocity and compliance-driven replacement cycles. Forecast inputs incorporated FDA validation protocol durations, EU AI Act implementation timelines, and India's BIS modernization trajectory.
Caveats apply where multi-cloud DevOps talent scarcity, pharmaceutical traceability certification delays, or cross-border data residency enforcement could materially shift the outlook. Deviation in hyperscaler infrastructure pricing or regulatory deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Visitor Identification Software Market
Software & Services
Quality Management Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Data Conversion Services Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
App Creation Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Pure Play Software Testing Market