
 Robotic Pool Cleaner Market | 2026-2036
Robotic Pool Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Pool Cleaner Market Intelligence
The hospitality sector is expanding its share of robotic pool cleaner procurement as hotels and resorts automate pool maintenance to cut labor expenses. Maytronics leverages decades of specialized engineering to dominate premium in-ground system sales across North America. Pentair anchors its position through backward integration into pump and filtration technology. Aiper competes aggressively on price in the cordless, above-ground segment.
A robotic pool cleaner is an autonomous, electrically powered device that traverses pool surfaces using brush mechanisms and suction or pressure systems to remove debris, algae, and sediment without human intervention. These units typically operate on low-voltage DC motors, employ microprocessor-controlled navigation algorithms, and separate particulate matter through cartridge or bag filtration. In-ground product types command the largest revenue share due to higher unit values and complex surface geometries. Smart navigation technology leads growth as AI-driven mapping reduces cleaning cycle times and energy consumption. The residential end user segment remains the volume base, though commercial applications generate superior per-unit margins.
The EPA Energy Star program and Ecodesign regulations from the European Commission shape motor efficiency mandates and filtration performance benchmarks for pool equipment manufacturers. The EU F-Gas Regulation and REACH compliance requirements additionally constrain material choices for seals and housings. Stakeholders must monitor evolving cordless battery standards and IP waterproofing certifications as product architectures shift away from tethered power supplies.
Market Dynamics
The transition from corded to cordless battery architectures is compressing manufacturing lead times while simultaneously intensifying IP competition around waterproofing and navigation algorithms. This shift is redistributing value capture from traditional pump-motor suppliers toward battery management system specialists.
Growth Catalysts
- Residential pool density:Florida, California, and Texas maintain the highest household pool penetration rates in the United States, creating concentrated demand clusters for automated maintenance equipment.
- EPA Energy Star efficiency mandates:Stricter motor performance benchmarks are accelerating replacement cycles for legacy suction-side cleaners that fail to meet updated power consumption thresholds.
- Hospitality labor cost pressure:Hotels and resorts are automating pool maintenance to reduce seasonal staffing requirements and standardize cleaning quality across property portfolios.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production for cordless units depends heavily on East Asian cell manufacturers, exposing assemblers to raw material volatility and logistics bottlenecks.
- REACH compliance complexity:The European Chemicals Agency's evolving substance restrictions are constraining seal and housing material choices, extending product development timelines for EU-bound models.
- Suction-side cleaner substitution:Lower-cost pressure and suction alternatives continue to capture price-sensitive above-ground pool owners, limiting robotic unit addressable market expansion.
Strategic Opportunities
- Smart home integration:Wi-Fi connectivity and app-based scheduling are enabling robotic cleaners to function as data nodes within broader residential automation ecosystems, opening recurring software revenue streams.
- Commercial service contracts:Municipal aquatic centers and fitness chains are outsourcing pool maintenance to specialized operators who prefer fleet-managed robotic units with centralized diagnostics.
- EU Green Deal alignment:The European Commission's circular economy action plan is creating preferential procurement pathways for equipment with modular, repairable designs and extended warranty terms.
Industry Challenges
- IP68 certification bottlenecks:Achieving reliable ingress protection ratings for submersible electronics requires specialized testing infrastructure that few contract manufacturers possess, limiting production scaling.
- Navigation algorithm talent scarcity:Development of AI-driven mapping systems demands robotics software expertise that pool equipment manufacturers must recruit from adjacent autonomous vehicle and consumer drone sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Pool Cleaner Market |
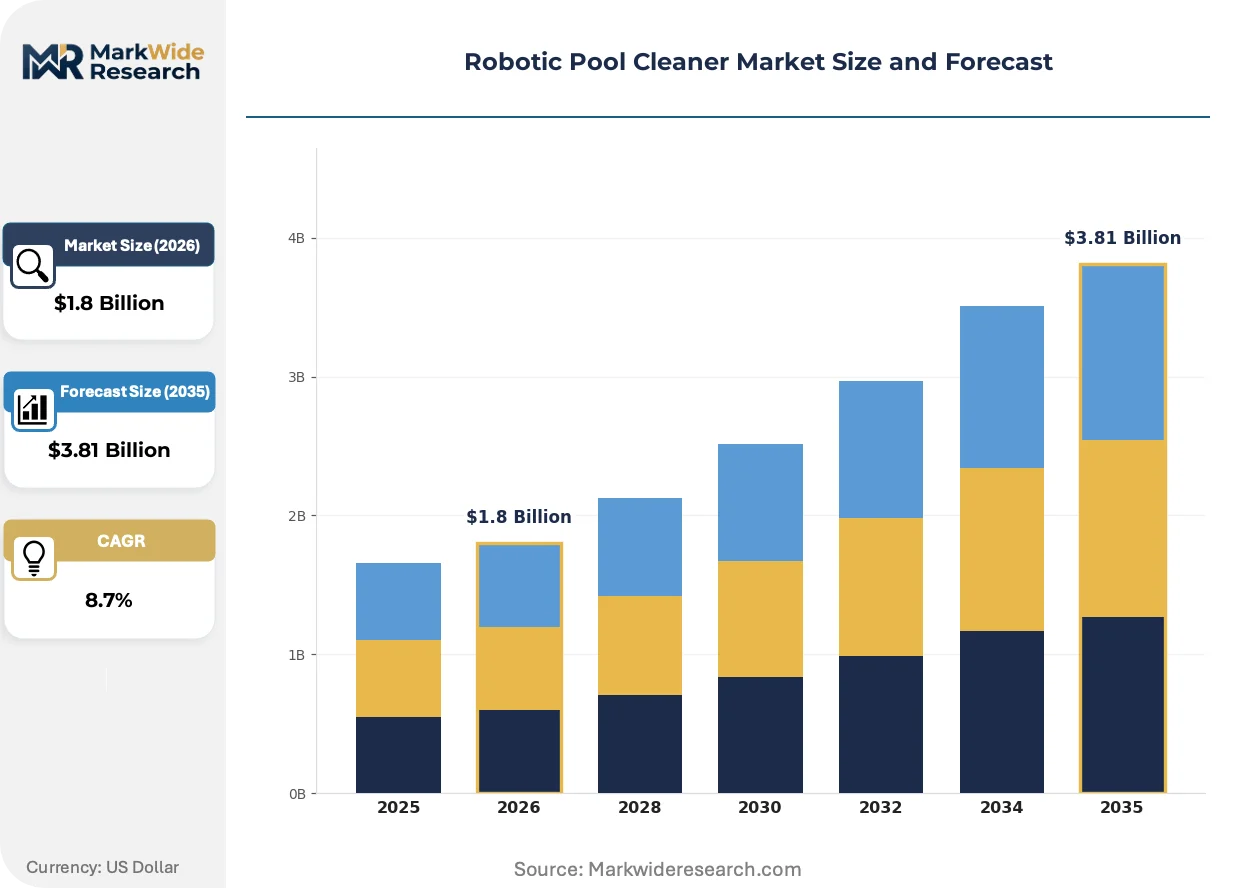
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ground, Above-Ground, Automated, Manual Technology: Smart Navigation, Remote Control, Suction Power, Filter Type End User: Residential, Commercial, Municipal, Hospitality Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Blue Helix, Hayward, Maytronics, Aqua Products, Zodiac, Aiper, Pentair, Waterco, Beatbot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Pool Cleaner Market Strategic Shifts & Innovations
Navigation autonomy is replacing random-path coverage patterns as the defining performance differentiator, compressing cleaning cycle duration while reducing energy consumption. This technological pivot is restructuring R&D investment priorities across the competitive landscape.
Solid-state battery chemistry is electrifying cordless robotic cleaner architectures by enabling higher energy density in compact form factors. Residential buyers are upgrading from entry-level corded units to premium battery-operated models at accelerated replacement intervals. This chemistry shift is compressing the addressable market for traditional tethered power supply manufacturers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in manufacturing processes, forcing seal and gasket suppliers to reformulate elastomer compounds. Pool equipment assemblers must validate alternative materials without compromising submersion durability. European-bound product lines are experiencing extended qualification timelines as manufacturers adapt to ECHA substance restrictions.
Direct-to-consumer channel expansion is fragmenting traditional dealer and distributor relationships that historically dominated pool equipment sales. Amazon and specialty e-commerce platforms are capturing growing share of above-ground and mid-tier in-ground unit transactions. This disintermediation is most pronounced in the United States, where seasonal purchasing patterns align with digital promotional calendars.
Robotic Pool Cleaner Market Segmentation
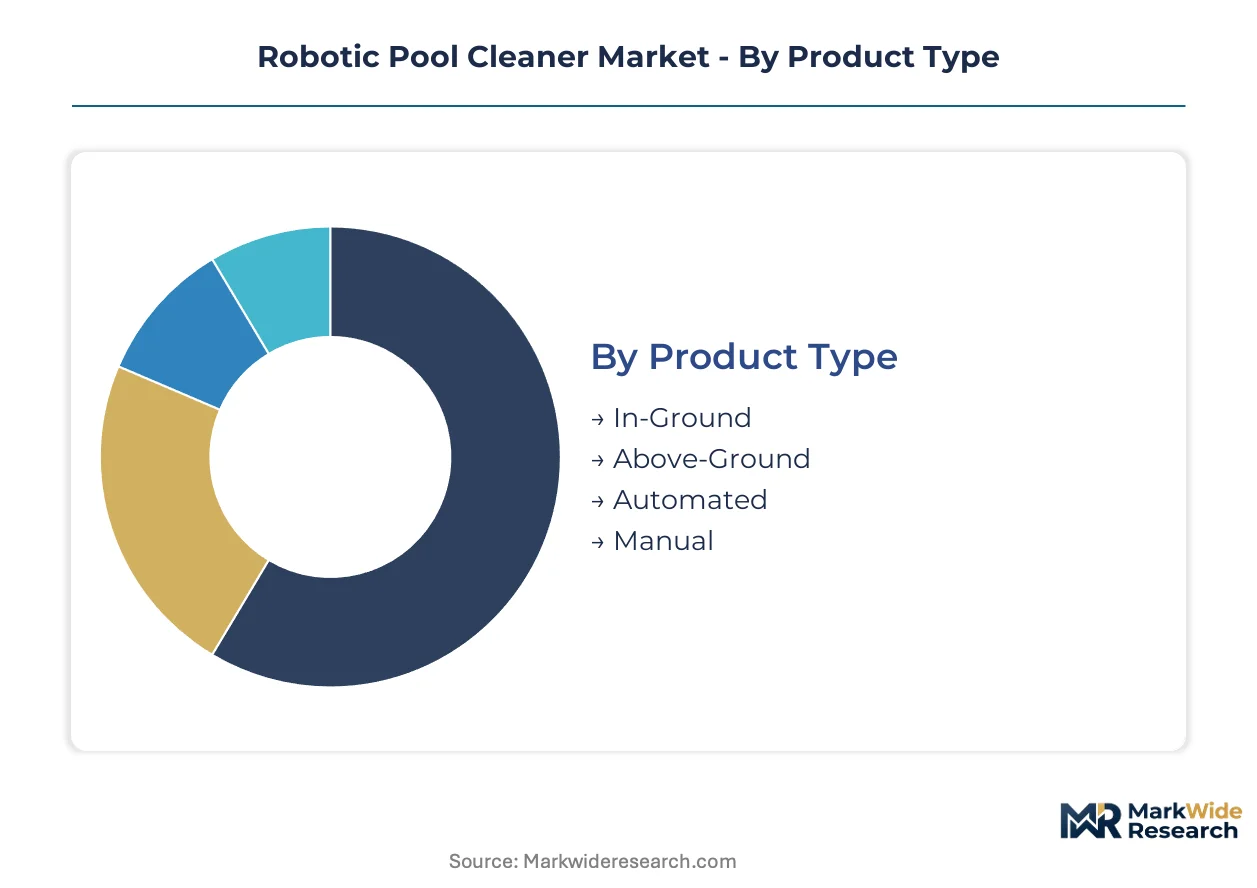
Robotic pool cleaner procurement decisions pivot on installation geometry, automation sophistication, and ownership economics. Segment boundaries increasingly blur as cordless architectures and AI navigation penetrate historically distinct price tiers.
Product Type:
Purchase decisions here track pool construction permanence and surface complexity, with unit economics scaling sharply from temporary above-ground installations to permanent in-ground systems.
- In-Ground:These units navigate complex surface geometries including slopes, steps, and benches through multi-axis brush systems and pressure jets. Demand clusters in Florida, California, and Texas where residential pool density supports premium automation investments. EPA Energy Star motor mandates accelerate replacement cycles for legacy suction-side equipment.
- Above-Ground:Lighter chassis designs accommodate flat-bottom vinyl or steel-wall constructions with simplified navigation algorithms. Cordless battery models from Aiper and Wybot capture price-sensitive buyers through direct-to-consumer channels. REACH compliance complexity extends EU-bound product development timelines for seal materials.
- Automated:Microprocessor-controlled units with programmable cleaning cycles and debris sensors reduce human intervention requirements.
- Manual:Hand-guided suction devices persist in budget segments and specialized spot-cleaning applications.
Volume sits with Above-Ground; growth tilts toward In-Ground.
Technology:
Performance differentiation now hinges on software capabilities rather than mechanical specifications, restructuring R&D investment toward robotics talent recruitment.
- Smart Navigation:AI-driven mapping systems using gyroscopic sensors and wall-tracking algorithms compress cleaning cycle duration by eliminating random-path redundancy. Development demands robotics software expertise sourced from autonomous vehicle and consumer drone sectors. EU-bound models face extended IP68 certification timelines at specialized testing facilities.
- Remote Control:Wi-Fi and Bluetooth connectivity enable app-based scheduling, zone targeting, and maintenance alerts. These features position robotic cleaners as data nodes within residential automation ecosystems, opening recurring software revenue streams.
- Suction Power:Motor specification remains a baseline hygiene factor with efficiency benchmarks set by EPA Energy Star and Ecodesign regulations.
- Filter Type:Cartridge and bag filtration systems determine debris capacity and maintenance frequency for different pool environments.
Procurement concentrates on Smart Navigation; Remote Control climbs the fastest.
End User:
Ownership structure dictates automation requirements, with commercial operators prioritizing fleet diagnostics and standardized cleaning protocols.
- Residential:Individual pool owners drive unit volume through seasonal replacement cycles and upgrade paths from corded to cordless architectures. Solid-state battery chemistry enables compact form factors that accelerate premium model adoption.
- Commercial:Municipal aquatic centers and fitness chains outsource maintenance to specialized operators who prefer fleet-managed units with centralized diagnostics. Per-unit margins exceed residential segments significantly.
- Municipal:Public recreation facilities require durable equipment with extended warranty terms aligned with EU circular economy procurement pathways.
- Hospitality:Hotels and resorts automate pool maintenance to reduce seasonal staffing requirements and standardize cleaning quality across property portfolios.
Residential commands volume; Hospitality shows steepest expansion trajectory.
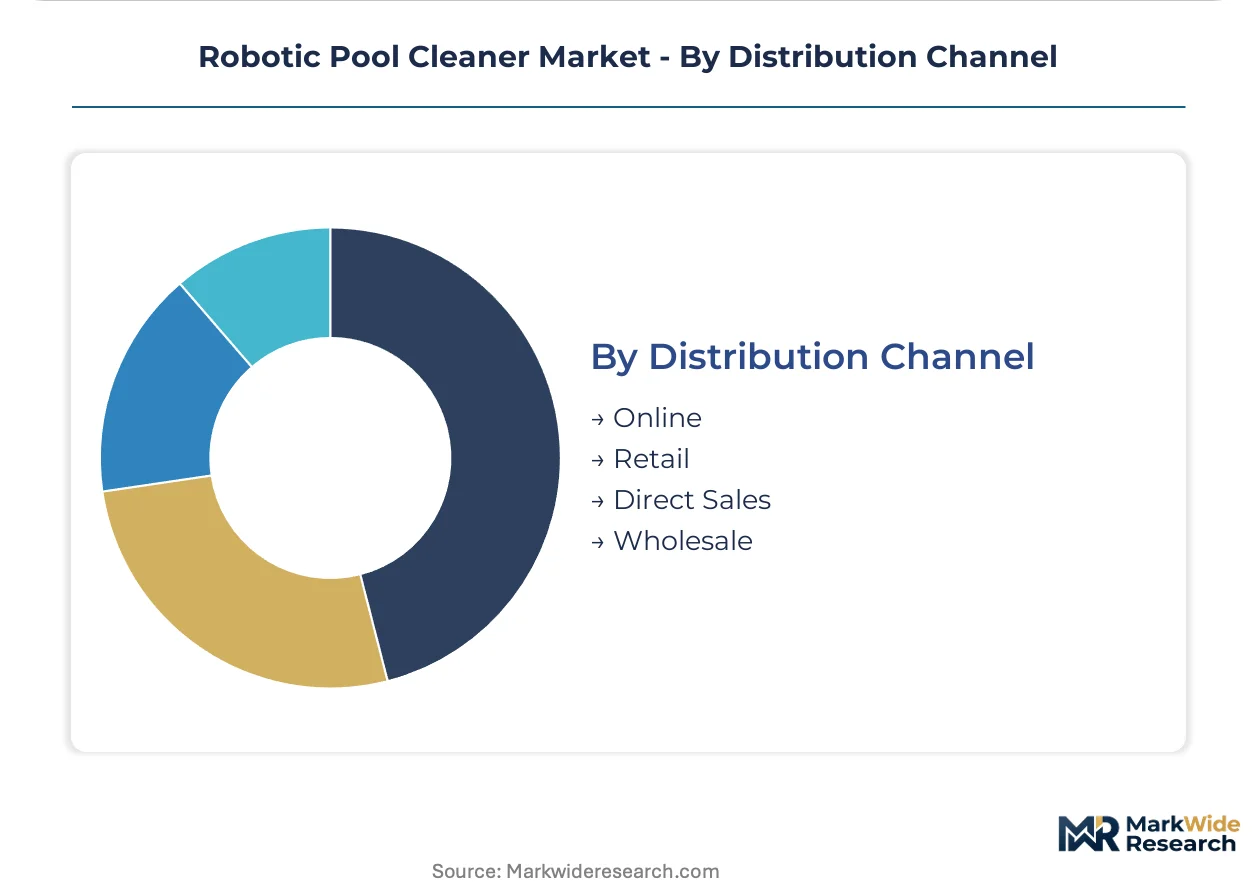
Distribution Channel:
Channel selection reflects buyer sophistication and purchase urgency, with seasonal patterns increasingly synchronized with digital promotional calendars.
- Online:Amazon and specialty e-commerce platforms capture growing share of above-ground and mid-tier in-ground transactions. Direct-to-consumer expansion fragments traditional dealer relationships.
- Retail:Pool specialty stores and big-box retailers provide hands-on product demonstration and immediate availability for urgent replacements.
- Direct Sales:Premium in-ground systems often move through manufacturer-authorized installers who bundle equipment with commissioning services.
- Wholesale:Distributor networks serve regional pool service companies and hospitality procurement departments with volume pricing structures.
Volume concentrates in Retail; Online gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's pool density concentration creates a specialized demand cluster that anchors North American procurement patterns. California's Title 24 building efficiency standards accelerate replacement cycles for legacy equipment. Texas municipal water conservation programs subsidize automated cleaning systems.
United States
Florida, California, and Texas maintain the highest residential pool penetration rates, generating concentrated demand clusters for premium automation equipment. EPA Energy Star motor efficiency mandates accelerate replacement cycles for suction-side cleaners that fail updated power consumption thresholds. The Phoenix-Mesa-Scottsdale metro area experiences rapid hospitality sector expansion, driving commercial procurement of fleet-managed units.
Germany
Stringent Ecodesign requirements from the European Commission shape motor efficiency benchmarks and filtration performance standards for pool equipment manufacturers. The EU F-Gas Regulation constrains seal and gasket material choices, extending product development timelines. Bavaria's recreational facility operators prefer modular, repairable designs aligned with circular economy procurement pathways.
France
Hospitality sector automation spreads across Côte d'Azur resort properties seeking standardized cleaning protocols and reduced seasonal staffing. REACH compliance complexity from the European Chemicals Agency restricts housing material formulations. The Provence-Alpes-Côte d'Azur region hosts specialized testing infrastructure for IP68 waterproofing certification.
Australia
High residential pool ownership rates in Queensland and New South Wales sustain steady replacement demand for cordless battery architectures. The country's national energy efficiency program incentivizes low-voltage DC motor adoption. Sydney's pool service companies consolidate around fleet-managed robotic units with centralized diagnostics capabilities.
Spain
Tourism-dependent hospitality operators across the Balearic and Canary Islands automate pool maintenance to manage labor cost volatility. EU Green Deal alignment creates preferential procurement pathways for equipment with extended warranty terms. Catalonia's manufacturing base supplies waterproofing components to cordless cleaner assemblers.
Robotic Pool Cleaner Market Key Industry Players
Top-tier vendors anchor premium in-ground system sales, while mid-tier specialists compete aggressively on cordless above-ground pricing. The vendor base stratifies across three functional tiers: legacy pump-filtration integrators, specialized robotics engineers, and direct-to-consumer battery specialists. Dominant competitive moves include backward integration into motor and battery supply chains, plus strategic partnerships with smart home platform operators.
Within the specialized robotics tier, Maytronics exemplifies engineering-focused positioning through decades of dedicated pool automation development. Pentair anchors the integrated systems vector through captive supply of pump and filtration technology. Aiper occupies the cordless disruption position, competing on price in battery-powered above-ground segments through direct-to-consumer channel expansion.
| Leading Market Players |
|---|
| Blue Helix |
| Hayward |
| Maytronics |
| Aqua Products |
| Zodiac |
| Aiper |
| Pentair |
| Waterco |
| Beatbot |
| Others |
Cost & Logistics Intelligence
Backward integration into motor and battery supply chains anchors both manufacturing control and pricing power for established vendors, while cordless architecture shifts redistribute value capture from traditional pump-motor suppliers toward battery management specialists serving EPA Energy Star and Ecodesign compliance requirements.
Pricing Analysis
Short lead-time premiums command pricing advantages for IP68-certified units with validated waterproofing, while spot inventory of legacy corded models faces discount pressure from cordless substitution. Three-tier pricing structure across premium smart-navigation, standard programmable, and economy manual tiers differentiates on AI mapping capability and EPA motor efficiency certification. Cost compression in the above-ground segment intensifies because Aiper and Wybot direct-to-consumer channels bypass traditional dealer markups. Residential buyers show highest price sensitivity, while hospitality procurement prioritizes fleet diagnostics and standardized cleaning protocols over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian lithium-ion cell manufacturers to North American and European assembly plants compresses margins for cordless unit producers dependent on just-in-time battery pack delivery. China, South Korea, and Japan concentrate cell production for cordless architectures, while Germany and Spain supply waterproofing components and specialized IP68 testing infrastructure. Raw material dependencies center on lithium carbonate, rare-earth magnets for DC motors, and reformulated elastomer compounds compliant with EU F-Gas Regulation and REACH restrictions. Single-source vulnerability in solid-state battery chemistry development poses structural risk. Distribution runs through Amazon and specialty e-commerce platforms fragmenting traditional pool dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
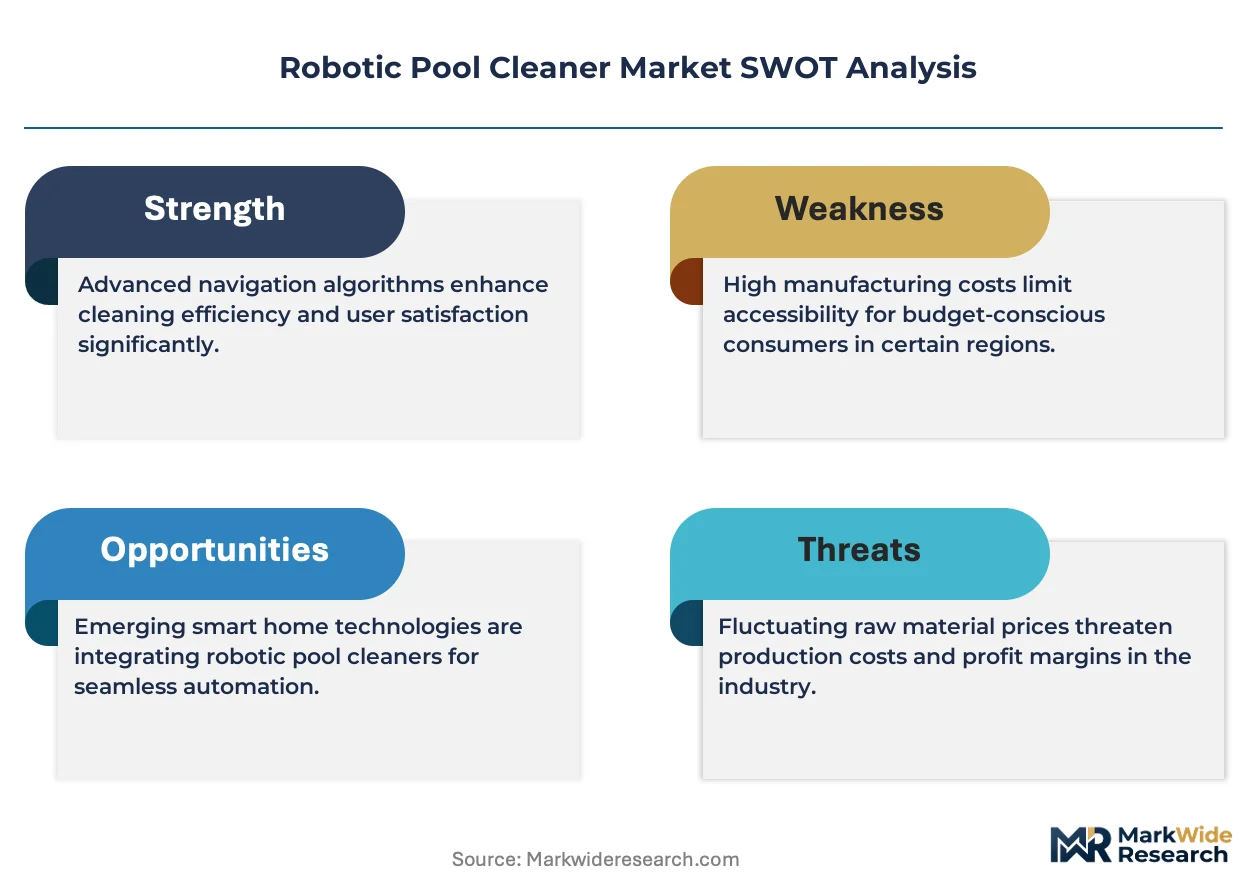
IP68 certification bottlenecks at specialized testing facilities constrain production scaling, propping pricing premiums for validated submersible electronics as supply fails to match cordless demand acceleration.
For Market Incumbents: Deploy captive battery supply agreements to secure lithium-ion cell allocation ahead of hospitality fleet procurement surges. Deepen backward integration into motor winding and filtration cartridge production to defend margin position against Aiper price aggression in above-ground segments. Prioritize Ecodesign pre-certification for EU-bound models before REACH substance restrictions tighten seal material specifications. For New Entrants and Emerging Players: Launch via direct-to-consumer Amazon storefronts targeting Texas and Florida residential replacement cycles with cordless above-ground units. White-space concentrates in municipal aquatic center fleet contracts requiring centralized diagnostics, a segment underserved by hospitality-focused incumbents. Beatbot and Wybot demonstrate penetrable entry points through aggressive digital promotional calendar alignment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pump-filtration integrators seeking robotics capabilities, with Maytronics and Pentair as logical acquirers of navigation algorithm talent. Long-term viability favors specialists with in-house IP68 testing infrastructure and REACH-compliant material libraries. Watch cordless battery standardization announcements from IEEE or IEC as inflection indicators for architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Positions robotic cleaners as data nodes within Alexa and Google Home ecosystems, opening recurring software revenue. |
| IP68 Certification Pre-Investment | Locks in specialized testing facility relationships before capacity constraints extend qualification timelines for EU-bound models. |
| Solid-State Battery Partnership | Secures higher energy density chemistry enabling compact form factors that accelerate premium cordless adoption. |
| Hospitality Fleet Service Contracts | Captures commercial margins through centralized diagnostics preferred by Marriott and Hilton property portfolios. |
| REACH-Compliant Material Reformulation | Ensures continued EU market access as ECHA substance restrictions constrain seal and housing elastomer choices. |
Research Approach
Multi-period observation of cordless architecture adoption rates, EPA Energy Star replacement cycles, and hospitality procurement patterns anchored the trend analysis, supplemented by interviews with pool equipment R&D directors, battery management system engineers, hospitality facilities managers, and specialty e-commerce category buyers. Secondary validation drew from SEC 10-K filings, ECHA substance restriction updates, IEEE battery standardization documents, and customs trade data for pool equipment imports. Bottom-up unit shipment modeling triangulated against top-down expenditure estimates from municipal recreation budgets and hospitality capital expenditure disclosures.
Input-output matrices mapped product type, technology tier, end-user segment, and distribution channel dimensions across the projection horizon. CAGRs derived from segmented growth rate blending weighted by Florida-California-Texas demand concentration and EU regulatory compliance timelines. Forecast inputs included lithium-ion cell price trajectories, IP68 certification facility capacity expansion plans, and smart home platform partnership announcements.
REACH substance list revisions, solid-state battery commercialization delays, and hospitality labor cost volatility are the dominant revision risks that could compress or extend forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Commercial Locker Market
Household Items
Washing Machine Cleaner Market
Household Items
UK Digital Showers Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
Global Tableware Market
Household Items
Flushable Wipes Market
Household Items
Steam Cleaners Market
Household Items
Kuwait Gas Hobs Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
United States Barbeque Grill Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Stick Vacuum Cleaner Market
Household Items
India Cookware Market
Household Items
Window Rain Guards Market