
 Asia-Pacific Hand Dryer Market | 2026-2036
Asia-Pacific Hand Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hand Dryer Market Analysis
Aftermarket service revenue is reconfiguring competitive economics across the Asia-Pacific hand dryer landscape. TOTO leverages its extensive service network in Japan to capture recurring maintenance contracts. Dyson sustains premium positioning through proprietary digital motor technology and direct-to-facility channel control. Mitsubishi Electric anchors regional manufacturing scale with integrated production of high-efficiency motors and sensor assemblies.
Asia-Pacific hand dryers are electromechanical devices that use forced air streams, typically generated by brushless DC motors operating at rotational speeds exceeding 100,000 RPM, to evaporate or strip water from hands within 10-15 seconds. These units serve commercial and institutional restrooms by reducing paper waste, lowering operational costs, and improving hygiene outcomes through touchless operation. Jet air technology dominates premium installations in hospitality and healthcare settings where rapid dry times justify higher capital outlay. Warm air products occupy the bulk of education and mid-tier commercial demand where upfront cost sensitivity shapes procurement decisions. Eco-friendly variants incorporating heat-recovery systems and low-wattage motors represent the fastest-growing segment as facility operators face escalating electricity tariffs.
China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility in public restroom equipment, while India's BIS mandates energy-performance labeling for commercial appliances. Japan's METI promotes building energy codes that incentivize low-power hand dryer installations in new commercial construction. Facility procurement teams must weigh total cost of ownership against capital expenditure constraints when specifying equipment across mixed-use developments.
Market Dynamics
Aftermarket service revenue is reconfiguring competitive economics across the Asia-Pacific hand dryer landscape. TOTO leverages its extensive service network in Japan to capture recurring maintenance contracts. Dyson sustains premium positioning through proprietary digital motor technology and direct-to-facility channel control. Mitsubishi Electric anchors regional manufacturing scale with integrated production of high-efficiency motors and sensor assemblies.
Growth Catalysts
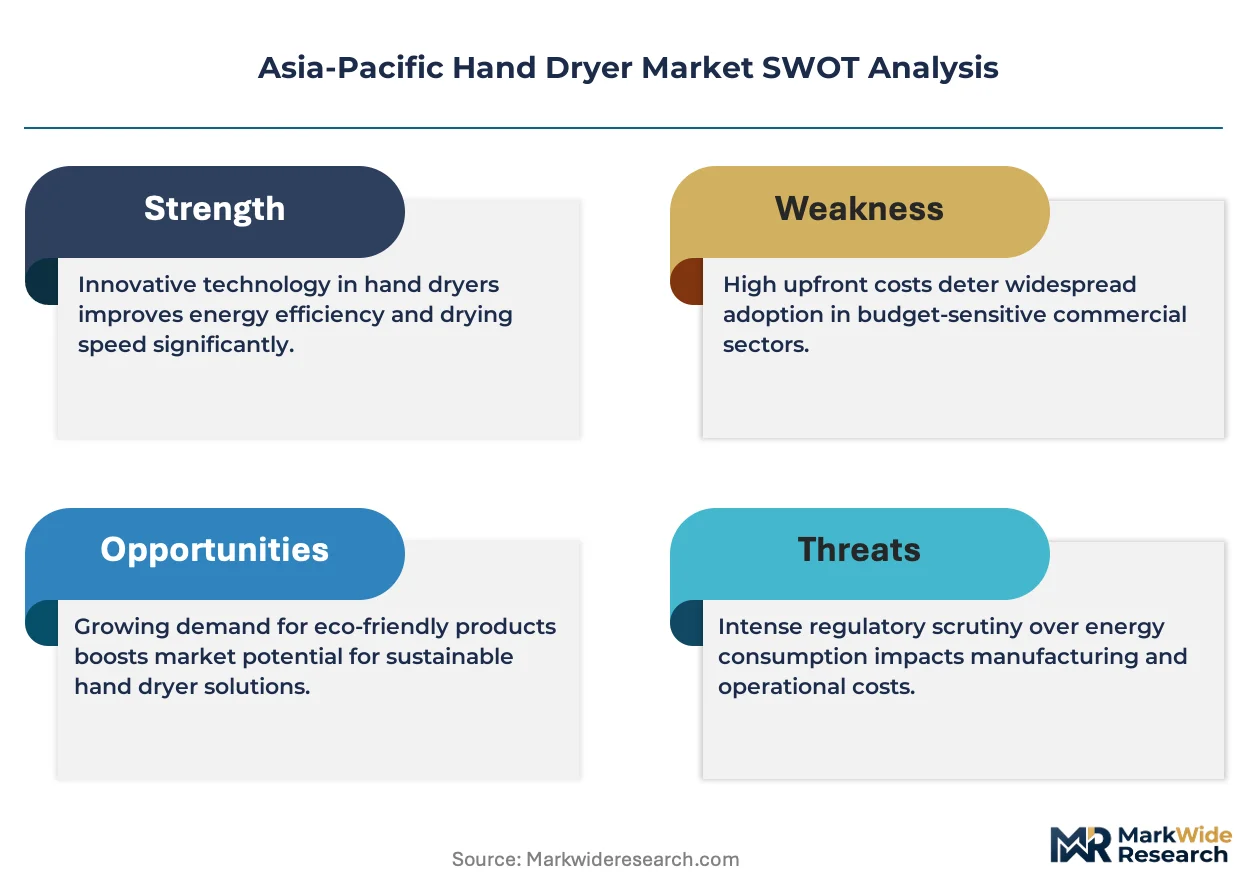
- China's GB standards for electromagnetic compatibility:Facility managers in Shanghai and Beijing are accelerating replacement cycles to achieve compliance with SAMR-mandated safety certifications.
- Heat-recovery motor systems:Eco-friendly variants incorporating heat-exchanger technology are capturing procurement preference as electricity tariffs escalate across India's metropolitan transit hubs.
- Touchless operation protocols:Healthcare facilities in Singapore and Sydney are specifying sensor-activated units to meet infection-control benchmarks.
Market Restraints
- Brushless DC motor supply concentration:High-RPM motor production clusters in Guangdong and Osaka create vulnerability to component availability shocks.
- Copper and rare-earth magnet cost volatility:Permanent magnet materials for compact motor assemblies face price swings tied to export quota policies.
- Acoustic emission limits:Japan's METI building energy codes impose noise thresholds that disqualify older warm-air models from new commercial construction.
Strategic Opportunities
- Vietnam's underpenetrated hospitality sector:Da Nang and Ho Chi Minh City hotel developments present first-mover positioning for jet-air technology suppliers.
- India's BIS energy-performance labeling mandate:Star-rating requirements for commercial appliances create regulatory tailwind for certified low-wattage product lines.
- Direct-to-facility digital channels:Procurement platforms are disintermediating traditional distributor networks for standardized warm-air specifications.
Industry Challenges
- Sensor calibration expertise shortage:Infrared proximity detection systems require specialized field technicians that facility management contractors struggle to source.
- GB standard certification timelines:SAMR testing protocols for electromagnetic compatibility extend product launch schedules by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hand Dryer Market |
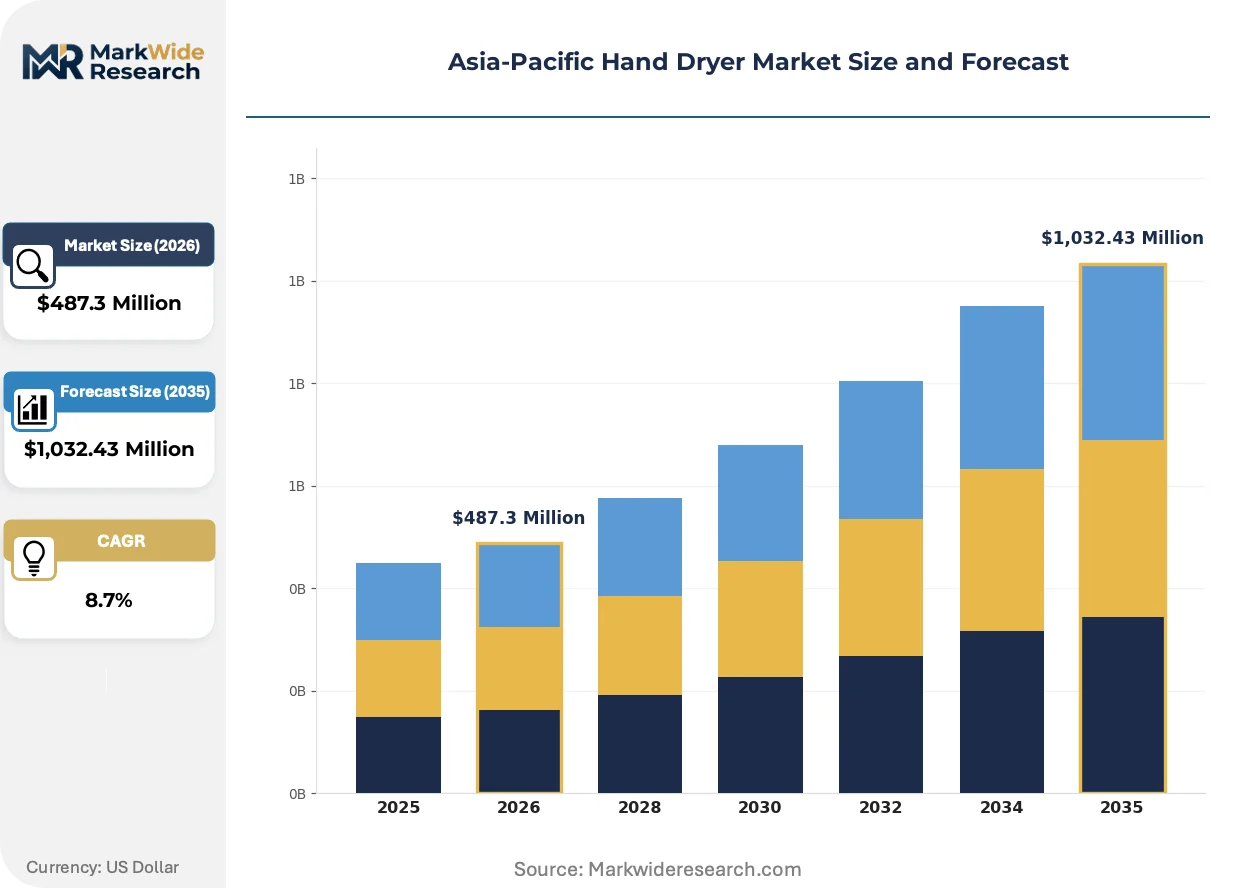
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, High-Speed, Infrared End User: Commercial, Healthcare, Education, Hospitality Installation Type: Wall-Mounted, Floor Stand, Portable, Countertop Technology: Jet Air, Warm Air, Eco-Friendly, Hybrid |
| Companies Covered | World Dryer, TOTO, Dyson, Panasonic, AIKE, Mitsubishi Electric, Bobrick Washroom Equipment, JVD, Excel Dryer, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hand Dryer Market Emerging Trajectories
Digital motor architectures and connected facility management systems are compressing replacement cycles and reshaping procurement specifications across commercial restroom infrastructure.
Brushless DC motors operating above 100,000 RPM are digitizing performance monitoring capabilities through embedded Hall-effect sensors and real-time current-draw analytics. Airport operators in Seoul and Hong Kong are specifying these units for high-traffic concourses where predictive maintenance reduces downtime. The technology is digitizing competitive differentiation by enabling outcome-based service contracts that tie vendor compensation to operational uptime metrics.
China's SAMR enforcement of GB 4706.15 for electrical safety in public restroom equipment is tightening compliance windows for imported products. Manufacturers must submit electromagnetic compatibility test reports to regional certification bodies before facility procurement teams can specify equipment. Healthcare and hospitality segments in tier-one cities are responding by demanding pre-certified product lines with documented conformity assessment documentation.
Facility procurement teams are consolidating supplier relationships around vendors offering bundled installation and multi-year maintenance agreements. Traditional distributor networks serving education and municipal segments are losing share to manufacturer-direct service organizations. This consolidation is most visible in Australia's commercial property management sector, where REITs are standardizing hand dryer specifications across portfolio-wide restroom retrofits.
Asia-Pacific Hand Dryer Market Segmentation
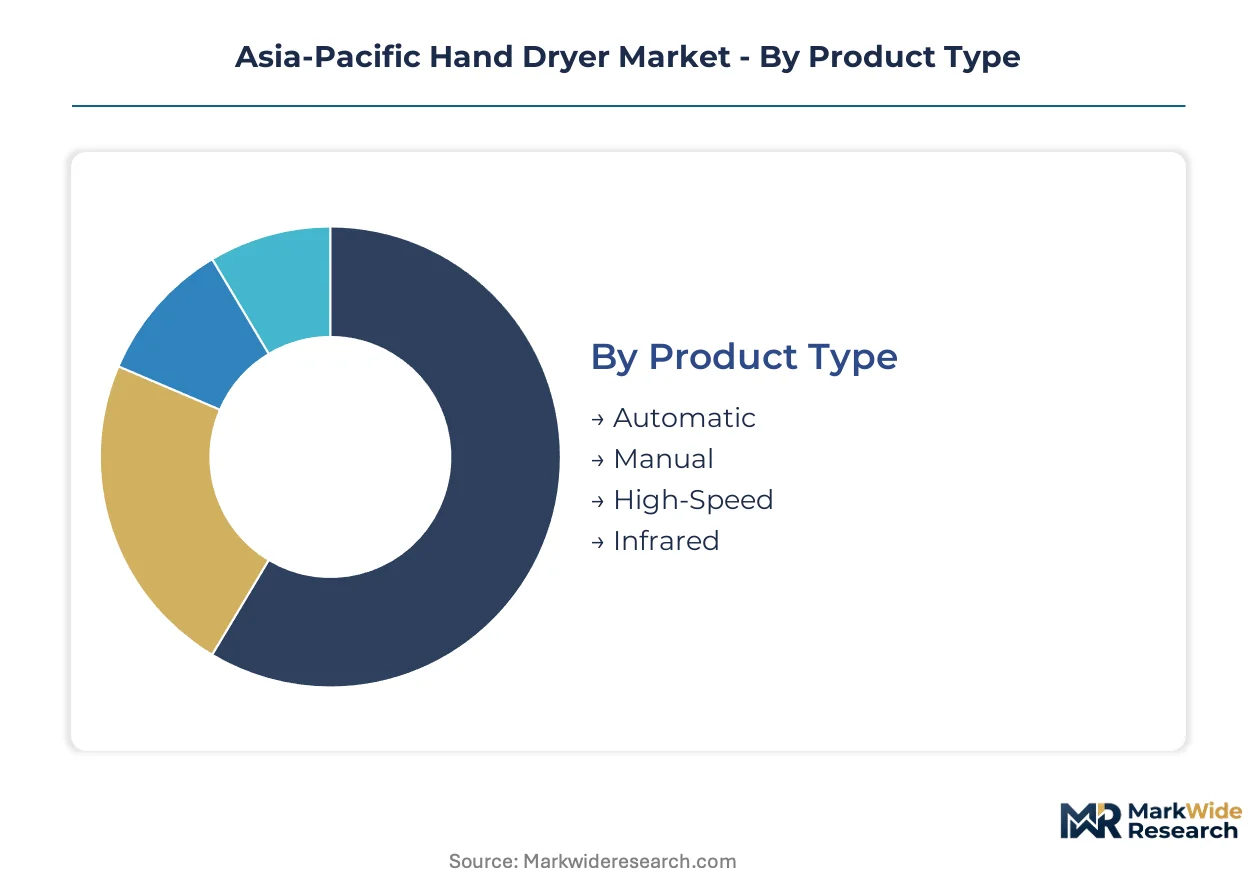
Product architecture, installation constraints, and facility-specific hygiene protocols create distinct demand pockets across the Asia-Pacific hand dryer landscape. Procurement teams in airports, hospitals, and schools prioritize different performance attributes, fragmenting supplier go-to-market strategies.
Product Type:
Mature automatic formats coexist with emerging high-speed variants as facility operators balance capital constraints against operational throughput requirements.
- Automatic:Sensor-activated units dominate transit hubs and corporate campuses across Shanghai and Singapore. Touchless activation protocols in healthcare settings accelerate replacement of manual push-button units.
- Manual:Push-button warm-air products retain share in India's municipal schools and budget-constrained commercial developments. BIS energy-performance labeling mandates pressure suppliers to improve motor efficiency in this price-sensitive tier.
- High-Speed:Brushless DC motors exceeding 100,000 RPM compress dry times to 10-12 seconds. Premium hospitality developments in Sydney and Seoul specify these units for guest experience differentiation.
- Infrared:Proximity-sensing activation modules integrate with building automation systems. Smart restroom deployments in Tokyo's commercial towers favor these connected variants.
Automatic retains volume leadership; high-speed holds the steepest expansion curve.
End User:
Application-specific hygiene benchmarks and traffic density patterns reshape procurement specifications across facility types.
- Commercial:Mixed-use developments and retail complexes in Beijing and Mumbai drive bulk procurement of standardized warm-air units. Facility management contractors negotiate multi-year maintenance bundles to reduce total cost of ownership.
- Healthcare:Infection-control protocols in Singapore's public hospitals and Australia's private clinic networks mandate HEPA-filtered jet air systems. Sensor calibration requirements create vendor stickiness through specialized service contracts.
- Education:India's K-12 infrastructure expansion and Japan's school modernization programs absorb high volumes of economy-tier wall-mounted products. Acoustic emission limits in METI building codes disqualify noisier warm-air models.
- Hospitality:Da Nang and Ho Chi Minh City hotel developments specify designer-integrated hand dryers for guest restroom aesthetics. Jet air technology captures preference in five-star properties where dry time justifies capital outlay.
Commercial commands procurement volume; healthcare generates the highest margin per unit.
Installation Type:
Physical mounting constraints and restroom footprint limitations determine product form factor selection across new construction and retrofit projects.
- Wall-Mounted:Recessed and surface-mounted configurations dominate standard commercial restroom layouts. China's tier-one city building codes specify minimum clearance requirements that favor compact motor assemblies.
- Floor Stand:Freestanding units serve temporary installations and high-traffic overflow areas. Exhibition centers in Bangkok and Kuala Lumpur deploy these for event-driven capacity scaling.
- Portable:Battery-powered and plug-in variants address construction site welfare facilities and outdoor event infrastructure. Limited dry-time performance restricts penetration beyond temporary use cases.
- Countertop:Integrated basin-mounted systems appear in premium hospitality and designer commercial fit-outs. Space-constrained restrooms in Tokyo's high-rise developments favor this minimalist aesthetic.
Wall-mounted anchors installed base; countertop gains share in premium new construction.
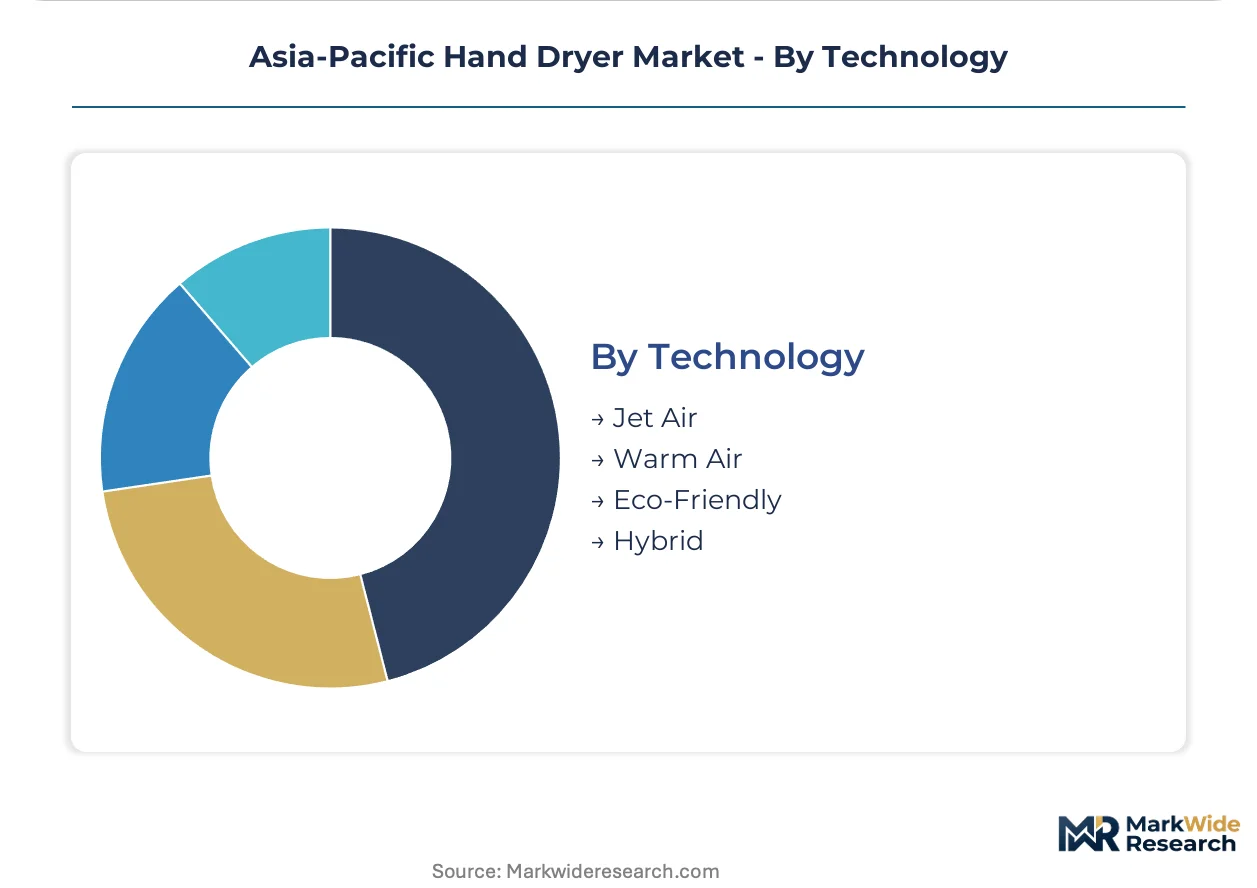
Technology:
Energy efficiency trajectories and dry-time performance separate procurement tiers across climate zones and electricity tariff environments.
- Jet Air:High-velocity unheated air streams strip water through kinetic force rather than evaporation. Airport operators in Hong Kong and Seoul specify these for concourse throughput where seconds per user accumulate to operational capacity.
- Warm Air:Heated airflow systems dominate education and mid-tier commercial demand. India's BIS star-rating requirements pressure manufacturers to improve heat-exchanger efficiency in this cost-sensitive segment.
- Eco-Friendly:Heat-recovery motor systems and low-wattage designs expand most quickly as electricity tariffs escalate across metropolitan transit hubs. Australia's commercial property REITs standardize these for portfolio-wide sustainability commitments.
- Hybrid:Dual-mode units switch between jet and warm air based on ambient temperature sensors. Seasonal climate variation in northern China and Japan creates addressable demand for adaptive performance.
Warm air maintains installed base dominance; eco-friendly climbs the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-RPM motor manufacturing clusters in Guangdong and Osaka concentrate component supply, while procurement demand fragments across metropolitan transit hubs and hospitality developments throughout the region.
China
Shanghai and Beijing facility managers accelerate replacement cycles to meet SAMR-mandated GB standards for electromagnetic compatibility. China's SAMR enforces certification timelines that extend product launch schedules. Tier-one city building codes specify minimum clearance requirements favoring compact motor assemblies in new commercial construction.
Japan
Tokyo commercial towers drive smart restroom deployments favoring connected infrared variants. METI building energy codes impose noise thresholds that disqualify older warm-air models from new construction. Osaka anchors regional manufacturing scale with integrated production of high-efficiency motors and sensor assemblies.
India
Mumbai mixed-use developments and Delhi-NCR transit hubs absorb bulk procurement of standardized warm-air units. BIS mandates energy-performance labeling for commercial appliances, creating regulatory tailwind for certified low-wattage product lines. Metropolitan school modernization programs in Maharashtra and Karnataka drive economy-tier wall-mounted demand.
Australia
Sydney and Melbourne REITs standardize hand dryer specifications across portfolio-wide restroom retrofits. Commercial property management consolidation favors vendors offering bundled installation and multi-year maintenance agreements. Healthcare facilities in New South Wales specify HEPA-filtered jet air systems to meet infection-control benchmarks.
Vietnam
Da Nang and Ho Chi Minh City hotel developments present first-mover positioning for jet-air technology suppliers. Underpenetrated hospitality infrastructure creates addressable demand for guest experience differentiation. Five-star properties specify designer-integrated units where dry time justifies capital outlay.
Asia-Pacific Hand Dryer Market Vendor Landscape
Integrated manufacturers and specialized component suppliers split the market along technology-control and service-coverage vectors. The vendor base organizes into three strategic archetypes: full-stack producers capturing margin through captive motor and sensor production; brand-anchored specialists leveraging proprietary digital architectures; and regional fabricators competing on installation proximity and maintenance response times. Competitive moves concentrate on backward integration into permanent magnet supply chains and direct-to-facility channel disintermediation.
Within the full-stack producer tier, Mitsubishi Electric and Panasonic exemplify integrated manufacturing positions, while TOTO anchors the service-network archetype through recurring maintenance contract capture. Dyson occupies a position on the premium-technology vector, with its proprietary digital motor architecture representing the brand-anchored specialist model. These three companies collectively illustrate the competitive geometry defined by manufacturing scale, proprietary technology control, and aftermarket service coverage across the Asia-Pacific landscape.
| Leading Market Players |
|---|
| World Dryer |
| TOTO |
| Dyson |
| Panasonic |
| AIKE |
| Mitsubishi Electric |
| Bobrick Washroom Equipment |
| JVD |
| Excel Dryer |
| Others |
Supply Flow & Price Mechanics
Guangdong and Osaka manufacturing clusters for brushless DC motors above 100,000 RPM concentrate upstream supply power, directing margin capture toward integrated producers with captive motor and sensor production. Facility procurement teams face asymmetric pricing power where component scarcity in permanent magnet assemblies translates directly to tiered product positioning downstream.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture across the Asia-Pacific hand dryer landscape. Three-tier pricing structure across premium, standard, and economy levels segments procurement tiers by certification grade and motor performance specifications. Pricing pressure stems from electricity tariff escalation pressuring facility operators toward low-wattage certified units. Education and municipal segments in India exhibit highest price sensitivity, while healthcare facilities in Singapore and Australia absorb premium positioning for infection-control compliance.
Supply Chain Analysis
Permanent magnet feedstock for compact motor assemblies draws from China, Japan, and South Korea processing clusters. Neodymium rare-earth magnets, copper windings, and infrared sensor modules constitute critical input dependencies. Single-source vulnerability concentrates in Guangdong motor winding facilities exposed to export quota policy shifts. Distribution runs through manufacturer-direct service organizations disintermediating traditional distributor networks across Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific hand dryer demand disruption accelerates through regulatory tightening on energy-performance labeling and electromagnetic compatibility certification. India's BIS mandates and China's SAMR enforcement compress replacement cycles and reshape procurement specifications across commercial facility portfolios.
For Market Incumbents: Entrench service-network density to capture recurring maintenance contracts as procurement consolidates around bundled installation agreements. Backward integration into permanent magnet supply chains defends margin position against rare-earth price volatility. Counter direct-to-facility channel disintermediation through predictive maintenance capabilities tied to digital motor monitoring systems.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated hospitality sector where Da Nang and Ho Chi Minh City hotel developments lack established supplier relationships. Jet-air technology specifications in five-star properties present first-mover positioning with lower incumbent lock-in than transit hub or healthcare segments. Pursue designer-integrated countertop configurations for premium new construction where aesthetic differentiation commands procurement preference.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional fabricators competing on installation proximity and maintenance response times across Southeast Asian markets. Five-to-ten year viability hinges on certification compliance capabilities as GB standards and BIS labeling mandates tighten. Monitor SAMR electromagnetic compatibility certification timelines as inflection signal for product launch velocity and market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Supply | Captive neodymium sourcing insulates Mitsubishi Electric and Panasonic from export quota volatility. |
| Direct-to-Facility Digital Channel Launch | Procurement platform disintermediation strips margin from traditional distributor networks serving education segments. |
| Predictive Maintenance Service Contract Rollout | Hall-effect sensor analytics enable TOTO's uptime-guarantee positioning in Tokyo commercial towers. |
| GB Standard Pre-Certification Investment | SAMR electromagnetic compatibility documentation accelerates facility specification in Shanghai and Beijing. |
| Heat-Recovery Motor System Development | Eco-friendly variants capture procurement preference as Australia's commercial REITs execute portfolio-wide sustainability commitments. |
Methodological Framework
A standing panel of facility management directors, commercial property procurement leads, aftermarket service technicians, and BIS certification auditors provided ongoing calibration across the research process. Primary interviews with airport operations managers and hospital infection-control officers combined with secondary validation from SAMR certification databases, BIS energy-labeling registries, and METI building code documentation. Customs records for brushless DC motor imports and commercial construction permit filings supplied demand-side triangulation against manufacturer shipment data. Bottom-up facility installation estimates and top-down regional electricity consumption for restroom equipment reconciled through iterative cross-checking.
Scenario-bracketing around regulatory enforcement intensity and electricity tariff trajectory bounded the analytical framework across the projection horizon. Segmentation modeling incorporated product architecture, installation type, end-user facility category, and technology tier dimensions. CAGRs derived from installed base replacement cycles and new commercial construction pipeline analysis. Forecast inputs included SAMR certification timeline assumptions and BIS star-rating adoption curves across Indian metropolitan transit authorities.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and electricity tariff escalation would shift the trajectory of eco-friendly variant adoption. Forecasts reflect documented assumptions on regulatory enforcement consistency and rare-earth magnet price stability. Cross-checking against regional customs data for high-RPM motor component trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Paper Towel Dispenser Market
Household Items
Chest Freezers Market
Household Items
Global Nap Pod Market
Household Items
United States Barbeque Grill Market
Household Items
Sorting Hampers Market
Household Items
Permanent Marker Market
Household Items
Residential Water Purifier Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Electric Brooms Market
Household Items
Leaf Blower Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Saudi Arabia Cookware Market
Household Items
Sanitary Metal Ware Market
Household Items
Bristle Brush Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Gas Hobs Market