
 China Cookware Market | 2026-2036
China Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
China Cookware Market Insights
Smart connectivity as a software-defined feature layer is realigning how cookware value gets captured. Zhejiang Supor Co., Ltd. leverages its appliance ecosystem to bundle intelligent temperature control across product lines. Midea anchors smart kitchen integration through its IoT platform, extending data services beyond hardware margins. Jiangmen Changwen Cookware and Kitchenware Co., Ltd. specializes in OEM scale production for export channels, competing on manufacturing throughput rather than branded software.
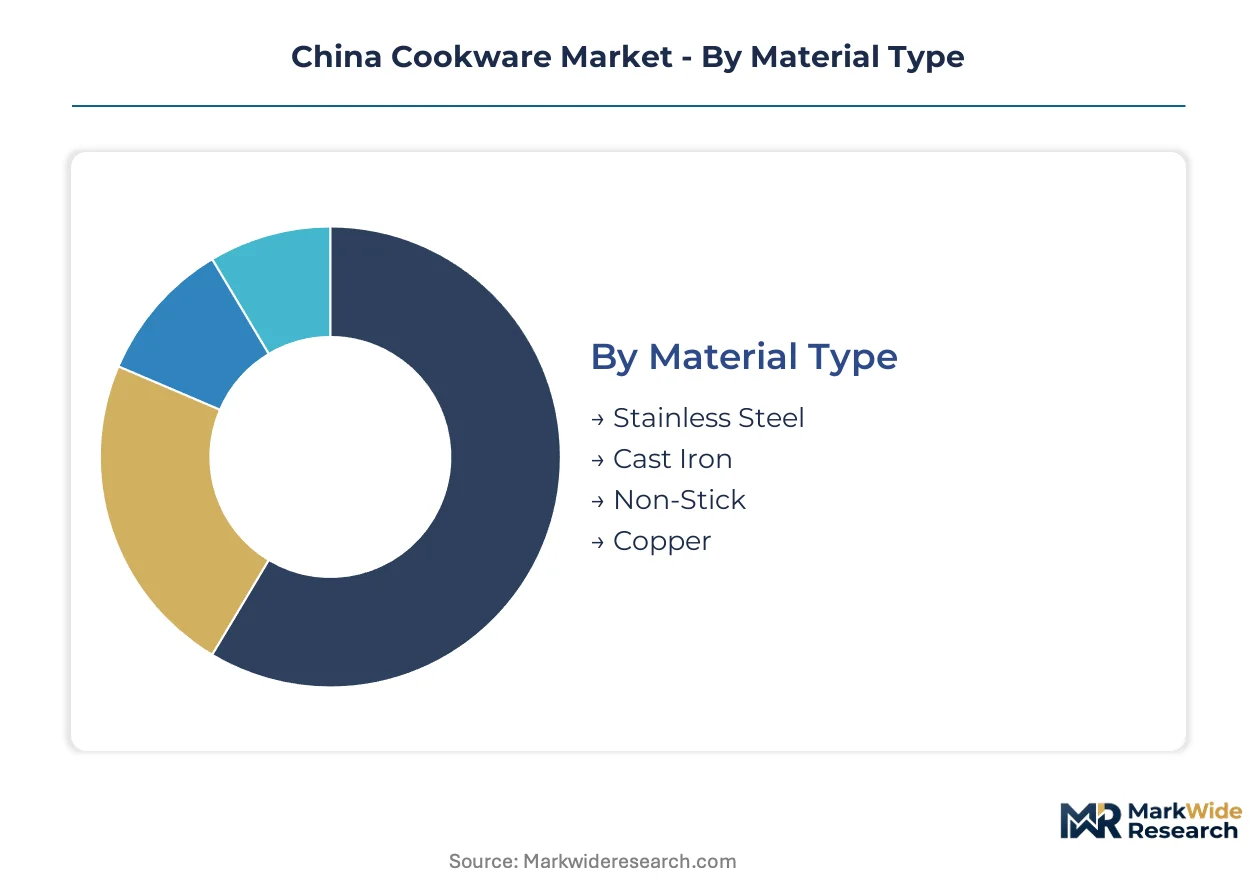
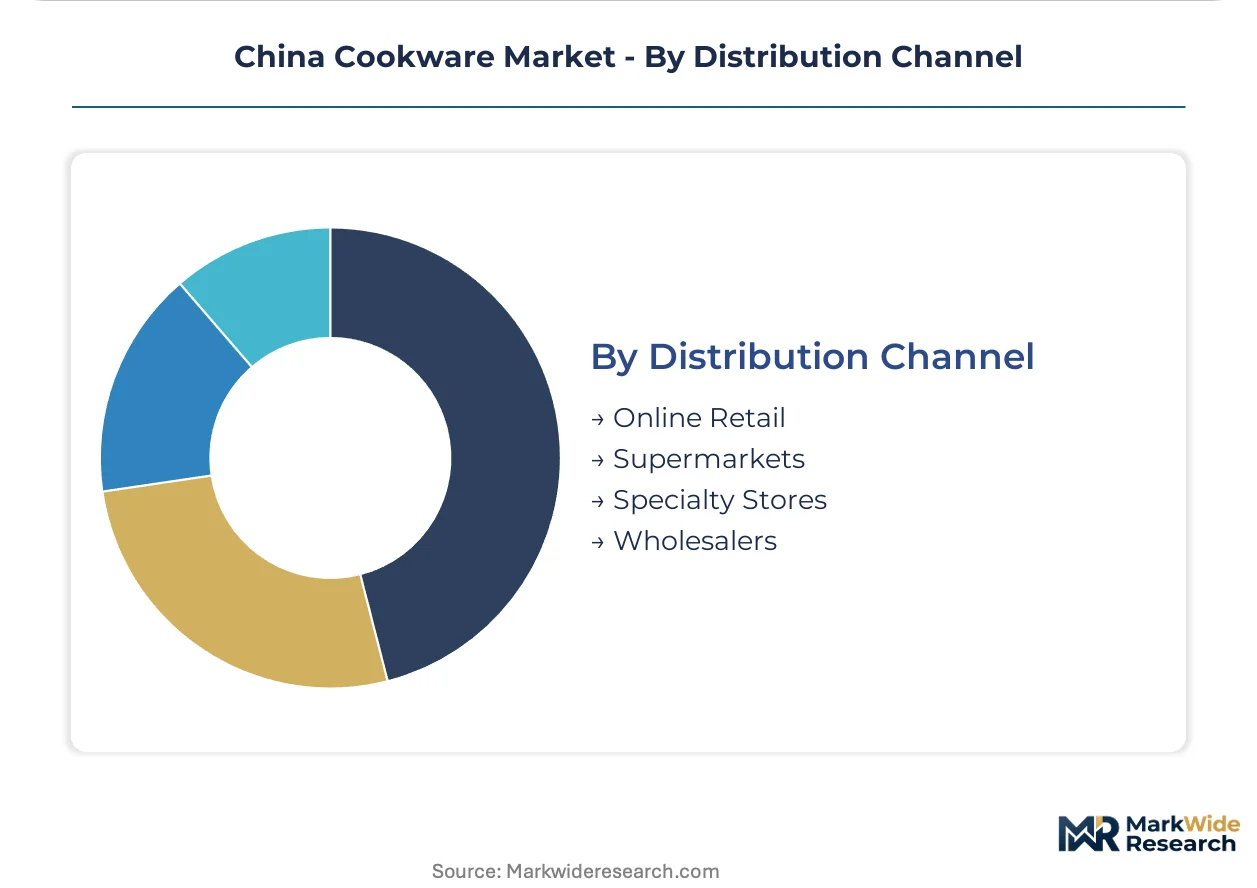
Cookware comprises vessels and utensils fabricated from metals, ceramics, or composites designed for thermal conduction, food preparation, and serving at temperatures typically ranging from 150°C to 300°C depending on application. Stainless steel and cast iron dominate the material type category due to durability and heat retention properties that professional kitchens demand. Online retail channels within the distribution channel segment are capturing the fastest volume expansion as live-stream commerce platforms reshape consumer discovery and purchase behavior. The end user segment shows restaurants and catering companies driving premium non-stick and copper product adoption as commercial operators prioritize labor efficiency and consistent output quality.
China's national standards body administers GB 4806 food-contact material regulations that mandate heavy metal migration limits and coating safety testing for all domestic cookware sales. The State Administration for Market Regulation enforces product quality certification requirements that filter substandard manufacturers from supermarket and specialty store shelves. MIIT smart home standardization initiatives are creating interoperability mandates that favor connected cookware platforms over isolated products. Stakeholders must monitor how GB standard revisions incorporate recycled content requirements and whether smart kitchen data governance rules emerge as a new compliance frontier.
Market Dynamics
Live-stream commerce platforms are compressing purchase cycles and forcing cookware brands to rebuild their distribution economics around real-time engagement rather than traditional retail shelf placement.
Growth Catalysts
- GB 4806 food-contact standards:Heavy metal migration limits and coating safety testing are filtering substandard manufacturers from supermarket channels, elevating compliant brands.
- MIIT smart home interoperability mandates:Connected cookware platforms gain regulatory preference over isolated products, accelerating ecosystem bundling.
- Yangtze River Delta manufacturing cluster:Concentrated stainless steel and aluminum supply chains in Shanghai, Jiangsu, and Zhejiang provinces reduce procurement lead times for domestic brands.
Market Restraints
- Nickel and chromium price volatility:Stainless steel input costs fluctuate with commodity markets, squeezing margin stability for mid-tier producers.
- Coating technology concentration:Premium non-stick ceramic and diamond-infused formulations remain concentrated among specialized chemical suppliers, creating supply bottlenecks.
- Induction compatibility limitations:Cast iron and copper-core products face technical barriers in rural households where induction penetration remains uneven.
Strategic Opportunities
- Central and Western provinces:Henan, Sichuan, and Hubei show underpenetrated premium cookware penetration relative to coastal urban centers.
- Dual carbon policy alignment:Energy-efficient induction-compatible product lines qualify for green manufacturing incentives under national decarbonization targets.
- Community group buying channels:Pinduoduo-style collective procurement models are emerging as a new volume channel beyond traditional e-commerce platforms.
Industry Challenges
- Smart kitchen software integration:Legacy hardware manufacturers lack embedded systems expertise to develop proprietary IoT firmware for temperature control and recipe automation.
- GB standard revision timelines:Pending updates to recycled content requirements create certification uncertainty for product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cookware Market |
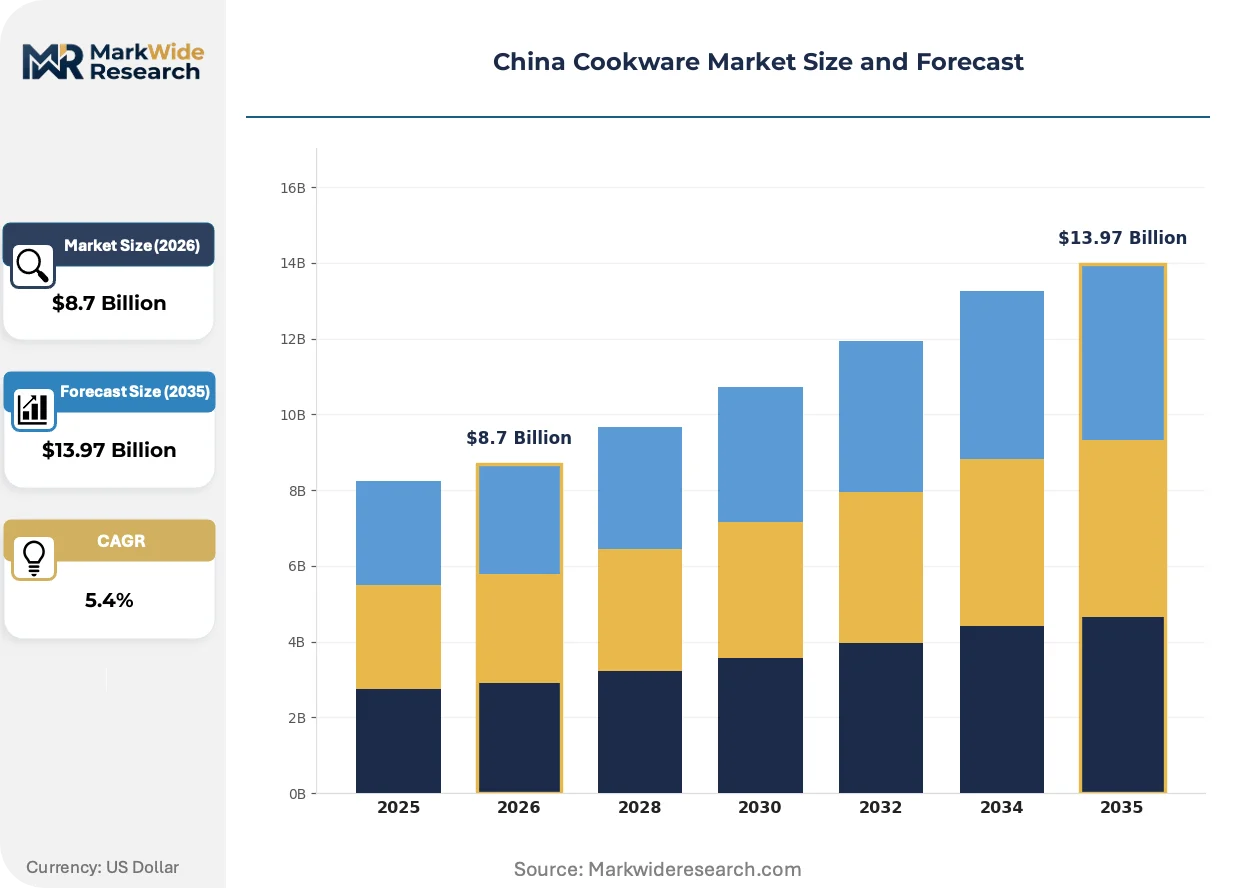
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Cast Iron, Non-Stick, Copper Product Type: Pans, Pots, Bakeware, Utensils End User: Households, Restaurants, Catering Companies, Hotels Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Jiangmen Changwen Cookware and Kitchenware Co., Ltd., Linkfair Household, Zhejiang Supor Co., Ltd., Aishida Co., Ltd., Zhejiang Meyer, Midea, Gree Electric Appliances, Inc., Cooker King, Haier Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cookware Market Trends and Innovations
Material science advances and regulatory tightening are converging to redefine performance benchmarks across price tiers, while digital distribution formats rewrite how value reaches end users.
Multi-layer composite construction is consolidating thermal performance expectations in premium segments. Five-ply copper-core stainless steel configurations now dominate chef-grade demand in Shanghai and Beijing commercial kitchens. This construction method is consolidating heat distribution standards that previously required separate copper and steel vessels.
GB standard revisions for recycled content incorporation are accelerating material traceability investments. Domestic manufacturers must document supply chain provenance to maintain supermarket shelf access under SAMR enforcement protocols. Zhejiang and Jiangsu producers are responding fastest, integrating scrap metal verification systems ahead of formal mandate deadlines.
Live-stream commerce has compressed consumer discovery-to-purchase cycles from weeks to hours. Douyin and Kuaishou platforms now capture significant cookware volume, displacing traditional Tmall flagship store traffic. This behavioral shift concentrates marketing spend on influencer partnerships and real-time demonstration content rather than static product photography.
China Cookware Market Segmentation
Cookware purchasing decisions in China diverge sharply between mass-market commodity buyers and specialized commercial operators seeking precise thermal performance. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows.
Material Type:
Customization intensity runs from standardized commodity metals to engineered composite formulations requiring precise alloy control.
- Stainless Steel:Chromium-nickel austenitic grades dominate commercial kitchen procurement in Shanghai and Beijing due to corrosion resistance and dishwasher durability. Yangtze River Delta fabricators source 304 and 316 grades from local Jiangsu mills, compressing lead times for domestic brands against import competition.
- Cast Iron:Traditional sand-cast vessels retain heat distribution advantages for slow-cooking applications across Sichuan and Hunan provincial restaurants. Enamel-coated variants from Hebei foundries command premium positioning in urban household segments seeking aesthetic table-to-oven functionality.
- Non-Stick:Ceramic and diamond-infused polymer coatings from specialized chemical suppliers enable reduced-oil cooking for health-conscious consumers in Guangdong and Zhejiang.
- Copper:Pure copper and copper-core laminates serve professional chef demand in Michelin-tracked establishments across Shenzhen and Chengdu where thermal responsiveness determines output consistency.
Leading the category by volume: Stainless Steel. Growing fastest: Non-Stick.
Product Type:
Application specificity separates single-purpose vessels from modular systems designed for kitchen workflow integration.
- Pans:Wok configurations dominate Chinese household and restaurant use, with carbon steel and clad stainless variants sized for residential gas burners versus commercial range outputs. Live-stream commerce platforms now move significant volume through real-time cooking demonstrations.
- Pots: Stockpots and saucepans concentrate demand in catering operations across Henan and Hubei where batch preparation efficiency drives procurement decisions. Multi-ply construction with aluminum cores penetrates premium segments seeking reduced scorching.
- Bakeware: Sheet pans, cake molds, and specialty forms serve Western-influenced bakery chains expanding in Tier-2 cities. Silicone and aluminized steel formulations compete on release properties and thermal cycling durability.
- Utensils: Ladles, spatulas, and skimmers complete cookware sets for household gift-giving occasions, with bamboo and high-temperature nylon gaining share against traditional metal tools.
Volume leadership: Pans. Steepest expansion trajectory: Bakeware.
End User:
Purchasing sophistication scales from price-sensitive household decision-makers to procurement departments with total-cost-of-ownership frameworks.
- Households:Replacement cycles accelerate in urban centers where kitchen renovation triggers coordinated appliance and cookware upgrades. Douyin and Kuaishou discovery patterns compress consideration phases from weeks to single sessions.
- Restaurants: Independent operators and chain franchises in Guangzhou and Hangzhou prioritize induction compatibility and rapid thermal recovery for high-turnover service environments.
- Catering Companies: Central kitchen operations across Shandong and Jiangsu specify NSF-equivalent certification and stackability for storage density in high-volume meal production.
- Hotels: International chain properties in Beijing and Shanghai source uniform specifications across property portfolios, with in-room dining presentation ware requiring dishwasher-safe finishes.
Volume concentration: Households. Fastest commercial expansion: Catering Companies.
Distribution Channel:
Channel economics separate inventory-heavy traditional retail from digitally native fulfillment models with different working capital requirements.
- Online Retail:Tmall, JD.com, and emerging live-stream platforms capture urban household volume through algorithmic personalization and influencer endorsement. Same-day delivery capabilities in Tier-1 cities reduce purchase friction for impulse replacements.
- Supermarkets: RT-Mart, Yonghui, and regional chains maintain cookware aisles for tactile evaluation by older demographics less comfortable with digital purchasing. SAMR certification visibility filters non-compliant products from shelf access.
- Specialty Stores: Kitchenware boutiques in Shanghai Xintiandi and Beijing SKP position premium imports and domestic designer collections for gift purchasing occasions.
- Wholesalers: Yiwu market distributors and regional supply houses serve restaurant and hotel procurement through relationship-based volume pricing and extended payment terms.
Volume leadership: Online Retail. Gaining share fastest: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in eastern coastal provinces while consumption spreads inland through e-commerce penetration. The Yangtze River Delta generates the majority of stainless steel and aluminum fabrication output. Provincial governments compete through green manufacturing incentives and smart home integration mandates.
Shanghai
High-income households drive replacement cycles for premium multi-ply cookware. SAMR enforces GB 4806 certification visibility across retail channels. Pudong and Minhang districts host headquarters operations for brands coordinating national distribution networks.
Jiangsu
Stainless steel mills in Wuxi and Changzhou supply 304 and 316 grades to downstream fabricators. MIIT smart home interoperability standards favor connected product development in Suzhou industrial parks. Yangzhou enamel-coating foundries serve export markets through Ningbo port access.
Zhejiang
Yongkang hardware clusters produce carbon steel woks for domestic and Southeast Asian markets. Hangzhou live-stream commerce studios generate significant cookware volume through influencer partnerships. Ningbo port logistics reduce export lead times for OEM manufacturers.
Guangdong
Pearl River Delta factories supply ceramic-coated non-stick products for health-conscious consumers in Shenzhen and Guangzhou. GB standard revisions on coating safety testing filter smaller producers from supermarket shelves. Foshan aluminum extrusion plants feed downstream cookware assembly.
Sichuan
Chengdu restaurant operators drive demand for cast iron vessels in slow-cooking applications. Underpenetrated premium segments relative to coastal cities attract brand expansion through JD.com regional fulfillment centers. Chongqing manufacturing zones develop induction-compatible product lines for western province households.
China Cookware Market Competitive Landscape
Top-tier vendors anchor ecosystem bundling strategies, while mid-scale fabricators compete on manufacturing throughput and OEM relationships. The market exhibits tiered concentration with appliance conglomerates, specialized cookware brands, and export-focused manufacturers occupying distinct competitive positions. Appliance conglomerates leverage IoT platforms for smart kitchen integration. Specialized brands compete on material science and coating technology. Export manufacturers prioritize scale economies and certification compliance. Dominant competitive moves include backward integration into metal supply chains and strategic partnerships with live-stream commerce platforms.
Within the ecosystem-tier, Zhejiang Supor Co., Ltd. and Midea occupy positions that exemplify platform-based competition through connected product portfolios. Jiangmen Changwen Cookware and Kitchenware Co., Ltd. represents the manufacturing-scale archetype serving export channels. These three anchors illustrate how competitive advantage separates across software-defined features, brand equity, and production efficiency.
| Leading Market Players |
|---|
| Jiangmen Changwen Cookware and Kitchenware Co., Ltd. |
| Linkfair Household |
| Zhejiang Supor Co., Ltd. |
| Aishida Co., Ltd. |
| Zhejiang Meyer |
| Midea |
| Gree Electric Appliances, Inc. |
| Cooker King |
| Haier Inc. |
| Others |
Pricing and Supply Chain Analysis
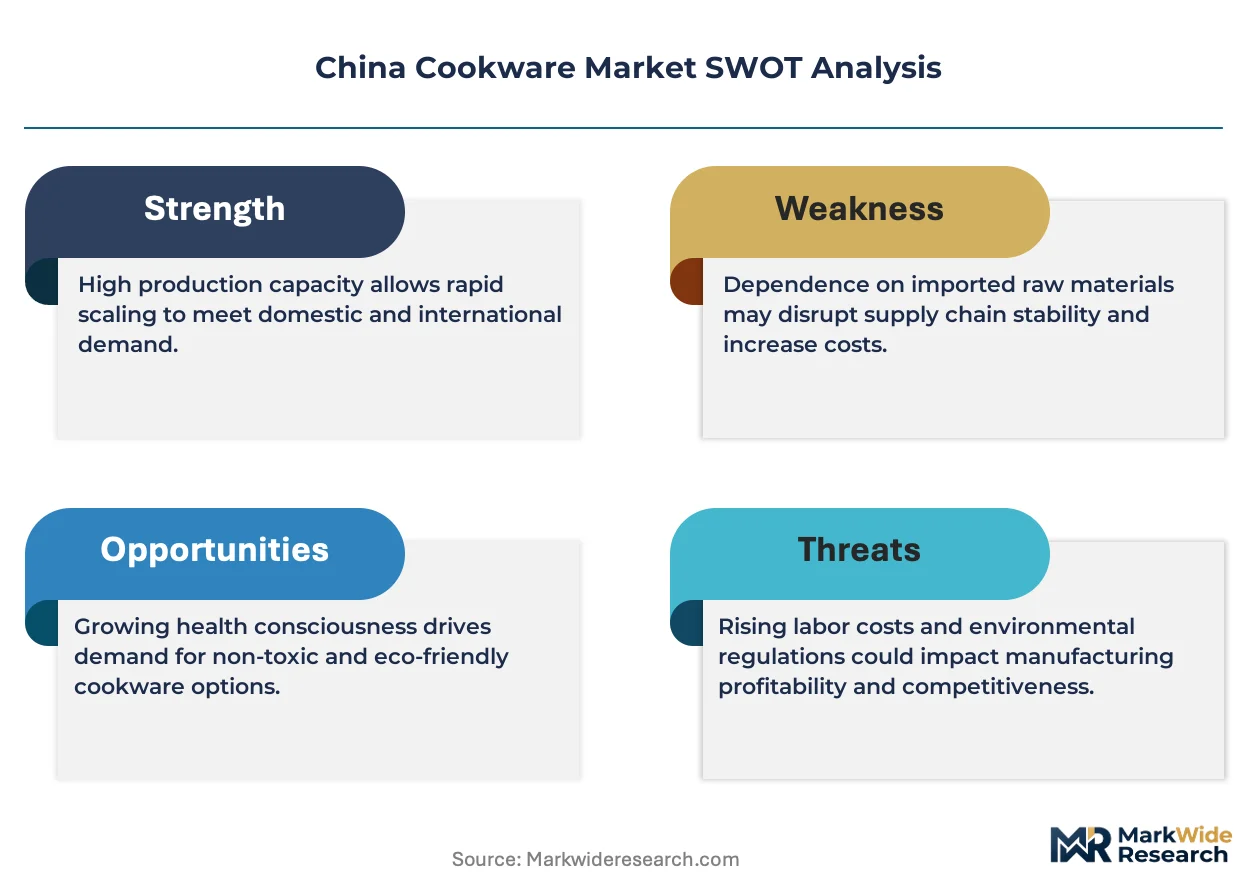
Certification-grade bifurcation between GB 4806-compliant premium tiers and uncertified commodity production manifests in pricing power concentration among Yangtze River Delta fabricators while squeezing margin structures for inland assemblers dependent on spot metal purchases. This divergence feeds directly into supply chain configurations, as SAMR enforcement filters non-compliant manufacturers from supermarket channels and live-stream commerce platforms amplify price transparency for discerning urban buyers.
Pricing Analysis
Margin tightening in mid-tier stainless steel cookware reflects nickel and chromium price volatility transmitted from Jiangsu mill contracts to downstream fabricators. Three-tier pricing structure across premium, standard, and economy levels separates induction-compatible multi-ply products from single-layer aluminum vessels and uncoated carbon steel woks. Pricing pressure intensifies in standard tiers as live-stream commerce platforms compress promotional cycles and force inventory liquidation. Household buyers in Tier-2 cities exhibit highest price sensitivity, while Michelin-tracked restaurant procurement in Shenzhen prioritizes thermal performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized ceramic and diamond-infused coating suppliers concentrated in Guangdong and Zhejiang chemical parks. Raw material flows draw from Jiangsu stainless steel mills, Hebei cast iron foundries, and Foshan aluminum extrusion plants. Supply chain risk centers on coating technology concentration creating certification bottlenecks under pending GB standard revisions. Distribution runs through Ningbo and Shanghai port logistics for export OEMs, while domestic fulfillment leverages JD.com regional warehouses and Douyin live-stream studio partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's cookware market is consolidating around regulatory compliance and smart home integration capabilities, with SAMR enforcement and MIIT interoperability mandates forcing subscale manufacturers toward exit or acquisition.
For Market Incumbents: To counter margin erosion from commodity metal price volatility, secure captive supply through backward integration into Jiangsu stainless steel sourcing or long-term offtake agreements with Yangzhou enamel-coating foundries. Defensive positioning requires accelerating GB 4806 certification investments ahead of recycled content mandate deadlines to maintain supermarket shelf access. For New Entrants and Emerging Players: Central and Western province catering operators represent the most penetrable buyer archetype, with Henan and Sichuan central kitchens seeking NSF-equivalent certified stockpots at price points below coastal premium brands. Community group buying channels through Pinduoduo-style collective procurement models offer lower customer acquisition costs than Tmall flagship store competition. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale OEM manufacturers possessing GB certification infrastructure and live-stream commerce platform relationships, given SAMR enforcement creating acquisition opportunities from distressed subscale competitors. Long-term viability favors targets with demonstrated induction-compatible product development and documented supply chain traceability systems. The signal to watch is MIIT smart home standard finalization accelerating ecosystem bundling requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Supply | Jiangsu mill partnerships reduce nickel price exposure for stainless steel fabricators. |
| Smart Kitchen Platform Certification | MIIT interoperability compliance unlocks Midea and Supor ecosystem bundling opportunities. |
| Live-Stream Commerce Partnership | Douyin studio relationships compress discovery-to-purchase cycles for urban household volume. |
| Recycled Content Traceability Investment | Scrap metal verification systems secure SAMR shelf access under pending GB revisions. |
| Central Province Distribution Expansion | JD.com regional fulfillment centers penetrate underpenetrated Henan and Sichuan catering demand. |
Research Methodology
Independent corroboration across SAMR certification databases, Yangtze River Delta customs records, and MIIT smart home standard filings underwrites the qualitative findings presented. Primary interviews with cookware brand procurement directors, Jiangsu stainless steel mill sales managers, and Guangdong coating technology R&D leads combined with secondary validation from GB standard revision drafts and live-stream commerce platform disclosure statements. Bottom-up volume estimates from provincial manufacturing cluster surveys triangulate against top-down market sizing from appliance ecosystem revenue allocations.
Comparable-period anchoring to historical replacement cycle data and urban household kitchen renovation rates shapes the projection methodology across the analysis window. Segmentation dimensions modeled include material type, product configuration, end-user procurement sophistication, and distribution channel economics. CAGRs derive from fitted growth curves incorporating MIIT smart home penetration assumptions and SAMR enforcement intensity scenarios. Industry-specific inputs include nickel futures price trajectories and live-stream commerce platform GMV disclosure patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GB standard revision timelines and dual carbon policy implementation pace. Forecasts reflect documented assumptions regarding induction cooker household penetration rates and recycled content mandate effective dates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Trash Can Market
Household Items
Garbage Disposals Market
Household Items
Kuwait Gas Hobs Market
Household Items
India Digital Showers Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Electric Shoe Dryer Market
Household Items
Powered Lawn Mowers Market
Household Items
Shoe Shine Machine Market
Household Items
Luxury Massage Chair Market
Household Items
Shower Heads Market
Household Items
Air Freshener Market
Household Items
Dryer Sheets Market
Household Items
Portable Showers Market
Household Items
Mosquito Repellent Candles Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market