
 Multi-Door Fridges Market | 2026-2036
Multi-Door Fridges Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Door Fridges Market Insights
Software-defined temperature zoning through subscription-based cooling profiles is pivoting how manufacturers monetize multi-door refrigerators beyond the initial hardware sale. Samsung Electronics leverages its SmartThings ecosystem to sustain recurring engagement through automated inventory tracking and recipe suggestions. LG Electronics anchors its competitive position with InstaView technology and craft ice production capabilities that differentiate premium French Door offerings.
Multi-door fridges are refrigeration appliances with three or more compartment doors, typically employing dual or variable compressor systems to maintain independent temperature and humidity zones between 0°C and 5°C for fresh produce preservation alongside sub-zero freezer chambers. French Door configurations command the largest installed base among product types due to ergonomic access patterns and flexible storage geometry, while Smart Fridge technology represents the fastest-expanding technology segment as voice integration and camera-based inventory systems migrate from flagship to mid-tier price bands. Energy Efficient certification tiers concentrate margin pools in markets where MEPS standards tighten procurement specifications for residential and food service end users.
The US Department of Energy enforces minimum efficiency standards under ENERGY STAR that compel compressor redesigns and vacuum panel insulation adoption, while the EU F-Gas Regulation mandates hydrofluorocarbon phase-down timelines affecting refrigerant selection across Electrolux AB and BSH Hausgeräte manufacturing footprints. China's GB standards on household appliance energy consumption create parallel compliance obligations for Haier Group Corporation and Midea Group domestic production. Stakeholders must monitor divergence between regional refrigerant protocols and smart appliance data governance frameworks to align R&D allocation with market access requirements.
Market Dynamics
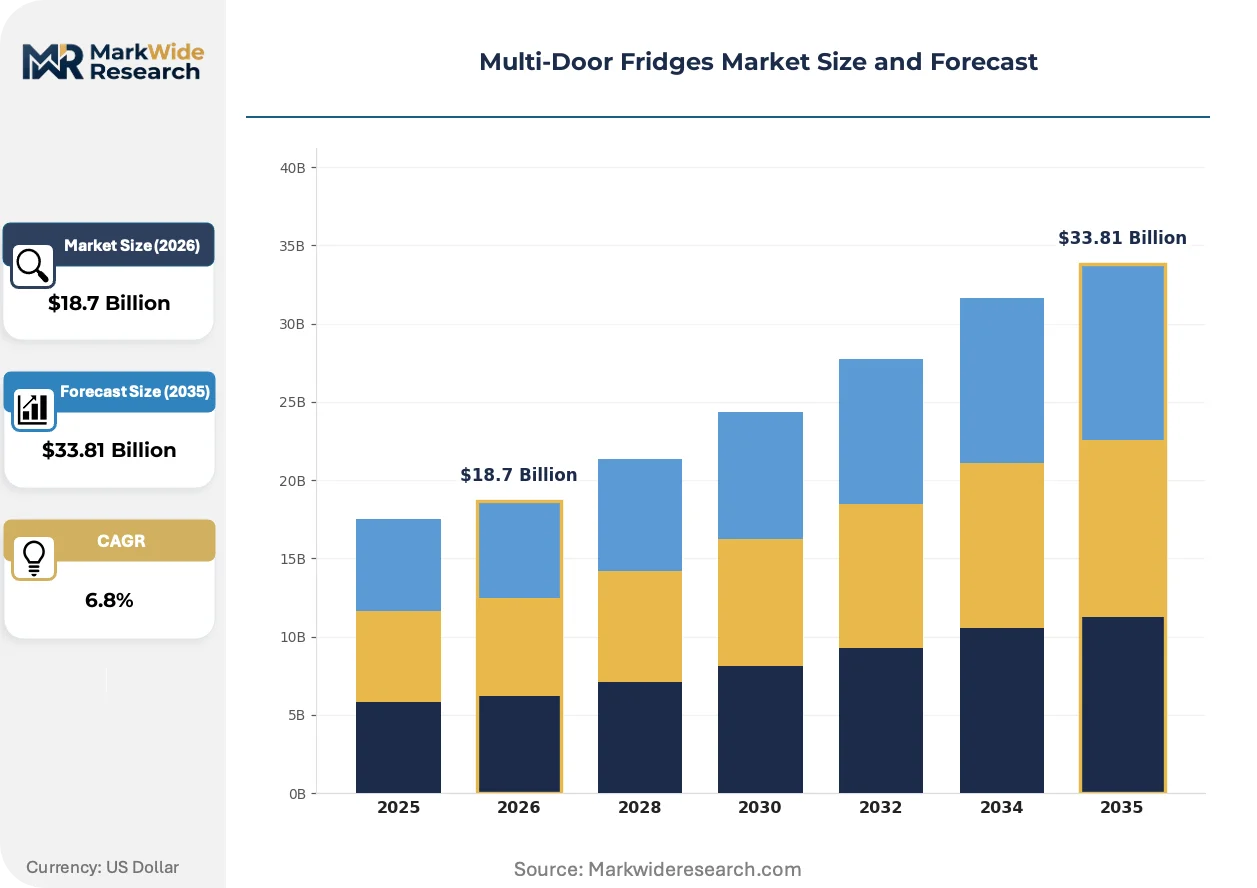
Convertible cooling zones and software-defined temperature management are restructuring how manufacturers capture value, shifting revenue from one-time hardware sales toward recurring digital services attached to multi-door refrigerator ecosystems.
Growth Catalysts
- F-Gas Regulation phase-down:The EU mandate on hydrofluorocarbon reduction accelerates compressor redesigns and natural refrigerant adoption across European manufacturing footprints.
- Urban household density:Residential consumers in tier-one Chinese cities prioritize French Door configurations with flexible storage geometry for space-constrained kitchens.
- Smart appliance ecosystems:Voice integration and camera-based inventory systems migrate from flagship to mid-tier price bands, expanding addressable market for connected multi-door units.
Market Restraints
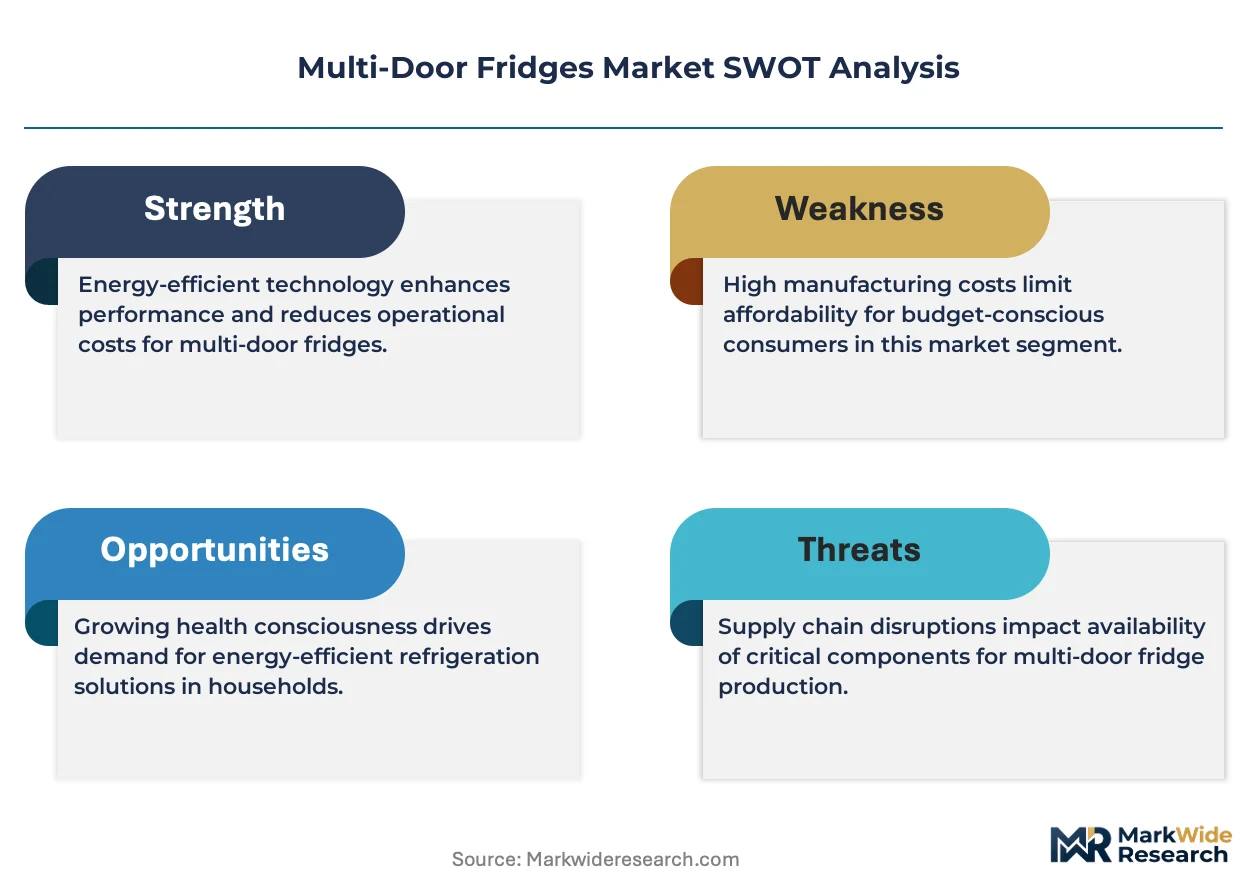
- Copper and steel input volatility:Compressor manufacturing and cabinet fabrication face margin pressure from base metal price swings in commodity markets.
- Refrigerant protocol fragmentation:Divergent phase-down timelines between EU F-Gas Regulation, US EPA SNAP rules, and China's GB standards complicate platform standardization.
- Technical limitation in vacuum panel insulation:Manufacturing scale constraints and assembly complexity limit adoption in cost-sensitive product tiers.
Strategic Opportunities
- Subscription-based cooling profiles:Software-defined temperature zoning enables recurring revenue streams through automated inventory tracking and recipe suggestion services.
- India PLI scheme incentives:Production-linked incentive frameworks for white goods manufacturing attract component localization and domestic assembly investments.
- Grocery delivery platform integration:Smart fridge inventory management converges with e-commerce logistics, creating data monetization pathways in China's urban markets.
Industry Challenges
- Refrigeration engineer scarcity:Natural refrigerant system design and variable compressor calibration require specialized technical talent in short supply across manufacturing bases.
- Multi-jurisdiction certification timelines:Parallel ENERGY STAR, BIS energy labeling, and GB standards compliance extend product launch cycles and testing expenditures.
- Legacy kitchen footprint incompatibility:French Door and Side-by-Side dimensions conflict with existing cabinetry standards in retrofit residential installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Door Fridges Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side-by-Side, French Door, Bottom Freezer, Top Freezer Technology: Smart Fridge, Energy Efficient, Convertible, Frost Free End User: Residential, Commercial, Hospitality, Food Service Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Appliance Showrooms |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Electrolux AB, Haier Group Corporation, BSH Hausgeräte, Panasonic Corporation, Midea Group, Hisense Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Door Fridges Market Trends and Innovations
Digital service layers are absorbing hardware-centric business models across the multi-door refrigerator value chain, with manufacturers competing on software integration depth rather than cooling performance alone.
Variable compressor technology is absorbing fixed-speed system share as dual and inverter-driven configurations enable precise temperature modulation between independent zones. Premium residential buyers in South Korea and Japan specify these systems for humidity-sensitive produce preservation. The technology is absorbing margin from conventional compressor suppliers while shifting value capture toward semiconductor and control system vendors.
The EU F-Gas Regulation mandates specific hydrofluorocarbon phase-down percentages that force refrigerant transitions across Electrolux AB and BSH Hausgeräte production lines. Compressor OEMs must qualify alternative working fluids including isobutane and propane blends with revised safety protocols. French Door and premium Side-by-Side segments face the steepest compliance costs due to larger charge sizes and stricter leakage thresholds.
Urban Indian households now specify convertible freezer-to-fridge compartments as standard rather than premium features, compressing upgrade cycles and flattening tiered pricing structures. Retail channels in Mumbai and Delhi report inventory turnover concentration in mid-range SKUs with zone flexibility. This preference rotation pressures manufacturers to democratize features previously reserved for flagship price bands.
Multi-Door Fridges Market Segmentation
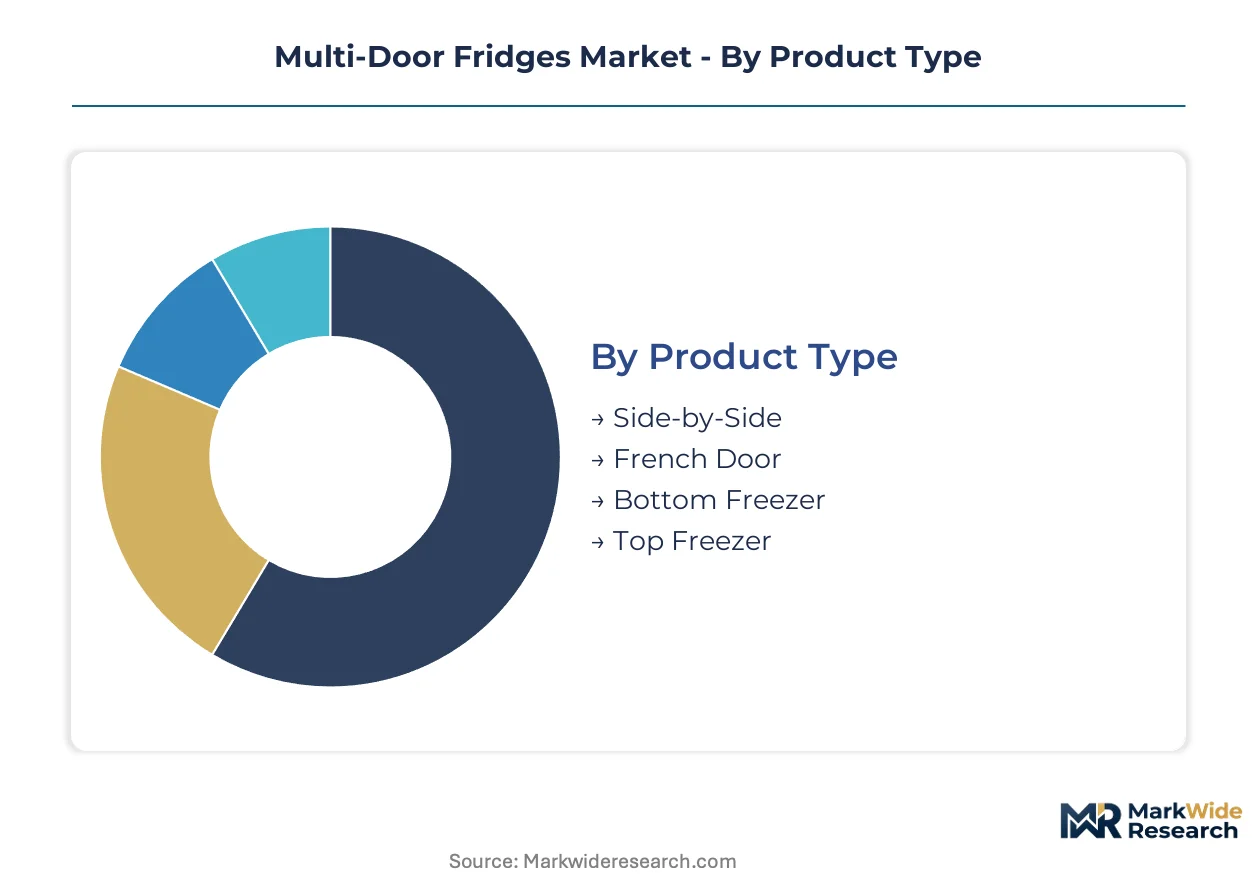
Multi-door refrigerator purchasing patterns diverge sharply across household configurations, energy compliance regimes, and channel access. Manufacturers must align platform architectures with these distinct buyer profiles to avoid margin erosion from misaligned feature bundling.
Product Type:
Buyers prioritize door geometry based on kitchen footprint constraints and ergonomic access preferences rather than cooling performance alone.
- French Door:Twin upper doors swing outward from a central mullion, creating wide refrigerated compartments above a pull-out freezer drawer. Urban Indian households in Mumbai and Delhi specify these configurations for space-constrained modular kitchens where aisle clearance limits single-door swing arcs.
- Side-by-Side:Vertical split compartments place fresh food and freezer chambers at eye level with narrow door swing requirements. US residential retrofits favor these units where existing cabinetry predates standard French Door cutout dimensions.
- Bottom Freezer:Single refrigerator door above a drawer-style freezer compartment concentrates value in mid-tier price bands across European markets where ENERGY STAR-equivalent EU labeling drives efficiency-focused procurement.
- Top Freezer:Conventional configuration with freezer compartment above refrigerated storage retains cost-sensitive demand in emerging markets and rental property installations where capital expenditure minimization dominates selection criteria.
French Door leads volumes today; Side-by-Side is gaining share fastest in retrofit-heavy developed markets.
Technology:
Feature differentiation now concentrates in digital service layers and energy compliance tiers rather than mechanical cooling advances.
- Smart Fridge:Camera-based inventory systems, voice integration, and grocery platform APIs transform appliances into kitchen ecosystem hubs. Samsung SmartThings and LG ThinQ deployments in China's tier-one cities integrate with Alibaba and JD.com delivery logistics for automated replenishment workflows.
- Energy Efficient:Vacuum panel insulation, inverter compressors, and optimized refrigerant charges meet escalating MEPS thresholds. US ENERGY STAR certification and India's BIS labeling create parallel procurement specifications that disqualify legacy platforms from government and corporate volume purchasing.
- Convertible:Software-defined temperature zones enable freezer-to-refrigerator compartment switching on demand. Indian urban households now treat this capability as baseline expectation, compressing premium tier pricing power for zone-flexible SKUs.
- Frost Free:Forced-air circulation and automated defrost cycles eliminate manual ice removal. This technology has achieved near-universal adoption in mid-tier and premium segments, relegating direct-cool systems to economy price bands.
Energy Efficient certification dominates current procurement specifications; Smart Fridge connectivity is climbing the fastest as voice and camera systems migrate downward from flagship positioning.
End User:
Volume requirements and compliance obligations fragment demand across household scale and regulatory exposure.
- Residential:Individual household procurement dominates absolute unit volumes, with purchase decisions driven by kitchen renovation cycles, energy label visibility, and smart home ecosystem compatibility. French Door configurations concentrate in owner-occupied housing with sufficient aisle clearance.
- Commercial:Small retail and office installations require compact multi-door units with display visibility and beverage-optimized temperature zones. Procurement runs through specialized dealers with service contract bundling rather than consumer retail channels.
- Hospitality:Hotels and serviced apartments specify built-in or panel-ready multi-door units with uniform aesthetic standards across property portfolios. Volume purchasing agreements with Electrolux AB and BSH Hausgeräte dominate this segment.
- Food Service:Restaurants and catering operations demand NSF-certified commercial variants with stainless steel construction and rapid temperature recovery after door opening. These specifications diverge from residential platforms in compressor duty cycles and insulation density.
Residential channels move the most units annually; Food Service is expanding most quickly as ghost kitchen infrastructure proliferates in urban delivery corridors.
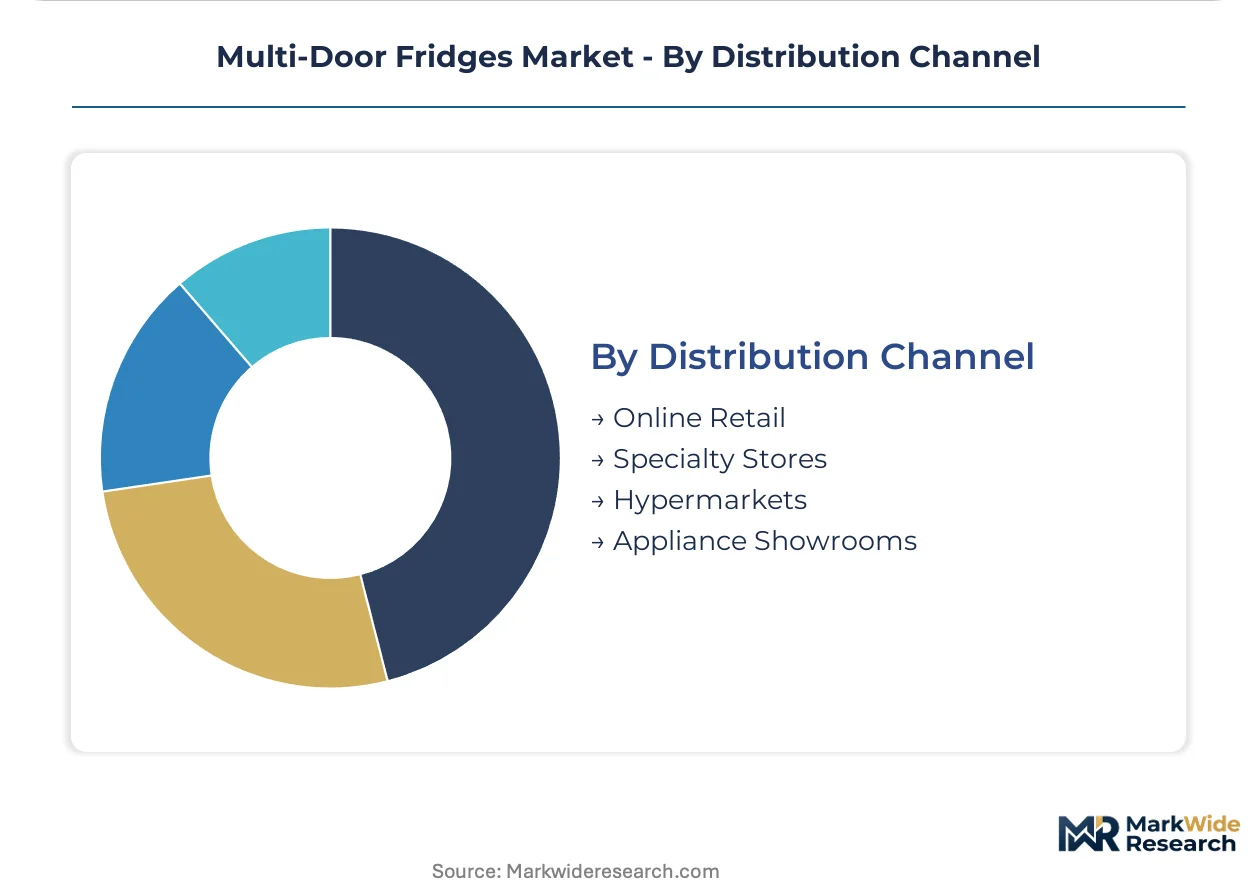
Distribution Channel:
Channel selection determines margin capture, installation service bundling, and post-sale engagement depth.
- Online Retail:Platform aggregators including Amazon and regional equivalents capture price-sensitive comparison shoppers with transparent specification filtering and user review visibility. Logistics networks now accommodate last-mile delivery of 300+ liter appliances in major metropolitan markets.
- Specialty Stores:Dedicated appliance retailers provide consultation-driven selection, installation coordination, and extended warranty programs. These channels retain premium segment concentration where demonstration of InstaView and craft ice features influences purchase decisions.
- Hypermarkets:Mass merchandisers including Walmart and Carrefour stock volume SKUs with promotional pricing cycles tied to holiday and renovation seasons. Limited sales assistance shifts purchasing toward established brand preferences and visible energy label tiers.
- Appliance Showrooms:Manufacturer-owned or exclusive dealer networks showcase full product portfolios with kitchen design integration services. Samsung and LG operate these formats in South Korea and select US markets to control brand presentation and capture installation margin.
Online Retail leads transaction volume today; Appliance Showrooms are gaining share fastest as manufacturers seek direct consumer relationships and subscription service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smart appliance ecosystem integration outpaces India's energy-label-driven procurement, while both markets reshape compressor technology roadmaps through divergent regulatory pathways.
China
Haier and Midea anchor smart fridge deployment in tier-one cities where grocery delivery platforms integrate with refrigerator inventory systems. GB standards on household appliance energy consumption compel domestic manufacturers to optimize refrigerant charges and insulation density. The Yangtze River Delta cluster concentrates production of variable compressor systems for export and domestic premium segments.
India
Urban households in Mumbai and Delhi specify French Door configurations with convertible cooling zones for modular kitchen layouts. BIS energy labeling mandates disqualify legacy platforms from government and corporate volume purchasing. The Maharashtra-Gujarat industrial corridor attracts component localization investments under PLI scheme incentives for white goods manufacturing.
United States
Residential retrofits favor Side-by-Side units where existing cabinetry predates French Door cutout dimensions. ENERGY STAR minimum efficiency standards compel vacuum panel insulation adoption and compressor redesigns. The Southeast manufacturing belt houses assembly operations serving price-sensitive comparison shoppers through mass merchandiser channels.
Germany
Electrolux AB and BSH Hausgeräte production lines face steep compliance costs from EU F-Gas Regulation hydrofluorocarbon phase-down timelines. Natural refrigerant transitions require revised safety protocols for isobutane and propane blends in premium segments. The Bavaria-Baden-Württemberg cluster specializes in built-in and panel-ready units for hospitality portfolio purchasing.
South Korea
Premium residential buyers specify variable compressor technology for humidity-sensitive produce preservation. Samsung SmartThings and LG ThinQ deployments sustain recurring engagement through automated inventory tracking. The Seoul Capital Area concentrates R&D for semiconductor and control system vendors capturing value from inverter-driven configurations.
Multi-Door Fridges Market Competitive Landscape
Top-tier vendors anchor the premium smart appliance tier, while mid-scale fabricators compete on energy compliance and regional distribution density. The vendor base stratifies across three tiers: ecosystem-integrated conglomerates, component-specialized OEMs, and private-label assemblers. Two strategic archetypes dominate: software platform owners monetizing recurring digital services, and efficiency-focused manufacturers capturing margin from tightening MEPS standards. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms navigate refrigerant protocol fragmentation.
Among Asia-Pacific-based conglomerates, Samsung Electronics and LG Electronics exemplify the ecosystem-integrated archetype, while Haier Group Corporation occupies a position bridging smart platform deployment with manufacturing scale. Electrolux AB represents the efficiency-focused European tier, anchoring natural refrigerant transitions under F-Gas Regulation compliance timelines. These three firms collectively illustrate how geographic regulatory exposure shapes competitive positioning across software-defined and hardware-centric value capture models.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| Haier Group Corporation |
| BSH Hausgeräte |
| Panasonic Corporation |
| Midea Group |
| Hisense Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compressor specialists in South Korea and Japan anchor variable-speed system production, creating pricing discipline through captive semiconductor sourcing and long-term OEM supply contracts that resist spot-market volatility.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for inverter-driven compressor modules, compressing margins for legacy fixed-speed suppliers. Three-tier pricing structure across premium smart-enabled, standard energy-certified, and economy direct-cool tiers separates buyers by certification grade and ecosystem integration depth. Cost compression in entry-level segments is intensifying because Indian PLI scheme incentives localize component fabrication. Price-sensitive residential retrofits in the United States drive demand for Side-by-Side configurations, while premium French Door buyers in Seoul and Tokyo absorb smart-feature premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Haier and Midea assembly operations, bypassing distributor markups for compressor and control system procurement. Manufacturing concentrates in China, South Korea, and Germany, with the Yangtze River Delta feeding domestic premium segments and Bavaria specializing in natural refrigerant transitions under EU F-Gas Regulation timelines. Supply draws from copper cathode, electrical steel, and semiconductor wafer inputs. Single-source vulnerability in rare-earth magnet supply for inverter compressor motors creates exposure to export restriction shocks. Distribution runs through manufacturer-direct platforms and specialized appliance retailers with installation service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-door refrigerator manufacturing operates as a geographic-arbitrage play between India's PLI-subsidized component localization and Germany's steep F-Gas Regulation compliance costs, rewarding footprint shifts toward South Asian assembly.
For Market Incumbents: Cement ecosystem lock-in through SmartThings or ThinQ platform exclusivity, preventing subscriber migration to rival digital services. Deepen backward integration into semiconductor and control system production to capture value migrating from mechanical cooling to electronics. Defend against Chinese OEMs' grocery-platform integration by accelerating automated inventory tracking deployment in European and North American markets.
For New Entrants and Emerging Players: Begin with convertible cooling zone specialization for India's mid-range urban households, where BIS energy labeling mandates disqualify legacy imports but local assembly incentives lower barrier to entry. Target Maharashtra-Gujarat industrial corridor partnerships for component sourcing cost parity. Pursue white-label manufacturing contracts for European brands seeking F-Gas Regulation compliance without captive production.
For Investors and Strategic Acquirers: Valuations sit cheapest among private-label assemblers without captive smart-platform development, offering turnaround potential through ecosystem licensing. Long-term viability hinges on refrigerant protocol convergence and software service attachment rates. Acquisition target archetype: mid-scale OEMs with ENERGY STAR certification infrastructure and underutilized capacity in Southeast Asia. Monitor EU F-Gas Regulation phase-down acceleration as inflection signal for natural refrigerant transition capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Platform Integration | Samsung SmartThings and LG ThinQ deployments in China's tier-one cities automate grocery replenishment through Alibaba and JD.com APIs. |
| Natural Refrigerant Transition | Electrolux AB and BSH Hausgeräte production lines in Germany adopt isobutane and propane blends under EU F-Gas Regulation mandates. |
| Component Localization | India's PLI scheme attracts compressor and vacuum panel insulation investments to the Maharashtra-Gujarat corridor. |
| Variable Compressor Scale-Up | Seoul Capital Area R&D centers feed semiconductor and control system demand for inverter-driven configurations. |
| Grocery Platform Partnership | Haier and Midea integrate refrigerator inventory management with delivery logistics in China's urban markets. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and channel inventory audits — were reconciled across primary interviews with white goods procurement managers, compressor OEM technical directors, appliance retailer category buyers, and smart platform integration engineers. Secondary validation drew from ENERGY STAR certification records, BIS energy labeling registries, EU F-Gas Regulation implementation reports, and SEC 10-K disclosures from listed manufacturers. Bottom-up unit shipment modeling and top-down value aggregation were cross-checked for consistency.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation by product type, technology tier, end-user category, and distribution channel. CAGRs were derived from trend extrapolation against efficiency standard tightening curves and smart-feature penetration rates. Industry-specific forecast inputs included refrigerant charge size compliance costs and grocery-platform API integration adoption.
Several conditions sit outside the modeled scope, including abrupt refrigerant protocol divergence, trade barrier escalation affecting compressor component flows, and smart-platform data governance framework fragmentation. Forecasts reflect base-case assumptions about MEPS standard harmonization and copper price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dryer Sheets Market
Household Items
Cat Hair Remover Market
Household Items
Insulated Water Bottles Market
Household Items
Insulated Tumblers Market
Household Items
Scouring Pads Market
Household Items
Luxury Massage Chair Market
Household Items
Canada Digital Showers Market
Household Items
Portable Steamers Market
Household Items
Ultrasonic Diffusers Market
Household Items
Europe Cookware Market
Household Items
Smart Faucets Market
Household Items
South Korea Cookware Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Italy Digital Showers Market
Household Items
Replacement Sheets Market
Household Items
Knife Market