
 Party Supplies Market | 2026-2036
Party Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Party Supplies Market Intelligence
Corporate event procurement is unwinding the historical dominance of individual household buyers in party supply channels. Party City Holdco Inc. leverages its vertically integrated manufacturing and retail footprint to control shelf presence across North America. Amscan anchors the wholesale distribution layer through deep relationships with independent party stores and e-commerce platforms. Huhtamaki competes aggressively on sustainable packaging credentials, extending its molded fiber technology into disposable tableware lines.
Party supplies encompass disposable and reusable goods manufactured from paper, plastic, foil, latex, and biodegradable substrates, designed to facilitate decoration, serving, and gifting at social gatherings. Production employs thermoforming, extrusion blowing, and flexographic printing to achieve color consistency, food-contact safety, and batch scalability for seasonal peaks. Decorations and tableware command the largest share of current revenue, while biodegradable materials represent the fastest-growing segment as regulatory pressure and buyer preference shift away from conventional plastics. Event planners and corporations now concentrate margin pools through volume contracts and customized theming services that individual consumers rarely access.
The FDA governs food-contact materials in paper and plastic tableware through 21 CFR standards, while the EPA regulates per- and polyfluoroalkyl substance discharge from coating operations. The EU REACH framework and Single-Use Plastics Directive restrict specific polymer grades and mandate extended producer responsibility schemes across member states. Stakeholders must monitor evolving state-level packaging laws in California, New York, and Washington, where precursor regulations often diffuse nationally through supply chain standardization.
Market Dynamics
Event planners and corporate procurement teams are consolidating purchase volumes into multi-year contracts, compressing margins for traditional retail channels while opening premium service tiers for vendors capable of integrated theming and logistics coordination.
Growth Catalysts
- Molded fiber technology:Huhtamaki and European converters are scaling thermoformed pulp production lines to replace plastic tableware ahead of compliance deadlines.
- EU Single-Use Plastics Directive:Extended producer responsibility schemes across Germany, France, and Italy are accelerating material substitution investments by importers and domestic manufacturers.
- Metropolitan celebration corridors:Demand clusters in California, Texas, and Florida are absorbing specialized inventory for quinceañeras, corporate activations, and sports-related events.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polystyrene resin prices swing with crude oil benchmarks, squeezing margin predictability for disposable tableware producers.
- Latex balloon supply concentration:Malaysia and Thailand host over 80 percent of natural rubber processing capacity, exposing decorators to climate and labor disruption risks.
- Biodegradable certification timelines:ASTM D6400 and EN 13432 testing protocols require 6-12 month validation cycles before products qualify for municipal composting streams.
Strategic Opportunities
- India festive economy:Diwali and wedding season demand remains fragmented among unorganized retailers, creating white space for branded supply chains.
- Reusable silicone tableware:Convergence of food-grade silicone molding and direct-to-consumer subscription models opens recurring revenue channels.
- California SB 54 mandates:Source reduction and recyclability requirements for single-use packaging create first-mover advantages for compliant suppliers.
Industry Challenges
- Flexographic color matching:Seasonal SKU proliferation strains pre-press calibration teams, causing batch rejection rates to spike during Q3 production ramps.
- ERP integration with legacy wholesale systems:Independent party stores operate on 1990s-era inventory platforms that resist API connectivity for real-time replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Party Supplies Market |
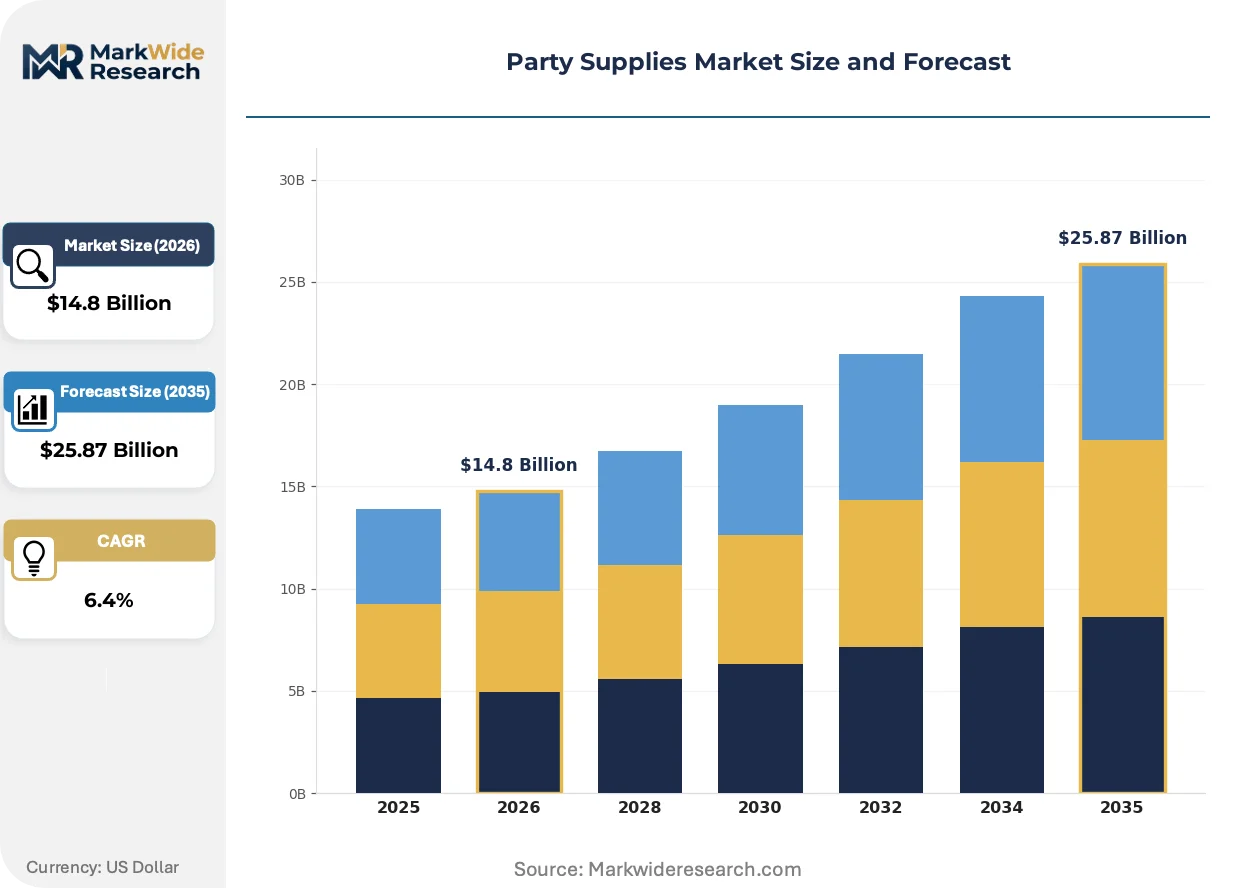
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloons, Tableware, Decorations, Party Favors Event Type: Birthday Parties, Weddings, Corporate Events, Holiday Celebrations Material: Plastic, Paper, Foil, Biodegradable Customer Type: Individuals, Event Planners, Corporations, Schools |
| Companies Covered | Party City Holdco Inc., American Greetings Corporation, Unique Industries Inc., Amscan, Oriental Trading Company, Shutterfly Inc., Huhtamaki, Betallic LLC, Ginger Ray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Party Supplies Market Strategic Shifts & Innovations
Material science breakthroughs and procurement centralization are rewriting competitive rules across decoration, serving, and distribution categories.
Molded fiber tableware is displacing conventional plastic plates and cups in corporate catering channels. Event management companies in the United States and Germany are specifying compostable alternatives for 500-plus attendee functions. The shift compresses pricing power for incumbent thermoformers while rewarding pulp converters with volume commitments and multi-year service contracts.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact coatings are forcing reformulation of grease-resistant paper plates across European supply chains. German converters face the steepest compliance curves due to early national implementation ahead of the 2026 EU harmonization deadline. Decorative foil stamping operations are migrating to PFAS-free barrier coatings, extending product development cycles by 4-8 months.
Corporate event departments are consolidating vendor relationships from fragmented spot purchasing to integrated annual agreements with theming and logistics bundled. Independent party retailers in Texas and Florida are losing share to direct manufacturer relationships as procurement authority migrates to centralized facilities teams. The compression is most visible in Fortune 500 headquarters relocations and pharmaceutical conference circuits.
Party Supplies Market Segmentation
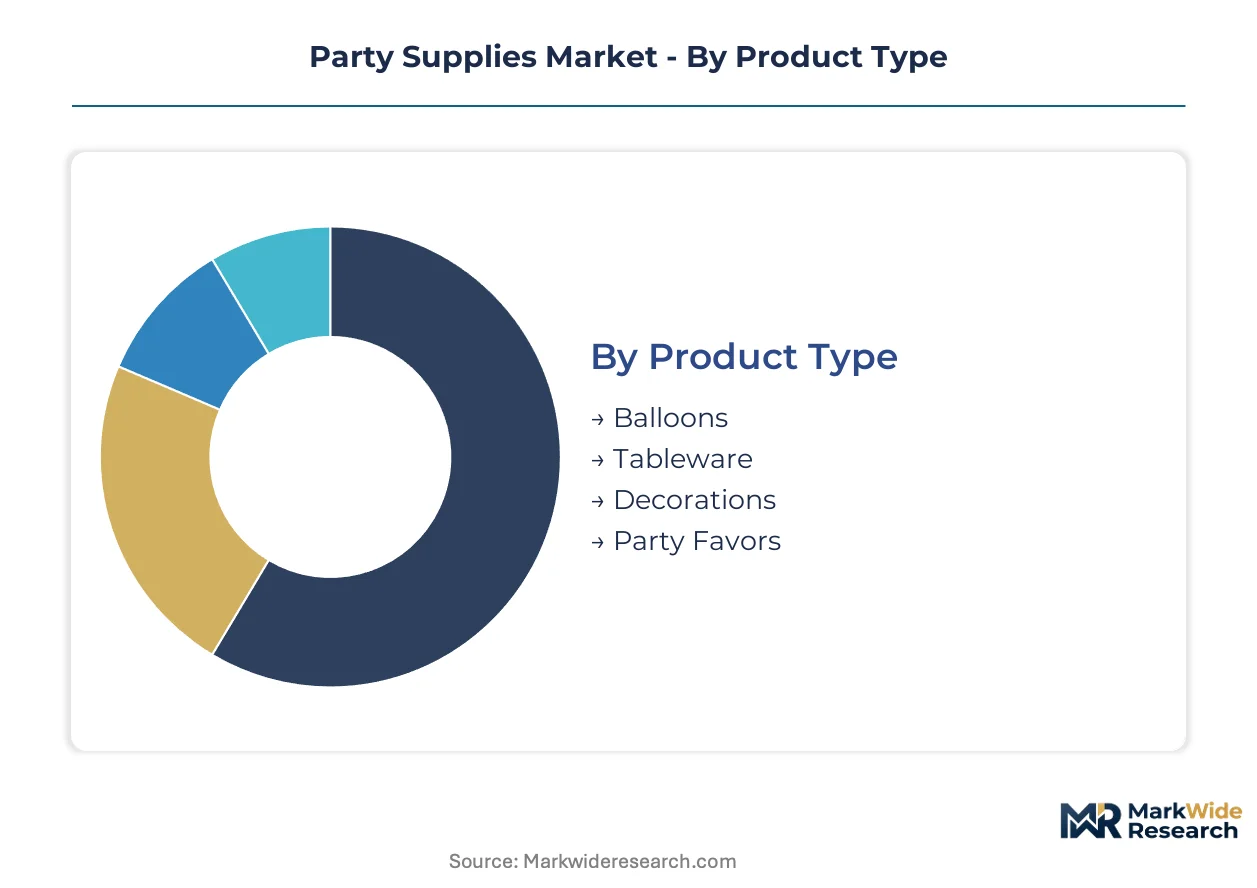
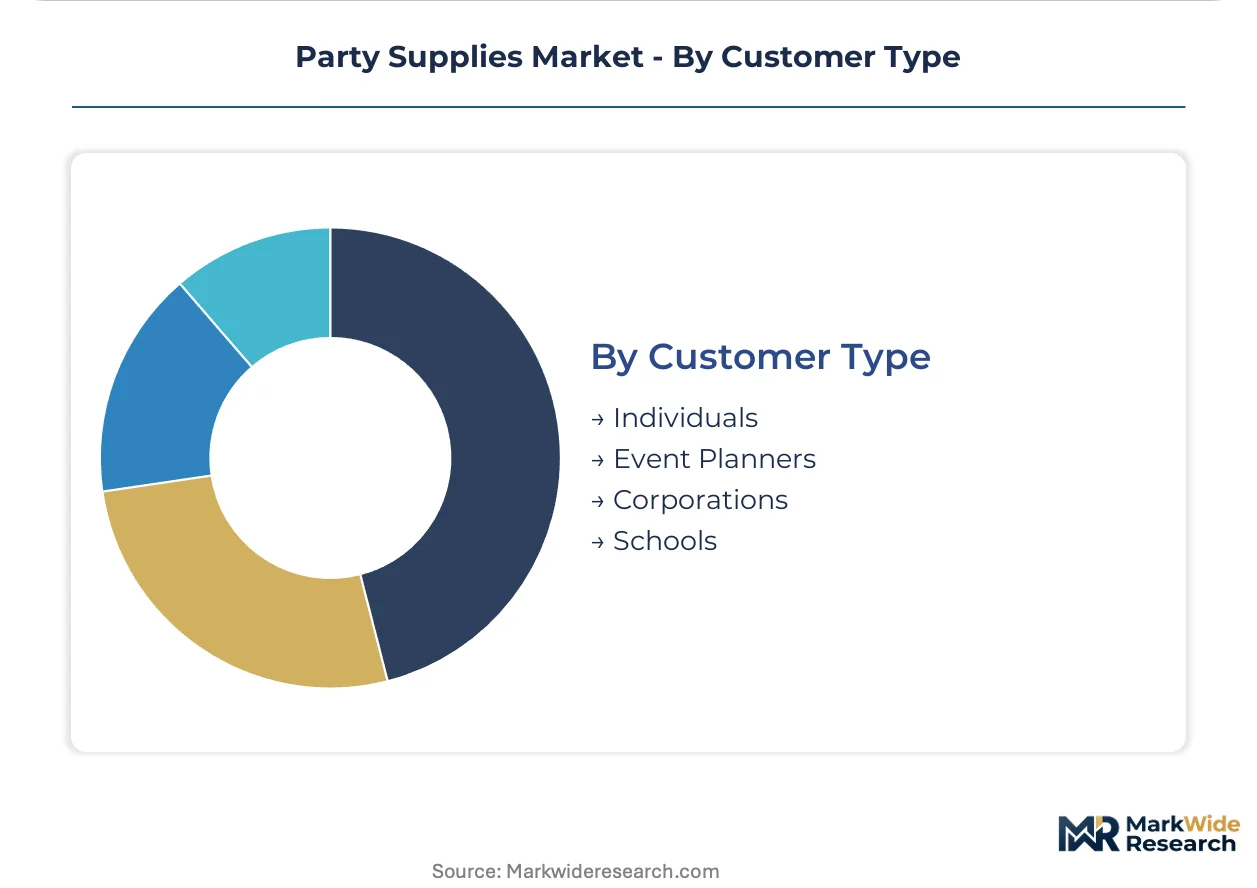
Party supplies segment along four intersecting dimensions that determine pricing power, material substitution risk, and channel strategy. Procurement centralization by event planners and corporations is compressing traditional retail margins while elevating service-intensive segments.
Product Type:
Tableware and decorations face the most acute substitution pressure as molded fiber technology displaces conventional plastics in corporate catering channels.
- Tableware:Comprises disposable plates, cups, cutlery, and serving accessories manufactured through thermoforming, extrusion blowing, or molded fiber processes. Demand concentrates in California, Texas, and Florida metropolitan corridors for quinceañeras and corporate activations, with molded fiber variants capturing volume from polypropylene as FDA food-contact standards tighten.
- Decorations:Includes banners, streamers, centerpieces, and themed backdrops produced via flexographic printing and die-cutting operations. Corporate procurement teams in pharmaceutical and technology sectors are consolidating annual agreements for 500-plus attendee functions, bundling theming services with logistics coordination.
- Balloons:Latex and foil inflatables dependent on natural rubber supply chains concentrated in Malaysia and Thailand. Climate disruption and labor volatility expose decorators to input cost spikes.
- Party Favors:Small gift items and novelty products distributed to event attendees. Schools and individual consumers drive fragmented spot purchasing with minimal contract discipline.
Tableware retains volume leadership; biodegradable material variants hold the steepest expansion curve.
Event Type:
Margin pools concentrate where procurement authority has shifted from fragmented household buying to centralized facilities management.
- Corporate Events:Conferences, product launches, and employee gatherings requiring coordinated theming, catering disposables, and logistics. Fortune 500 headquarters relocations and pharmaceutical conference circuits in California and Texas are absorbing specialized inventory through multi-year vendor agreements.
- Weddings:Premium celebrations demanding customized decoration schemes and elevated tableware specifications. Event planners are capturing margin through design services rather than commodity supply.
- Birthday Parties:Individual and family celebrations historically driving retail channel volume. Party City and independent stores face compression as procurement migrates to direct manufacturer relationships.
- Holiday Celebrations:Seasonal peaks including Halloween, New Year's, and cultural festivals. Flexographic color matching strains pre-press calibration teams during third-quarter production ramps.
Corporate events command premium pricing tiers; birthday parties maintain the broadest addressable base.
Material:
Regulatory pressure from the EU Single-Use Plastics Directive and California SB 54 is accelerating capital reallocation across substrate categories.
- Biodegradable:Molded fiber, bagasse, and certified compostable polymers validated under ASTM D6400 and EN 13432 protocols. Huhtamaki and European converters are scaling thermoformed pulp production lines ahead of compliance deadlines.
- Plastic:Polypropylene and polystyrene resins subject to petrochemical feedstock volatility. Margin predictability erodes with crude oil benchmark swings.
- Paper:Grease-resistant plates and food-contact items facing REACH restrictions on per- and polyfluoroalkyl substances. German converters confront the steepest reformulation curves.
- Foil:Metallic laminates and stamping materials for decorative applications. PFAS-free barrier coating migration extends product development cycles.
Plastic retains installed base dominance; biodegradable substrates are gaining share fastest.
Customer Type:
Procurement consolidation is bifurcating the market between volume-contracted institutional buyers and residual spot purchasers.
- Event Planners:Professional coordinators consolidating purchase volumes into integrated annual agreements with bundled theming and logistics. Independent party retailers in Texas and Florida are losing share to direct manufacturer relationships.
- Corporations:Facilities and procurement departments managing recurring event calendars through centralized vendor management. Multi-year contracts compress margins while opening premium service tiers.
- Individuals:Household consumers purchasing through retail channels for personal celebrations. Historical channel dominance is unwinding as procurement authority migrates.
- Schools:Educational institutions with constrained budgets and fragmented purchasing authority. ERP integration with legacy wholesale systems resists real-time replenishment connectivity.
Event planners capture the most concentrated margin pools; individuals retain the deepest addressable penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply molded fiber tableware and plastic decorations to North American and European distributors, while Malaysian and Thai processors dominate natural rubber balloon exports. Trade corridors concentrate procurement authority in destination markets where event planners and corporate buyers negotiate multi-year contracts.
United States
Corporate event procurement and quinceañera celebrations in California, Texas, and Florida metropolitan corridors absorb specialized inventory through direct manufacturer relationships. The FDA governs food-contact materials in paper and plastic tableware through 21 CFR standards. Houston and Miami logistics hubs route biodegradable tableware imports from Asian suppliers to Fortune 500 headquarters and pharmaceutical conference circuits.
Germany
REACH restrictions on per- and polyfluoroalkyl substances in food-contact coatings force rapid reformulation of grease-resistant paper plates ahead of the 2026 EU harmonization deadline. The EU Single-Use Plastics Directive mandates extended producer responsibility schemes across member states. Bavarian converters face the steepest compliance curves as early national implementation accelerates capital reallocation toward molded fiber production lines.
India
Diwali and wedding season demand remains fragmented among unorganized retailers, creating white space for branded supply chains to consolidate procurement. The Bureau of Indian Standards regulates product safety and quality benchmarks for disposable goods. Maharashtra and Gujarat manufacturing clusters scale thermoformed pulp capacity to serve domestic festive economy buyers and export markets in the Middle East.
Malaysia
Natural rubber processing for latex balloons concentrates in Malaysian and Thai facilities, exposing global decorators to climate disruption and labor volatility risks. The country's national environmental regulator monitors industrial discharge from coating operations. Peninsular Malaysia hosts over 80 percent of regional rubber processing capacity, with Johor and Selangor provinces anchoring balloon manufacturing for European and North American importers.
United Kingdom
Corporate procurement teams in London and the Southeast consolidate annual agreements for 500-plus attendee functions, bundling theming services with logistics coordination. The UK Environment Agency enforces packaging waste regulations aligned with EU extended producer responsibility frameworks. Midlands distribution centers handle seasonal peaks for Halloween and New Year's inventory, routing flexographic-printed decorations to independent party retailers.
Party Supplies Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and distribution reach. The vendor base fragments between vertically integrated retailers, wholesale distributors, and substrate converters, with consolidation pressure mounting as procurement authority migrates to centralized facilities teams. Three archetypes dominate: captive retail-manufacturing hybrids, wholesale distribution anchors, and sustainable packaging specialists. Competitive moves center on backward integration into raw material supply and geographic expansion through direct relationships with event planners.
Within the captive retail-manufacturing tier, Party City Holdco Inc. and Amscan occupy positions that exemplify control over shelf presence and wholesale distribution layers respectively. Huhtamaki represents the sustainable packaging specialist archetype, with its molded fiber technology credentials positioning it for volume commitments from corporate catering channels. These three entities anchor competitive dynamics as procurement centralization compresses margins for traditional retail channels while opening premium service tiers.
| Leading Market Players |
|---|
| Party City Holdco Inc. |
| American Greetings Corporation |
| Unique Industries Inc. |
| Amscan |
| Oriental Trading Company |
| Shutterfly Inc. |
| Huhtamaki |
| Betallic LLC |
| Ginger Ray |
| Others |
Cost & Logistics Intelligence
ASTM D6400 and EN 13432 certification protocols gate both supply qualification and price differentiation simultaneously, separating compostable tableware suppliers into premium tiers while locking uncertified converters out of municipal procurement channels entirely. Corporate event planners in California and Texas now demand validated biodegradability as a threshold condition, compressing margins for legacy plastic thermoformers while elevating pulp converters with multi-year service contracts.
Pricing Analysis
Current-generation molded fiber tableware commands premium positioning against prior-generation polypropylene disposables and next-generation reusable silicone alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from event planners. Cost compression in standard plastic tiers is intensifying because petrochemical feedstock volatility erodes margin predictability. Individual household buyers exhibit highest price sensitivity, while corporate procurement teams absorb premium tiers for compliance and brand positioning.
Supply Chain Analysis
China and Malaysia anchor global production for molded fiber tableware and natural rubber balloons respectively, with German converters supplying specialized grease-resistant paper coatings. Raw material dependencies center on thermoformed pulp feedstock, natural rubber latex, and PFAS-free barrier coatings for food-contact applications. Single-source vulnerability concentrates in Malaysian rubber processing facilities exposed to climate disruption. Distribution runs through Houston and Miami logistics hubs routing Asian imports to Fortune 500 headquarters and pharmaceutical conference circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization by event planners and corporate facilities teams fragments the addressable market into specialized service tiers, creating niches for vendors capable of integrated theming and logistics coordination.
For Market Incumbents: Fortify backward integration into thermoformed pulp production to defend against Huhtamaki's molded fiber expansion, while capturing API connectivity with independent party stores still operating on legacy inventory platforms. Secure multi-year corporate event contracts in California and Texas metropolitan corridors before procurement authority fully consolidates into direct manufacturer relationships. For New Entrants and Emerging Players: Anchor in India's fragmented festive economy, where Diwali and wedding season demand remains dispersed among unorganized retailers with minimal contract discipline. Target branded supply chain consolidation through direct relationships with Maharashtra event planners, leveraging domestic thermoformed pulp capacity scaling in Gujarat manufacturing clusters. For Investors and Strategic Acquirers: California SB 54 implementation reshapes the acquisition landscape toward compliant suppliers with validated composting certifications and established corporate catering relationships. Long-term viability favors substrate converters with in-house molded fiber production and direct event planner channels. Monitor biodegradable certification backlog timelines as the critical inflection signal for capacity-constrained premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Molded Fiber Capacity Expansion | Huhtamaki and European converters scale thermoformed pulp ahead of EU Single-Use Plastics Directive deadlines. |
| Direct-to-Corporate Procurement Relationships | Independent party retailers in Texas lose share as Fortune 500 facilities teams consolidate vendor management. |
| PFAS-Free Coating Reformulation | German converters face steepest compliance curves under REACH restrictions on food-contact barrier technologies. |
| India Festive Economy Brand Buildout | Branded supply chains capture white space from unorganized retailers during Diwali and wedding season peaks. |
| Reusable Silicone Subscription Models | Direct-to-consumer recurring revenue channels converge with food-grade silicone molding technology advances. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with event planners, corporate procurement directors, molded fiber production managers, and independent party store operators; and secondary validation through FDA 21 CFR filings, EPA discharge monitoring reports, EU REACH substance registrations, and trade customs data. Bottom-up triangulation across substrate converter capacity and top-down reconciliation against corporate event spending patterns anchored volume estimates.
Across the analysis window, forecasts modeled product type segmentation including tableware, decorations, balloons, and party favors; material categories spanning biodegradable, plastic, paper, and foil substrates; and customer type bifurcation between centralized institutional buyers and fragmented spot purchasers. CAGRs derived from regression analysis of historical procurement centralization rates and regulatory compliance investment cycles, with specific inputs from seasonal SKU proliferation patterns and flexographic production ramp constraints.
Decision-makers should treat outputs as directional under assumptions of continued EU Single-Use Plastics Directive enforcement and sustained corporate procurement centralization; material deviation in petrochemical feedstock volatility or biodegradable certification timelines would warrant model refresh. Recalibration cycles align with material shifts in regulatory implementation schedules and procurement authority migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Hand Dryer Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Robot Mops Market
Household Items
Europe Cookware Market
Household Items
Knife Set Market
Household Items
United States Commercial Bathroom Products Market
Household Items
MENA POU Water Purifiers Market
Household Items
Toilet Hygiene Products Market
Household Items
Air Care Market
Household Items
US Air Fresheners Market
Household Items
United States Barbeque Grill Market
Household Items
Bottle Openers Market
Household Items
Heated Towel Rail Market
Household Items
South Africa Cookware Market
Household Items
Sleeping Pillow Market
Household Items
Thermos Bottle Market