
 Mouth Spray Market | 2026-2036
Mouth Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Mouth Spray Market Insights
Subscription-based replenishment programs for mouth spray products is broadening recurring revenue streams beyond one-time retail purchases. Johnson & Johnson leverages its pharmacy relationships to secure shelf placement for therapeutic formulations. GlaxoSmithKline plc anchors its position through clinical credibility built on decades of oral health R&D. Colgate-Palmolive Company competes by extending its toothpaste brand equity into spray-format oral care extensions.
Mouth spray is a liquid or aerosolized formulation delivered via mechanical or pressurized actuation, typically containing antimicrobial agents, flavoring compounds, or active pharmaceutical ingredients in concentrations ranging from 0.05% to 2.0% by volume, designed for localized oral cavity application. Its primary commercial purpose spans consumer freshening, therapeutic pain relief, and professional dental hygiene support. The antiseptic product type captures the largest volume share as consumers prioritize germ-killing claims, while the whitening segment commands premium pricing due to peroxide-based formulation costs. Aerosol formulations lead in convenience-driven markets, though liquid pump formats gain traction among sustainability-focused buyers seeking propellant-free alternatives.
The US FDA oversees over-the-counter oral health products through its monograph system, while the EPA regulates volatile organic compounds in aerosol propellants, directly constraining formulation choices for spray manufacturers. The EU MDR and REACH frameworks impose substance disclosure and clinical substantiation requirements that elevate compliance costs for market entry. Stakeholders must monitor evolving propellant regulations and pharmacy reimbursement policies as determinants of which formulation technologies and distribution channels will sustain profitability.
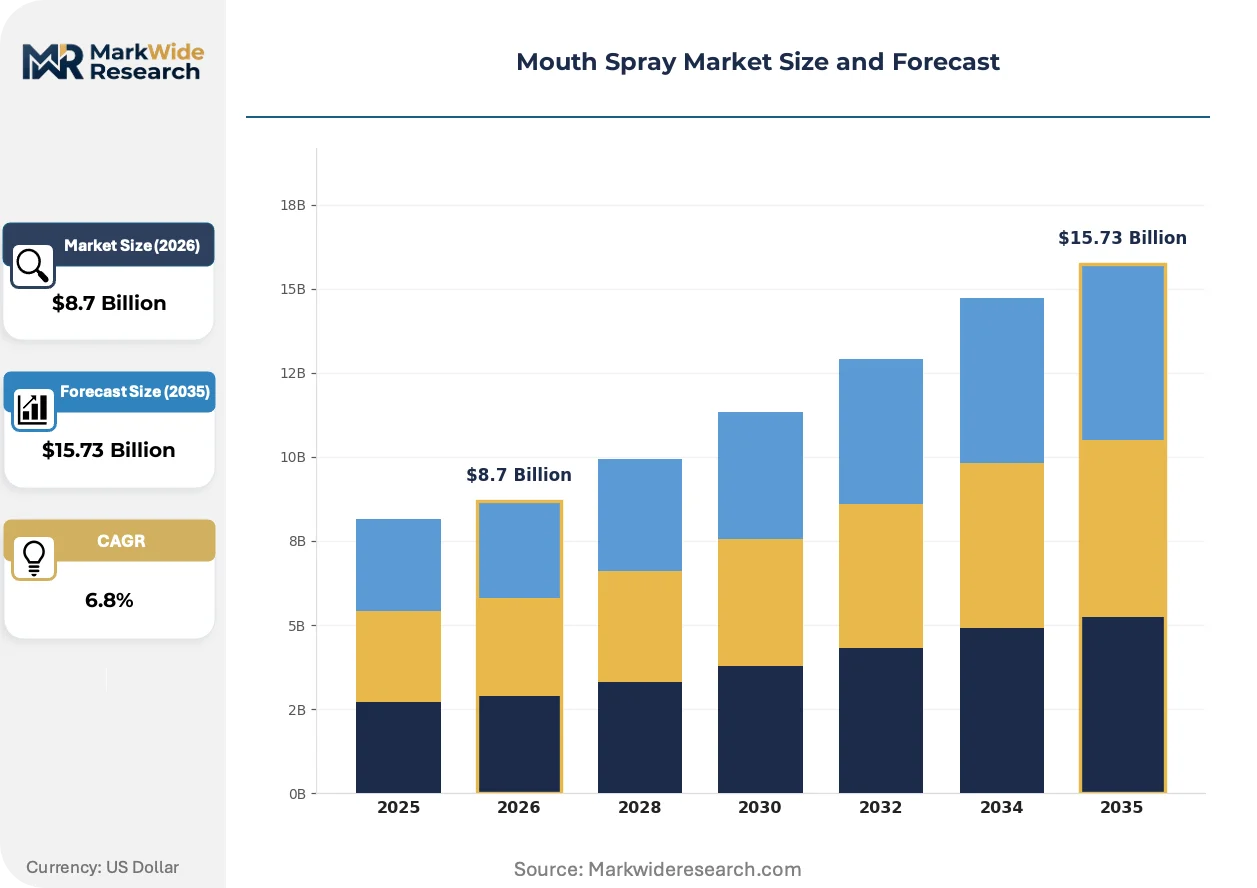
Market Dynamics
The EU Medical Device Regulation reclassification of oral therapeutic sprays is compressing formulation flexibility while elevating clinical substantiation burdens for manufacturers seeking European market access.
Growth Catalysts
- Antiseptic formulation demand:Dental clinics in Germany are expanding procurement of professional-grade mouth sprays for post-procedure patient care, creating institutional volume anchors.
- REACH substance disclosure:The EU framework is forcing competitive transparency on active ingredient sourcing, rewarding early-compliance formulators with pharmacy channel preference.
- Aerosol propellant innovation:Hydrofluorocarbon alternatives are unlocking regulatory continuity for pressurized formats under evolving EPA volatile organic compound rules.
Market Restraints
- Peroxide input volatility:Whitening segment manufacturers face margin compression from hydrogen peroxide supply concentration in Chinese chemical clusters.
- Propellant regulatory friction:The EPA's volatile organic compound limits constrain hydrofluorocarbon selection, forcing costly formulation redevelopment cycles.
- Liquid pump substitution:Sustainability-focused buyers are migrating to mechanical-actuation formats, threatening aerosol infrastructure amortization schedules.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer channels are capturing recurring revenue streams previously locked in pharmacy retail, with Germany showing highest adoption velocity.
- Propellant-free convergence:Mechanical pump technology combined with concentrated active delivery systems is opening premium positioning for sustainability-certified brands.
- MDR clinical data leverage:Therapeutic spray manufacturers with existing European clinical substantiation can extend dossiers into adjacent indications faster than new entrants.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in oral mucosal absorption kinetics is concentrating at mid-sized contract manufacturers, constraining in-house R&D scaling.
- Dual certification timelines:Simultaneous FDA monograph alignment and EU MDR technical documentation is extending market entry cycles for novel active ingredients.
- Legacy aerosol line conversion:Capital requirements for pump-format retooling are deferring sustainability transitions at family-owned European packaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouth Spray Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic, Flavoring, Pain Relief, Whitening Formulation: Aerosol, Liquid, Gel, Foam End User: Consumers, Dental Clinics, Hospitals, Pharmacies Distribution Channel: Online, Retail, Pharmacy, Supermarket |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline plc, Colgate-Palmolive Company, Procter & Gamble, Sunstar Suisse S.A., Lion Corporation, Church & Dwight Co., Inc., Dr. Fresh LLC, Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouth Spray Market Trends and Innovations
Formulation technology and distribution architecture are diverging sharply, with sustainability mandates and clinical credibility requirements pulling the market toward polarized competitive positions.
Mechanical pump actuation systems are overtaking pressurized aerosol formats in sustainability-focused European markets. These propellant-free delivery mechanisms eliminate volatile organic compound exposure while enabling precise dosage control. Pharmacy chains in Germany and Scandinavia are prioritizing shelf placement for pump-format therapeutic sprays. The structural consequence is a bifurcation where convenience-driven Southern European markets retain aerosol preference while Northern markets compress aerosol volume share.
REACH substance disclosure requirements are forcing granular supply chain documentation for all oral care actives. The industrial consequence is elevated compliance costs that disproportionately burden small and mid-sized formulators lacking dedicated regulatory affairs functions. Therapeutic spray categories containing pharmaceutical-grade antimicrobials face the steepest documentation burdens, with German manufacturers responding by consolidating supplier relationships to reduce audit complexity.
Subscription-based replenishment programs are displacing one-time pharmacy purchases among chronic oral condition patients. Direct-to-consumer platforms are capturing patient adherence data that informs formulation refinement, while traditional pharmacy channels lose visibility into consumption patterns. This behavioral shift is most visible in Germany, where pharmacy-led distribution historically dominated but where digital-native competitors are now achieving comparable trust metrics through telehealth integration.
Mouth Spray Market Segmentation
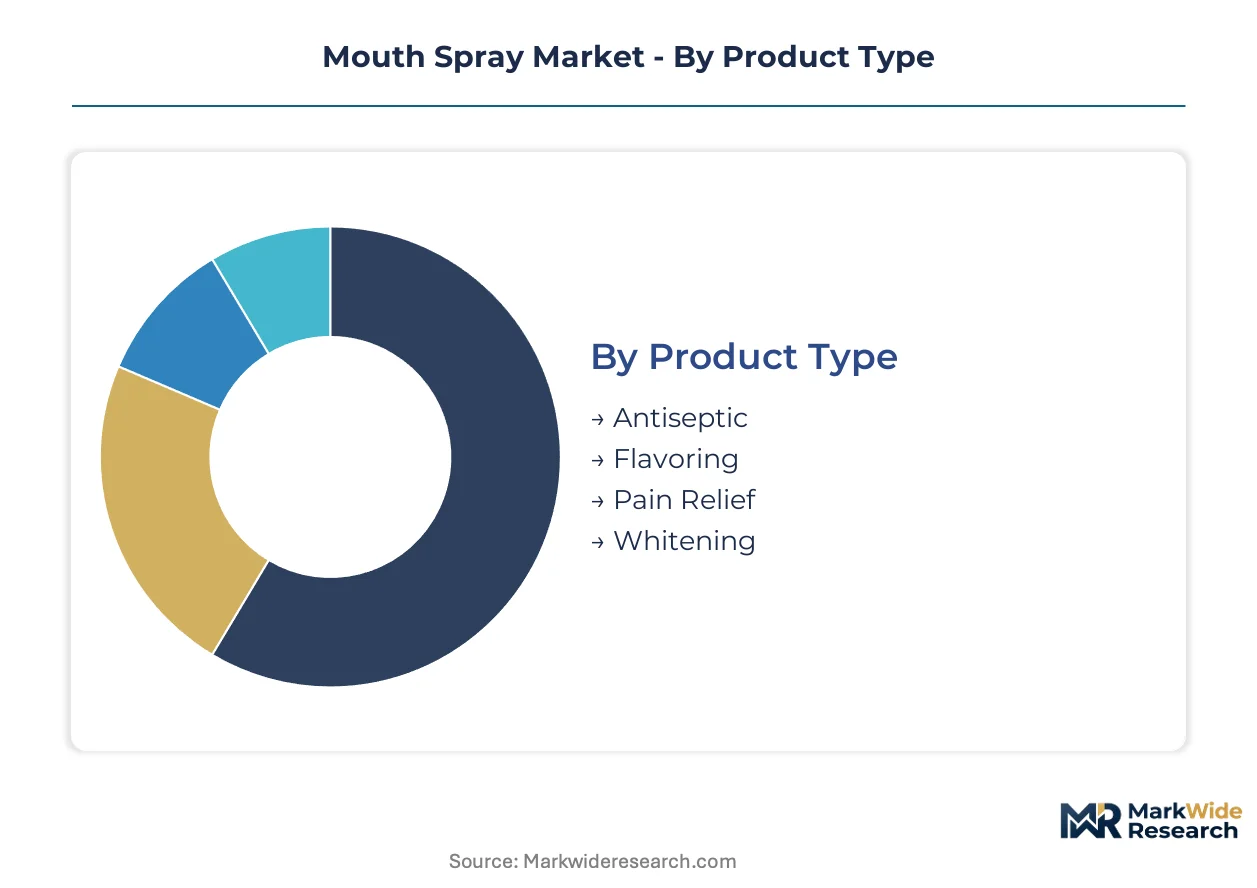
Mouth spray manufacturers navigate divergent margin structures across therapeutic and cosmetic positioning. Formulation choices and channel access determine which segments absorb regulatory compliance costs most efficiently.
Product Type:
Volume concentration sits with germ-killing claims while premium pricing clusters around aesthetic outcomes.
- Antiseptic:Formulations containing chlorhexidine or cetylpyridinium chloride in concentrations from 0.05% to 0.12% dominate institutional procurement. Dental clinics in Germany are expanding post-procedure dispensing programs, anchoring volume demand despite pharmacy reimbursement compression.
- Whitening:Peroxide-based systems at 1.0% to 2.0% hydrogen peroxide concentration command the highest unit economics. Supply volatility from Chinese chemical clusters is forcing manufacturers toward carbamide peroxide alternatives to stabilize input costs.
- Flavoring:Essential oil and synthetic flavorant blends target breath-freshening occasions with lower regulatory burdens.
- Pain Relief:Lidocaine or benzocaine formulations occupy niche therapeutic positioning with FDA monograph constraints.
Today's leader: Antiseptic. Tomorrow's challenger: Whitening.
Formulation:
Delivery mechanism selection increasingly reflects geography-specific sustainability mandates rather than pure performance optimization.
- Aerosol:Pressurized hydrofluorocarbon or dimethyl ether propellant systems deliver fine particle distribution for rapid oral coverage. Southern European markets retain preference for convenience-driven actuation despite Northern European regulatory pressure on volatile organic compound emissions.
- Liquid:Mechanical pump systems eliminate propellant requirements while enabling precise dosage control. Pharmacy chains in Germany and Scandinavia are prioritizing shelf placement for pump-format therapeutic sprays as REACH disclosure requirements intensify.
- Gel:Viscous formulations offer prolonged mucosal contact for therapeutic actives.
- Foam:Aerated liquid systems provide alternative texture positioning with lower packaging complexity.
Aerosol retains volume dominance. Liquid pumps are gaining share fastest in sustainability-certified channels.
End User:
Procurement authority is fragmenting across institutional buyers with divergent specification requirements.
- Dental Clinics:Professional-grade formulations with clinical substantiation documentation are capturing expanding post-procedure care protocols. The EU MDR reclassification is elevating quality thresholds for therapeutic sprays entering European clinical settings.
- Consumers:Direct purchasing for breath-freshening and cosmetic applications concentrates in retail and online channels with price sensitivity driving private-label acceptance.
- Hospitals:Centralized procurement of antiseptic formulations follows infection control committee specifications.
- Pharmacies:Pharmacist-recommended therapeutic positioning maintains strong consumer trust in German-speaking markets.
Dental clinics anchor institutional volume. Direct-to-consumer platforms are disrupting pharmacy channel lock-in.
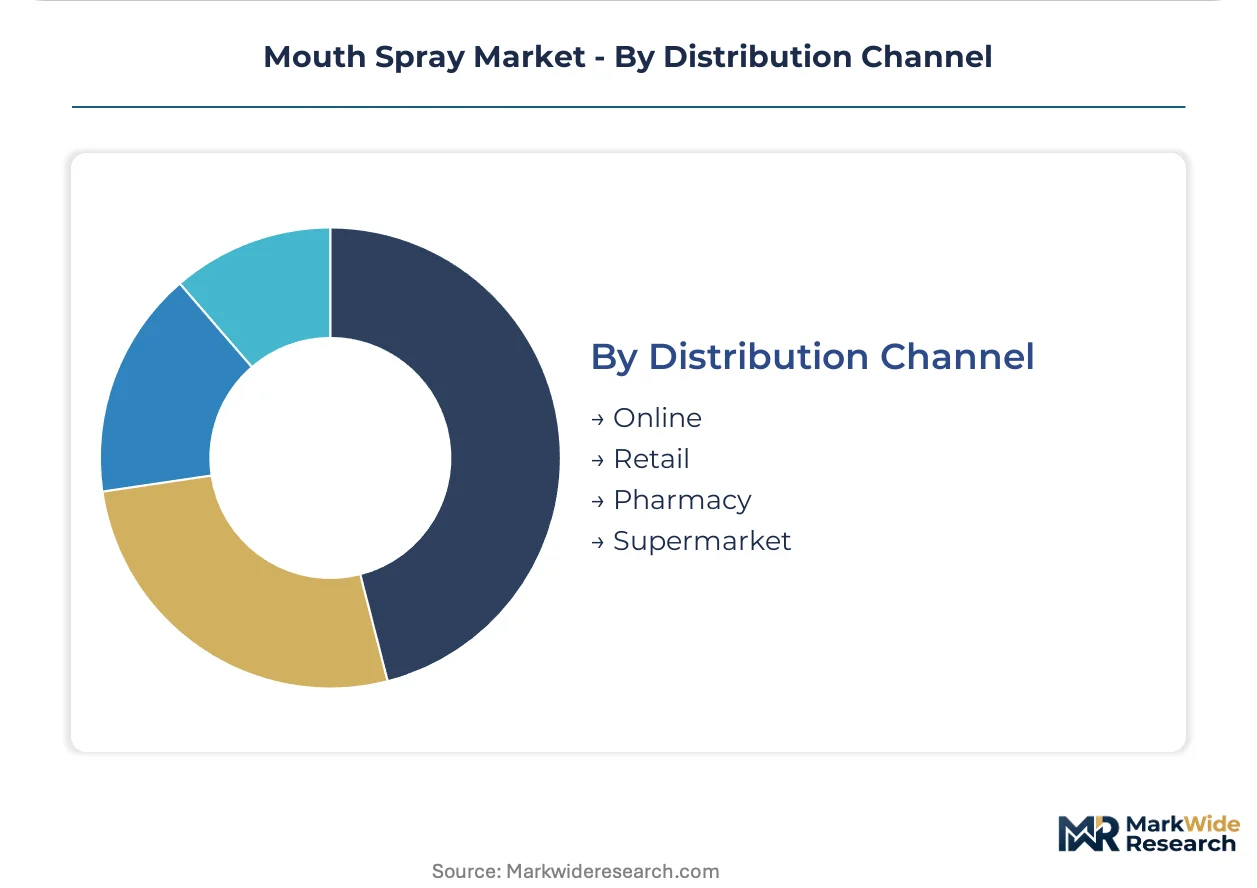
Distribution Channel:
Channel selection determines whether manufacturers capture recurring revenue or remain trapped in transactional retail cycles.
- Pharmacy:Pharmacist consultation and reimbursement eligibility sustain premium positioning for therapeutic formulations. German pharmacy-led distribution channels maintain strong consumer trust in oral care formulations with clinical credibility requirements.
- Online:Subscription-based replenishment programs are displacing one-time purchases among chronic condition patients. Direct-to-consumer platforms capture adherence data that informs formulation refinement while bypassing traditional retail margin structures.
- Retail:Mass merchandisers and convenience stores concentrate volume for flavoring and breath-freshening segments.
- Supermarket:Private-label shelf placement competes on price for basic antiseptic and flavoring formulations.
Pharmacy channels defend margin position. Online subscription models are climbing the fastest in patient adherence applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in channel structure, with pharmacy-led distribution dominating German procurement while direct-to-consumer platforms capture share in American markets. Japan and China present contrasting regulatory pathways for therapeutic formulations. Brazil rounds out the analysis as Latin America's volume anchor.
Germany
Dental clinics in Bavaria and North Rhine-Westphalia are expanding post-procedure dispensing programs for professional-grade antiseptic sprays. The EU Medical Device Regulation reclassification tightens clinical substantiation requirements for therapeutic formulations entering clinical settings. Frankfurt and Hamburg host contract manufacturing clusters where REACH compliance documentation is being centralized to reduce supplier audit complexity.
United States
Subscription-based replenishment programs are displacing pharmacy purchases among chronic oral condition patients in California and New York Metro. The FDA's monograph system governs over-the-counter oral health products while the EPA constrains volatile organic compounds in aerosol propellants. Greater Boston's biotechnology corridor is attracting formulation specialists focused on oral mucosal absorption kinetics.
Japan
Pharmacist-recommended therapeutic positioning maintains strong consumer trust in Tokyo and Osaka metropolitan markets. The Ministry of Health, Labour and Welfare oversees pharmaceutical-grade antimicrobial approvals through PMDA consultation pathways. Kansai region manufacturers are retooling liquid pump lines to meet sustainability certification requirements from domestic pharmacy chains.
China
Private-label breath-freshening segments concentrate volume in Pearl River Delta retail channels. The National Medical Products Administration regulates therapeutic claims while provincial environmental bureaus enforce volatile organic compound limits on aerosol production. Yangtze River Delta chemical clusters supply hydrogen peroxide inputs to whitening formulation manufacturers facing margin compression.
Brazil
Mass merchandisers in São Paulo and Rio de Janeiro drive flavoring and breath-freshening segment volume with price-sensitive private-label acceptance. ANVISA governs pharmaceutical-grade antimicrobial registrations with timelines extending market entry for novel actives. Southeastern manufacturing zones are adapting pump-format packaging lines to serve sustainability-focused export markets.
Mouth Spray Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing portfolios concentrating around oral care heritage brands while institutional procurement favors clinical documentation capabilities. The market structures into three tiers: multinational consumer health divisions with pharmacy network access, mid-sized therapeutic specialists with EU MDR dossiers, and private-label contract manufacturers serving retail price points. Consolidation pressure is mounting as dual certification timelines extend market entry cycles for novel active ingredients.
Within the multinational consumer health tier, Johnson & Johnson and GlaxoSmithKline plc exemplify divergent channel strategies. Johnson & Johnson leverages pharmacy relationships to secure shelf placement for therapeutic formulations, while GlaxoSmithKline plc anchors positioning through decades of oral health R&D credibility. Colgate-Palmolive Company occupies a position extending toothpaste brand equity into spray-format extensions, representing the brand architecture approach to format expansion.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Colgate-Palmolive Company |
| Procter & Gamble |
| Sunstar Suisse S.A. |
| Lion Corporation |
| Church & Dwight Co., Inc. |
| Dr. Fresh LLC |
| Reckitt Benckiser Group plc |
| Others |
Pricing and Supply Chain Analysis
Mechanical pump actuation technology is displacing pressurized aerosol formats across Northern European markets, simultaneously eroding legacy manufacturing asset values while compressing cost structures for propellant-free formulations. This transition concentrates pricing power among contract manufacturers with liquid pump packaging capabilities in Germany and Scandinavia, while forcing Southern European aerosol specialists into defensive cost repositioning.
Pricing Analysis
Capacity additions in Chinese hydrogen peroxide chemical clusters are reshaping price floors for whitening segment manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified therapeutic sprays from cosmetic breath-fresheners and private-label commodity formulations. Price differentiation hinges on clinical substantiation documentation and pharmacy reimbursement eligibility. Cost compression in peroxide inputs is intensifying because supply concentration in Yangtze River Delta producers creates procurement leverage. Dental clinics show least price sensitivity due to institutional procurement protocols, while mass retail consumers in Brazil and China drive hardest bargain.
Supply Chain Analysis
Hydrofluorocarbon propellant supply rests on Japanese and German specialty chemical producers with EPA volatile organic compound constraints tightening availability. Active pharmaceutical ingredient sourcing draws from Indian and Chinese API manufacturers, while mechanical pump components concentrate in German packaging engineering clusters. Single-source vulnerability sits with hydrogen peroxide feedstock from Chinese chemical clusters subject to environmental bureau production curbs. Distribution runs through pharmacy-led channels in Germany and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mouth spray market has entered late-cycle quality phase where therapeutic formulations with EU MDR dossiers command persistent premium over commodity breath-fresheners. Patient adherence data from subscription platforms is redirecting R&D investment toward chronic condition management specifications.
For Market Incumbents: Deploy clinical data leverage from existing EU MDR technical documentation to accelerate adjacent indication approvals faster than new entrants can compile dossiers. Consolidate supplier relationships to reduce REACH audit complexity as substance disclosure requirements intensify. Channel control through pharmacy network access defends margin position against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: EU MDR reclassification in Germany opens a window for propellant-free pump format specialists to capture sustainability-certified pharmacy shelf space. Target Scandinavian markets where mechanical actuation preference runs ahead of Southern Europe. Pursue white-space in carbamide peroxide whitening alternatives to bypass Chinese hydrogen peroxide supply volatility. Go-to-market angle: telehealth integration for chronic oral condition patient adherence.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized contract manufacturers with liquid pump packaging capabilities and existing EU MDR dossiers. Long-term viability favors vertically integrated players controlling both formulation chemistry and mechanical actuation engineering. Acquisition target archetype: German packaging suppliers with retooling capacity for sustainability transitions. Signal to watch: pharmacy reimbursement policy shifts that elevate therapeutic spray eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical substantiation dossiers unlock pharmacy channel access and reimbursement eligibility in Germany. |
| Propellant-Free Manufacturing Transition | Liquid pump retooling aligns with REACH disclosure requirements and Scandinavian sustainability mandates. |
| Subscription Platform Development | Direct-to-consumer adherence data informs formulation refinement while bypassing retail margin structures. |
| Supplier Relationship Consolidation | Reduced audit complexity accelerates compliance velocity under intensifying REACH substance disclosure. |
| Carbamide Peroxide Formulation Pivot | Alternative whitening chemistry stabilizes input costs against Chinese hydrogen peroxide supply concentration. |
Research Methodology
Direct dialogue with formulation chemists, pharmacy procurement managers, dental clinic supply directors, and contract manufacturing executives grounded qualitative insights. Secondary validation drew from FDA monograph filings, EPA volatile organic compound rulemakings, EMA MDR guidance documents, and REACH substance registration databases. Bottom-up segment sizing triangulated against top-down market value estimates from customs trade records and pharmacy sales audits.
Segment-level projections across product type, formulation mechanism, end user category, and distribution channel fed into analytical framework spanning the projection horizon. CAGRs were derived from regression analysis against historical volume trajectories and regulatory event impacts. Forecast inputs incorporated propellant regulatory timelines, pharmacy reimbursement policy shifts, and mechanical pump technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA propellant rule changes or EU MDR enforcement intensity variations. Assumptions reflect documented regulatory pathways and channel migration patterns. A small set of named triggers warrants ongoing watch: hydrogen peroxide supply disruptions, MDR clinical data requirements expansion, and subscription platform patient adherence metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
China Oral Care Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Adult Oral Care Products Market
Oral Care
BRICS Oral Care Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Children's Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Hygiene Products Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Xerostomia Treatment Market
Oral Care
Oral Antiseptics Market
Oral Care
Halitosis Treatment Market
Oral Care
Dry Mouth Relief Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Kids Toothpaste Market