
 Germany Smart Home Market | 2026-2036
Germany Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Smart Home Market Insights
Capital-intensity divergence between integrated hardware manufacturers and software-centric platforms is reorganizing competitive dynamics in the Germany Smart Home Market. Siemens AG leverages its industrial automation heritage to dominate building management system integration. Robert Bosch anchors its position through captive semiconductor and sensor production. Amazon.com Inc. competes via voice-interface ecosystem lock-in and Prime-channel distribution density.
Germany Smart Home denotes residential and commercial building environments where interconnected devices automate climate control, security, lighting, and appliance management through centralized or distributed intelligence architectures. Systems typically rely on mesh-network protocols with sub-50ms latency requirements and AES-128 encryption minimums to ensure real-time responsiveness and data integrity across heterogeneous device fleets. Smart Security Systems command premium pricing due to insurance-linked installation mandates and GDPR-driven data sovereignty requirements. Smart Thermostats represent the fastest-expanding product category as the Building Energy Act (GEG) compels heating system modernization. Wi-Fi and Zigbee protocols split the connectivity layer, with Zigbee gaining ground in retrofit scenarios where mesh resilience outweighs bandwidth demands.
The Federal Network Agency (Bundesnetzagentur) enforces cybersecurity certification under the IT Security Act, while the KfW development bank ties renovation subsidies to connected building technology compliance. VDE certification and CE marking under the EU Radio Equipment Directive further constrain market access for non-compliant hardware imports. Stakeholders must monitor whether the EU Cyber Resilience Act extends mandatory vulnerability disclosure to smart home firmware, reshaping product lifecycle obligations and aftermarket service economics.
Market Dynamics
The Building Energy Act (GEG) is compressing replacement cycles for heating infrastructure, forcing landlords and homeowners to choose between connected thermostats and penalty-bearing non-compliance. This regulatory pressure is restructuring procurement priorities across the retrofit-dominant German housing stock.
Growth Catalysts
- EU Green Deal efficiency mandates:National transposition requires multi-family housing complexes to install connected heating controls, creating mandatory replacement demand that bypasses consumer preference cycles.
- Zigbee mesh protocol resilience:Retrofit installers favor this standard in aging buildings where Wi-Fi penetration fails, expanding addressable housing stock beyond new construction.
- North Rhine-Westphalia urban density:Concentrated rental housing in Cologne, Düsseldorf, and Essen generates cluster economies for installer networks and bulk procurement.
Market Restraints
- GDPR data sovereignty compliance costs:Local server requirements and encryption standards inflate hardware BOM costs versus non-EU competitors.
- Semiconductor supply concentration in East Asia:Sensor and microcontroller lead times remain volatile, constraining production planning for German OEMs.
- Copper and rare earth input volatility:Motor drives and antenna components face commodity price swings that compress margin buffers on mid-tier products.
Strategic Opportunities
- Baden-Württemberg premium housing stock:Stuttgart and Karlsruhe owner-occupied segments show underpenetration for whole-home automation versus Berlin and Munich saturation.
- KfW renovation subsidy linkage:Connected building technology compliance unlocks preferential financing rates, creating a channel incentive for integrated system sales.
- Matter protocol convergence with energy management:Unified interoperability standards reduce integration friction, enabling cross-brand ecosystem plays previously blocked by proprietary lock-in.
Industry Challenges
- Cybersecurity firmware lifecycle obligations:The IT Security Act requires multi-year vulnerability patching commitments that strain aftermarket service economics for hardware-centric vendors.
- Installer certification bottlenecks:VDE and KNX partner program capacity constraints limit trained deployment workforce, throttling retrofit velocity in peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Smart Home Market |
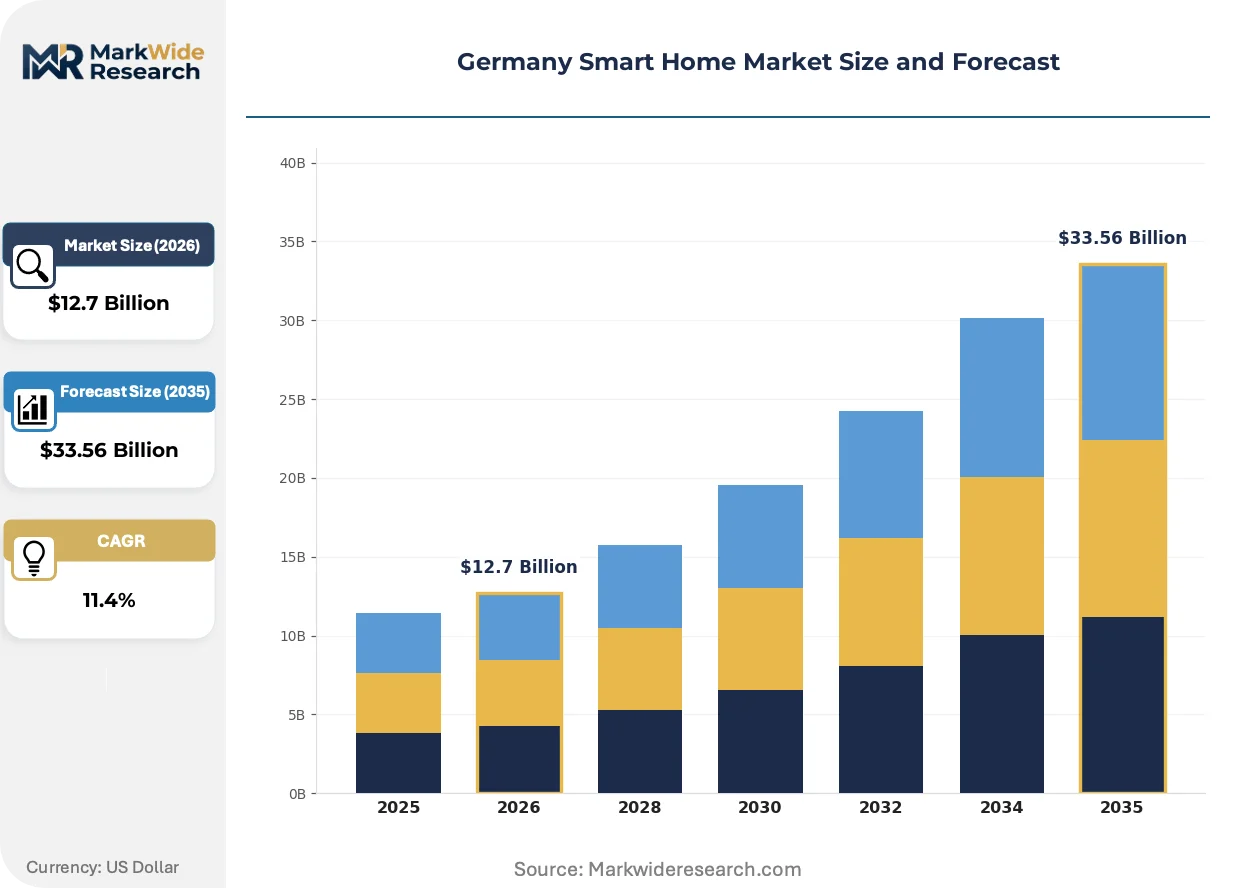
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security Systems, Smart Thermostats, Smart Appliances Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave End User: Residential, Small Enterprises, Large Enterprises, Installers Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Schneider Electric, Honeywell International Inc., Siemens AG, Robert Bosch, Google LLC, Amazon.com Inc., Apple Inc., ABB, BSH Hausgeräte, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Smart Home Market Trends and Innovations
Protocol unification and regulatory telemetry requirements are converging to reshape product architecture priorities. Vendors must now engineer for compliance data streams and cross-brand interoperability simultaneously.
Matter-over-Thread is supplanting proprietary Zigbee implementations as the default stack for new device introductions. Premium thermostat and lighting OEMs are adopting this standard to reduce SKU fragmentation across export markets. The structural consequence is compressing R&D overhead for multi-protocol support while accelerating ecosystem consolidation around Apple, Google, and Samsung hubs.
The EU Cyber Resilience Act is mandating vulnerability disclosure timelines and automatic update capabilities for radio equipment. Hardware vendors must restructure firmware development workflows to accommodate sustained security patching obligations. Smart security systems face the steepest compliance burden, as insurance-linked installation mandates already require documented maintenance records.
Property management procurement is consolidating around integrated service contracts that bundle hardware, installation, and cloud subscription into single-line expenses. Mid-size housing cooperatives in Bavaria are displacing transactional equipment purchases with multi-year operational agreements. This shift is most visible in Munich's rental market, where professionalized landlord entities now specify outcome-based climate control guarantees rather than device specifications.
Germany Smart Home Market Segmentation
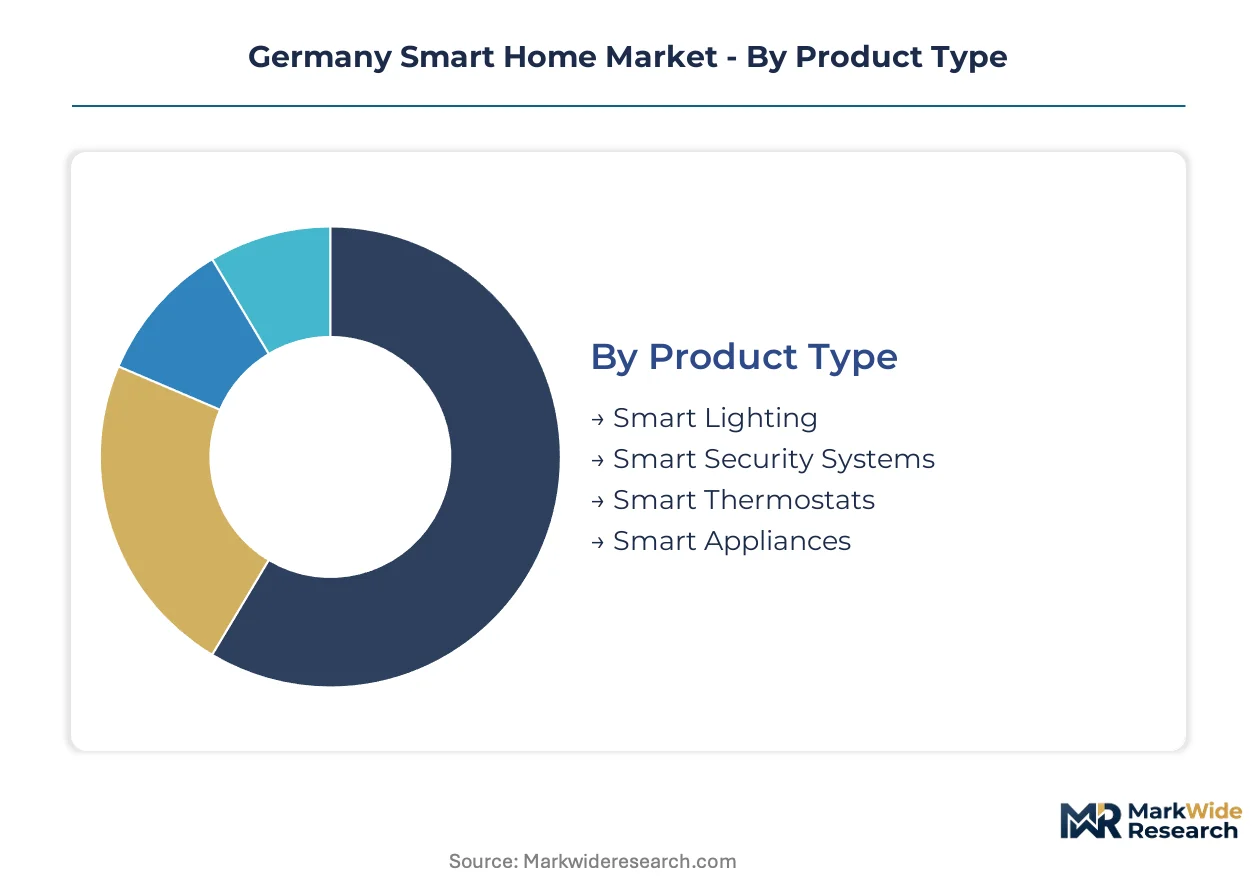
Segmentation in the Germany Smart Home Market reveals how regulatory mandates reshape channel economics. The Building Energy Act forces product-specific procurement patterns, while installer certification bottlenecks concentrate volume in select distribution pathways.
Product Type:
Channel mix varies sharply across product categories, with insurance-mandated security systems flowing through certified installer networks while thermostats penetrate via subsidized retrofit programs.
- Smart Security Systems:Insurance-linked installation mandates under German liability frameworks require professional deployment with documented maintenance records. Demand concentrates in North Rhine-Westphalia rental housing complexes where landlord liability exposure drives specification. GDPR data sovereignty requirements inflate hardware BOM costs versus non-EU alternatives.
- Smart Thermostats:Mesh-network enabled devices with sub-50ms latency requirements automate climate control through centralized intelligence architectures. Bavarian and Baden-Württemberg multi-family housing complexes generate cluster economies as the GEG compels heating modernization. KfW subsidy linkage creates preferential financing channels for integrated system sales.
- Smart Lighting:Connected fixtures with AES-128 encryption minimums deploy through both retrofit installer networks and consumer retail channels.
- Smart Appliances:Refrigerators, washing machines, and ovens with embedded connectivity rely on Wi-Fi and Matter-over-Thread protocols for cross-brand interoperability.
By volume, Smart Thermostats leads. By growth pace, Smart Security Systems is ahead.
Technology:
Cost tier stratification separates premium protocol stacks from economy implementations, with Zigbee mesh resilience commanding installer premiums in aging building stock.
- Zigbee:Mesh-network protocol with self-healing topology dominates retrofit scenarios where building penetration challenges defeat Wi-Fi. North Rhine-Westphalia installer networks favor this standard for multi-family housing deployments. The Matter protocol convergence is supplanting proprietary implementations.
- Wi-Fi:High-bandwidth connectivity supports video streaming and cloud-dependent applications in owner-occupied premium housing. Stuttgart and Karlsruhe segments show underpenetration versus Berlin saturation. Latency requirements under 50ms strain router infrastructure in dense urban deployments.
- Bluetooth:Low-energy protocol enables direct smartphone pairing for point solutions without hub dependency.
- Z-Wave:Sub-GHz frequency band penetrates building materials more effectively than 2.4 GHz alternatives in concrete-heavy construction.
By installed base, Wi-Fi dominates. By retrofit momentum, Zigbee is expanding most quickly.
End User:
Customer type determines procurement modality, with residential retrofit displacing transactional purchases through multi-year operational agreements in professionalized landlord entities.
- Residential:Homeowners and tenants in urban centers across North Rhine-Westphalia, Bavaria, and Baden-Württemberg drive replacement demand. Munich rental market professionalization specifies outcome-based climate guarantees rather than device specifications. KfW renovation subsidies unlock preferential financing for connected building technology compliance.
- Installers:VDE and KNX partner program certified technicians constitute a bottlenecked deployment workforce. Peak demand windows in Q4 heating season strain capacity. Training program expansion lags retrofit velocity requirements.
- Small Enterprises:Retail storefronts and office clusters adopt entry-level security and lighting automation through distributor channels.
- Large Enterprises:Corporate campuses integrate building management systems with industrial automation heritage platforms.
By unit volume, Residential leads. By contract value concentration, Large Enterprises is climbing the fastest.
Distribution Channel:
Supply concentration in East Asian semiconductor inputs shapes margin structure across channel tiers, with direct sales capturing premium integration services.
- Direct Sales:Integrated service contracts bundle hardware, installation, and cloud subscription into single-line expenses for property management procurement. Mid-size Bavarian housing cooperatives displace transactional equipment purchases with multi-year operational agreements. Outcome-based climate control guarantees replace device specifications in Munich.
- Distributors:Regional wholesalers aggregate demand from installer networks facing VDE certification bottlenecks. Inventory carrying costs reflect volatile copper and rare earth input pricing. Lead time volatility from East Asian sensor suppliers constrains production planning.
- Online Retail:Amazon Prime-channel density competes via voice-interface ecosystem lock-in for consumer-direct thermostat and lighting sales.
- Offline Retail:Specialist electronics retailers serve do-it-yourself segments with plug-and-play security cameras and smart speakers.
By transaction count, Online Retail leads. By contract value growth, Direct Sales shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's smart home market exhibits a net import dependency for semiconductor components, with domestic production concentrated in industrial automation and building management systems. Regional demand patterns cluster around urban rental markets and owner-occupied premium housing segments.
North Rhine-Westphalia
Multi-family housing complexes in Cologne, Düsseldorf, and Essen generate dense retrofit demand as the Building Energy Act compels heating modernization. The KfW development bank channels renovation subsidies through regional lender networks, accelerating connected thermostat deployment. Installer certification bottlenecks concentrate volume in established VDE partner programs across the Ruhr metropolitan corridor.
Bavaria
Munich's professionalized landlord entities specify outcome-based climate control guarantees rather than device specifications, displacing transactional equipment purchases. The state's housing cooperatives pioneer integrated service contracts bundling hardware, installation, and cloud subscription. Matter protocol adoption accelerates in Nuremberg and Augsburg as export-oriented OEMs reduce SKU fragmentation.
Baden-Württemberg
Stuttgart and Karlsruhe owner-occupied segments show underpenetration for whole-home automation versus Berlin and Munich saturation, creating whitespace for premium system vendors. The state's industrial automation heritage feeds building management integration capabilities. Cybersecurity certification requirements under the IT Security Act favor domestic firmware development workflows.
Berlin-Brandenburg
Capital region rental density drives insurance-mandated smart security system penetration in professionalized housing portfolios. GDPR data sovereignty requirements inflate hardware BOM costs for cloud-dependent applications. The Federal Network Agency's enforcement headquarters shapes national compliance interpretation for connected building technology.
Lower Saxony
Hanover's mid-size property management sector adopts Zigbee mesh implementations where aging building stock defeats Wi-Fi penetration. Regional distributor networks aggregate demand from installer networks facing peak-season capacity constraints. Copper and rare earth input volatility compresses margin buffers on motor drive components sourced through Hamburg port logistics.
Germany Smart Home Market Competitive Landscape
Concentration sits with industrial automation conglomerates and voice-interface ecosystem platforms. The market structure tiers between integrated hardware manufacturers with captive semiconductor production and software-centric platforms competing through distribution density. Three archetypes dominate: building management system integrators leveraging industrial heritage, consumer electronics platforms with voice-interface lock-in, and captive-component producers controlling sensor supply chains. M&A activity targets cybersecurity certification capabilities, while strategic partnerships focus on Matter protocol convergence.
Among Germany-based industrial conglomerates, Siemens AG and Robert Bosch occupy positions exemplifying building management integration and captive sensor production respectively. Amazon.com Inc. represents voice-interface ecosystem competition through Prime-channel density. These three anchors illustrate how capital-intensity divergence between hardware manufacturing and platform economics reorganizes procurement channel access.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International Inc. |
| Siemens AG |
| Robert Bosch |
| Google LLC |
| Amazon.com Inc. |
| Apple Inc. |
| ABB |
| BSH Hausgeräte |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts bundling hardware, installation, and cloud subscription lock in supply access for property management procurement while compressing price visibility across the German retrofit channel. The KfW subsidy linkage creates preferential financing tiers that separate integrated system vendors from transactional equipment sellers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Germany Smart Home Market. Premium tiers capture VDE-certified installers serving insurance-mandated security deployments, while economy tiers serve do-it-yourself retail channels with stripped-down feature sets. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the mid-tier is intensifying because semiconductor supply volatility forces inventory carrying cost absorption. Housing cooperatives show lowest price sensitivity due to KfW-subsidized financing, while individual homeowners in offline retail channels exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for sensors and microcontrollers remain volatile, constraining production planning for German OEMs dependent on East Asian inputs. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with rare earth processing anchored in China. Raw material dependencies include copper for motor drives, neodymium for antenna components, and silicon carbide for power management chips. Single-source vulnerability in advanced node semiconductor supply creates exposure to geopolitical disruption. Distribution runs through regional VDE-certified installer networks and Amazon Prime-channel density for consumer-direct segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol convergence is compressing ecosystem fragmentation into platform-economics consolidation, rewarding vendors with hub-integration capabilities and punishing proprietary lock-in strategies.
For Market Incumbents: Secure firmware development workflows capable of sustained security patching under the EU Cyber Resilience Act's vulnerability disclosure mandates. Deepen backward integration into captive sensor production to offset East Asian supply concentration. Defend against voice-interface ecosystem lock-in by Amazon through Matter-over-Thread certification investments that preserve cross-brand interoperability. For New Entrants and Emerging Players: Anchor in Baden-Württemberg's underpenetrated owner-occupied premium housing stock, where Stuttgart and Karlsruhe segments lag Berlin and Munich saturation. Target mid-size Bavarian housing cooperatives displacing transactional purchases with multi-year operational agreements. Pursue KfW renovation subsidy linkage as the primary go-to-market angle, unlocking preferential financing channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service contract providers bundling hardware, installation, and cloud subscription into single-line expenses. Long-term viability favors vendors with cybersecurity certification capabilities and Matter protocol compliance across the projection horizon. Acquisition targets should demonstrate VDE partner program certification and established installer network relationships. Watch for EU Cyber Resilience Act enforcement timelines as the signal indicating firmware lifecycle obligation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Reduces SKU fragmentation for export-oriented OEMs competing across European markets. |
| Cybersecurity Capability Acquisition | Addresses IT Security Act compliance burdens and insurance-linked installation mandates. |
| Installer Network Expansion | Resolves VDE and KNX partner program bottlenecks throttling retrofit velocity. |
| KfW Subsidy Channel Integration | Captures preferential financing flows tied to connected building technology compliance. |
| Captive Sensor Production | Mitigates East Asian semiconductor supply volatility affecting German OEM planning. |
Research Methodology
Cross-validation between primary interviews with VDE-certified installers, property management procurement officers, KfW program administrators, and smart home OEM product managers anchors the qualitative findings. Secondary validation draws from Federal Network Agency enforcement disclosures, KfW subsidy allocation databases, EU Cyber Resilience Act draft texts, and trade customs records for semiconductor imports. Bottom-up triangulation across installer network capacity constraints and top-down validation against housing stock modernization mandates ensure methodological rigor.
Sensitivity analysis across regulatory enforcement intensity, subsidy allocation trajectories, and protocol adoption curves shapes the analytical framework. Segmentation dimensions modeled include product type, connectivity protocol, end-user archetype, and regional housing stock characteristics. CAGRs derive from replacement cycle compression under the Building Energy Act and retrofit penetration rates across North Rhine-Westphalia, Bavaria, and Baden-Württemberg urban clusters. Forecast inputs incorporate installer certification bottleneck resolution timelines and Matter protocol device introduction schedules.
Decision-makers should treat outputs as directional under sustained GEG enforcement and KfW subsidy continuity assumptions; material deviation in regulatory timelines or semiconductor supply normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Global Bio-Based Chemicals Market
Others
Hookah Tobacco Market
Others
Snus Market
Others
AI In Government And Public Services Market
Others
Mobile Computer Market
Others
North America Machine Vision Systems Market
Others
Mainframe Market
Others
Global Smartphone ODM Market
Others
North America Healthcare Flexible Packaging Market
Others
Japan Automotive LED Lighting Market
Others
Manometers Market
Others
High Frequency Vibrator Market
Others
South America Orange Market
Others
Agitator Bead Mill Market
Others
Voice Controlled Devices Market