
 Product Design and Development Services Market | 2026-2036
Product Design and Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
Product Design and Development Services Market Intelligence
Shenzhen is narrowing the gap between concept design and mass manufacturing through integrated prototyping corridors that compress iteration cycles. IDEO leverages its human-centered methodology to anchor premium engagements in consumer electronics and healthcare hardware. Jabil Inc. sustains large-scale industrial design capacity across multiple continents, competing on manufacturing adjacency rather than pure creative output. Frog Design differentiates through embedded software-hardware integration capabilities that address connected product architectures.
Product design and development services encompass the systematic translation of functional requirements into manufacturable specifications through iterative modeling, material selection, and usability validation against defined performance thresholds. These services bridge engineering feasibility with commercial viability, typically delivering CAD-ready geometries, physical prototypes, and design-for-manufacturing guidance to reduce downstream tooling costs. User experience design captures expanding margin pools as digital interfaces become inseparable from physical product value, while prototyping services face commoditization pressure from desktop manufacturing tools. Industrial design retains premium positioning where aesthetic differentiation drives consumer preference, particularly in furniture and medical devices where regulatory documentation requirements elevate service complexity.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements compel medical device manufacturers to engage design partners with validated risk management processes, reshaping vendor qualification criteria. China's GB standards administered by SAMR and Japan's METI industrial design promotion frameworks create divergent compliance pathways that favor regionally rooted service providers. Stakeholders must evaluate whether captive design studios or external specialist networks offer superior adaptability as product lifecycles compress and regulatory fragmentation deepens across target markets.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating platform development by externalizing design functions to specialized studios, compressing traditional in-house cycles while navigating fragmented regulatory requirements across target markets.
Growth Catalysts
- EU MDR technical documentation mandates:Medical device manufacturers require embedded compliance expertise, elevating demand for design partners with validated risk management processes and regulatory documentation capabilities.
- Shenzhen-Shanghai electronics clusters:Integrated prototyping corridors in China's industrial hubs compress iteration cycles between concept design and mass manufacturing, attracting hardware-intensive engagements.
- Electric vehicle platform architectures:Automotive electrification requires simultaneous hardware-software co-design, pulling specialized studios into long-term development partnerships with tier-one suppliers.
Market Restraints
- Desktop manufacturing commoditization:Affordable 3D printing and CNC routing tools enable in-house prototyping, eroding margins on basic physical modeling services.
- Regulatory fragmentation across FDA, EU MDR, and SAMR:Divergent compliance pathways force design firms to maintain multiple certification tracks, inflating overhead without proportional fee recovery.
- Specialized talent scarcity:Shortage of industrial designers with simultaneous expertise in GB standards and connected product architectures limits scalable delivery.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentive-driven production shifts create demand for design-for-manufacturing services among contract manufacturers establishing local capacity.
- Digital-physical convergence in medical devices:Wearable diagnostics and remote monitoring hardware require UX-hardware integration capabilities that pure engineering firms cannot supply.
- Carbon accounting integration:EU CSRD disclosure requirements push industrial clients toward design partners with lifecycle assessment tooling and material traceability systems.
Industry Challenges
- ISO 13485 certification timelines:Medical device design engagements face 12-18 month qualification delays before revenue recognition, straining cash flow for mid-cap studios.
- Legacy CAD system integration:Enterprise clients maintain proprietary data environments, forcing design partners to absorb software licensing costs and interoperability engineering.
- IP contamination risk in co-development:Shared invention frameworks between clients and studios generate complex ownership disputes that delay project closeouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Design and Development Services Market |
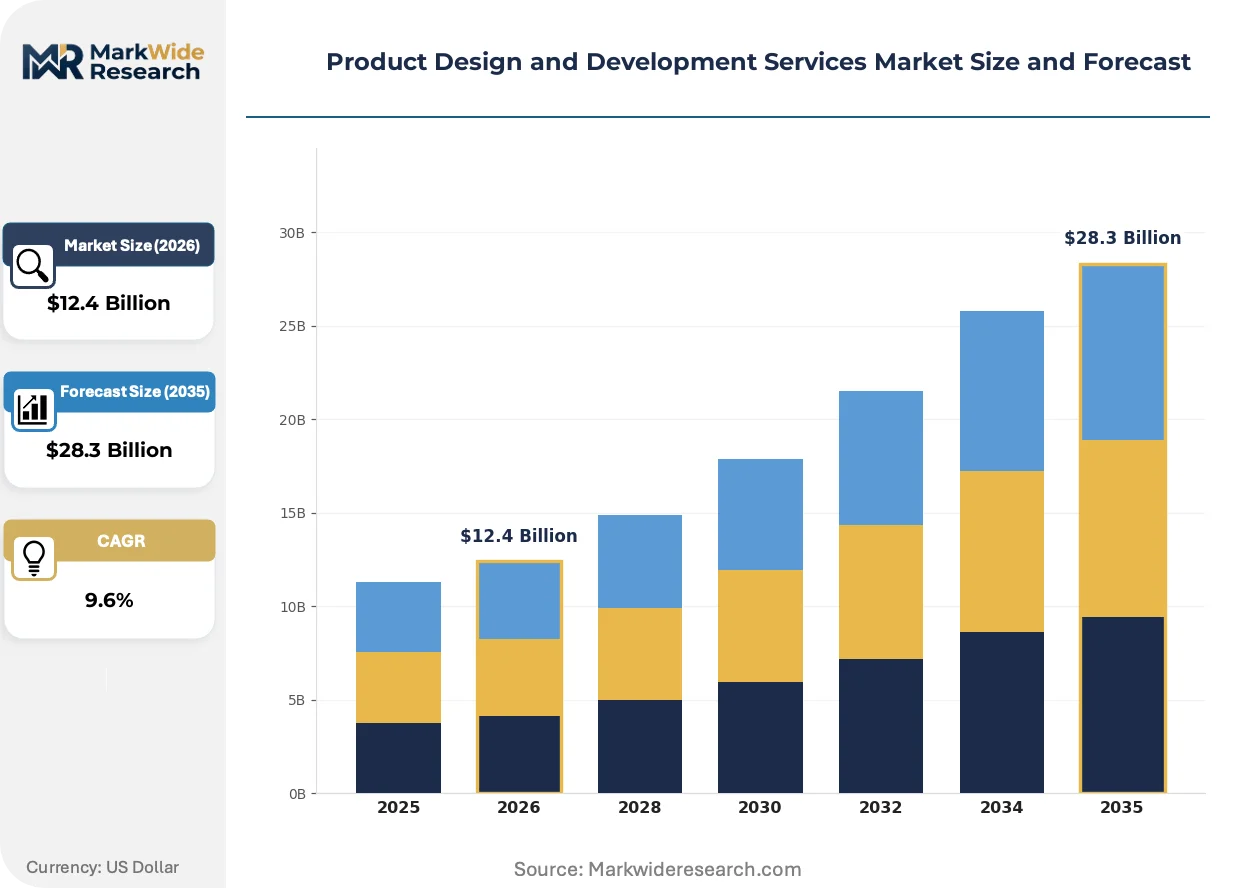
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.3 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Concept Design, Prototyping, User Experience Design, Industrial Design Technology: 3D Modeling, CAD Software, Virtual Reality, Simulation Tools End User: Consumer Electronics, Automotive, Furniture, Medical Devices Application: Product Development, Market Research, Design Consulting, Quality Assurance |
| Companies Covered | IDEO, Frog Design, R/GA, Ziba Design, Designit, PDD Group, Lunar, Smart Design, Jabil Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Design and Development Services Market Strategic Shifts & Innovations
Generative design algorithms and real-time rendering engines are compressing the concept-to-prototype pipeline, forcing traditional studios to differentiate through regulatory expertise rather than pure visualization speed.
AI-assisted topology optimization is rendering obsolete manual iterative refinement in structural component design. Automotive seating and medical implant manufacturers in Germany and Japan now deploy generative algorithms that explore thousands of load-bearing geometries in hours. This capability is rendering obsolete the premium positioning of studios that previously competed on iterative speed alone.
FDA 21 CFR Part 820 quality system regulations now require digital thread documentation from initial requirements through design verification. Medical device submissions demand immutable audit trails that connect every design decision to risk analysis outputs. FDA investigators are scrutinizing electronic signature workflows and version control integrity, compelling studios to rebuild internal quality management systems around compliant data architectures.
Enterprise procurement teams now unbundle concept design from manufacturing transfer, awarding separate contracts to optimize each phase. Medical device and industrial equipment buyers in the US and EU are qualifying multiple studios for ideation while retaining incumbent manufacturing partners for production ramp. This fragmentation pressures design-only firms to demonstrate manufacturing adjacency without actual captive capacity, often through joint venture arrangements with contract manufacturers.
Product Design and Development Services Market Segmentation
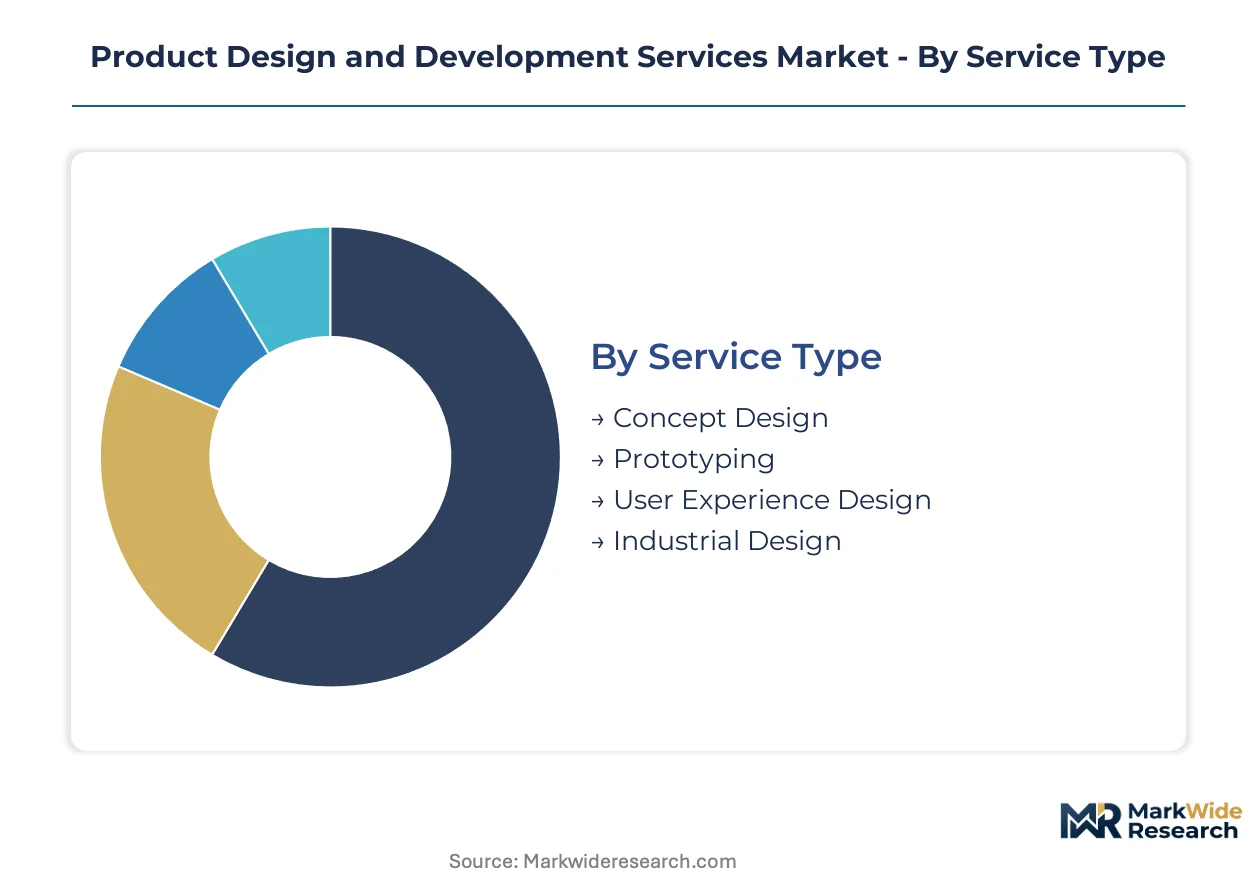
Service differentiation in product design and development hinges on post-launch support intensity, with regulatory documentation and design transfer services generating recurring revenue streams that pure concept work cannot match. Segment boundaries blur as clients demand integrated capabilities spanning ideation through manufacturing readiness.
Service Type:
After-sales service intensity varies dramatically across service types, with industrial design engagements requiring ongoing design-for-manufacturing support while concept design terminates at handoff.
- Industrial Design:Combines aesthetic form development with material specification and ergonomic validation against regulatory safety standards. Medical device manufacturers in Germany and Japan sustain long-term industrial design partnerships to navigate FDA 21 CFR Part 820 documentation requirements through multiple product generations. By volume, Industrial Design leads. By growth pace, User Experience Design is ahead.
- User Experience Design:Encompasses digital interface architecture, interaction flow mapping, and usability testing protocols for connected hardware products. Wearable diagnostics manufacturers concentrate UX investment in Shenzhen-Shanghai corridors where electronics hardware ecosystems enable rapid hardware-software iteration cycles.
- Prototyping:Delivers physical models through additive manufacturing, CNC machining, and soft tooling for functional validation.
- Concept Design:Translates market requirements into preliminary form studies and mood boards without engineering specification.
Margin structures diverge: Industrial Design commands premium fees for regulatory complexity, while Prototyping faces compression from desktop manufacturing tools.
Technology:
Technology selection tracks client maturity, with enterprise automotive and medical device buyers demanding simulation-integrated workflows while mid-market furniture and consumer electronics clients prioritize visualization speed.
- CAD Software:Generates parametric geometries, assembly structures, and manufacturing-ready documentation with version-controlled design histories. Automotive seating manufacturers in Germany deploy CAD-embedded generative algorithms that explore thousands of load-bearing configurations. CAD Software dominates by deployment scale. Simulation Tools expand most quickly as regulatory documentation demands deepen.
- 3D Modeling:Produces surface geometries and render-ready visualizations for stakeholder review and marketing applications.
- Simulation Tools:Validates structural, thermal, and fluid performance against specified load cases prior to physical prototyping.
- Virtual Reality:Enables immersive design review and spatial ergonomics assessment at full scale without physical construction.
Enterprise procurement increasingly unbundles visualization technology from simulation capability, creating vendor fragmentation.
End User:
End-user verticals exhibit divergent procurement patterns, with medical device and automotive buyers qualifying design partners through 12-18 month certification timelines while consumer electronics accelerates engagement velocity.
- Medical Devices:Requires embedded compliance expertise for FDA 21 CFR Part 820 and EU MDR technical documentation with immutable audit trail architectures. EU MDR mandates reshape vendor qualification criteria toward studios with validated risk management processes.
- Automotive:Demands hardware-software co-design capabilities for electric vehicle platform architectures, pulling specialized studios into long-term tier-one supplier partnerships.
- Consumer Electronics:Concentrates in Shenzhen-Shanghai industrial clusters where integrated prototyping corridors compress iteration cycles.
- Furniture:Retains premium industrial design positioning where aesthetic differentiation drives consumer preference.
Medical Devices concentrates the highest fee-per-project. Consumer Electronics generates the steepest volume expansion.
Application:
Application scope determines engagement duration, with full product development cycles extending 18-36 months while design consulting engagements complete in 8-16 weeks.
- Product Development:Encompasses complete translation from requirements through manufacturing transfer with design-for-manufacturing guidance. India's PLI scheme for electronics manufacturing creates demand among contract manufacturers establishing local capacity.
- Design Consulting:Delivers strategic positioning, competitive benchmarking, and technology roadmap advisory without execution responsibility.
- Market Research:Synthesizes user ethnography, trend analysis, and opportunity sizing to inform design brief development.
- Quality Assurance:Validates design outputs against specified performance thresholds and regulatory compliance requirements.
Product Development captures the largest project values. Design Consulting achieves the highest margin percentage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy external design studios for electric vehicle platform acceleration, while Chinese electronics clusters compress iteration cycles through integrated prototyping corridors. Medical device manufacturers in the United States and Japan navigate divergent FDA and PMDA compliance pathways. India's PLI scheme for electronics manufacturing reshapes regional demand patterns for design-for-manufacturing services.
United States
FDA 21 CFR Part 820 quality system regulations compel medical device manufacturers toward design partners with validated risk management processes and immutable audit trail architectures. Boston and Minneapolis medical technology corridors sustain long-term studio partnerships through multiple product generations. Enterprise procurement teams unbundle concept design from manufacturing transfer, qualifying multiple studios for ideation phases.
Germany
Automotive electrification demands simultaneous hardware-software co-design, pulling specialized studios into tier-one supplier relationships for seating and chassis systems. KBA type-approval frameworks intersect with EU MDR technical documentation requirements for diagnostic hardware. Stuttgart and Munich industrial clusters anchor design engagements for load-bearing component optimization using generative algorithms.
China
Shenzhen-Shanghai electronics ecosystems require rapid prototyping cycles that narrow the gap between concept design and mass manufacturing through integrated corridors. SAMR-administered GB standards create compliance pathways favoring regionally rooted service providers. Hardware-intensive engagements concentrate in Pearl River Delta clusters where contract manufacturers maintain captive design-for-manufacturing capabilities.
Japan
METI industrial design promotion frameworks support automotive OEM externalization of platform development functions to accelerate electric vehicle timelines. PMDA quality management system requirements for medical devices reshape vendor qualification toward studios with embedded regulatory documentation expertise. Nagoya and Osaka manufacturing belts sustain hardware-software integration demand for connected product architectures.
India
PLI scheme incentives for electronics manufacturing create demand for design-for-manufacturing services among contract manufacturers establishing local capacity. BIS certification requirements for industrial equipment elevate service complexity for foreign studios entering the market. Karnataka and Tamil Nadu electronics manufacturing clusters attract design partnerships for smartphone and wearable hardware development.
Product Design and Development Services Market Key Industry Players
Capability concentration sits with boutique studios possessing regulatory documentation expertise; scale advantage sits with manufacturing-adjacent firms competing on production integration rather than pure creative output. The vendor base organizes into three tiers: human-centered methodology specialists, hardware-software integration generalists, and manufacturing-captive design units. Consolidation pressure intensifies as enterprise procurement unbundles concept design from manufacturing transfer, forcing pure-play studios toward joint venture arrangements with contract manufacturers.
Within the methodology-driven tier, IDEO and Frog Design exemplify positioning anchored in human-centered frameworks for premium healthcare and consumer electronics engagements. Jabil Inc. occupies the manufacturing-adjacent archetype, leveraging continental production capacity to compete on design-for-manufacturing guidance rather than iterative speed alone. These three entities represent the dominant competitive vectors: creative methodology differentiation, regulatory compliance depth, and production integration scale.
| Leading Market Players |
|---|
| IDEO |
| Frog Design |
| R/GA |
| Ziba Design |
| Designit |
| PDD Group |
| Lunar |
| Smart Design |
| Jabil Inc. |
| Others |
Cost & Logistics Intelligence
Shenzhen's integrated prototyping corridors concentrate high-velocity design capacity, compressing iteration cycles and compressing margins for commoditized modeling services while elevating premium positioning for regulatory-compliant industrial design.
Pricing Analysis
Price spreads between German automotive design studios and Shenzhen-based prototyping houses reach multiples of five to ten times for comparable physical modeling deliverables. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales documentation intensity. Cost compression in concept design runs through desktop manufacturing adoption, eroding basic prototyping fees. Medical device manufacturers exhibit lowest price sensitivity due to FDA 21 CFR Part 820 compliance requirements, while consumer electronics buyers drive hardest bargain on per-iteration costs.
Supply Chain Analysis
Jabil Inc., Foxconn, and Pegatron hold captive design-for-manufacturing capacity across China, Mexico, and Eastern European production corridors. Raw material flows draw from German automotive-grade polymers, Japanese precision metals, and Chinese rare-earth magnet assemblies for connected hardware. Single-source vulnerability concentrates in Shenzhen-Shanghai electronics clusters where contract manufacturers maintain integrated prototyping corridors. Distribution runs through direct OEM procurement teams unbundling concept design from manufacturing transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product design and development services sit in early-cycle expansion as electric vehicle platform architectures and EU MDR compliance mandates pull specialized studios into long-term partnerships.
For Market Incumbents: Entrench regulatory documentation expertise as the primary defensive moat against manufacturing-adjacent competitors. ISO 13485 certification investment creates 12-18 month qualification barriers that mid-cap studios cannot breach. Backward integration into captive prototyping capacity in Shenzhen-Shanghai corridors defends margin position against pure-play concept houses. For New Entrants and Emerging Players: Build out design-for-manufacturing capabilities targeting India's PLI scheme electronics manufacturing clusters, where contract manufacturers lack embedded industrial design. Wearable diagnostics hardware-software integration represents the most penetrable white-space segment. Go-to-market through joint venture arrangements with established EMS providers accelerates credibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EU MDR documentation requirements deepen vendor stickiness across product generations. Acquisition targets should emphasize studios with validated risk management processes and immutable audit trail architectures. Watch FDA investigator emphasis on electronic signature workflow integrity as inflection signal for quality system investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Capability Buildout | FDA 21 CFR Part 820 compliance creates 12-18 month vendor lock-in for medical device engagements. |
| Hardware-Software Integration Partnership | Electric vehicle platform architectures require simultaneous co-design capabilities studios cannot silo. |
| Geographic Expansion to India PLI Clusters | Electronics manufacturing incentive schemes create design-for-manufacturing demand among contract manufacturers. |
| Generative Design Algorithm Deployment | AI-assisted topology optimization renders obsolete manual iterative refinement in structural component design. |
| Carbon Accounting Tool Integration | EU CSRD disclosure requirements push industrial clients toward lifecycle assessment and material traceability capabilities. |
Research Approach
Desk research of regulatory filing databases, industry association technical documentation, and customs trade records preceded structured interviews with industrial design directors, medical device regulatory affairs leads, automotive platform engineers, and contract manufacturing procurement heads. Primary fieldwork combined with secondary validation from FDA 510(k) submission databases, EU MDR technical file repositories, and SAMR GB standard administration records. Bottom-up service-type demand modeling triangulated against top-down end-user vertical spend analysis.
Assumptions held fixed include regulatory framework stability across FDA, EU MDR, and SAMR jurisdictions, while electric vehicle adoption curves and medical device connectivity penetration were varied across sensitivity bands. Segmentation modeling spanned service type, technology deployment, end-user vertical, and application scope dimensions across the projection horizon. CAGRs derived from historical growth rate analysis adjusted for structural shift magnitudes in electrification and compliance documentation intensity.
Stress conditions across tariff exposure in China-US electronics trade, ISO 13485 certification timeline extensions, and generative design algorithm adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Quarterly review of FDA investigator enforcement patterns, EU MDR notified body capacity, and Shenzhen prototyping corridor utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Master Data Management Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Global Cloud POS Market