
 Workspace As a Service Market | 2026-2036
Workspace As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Workspace As a Service Market Intelligence
The capability gap between hyperscale cloud providers and legacy virtualization vendors is collapsing as infrastructure commoditization erodes premium pricing power. Microsoft Corporation leverages its Entra identity fabric and Azure Virtual Desktop to anchor enterprise subscriptions within existing productivity ecosystems. VMware Inc. competes through deep virtualization heritage and Broadcom's channel control, while Citrix Systems Inc. specializes in high-definition remote protocols for graphics-intensive workloads.
Workspace As a Service delivers virtualized computing environments where desktop operating systems, applications, and data reside in cloud or hybrid data centers, streamed to endpoint devices via encrypted display protocols with latency thresholds typically below 150 milliseconds for standard productivity tasks. Virtual Desktop Infrastructure dominates current revenue pools due to established enterprise refresh cycles, though Containerization is displacing legacy virtualization for ephemeral, developer-centric workloads. Managed Workspaces capture expanding margin pools as mid-market buyers outsource endpoint security patching, identity governance, and compliance monitoring to specialized providers.
The EU AI Act, GDPR, and NIS2 Directive collectively mandate data localization, algorithmic transparency, and incident reporting that reshape procurement criteria for cross-border workspace deployments. FDA 21 CFR Part 11 and HIPAA in the United States impose parallel validation requirements on life sciences and healthcare adopters, fragmenting vendor certification roadmaps. Stakeholders must monitor regulatory divergence between data sovereignty regimes and cloud interoperability standards when selecting deployment architectures.
Market Dynamics
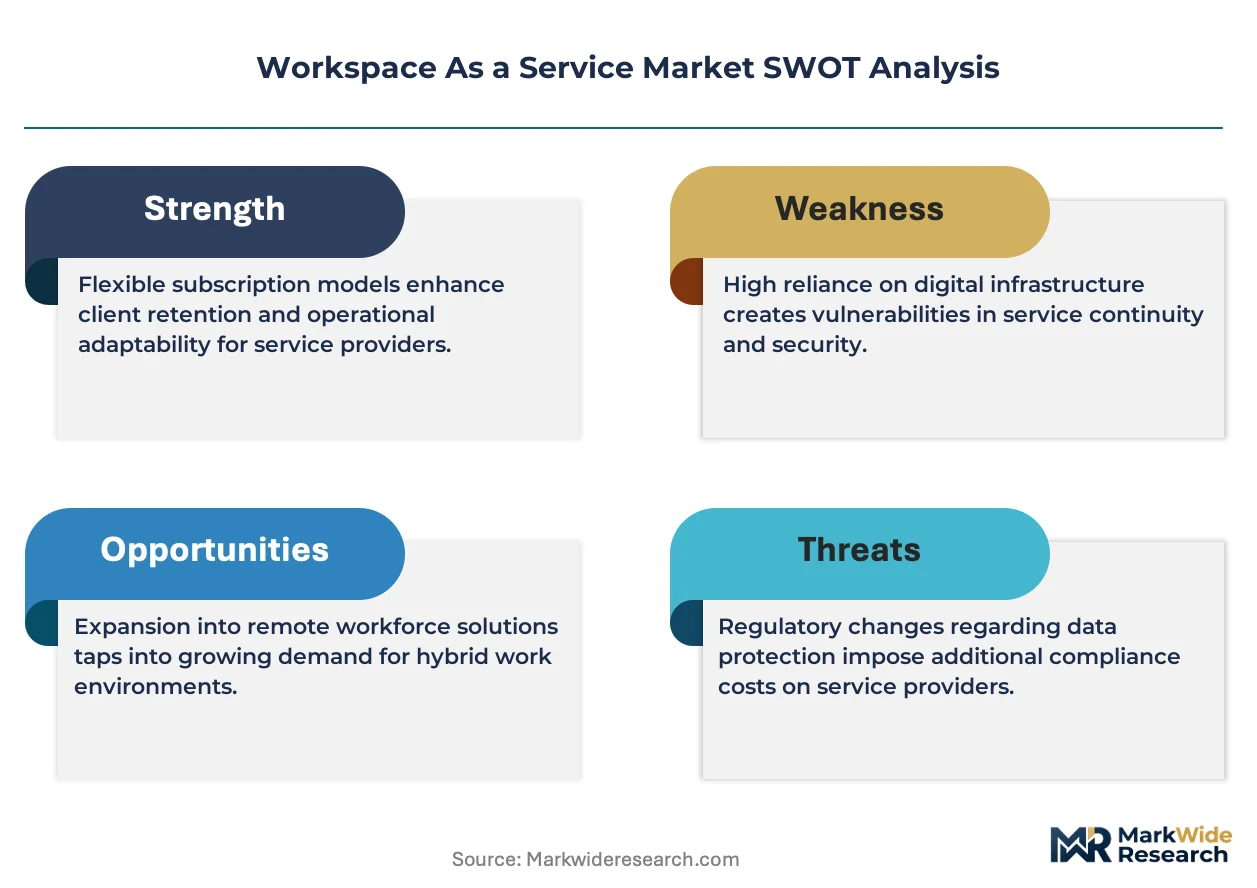
Enterprise data sovereignty mandates are collapsing the traditional cloud vendor selection framework, forcing procurement teams to prioritize jurisdictional control over performance benchmarks when evaluating workspace platforms.
Growth Catalysts
- EU AI Act compliance deadlines:Financial services institutions in Germany and France are accelerating migrations to sovereign-hosted virtual desktops to satisfy algorithmic transparency and data localization requirements.
- Containerization adoption:Developer-centric organizations are replacing persistent virtual machines with ephemeral containerized workspaces, reducing infrastructure overhead and improving CI/CD pipeline velocity.
- Healthcare digitization:HIPAA-covered entities in the United States are expanding managed workspace deployments to satisfy FDA 21 CFR Part 11 validation requirements for electronic records.
Market Restraints
- Broadcom channel consolidation:VMware's partner program restructuring has reduced distribution touchpoints, creating vendor lock-in risk for mid-market buyers dependent on legacy virtualization stacks.
- Latency physics:Sub-150 millisecond display protocol thresholds remain unattainable over standard internet connections in rural broadband deserts, limiting addressable geography.
- Graphics processing unit scarcity:NVIDIA supply concentration for virtual GPU acceleration is inflating per-user costs for engineering and media workloads.
Strategic Opportunities
- NIS2 Directive preparation:Managed service providers can capture compliance-mandated incident response and security monitoring contracts from EU enterprises with cross-border operations.
- Edge workspace nodes:Telecom operators in the United Kingdom are deploying micro data centers to deliver sub-50 millisecond desktop streaming for high-frequency trading floors.
- Zero trust architecture convergence:Identity-aware proxy integration with virtual desktop infrastructure is creating unified secure access bundles for hybrid workforce deployments.
Industry Challenges
- Legacy Active Directory entanglement:Decades of on-premises identity infrastructure complicate cloud-native workspace migrations and extend project timelines.
- Multi-cloud orchestration talent:Shortage of engineers proficient in both Citrix and Azure Virtual Desktop administration is inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workspace As a Service Market |
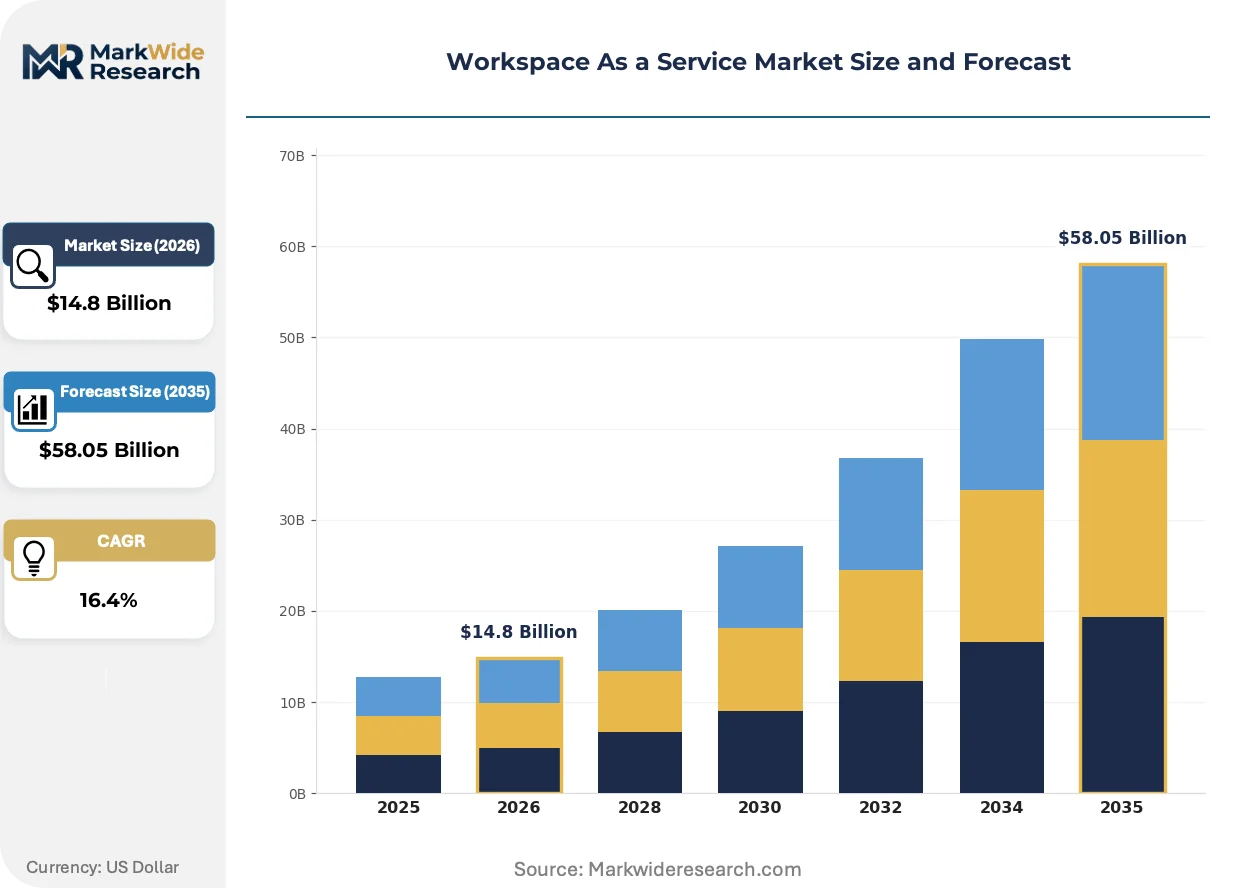
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Desktop Infrastructure, Managed Workspaces, Cloud Desktops, Remote Collaboration Tools End User: Small Enterprises, Large Corporations, Freelancers, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Technology: Virtualization, Containerization, API Integration, Network Security |
| Companies Covered | Amazon Web Services Inc., Microsoft Corporation, VMware Inc., Citrix Systems Inc., Unisys Corporation, Dell Technologies Inc., Google LLC, Tech Mahindra Limited, Colt Technology Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workspace As a Service Market Strategic Shifts & Innovations
Workspace delivery architectures are fragmenting along workload persistence lines, with vendor strategies diverging between high-security persistent desktops and ephemeral developer environments. This schism is reshaping R&D investment priorities and partnership ecosystems.
Container-based workspace runtimes are bifurcating the virtualization market. Kubernetes-orchestrated desktop pods deliver 40% faster provisioning than traditional VDI clones. DevOps teams at software vendors are adopting these ephemeral environments for secure build pipelines, compressing hardware refresh cycles and displacing perpetual license models with consumption-based pricing.
GDPR Article 44 transfer mechanism enforcement is tightening cross-border data flow restrictions. EU data protection authorities are rejecting standard contractual clauses for workspace deployments lacking technical supplementary measures. German automotive manufacturers are responding by mandating EU-sovereign cloud regions for all engineering workstation hosting, fragmenting vendor roadmaps between compliance-first and performance-first architectures.
Enterprise buying committees are consolidating workspace procurement under zero trust security transformation programs. CISOs are unbundling traditional desktop management from endpoint detection and response, selecting best-of-breed vendors for each layer. This pattern is most pronounced in United Kingdom financial services, where regulatory pressure from the Prudential Regulation Authority is accelerating vendor consolidation decisions.
Workspace As a Service Market Segmentation
Workspace As a Service procurement channels fragment sharply across service maturity tiers, with managed service providers dominating high-touch enterprise contracts while hyperscale marketplaces capture self-serve developer workloads. Understanding segment-channel alignment exposes margin concentration and competitive vulnerability points for vendor positioning.
Service Type:
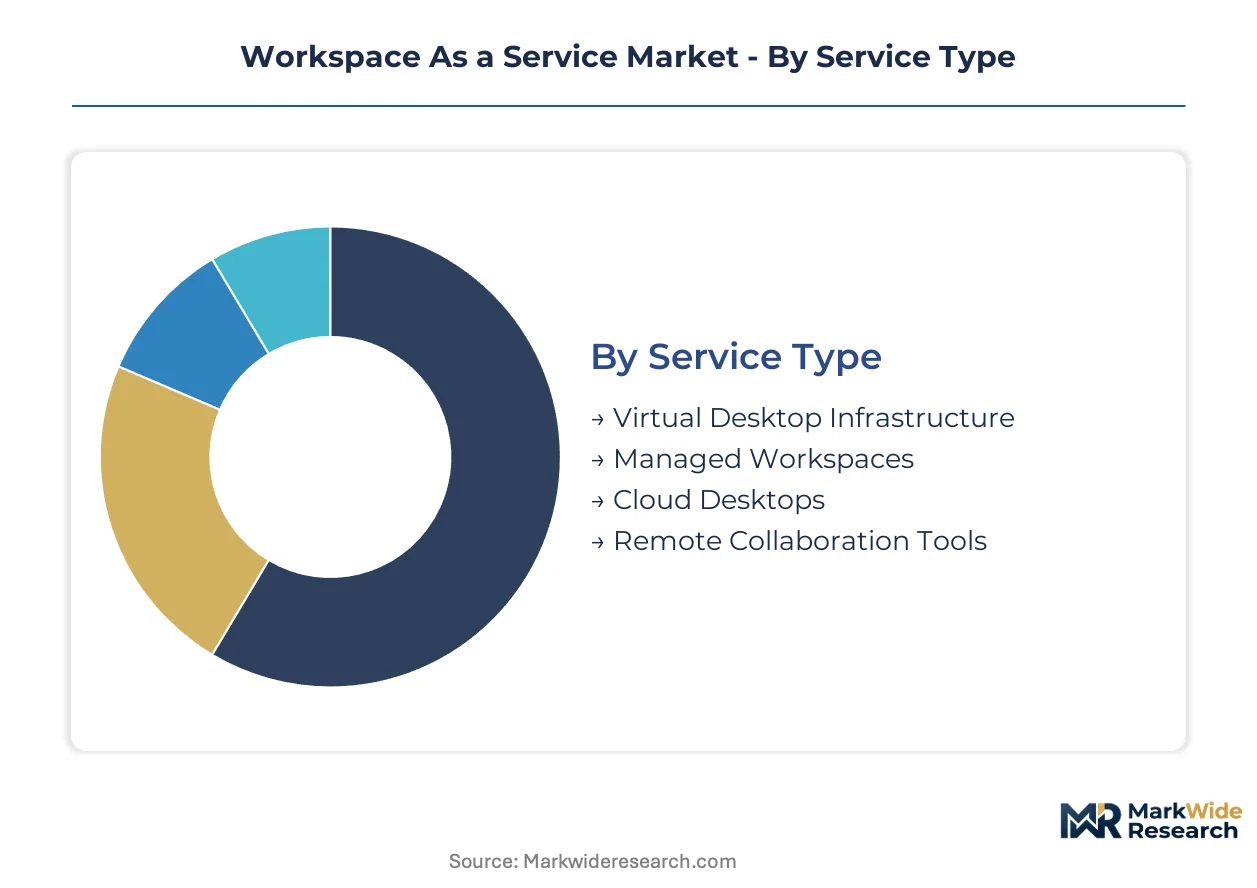
Channel mix varies dramatically by service complexity, with Virtual Desktop Infrastructure flowing through established value-added resellers and Managed Workspaces concentrating in specialized security-focused integrators.
- Virtual Desktop Infrastructure:Persistent desktop sessions hosted on centralized servers stream full Windows or Linux environments to thin clients. Financial services institutions in Germany and France are accelerating sovereign-hosted VDI procurement to satisfy EU AI Act data localization mandates ahead of compliance deadlines.
- Managed Workspaces:Comprehensive outsourcing bundles encompassing endpoint security patching, identity governance, and compliance monitoring. Mid-market buyers in the United Kingdom are consolidating procurement under zero trust transformation programs, capturing expanding margin pools for specialized providers.
- Cloud Desktops:Browser-accessible productivity environments with consumption-based billing.
- Remote Collaboration Tools:Application-specific streaming for video conferencing and document co-editing.
By volume, Virtual Desktop Infrastructure leads. By growth pace, Managed Workspaces is expanding most quickly.
End User:
Customer scale determines pricing architecture and sales cycle length, with Large Corporations demanding customized sovereign deployments and Small Enterprises accepting standardized SaaS tiers.
- Large Corporations:Multi-thousand seat deployments with bespoke compliance requirements. Healthcare organizations in the United States are expanding managed workspace footprints to satisfy FDA 21 CFR Part 11 validation requirements for electronic records systems.
- Small Enterprises:Sub-hundred seat implementations prioritizing rapid provisioning over customization. These buyers face acute vendor lock-in risk from VMware's partner program restructuring under Broadcom channel consolidation.
- Freelancers:Individual subscriptions with pay-as-you-go flexibility.
- Educational Institutions:Seasonal demand patterns with campus-wide licensing negotiations.
Large Corporations dominate current revenue pools. Small Enterprises are gaining share fastest as standardized offerings reduce implementation friction.
Deployment Model:
Architecture choice reflects data sovereignty risk tolerance, with regulated industries accepting higher operational burden for jurisdictional control.
- Public Cloud:Shared infrastructure with hyperscale economics. Developer-centric organizations are replacing persistent virtual machines with ephemeral containerized workspaces, compressing hardware refresh cycles.
- Private Cloud:Dedicated single-tenant environments. German automotive manufacturers are mandating EU-sovereign cloud regions for all engineering workstation hosting following GDPR Article 44 enforcement tightening.
- Hybrid Cloud:Workload portability across on-premises and cloud infrastructure.
- On-Premise:Fully captive data center deployments for maximum control.
Public Cloud holds the largest installed base. Private Cloud is climbing the fastest as regulatory pressure intensifies.
Technology:
R&D investment bifurcates between legacy virtualization optimization and cloud-native container orchestration, reshaping vendor competitive moats.
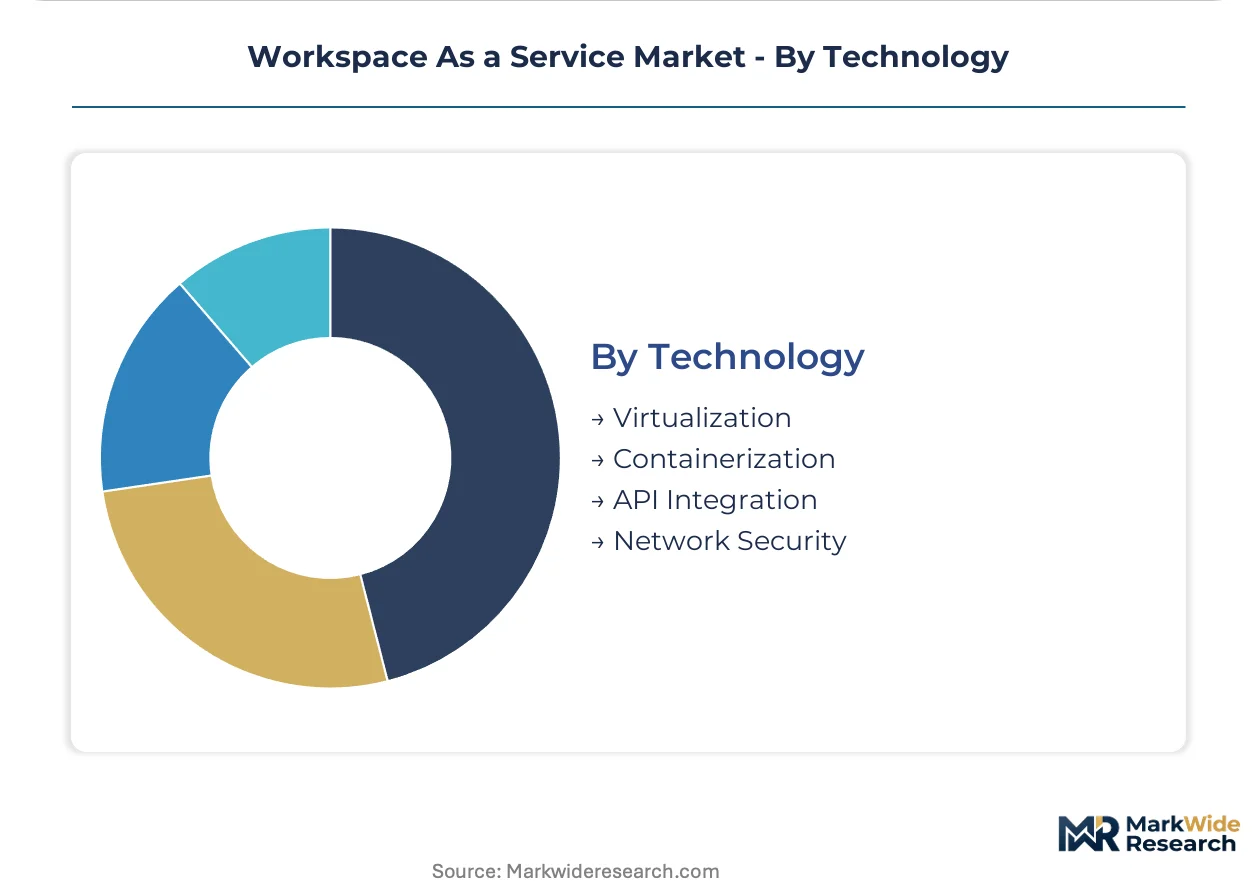
- Containerization:Kubernetes-orchestrated desktop pods delivering ephemeral environments. DevOps teams at software vendors are adopting these runtimes for secure build pipelines, achieving forty percent faster provisioning than traditional VDI clones.
- Virtualization:Hypervisor-based resource abstraction with mature management tooling. Legacy Active Directory entanglement complicates cloud-native migrations and extends project timelines for established enterprises.
- API Integration:Programmatic workspace provisioning and configuration management.
- Network Security:Encrypted display protocols and zero trust access enforcement.
Virtualization dominates current infrastructure spend. Containerization shows the steepest expansion trajectory as developer-centric adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate the lowest price elasticity as regulatory compliance overrides cost optimization, while small enterprises in the United States and United Kingdom exhibit acute sensitivity to per-seat pricing fluctuations.
Germany
Financial services institutions in Frankfurt and Munich are accelerating sovereign-hosted virtual desktop procurement to satisfy EU AI Act algorithmic transparency mandates ahead of enforcement deadlines. The Federal Financial Supervisory Authority (BaFin) is tightening cross-border data flow scrutiny for cloud workspace deployments. Automotive manufacturers in Stuttgart and Wolfsburg are mandating EU-sovereign cloud regions for all engineering workstation hosting following GDPR Article 44 enforcement tightening.
France
Paris-based banking groups are expanding managed workspace footprints to capture compliance-mandated incident response contracts under NIS2 Directive preparation timelines. The National Commission on Informatics and Liberty (CNIL) is rejecting standard contractual clauses for workspace deployments lacking technical supplementary measures. Aerospace and defense clusters in Toulouse are prioritizing zero trust architecture convergence for hybrid workforce security transformation programs.
United Kingdom
London financial services firms are consolidating workspace procurement under zero trust security transformation programs driven by Prudential Regulation Authority pressure. Telecom operators are deploying micro data centers to deliver sub-50 millisecond desktop streaming for high-frequency trading floors in the City. Healthcare organizations in Greater Manchester are expanding managed workspace deployments to satisfy FDA-aligned validation requirements for electronic records systems.
United States
HIPAA-covered entities in Boston and San Francisco are expanding managed workspace footprints to satisfy FDA 21 CFR Part 11 validation requirements for electronic records. The Securities and Exchange Commission is intensifying cybersecurity disclosure rules that reshape procurement criteria for financial services workspace platforms. Developer-centric organizations in Seattle are replacing persistent virtual machines with ephemeral containerized workspaces to compress CI/CD pipeline velocity.
India
IT services exporters in Bengaluru and Hyderabad are adopting container-based workspace runtimes for secure build pipelines serving global enterprise clients. The Reserve Bank of India's data localization guidelines are forcing financial institutions to evaluate sovereign-hosted virtual desktop architectures. Mid-market buyers in Mumbai are consolidating procurement under standardized SaaS tiers as implementation friction declines.
Workspace As a Service Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with hyperscale cloud providers anchoring infrastructure commoditization while specialized virtualization vendors retain premium positioning in graphics-intensive and regulated workloads. The vendor base organizes into three strategic tiers: identity-anchored productivity ecosystems, deep virtualization heritage platforms, and security-centric managed service specialists. Dominant competitive moves include hyperscale marketplace expansion into self-serve developer segments and channel consolidation that reduces distribution touchpoints for legacy virtualization stacks.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services Inc. exemplify the identity-anchored productivity ecosystem archetype, leveraging existing enterprise subscription relationships to capture virtual desktop workloads. VMware Inc. and Citrix Systems Inc. occupy positions within the deep virtualization heritage tier, with the latter specializing in high-definition remote protocol differentiation for latency-sensitive use cases. Tech Mahindra Limited represents the security-centric managed service specialist archetype, capturing compliance-mandated outsourcing contracts from mid-market buyers prioritizing endpoint governance over infrastructure ownership.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| Microsoft Corporation |
| VMware Inc. |
| Citrix Systems Inc. |
| Unisys Corporation |
| Dell Technologies Inc. |
| Google LLC |
| Tech Mahindra Limited |
| Colt Technology Services |
| Others |
Cost & Logistics Intelligence
Per-seat subscription contracts with consumption-based overage clauses lock in multi-year supply commitments for hyperscale cloud infrastructure while anchoring price predictability for enterprise procurement teams navigating EU AI Act compliance timelines.
Pricing Analysis
Managed security services and compliance monitoring bundles drive lifetime value expansion beyond base desktop streaming fees. Three-tier pricing structure across premium sovereign-hosted, standard multi-tenant, and economy self-service tiers reflects jurisdictional control levels and support depth. Cost compression in standard tiers is intensifying because hyperscale providers are absorbing infrastructure commoditization pressure. Small enterprises in the United States exhibit acute price sensitivity, while German financial institutions show minimal elasticity under BaFin-mandated data localization requirements.
Supply Chain Analysis
The United States and Ireland anchor hyperscale data center capacity for North American and European workspace delivery. Taiwan and South Korea supply critical GPU acceleration hardware for graphics-intensive virtual workstations. Supply chain vulnerability centers on NVIDIA chip allocation concentration for virtual GPU instances. Distribution runs through direct enterprise sales teams for large contracts and cloud marketplaces for developer self-provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workspace As a Service functions as a service-attach opportunity where managed security and compliance layers expand faster than raw compute infrastructure, rewarding vendors who bundle governance automation with desktop delivery.
For Market Incumbents: Shield installed base relationships by embedding zero trust identity fabrics deeper into existing productivity ecosystems before container-native alternatives displace persistent virtual machines. Prioritize certification investment for EU AI Act and HIPAA validation tiers to defend premium pricing against hyperscale commodity pressure. Channel control consolidation under Broadcom's VMware restructuring creates vendor lock-in risk that Microsoft and Amazon can exploit through migration incentives. For New Entrants and Emerging Players: Differentiate on sovereign data residency guarantees for mid-market buyers in France and Germany facing NIS2 Directive incident response mandates. Target containerized ephemeral workspaces for DevOps teams at software vendors seeking CI/CD pipeline acceleration. Lead with API-first provisioning and consumption-based billing to bypass legacy value-added reseller gatekeeping. For Investors and Strategic Acquirers: Security-centric managed service specialists with healthcare and financial services compliance expertise represent the most defensible acquisition profile. Long-term viability hinges on recurring revenue attachment rates exceeding infrastructure-only margins. Monitor GDPR Article 44 enforcement actions as the signal indicating which sovereign hosting architectures will capture compliance-premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | EU AI Act deadlines in Germany and France are accelerating demand for jurisdictional data control. |
| Zero Trust Architecture Integration | CISOs in UK financial services are unbundling endpoint security from desktop management layers. |
| Container-Native Workspace Development | Kubernetes-orchestrated pods deliver forty percent faster provisioning for DevOps build pipelines. |
| Managed Compliance Service Bundling | NIS2 Directive preparation is expanding incident response contract opportunities across EU enterprises. |
| Edge Micro Data Center Deployment | Telecom operators in London are deploying sub-fifty-millisecond nodes for high-frequency trading floors. |
Research Approach
Desk research of hyperscaler capex disclosures, regulatory filing databases, and channel partner program documentation preceded structured interviews with CISOs, IT procurement officers, platform engineers, and managed service provider executives. Primary fieldwork captured deployment architecture decisions, vendor switching triggers, and compliance-driven procurement criteria across financial services, healthcare, and software development verticals. Secondary validation drew from SEC 10-K infrastructure segments, EU regulatory impact assessments, and cloud marketplace transaction data. Bottom-up seat deployment estimates triangulated against top-down addressable workforce calculations.
Variance decomposition across service type, deployment model, organization scale, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions included persistent versus ephemeral workload persistence, public versus sovereign-hosted infrastructure, and vertical-specific compliance requirements. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU AI Act implementation timelines, Broadcom channel restructuring velocity, and containerization adoption curves in developer-centric organizations.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and hyperscale infrastructure investment continuity; material deviation in GPU supply availability or cross-border data flow restrictions would warrant model refresh. Recalibration cycles align with material shifts in sovereign cloud region deployment timelines and NIS2 Directive enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Distributed Performance and Availability Management Software Market