
 Control Room Solutions Market | 2026-2036
Control Room Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Control Room Solutions Market Analysis
The EU Green Deal is shifting procurement criteria for control room infrastructure across European energy operators. Schneider Electric leverages its EcoStruxure platform to anchor grid management contracts in markets with carbon accountability mandates. ABB competes through its Ability portfolio, which sustains long-term service relationships with transmission system operators. Siemens dominates the German-speaking utility segment through localized engineering support and IEC 61850 protocol leadership.
Control room solutions integrate video wall arrays, supervisory software, audio distribution networks, and real-time data networking equipment into unified command environments. Systems typically process multiple 4K video streams with sub-50-millisecond latency to enable coordinated incident response across distributed infrastructure. Video wall and control software segments lead investment flows, as operators replace legacy projection systems with direct-view LED and software-defined visualization platforms. The energy sector end-user category generates the fastest procurement velocity, driven by renewable integration complexity and decentralized generation monitoring requirements.
FERC Order 2222 in the United States and the EU Electricity Directive shape control room interoperability mandates and cybersecurity disclosure requirements. IEC 62443 standards for industrial automation security are becoming de facto procurement filters in European and North American utility tenders. Stakeholders must monitor evolving NERC CIP compliance thresholds and their cascading impact on software upgrade cycles and vendor qualification timelines.
Market Dynamics
Grid operators face escalating complexity from distributed renewable generation and bi-directional power flows, forcing wholesale replacement of analog control interfaces with software-defined visualization platforms that integrate SCADA, EMS, and weather forecasting into unified decision environments.
Growth Catalysts
- FERC Order 2222:US grid operators must enable aggregated distributed energy resource participation, requiring control room upgrades to manage bidirectional dispatch signals from rooftop solar and battery clusters.
- Direct-view LED video walls:LED pitch densities below 1.2mm are replacing rear-projection cubes in transmission control centers, eliminating lamp maintenance cycles and enabling 24/7 operational continuity.
- German transmission consolidation:Four regional dispatch centers are merging into two national facilities, triggering concentrated procurement of redundant control room infrastructure with IEC 61850 protocol compliance.
Market Restraints
- Copper and rare earth input volatility:Video wall driver boards and power supply units depend on copper laminate substrates and neodymium magnets, with price swings compressing hardware margins for integrators.
- Single-source GPU acceleration:Real-time rendering engines rely on NVIDIA datacenter GPUs, creating supply vulnerability when allocation prioritizes hyperscale cloud providers over industrial automation vendors.
- IEC 62443 certification timelines:Multi-year security assessment cycles for control system software delay product launches and freeze vendor qualification pipelines at European utilities.
Strategic Opportunities
- Offshore wind integration:North Sea cable landing stations in the Netherlands and Denmark require new coastal control facilities to synchronize HVDC converter stations with onshore grid balancing.
- AI-augmented alarm management:Machine learning classification of SCADA event floods converges with digital twin simulation to reduce operator cognitive load during cascading fault scenarios.
- EU Green Deal procurement mandates:Carbon footprint disclosure requirements for grid infrastructure create preference for vendors with embodied emissions certification and circular hardware take-back programs.
Industry Challenges
- IEC 61850 engineering expertise scarcity:Substation automation protocol implementation requires specialized systems integrators, with talent pools concentrated in Germany and Switzerland creating project bottlenecks elsewhere.
- Multi-vendor integration complexity:Control rooms must synchronize video walls from display specialists, middleware from software vendors, and audio systems from broadcast integrators without proprietary lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Control Room Solutions Market |
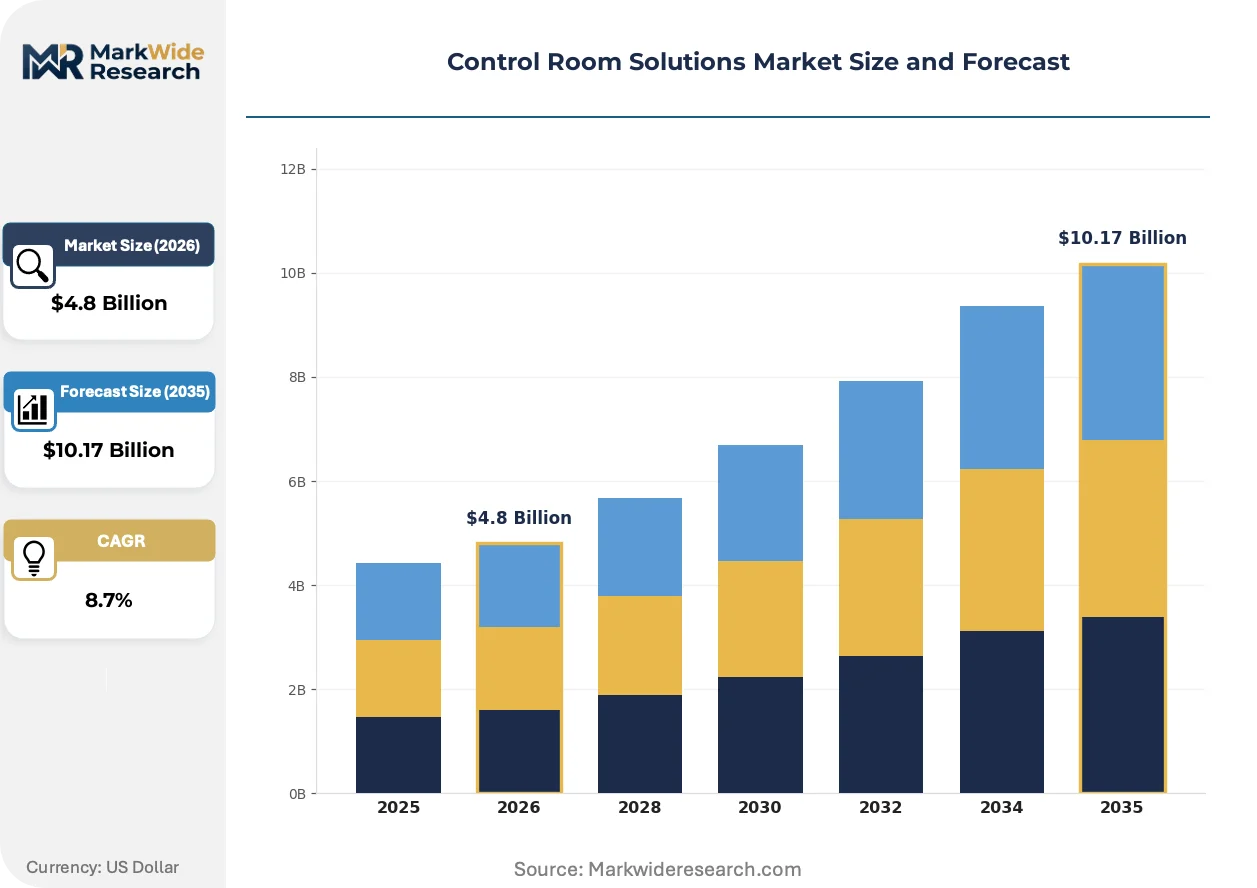
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Wall, Control Software, Audio Systems, Networking Equipment End User: Transportation, Energy Sector, Public Safety, Defense Technology: LED Displays, LCD Panels, Projection Systems, Touchscreens Application: Monitoring, Incident Management, Data Visualization, Command Operations |
| Companies Covered | Schneider Electric, ABB, Honeywell, Allegion, Brivo, Johnson Controls, Bosch, Coram, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Control Room Solutions Market Emerging Trajectories
Visualization hardware and control software architectures are converging around IP-based signal distribution, eliminating dedicated matrix switchers and enabling elastic scaling of video wall canvases through standard networking infrastructure.
Direct-view LED is electrifying control room display technology. Pixel pitches below 0.9mm deliver seamless imagery at typical operator viewing distances, eliminating bezel gaps that fragmented legacy LCD arrays. European transmission operators are specifying fine-pitch LED for new-build facilities, with German TSOs leading adoption. This technology is electrifying competitive dynamics by shifting procurement criteria from resolution specifications to thermal management and front-serviceability designs that minimize operational downtime.
The EU AI Act introduces risk classification for automated decision systems in critical infrastructure, including grid control applications with autonomous dispatch capabilities. Operators must document algorithmic transparency and human oversight protocols before deploying machine learning models for load forecasting. German-speaking utilities are responding by establishing internal AI governance boards and requiring vendor disclosure of training data provenance for predictive maintenance modules.
Buyer organizations are consolidating vendor relationships through multi-year framework agreements that bundle hardware, software licensing, and field engineering support. Single-source accountability replaces fragmented procurement of displays, processors, and control systems from separate suppliers. This concentration is most pronounced at Scandinavian distribution system operators, where standardization across regional control centers reduces spare parts inventory and training overhead.
Control Room Solutions Market Segmentation
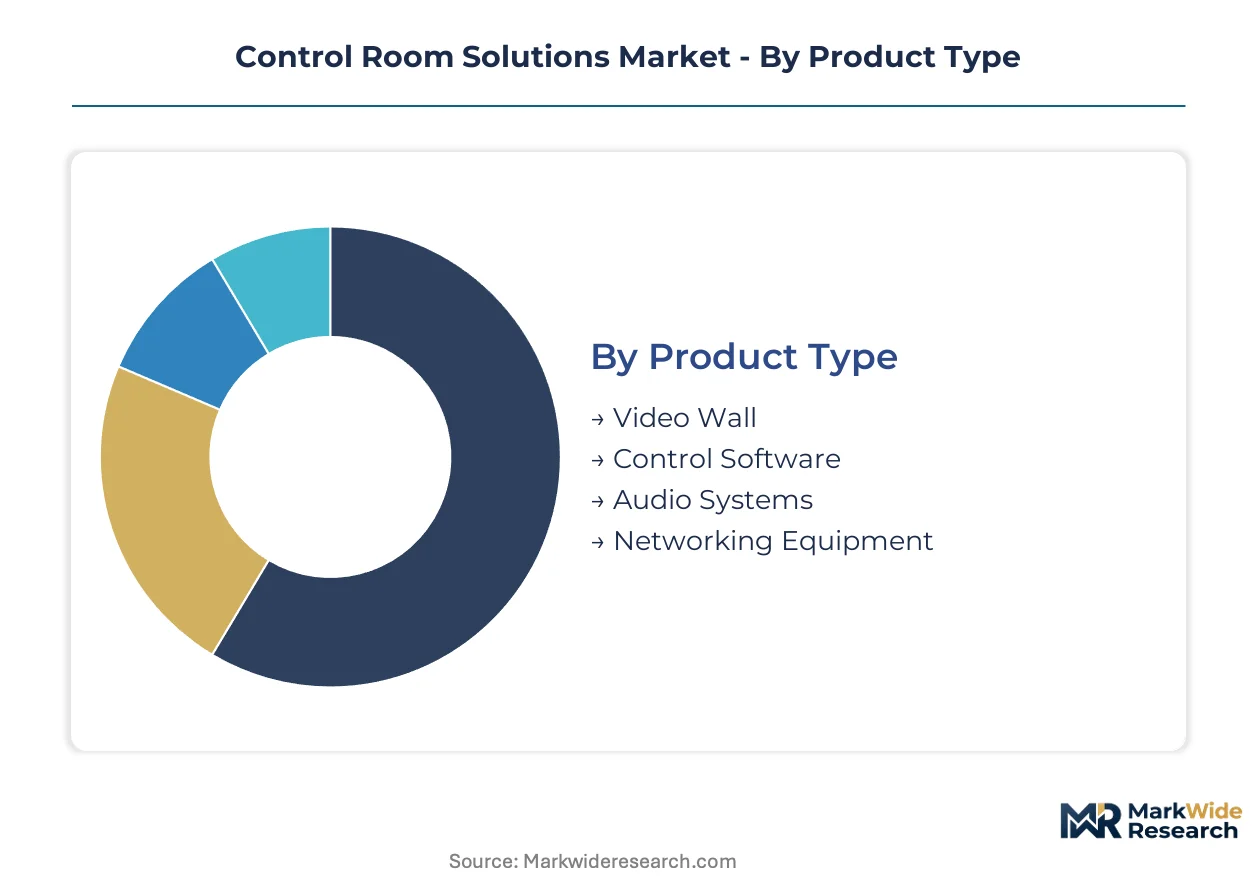
Control room procurement cycles follow distinct technology refresh patterns across hardware, software, and integration layers. Each segment category reflects different replacement timelines, from five-year video wall refreshes to decade-long software platform commitments. Understanding these rhythms enables vendors to align R&D investment with predictable budget windows.
Product Type:
Upgrade cycles vary sharply across product categories, with display hardware demanding capital-intensive replacement while software shifts toward recurring subscription models.
- Video Wall:Direct-view LED arrays with sub-1.2mm pixel pitch are displacing legacy rear-projection cubes in transmission control centers. German TSOs specify fine-pitch LED for 24/7 operational continuity, eliminating lamp maintenance cycles that disrupted legacy systems.
- Control Software:SCADA-integrated visualization platforms process multiple 4K streams with sub-50-millisecond latency. Scandinavian DSOs consolidate procurement through multi-year framework agreements, bundling licensing with field engineering support to reduce spare parts inventory.
- Audio Systems:IP-based distribution networks replace analog matrix infrastructure.
- Networking Equipment:Real-time data switching hardware enables elastic scaling of video wall canvases.
Video Wall sits at the top of the volume ranking, with Control Software climbing the fastest.
End User:
Customer concentration patterns reflect sector-specific regulatory pressures and infrastructure modernization mandates.
- Energy Sector:Grid operators manage renewable integration complexity through unified command environments. FERC Order 2222 compels US utilities to upgrade control rooms for bidirectional dispatch from distributed solar and battery clusters.
- Transportation:Air traffic and rail dispatch centers prioritize sub-50-millisecond latency for coordinated incident response.
- Public Safety:Emergency operations centers demand redundant visualization for 24/7 continuity.
- Defense:Secure facilities require IEC 62443-certified systems with multi-year security assessment cycles.
Energy Sector commands the largest procurement budgets, while Transportation shows the steepest expansion trajectory as airport modernization accelerates.
Technology:
Display technology selection hinges on viewing distance, ambient lighting, and front-serviceability requirements.
- LED Displays:Fine-pitch direct-view panels below 0.9mm deliver seamless imagery at operator workstations. EU Green Deal carbon disclosure requirements favor vendors with embodied emissions certification and circular hardware take-back programs.
- LCD Panels:Legacy arrays with bezel gaps fragment visualization continuity.
- Projection Systems:Rear-projection cubes face accelerated replacement as LED pitch densities improve.
- Touchscreens:Interactive surfaces enable direct manipulation of SCADA interfaces for load forecasting.
LED Displays dominate new-build specifications, with Touchscreens gaining share fastest through AI-augmented alarm management integration.
Application:
Use case prioritization shapes integration complexity and vendor qualification requirements.
- Monitoring:Continuous visualization of distributed infrastructure demands redundant video wall arrays with thermal management designs that minimize downtime.
- Incident Management:Coordinated response protocols require synchronized audio distribution and real-time data networking across multiple 4K streams.
- Data Visualization:Software-defined platforms integrate weather forecasting with EMS and SCADA for unified decision environments.
- Command Operations:Multi-vendor integration complexity forces standardization on IP-based signal distribution to eliminate proprietary lock-in.
Monitoring accounts for the deepest installed base, though Incident Management is expanding most quickly as grid operators face escalating fault scenario complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The control room solutions industry traces its commercial roots to German industrial automation engineering in the 1970s, when substation automation protocols first standardized operator interfaces for grid management. This engineering heritage continues to shape procurement patterns and technical specifications across utility markets worldwide.
United States
FERC Order 2222 mandates aggregated distributed energy resource participation, forcing grid operators to upgrade control rooms for bidirectional dispatch from rooftop solar and battery clusters. NERC CIP compliance thresholds cascade into software upgrade cycles and vendor qualification timelines. Texas and California transmission operators concentrate procurement of redundant video wall infrastructure with sub-50-millisecond latency requirements.
Germany
Four regional dispatch centers are consolidating into two national facilities, triggering concentrated demand for IEC 61850-compliant control room infrastructure. The EU Green Deal tightens grid reliability standards and imposes carbon footprint disclosure requirements on grid infrastructure procurement. Munich and Hamburg anchor engineering talent pools for substation automation protocol implementation.
United Kingdom
Offshore wind integration drives demand for coastal control facilities to synchronize HVDC converter stations with onshore grid balancing. The EU AI Act risk classification framework shapes procurement criteria for automated decision systems in grid control applications. North Sea cable landing stations in Grimsby and Teesside require new command environments.
Netherlands
North Sea offshore wind expansion necessitates new coastal control facilities for HVDC converter synchronization. EU Electricity Directive interoperability mandates and cybersecurity disclosure requirements filter vendor qualification. Rotterdam and Eindhoven concentrate transmission operator procurement of direct-view LED video wall arrays with front-serviceability designs.
China
Dual carbon goals accelerate grid modernization investments across provincial transmission operators. GB standards and MIIT industrial automation security frameworks shape procurement filters for control system software. Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing of video wall driver boards and real-time data networking equipment.
Control Room Solutions Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software-defined visualization and protocol compliance capabilities. The vendor base organizes into three tiers: integrated industrial automation conglomerates with full-stack portfolios, specialized display hardware manufacturers with thermal management expertise, and regional systems integrators with IEC 61850 engineering capabilities. Consolidation pressures favor multi-year framework agreements that bundle hardware, software licensing, and field engineering support. Vertical integration into GPU-accelerated rendering engines and IP-based signal distribution represents the dominant competitive trajectory.
Within the integrated automation tier, Schneider Electric and ABB exemplify archetypes competing through platform-based grid management contracts. Siemens anchors the German-speaking utility segment through localized engineering support. These three entities occupy positions defined by their respective protocol leadership, carbon accountability certification, and long-term service relationship structures rather than discrete product advantages.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Honeywell |
| Allegion |
| Brivo |
| Johnson Controls |
| Bosch |
| Coram |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Copper price volatility on the London Metal Exchange cascades through video wall manufacturing tiers, compressing margins for LED driver board producers while amplifying cost premiums for IEC 62443-certified control software bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified systems with multi-year security validation from rapid-deployment alternatives. Price differentiation hinges on IEC 61850 protocol compliance and front-serviceability engineering for 24/7 operational continuity. Cost compression in mid-tier hardware is intensifying because GPU allocation bottlenecks favor hyperscale cloud providers over industrial automation vendors. Scandinavian distribution system operators exhibit lowest price sensitivity due to framework agreement consolidation, while regional integrators in Southern Europe face acute margin pressure from talent scarcity.
Supply Chain Analysis
Dual-sourcing requirements for NVIDIA datacenter GPUs now mandate multi-supplier qualification across German transmission operators and North American utilities. Manufacturing concentrates in China for LED driver boards, Taiwan for GPU fabrication, and Germany for IEC 61850 engineering talent pools. Raw material dependencies draw from copper laminate substrates, neodymium magnets, and gallium nitride semiconductors. Single-source vulnerability around NVIDIA GPU allocation creates supply chain risk. Distribution runs through systems integrators with substation automation expertise rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German engineering talent premiums against Chinese manufacturing cost advantages create geographic-arbitrage opportunities for vendors balancing carbon disclosure mandates with margin preservation.
For Market Incumbents: Cement platform dominance through captive supply of GPU-accelerated rendering engines and exclusive IEC 61850 training partnerships with Munich engineering institutes. Schneider Electric and ABB already anchor grid management contracts; newcomers threaten through AI-augmented alarm management modules. Defensive moves require backward integration into IP-based signal distribution silicon and carbon accountability certification lock-in with EU Green Deal procurement officers. For New Entrants and Emerging Players: Enter via coastal control facilities for North Sea offshore wind integration, where HVDC converter synchronization demand outpaces established vendor capacity. White-space targets cluster in Netherlands and Denmark cable landing stations. Target AI governance board consulting for German-speaking utilities as the EU AI Act mandates algorithmic transparency documentation. Go-to-market angle: predictive maintenance modules with disclosed training data provenance. For Investors and Strategic Acquirers: Consolidation pressure builds where IEC 61850 engineering expertise concentrates in Germany and Switzerland while project demand spreads geographically. Long-term viability favors vendors with software-defined visualization platforms bundling hardware, licensing, and field engineering under single-source accountability. Acquisition target archetype: regional systems integrators with substation automation credentials and existing utility relationships. Signal to watch: NERC CIP compliance threshold revisions triggering vendor requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GPU Rendering Engines | Captive supply of NVIDIA-dependent acceleration reduces allocation vulnerability for FERC Order 2222 compliance upgrades. |
| Carbon Accountability Certification Program | EU Green Deal procurement mandates favor vendors with embodied emissions disclosure and circular hardware take-back. |
| Framework Agreement Consolidation | Scandinavian DSOs bundle multi-year licensing with field engineering to reduce spare parts inventory overhead. |
| AI Governance Board Partnership | German utilities require vendor disclosure of training data provenance for predictive maintenance module deployment. |
| Front-Serviceability Engineering Investment | Fine-pitch LED thermal management designs minimize operational downtime for 24/7 transmission control centers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with control room operators, substation automation engineers, utility procurement officers, and systems integration specialists against secondary validation through FERC filings, EIA grid modernization databases, IEC standard documentation, and EU Electricity Directive implementation reports. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure tracking.
Comparable historical periods anchored the projection horizon to technology refresh cycles observed across five-year video wall replacement timelines and decade-long software platform commitments. The analytical framework modeled deployment scale, integration complexity, regulatory framework stringency, and regional grid type across the forecast period. CAGRs derived from segment-level procurement velocity weighted by renewable integration mandates. Industry-specific inputs included SCADA system upgrade announcements and HVDC converter station commissioning schedules.
Inputs from utility planning officers and transmission operator procurement teams were available through the study window; gaps in confidential framework agreement pricing introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding FERC Order 2222 implementation pacing and EU AI Act enforcement timelines. Deviation in NERC CIP compliance threshold revisions or NVIDIA GPU allocation prioritization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
North America API Management Market