
 Metal and Metal Ores Market | 2026-2036
Metal and Metal Ores Market Size, Share, and Industry Trends Forecast 2026-2036
Metal and Metal Ores Market Analysis
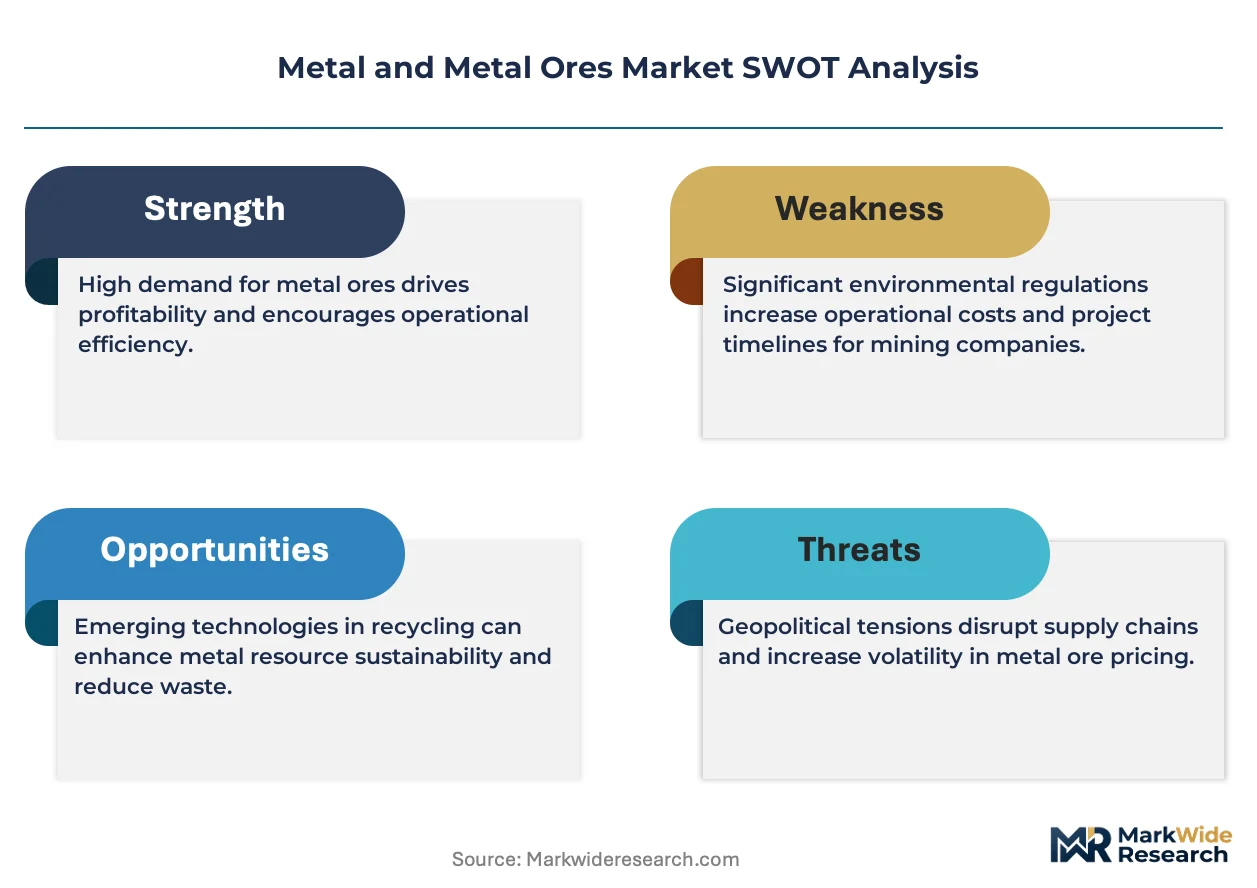
The premium-commodity split in metal and metal ores is recalibrating around carbon intensity and traceability credentials. BHP leverages integrated mine-to-port logistics to sustain cost leadership in Pilbara iron ore. Rio Tinto anchors its position through autonomous haulage systems that differentiate operating efficiency across copper and aluminum assets. Glencore competes via its trading arm's control over concentrate flows and concentrates on cobalt and nickel streams tied to energy transition demand.
Metal and metal ores encompass extracted geological deposits and refined metallic outputs with defined chemical compositions, typically processed through crushing, grinding, flotation, smelting, or electrolytic refinement to achieve industrial-grade purity thresholds. These materials serve as foundational inputs for infrastructure, transportation, energy systems, and manufactured goods requiring specific tensile, conductive, or thermal properties. Iron ore retains the largest volume footprint among product types, while nickel experiences the most rapid demand acceleration from battery cathode chemistry requirements. Aluminum ingots and sheets command margin premiums in aerospace and automotive lightweighting applications where grade certification dictates supplier qualification.
The EPA enforces emissions thresholds for US smelting facilities under the Clean Air Act, while the EU's REACH framework and Carbon Border Adjustment Mechanism impose disclosure and tariff obligations on imported metal products based on embedded carbon content. China's MEE administers dual carbon compliance timelines that restrict expansion permits for high-emission ferroalloy capacity. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate cost pass-through structures and relocation incentives for primary processing capacity.
Market Dynamics
Carbon accounting mandates are restructuring procurement hierarchies across smelting and refining operations, with embedded emissions now functioning as a primary supplier qualification filter alongside traditional purity and volume metrics.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers face disclosure obligations and tariff exposure based on embedded carbon, accelerating investment in low-emission smelting retrofits across European-bound supply chains.
- Electric vehicle battery cathode chemistry:High-purity nickel sulfate demand from NCM and NCA battery formulations is pulling capacity expansion into Indonesia's processing corridor.
- Aluminum lightweighting specifications:Aerospace and automotive OEMs are qualifying lithium-grade aluminum suppliers for structural components, creating margin premiums for certified producers.
Market Restraints
- Energy cost volatility:Smelting operations in Germany and Spain face margin compression from natural gas price swings that directly determine electrolytic aluminum production economics.
- Indonesian nickel concentrate concentration:Downstream battery manufacturers confront supply security exposure as Indonesian ore processing corridors consolidate under integrated mining-smelter operators.
- Scrap substitution ceiling:Secondary aluminum and copper flows face metallurgical limits in high-performance aerospace and electrical applications where primary metal traceability remains mandatory.
Strategic Opportunities
- Chilean copper belt expansion:Untapped porphyry deposits in the Atacama region offer brownfield development potential with existing infrastructure access and water rights frameworks.
- Green hydrogen reduction pilots:Direct reduction iron processes using hydrogen feedstock are opening decarbonization pathways for European steelmakers facing EU ETS compliance costs.
- Blockchain traceability platforms:Digital product passports tracking mine-to-mill carbon intensity are creating new service revenue layers for logistics intermediaries and certification bodies.
Industry Challenges
- Process metallurgist scarcity:Specialized expertise in hydrometallurgical extraction and electrowinning optimization is concentrating among retiring workforce cohorts in Australian and Canadian mining jurisdictions.
- Smelter retrofit capex cycles:Carbon capture and inert anode installations require 8-12 year payback horizons that conflict with quarterly earnings pressures at publicly traded producers.
- Multi-jurisdiction compliance stacking:Simultaneous adherence to EPA Clean Air Act thresholds, EU REACH substance restrictions, and China's MEE dual carbon timelines fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal and Metal Ores Market |
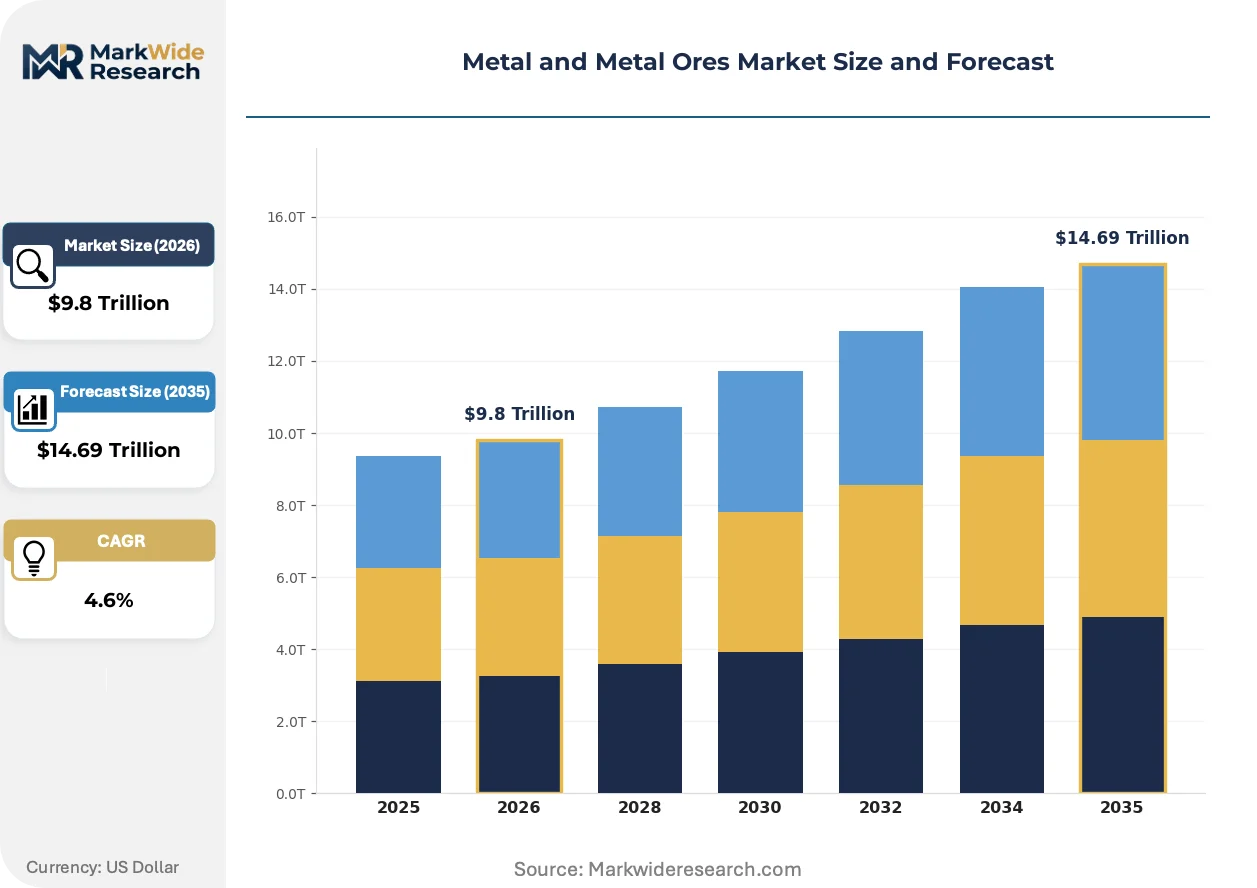
| Market Size in 2026 | $9.8 Trillion |
| Market Size in 2035 | $14.69 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Iron Ore, Nickel End Use Industry: Construction, Electronics, Aerospace, Automotive Form: Ingots, Sheets, Bars, Wire Grade: High-Grade, Medium-Grade, Low-Grade, Scrap |
| Companies Covered | BHP, Rio Tinto, Glencore, Freeport-McMoRan, Vale, Anglo American, Aluminum Corporation of China, Baoshan Iron & Steel, China Minmetals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal and Metal Ores Market Emerging Trajectories
Operational intelligence systems and process electrification are converging to redefine extraction economics, with digital twins and renewable-powered smelting emerging as parallel transformation vectors rather than sequential upgrades.
Direct lithium extraction from brine deposits is overtaking traditional solar evaporation methods in South American salars. BMW and Tesla procurement teams have qualified DLE-derived lithium carbonate for battery-grade specifications. This technology is compressing project development timelines from 18-24 months to under 12 months while reducing freshwater intensity.
China's MEE enforcement of dual carbon compliance timelines is restricting expansion permits for high-emission ferroalloy capacity. Domestic producers are redirecting capital toward Indonesian nickel processing joint ventures with hydropower offtake agreements. Ferrochrome and ferromanganese segments face the most severe permit constraints under the 2025-2030 emission intensity benchmarks.
Long-term offtake contracting with fixed-price escalators is displacing spot market procurement for battery-grade nickel and cobalt. Korean cathode manufacturers are locking in 5-7 year supply agreements directly with Indonesian HPAL operators. This pattern is most visible in binding memoranda between POSCO and Huayou Cobalt for MHP and mixed hydroxide precipitate volumes.
Metal and Metal Ores Market Segmentation
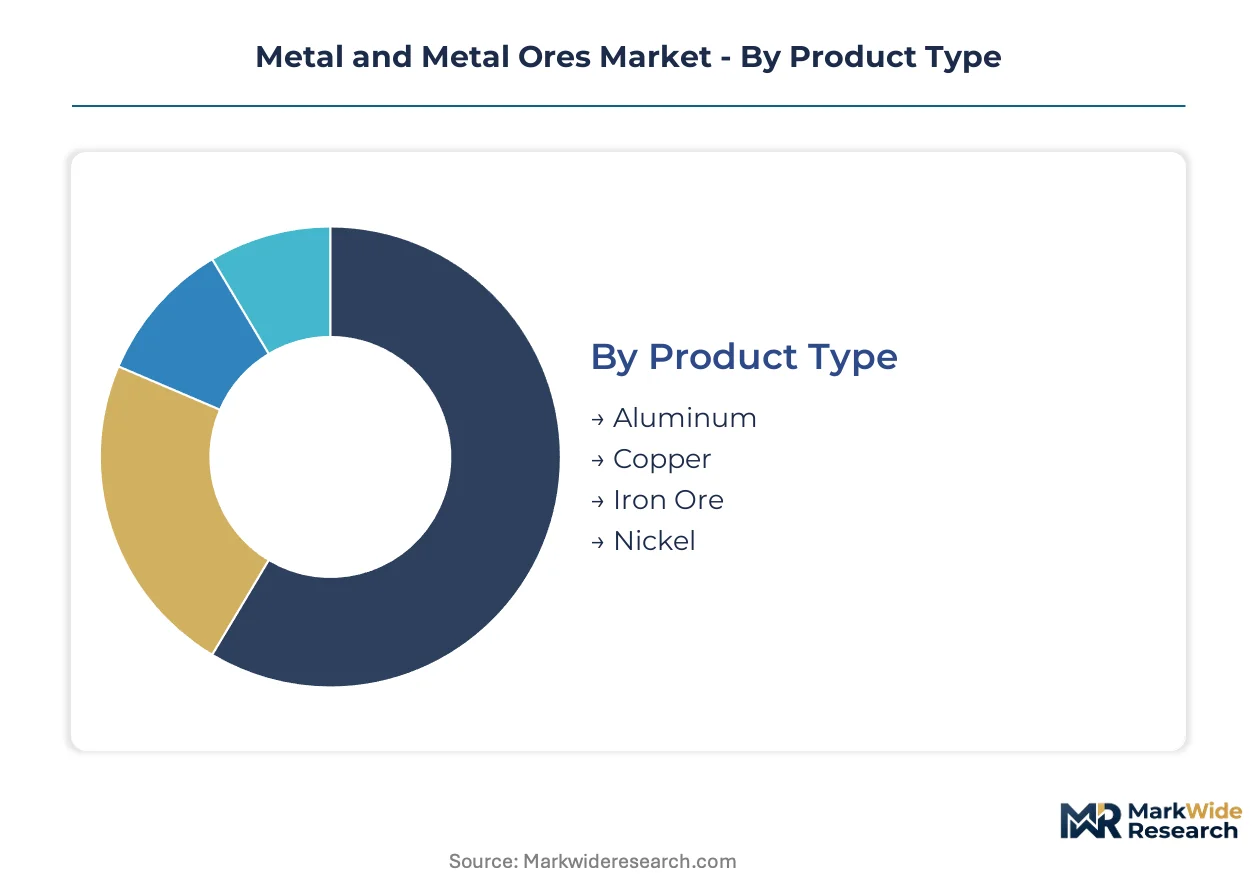
Metal and metal ores markets fragment across multiple technical and commercial dimensions, with product chemistry, physical form, and purity specifications determining end-use qualification pathways. Procurement hierarchies now weight carbon intensity and traceability credentials alongside traditional grade and volume metrics, reshaping how segments compete for margin and market position.
Product Type:
Volume leadership sits with bulk commodities moving through integrated mine-to-port infrastructure, while premium capture concentrates in battery-grade and aerospace-certified materials commanding qualification-driven pricing power.
- Iron Ore:Hematite and magnetite deposits processed through crushing, grinding, and magnetic separation dominate seaborne trade volumes. Pilbara operations in Australia and Carajás deposits in Brazil anchor supply to Chinese blast furnaces, though direct reduction-grade pellets are gaining share in European hydrogen steelmaking pilots.
- Aluminum:Bauxite refining through the Bayer process yields alumina feedstock for Hall-Héroult electrolytic smelting. Lithium-grade primary ingots from Quebec and Iceland hydropower smelters command aerospace qualification premiums as Boeing and Airbus tighten supplier certification.
- Copper:Porphyry deposits processed through flotation concentration and smelting provide cathode feedstock for electrical applications. Chilean concentrate flows through Antofagasta and Escondida anchor global refined supply.
- Nickel:Laterite ores processed via high-pressure acid leaching in Indonesia's Morowali corridor yield mixed hydroxide precipitate for battery cathode manufacturing. Korean cathode producers have locked multiyear offtake agreements with HPAL operators.
Today's leader: Iron Ore. Tomorrow's challenger: Nickel.
End Use Industry:
Application-driven segmentation separates infrastructure-weighted demand from technology-intensive qualification requirements, with mobility and energy transition sectors pulling capacity into new metallurgical specifications.
- Automotive:Body-in-white stamping and powertrain casting consume the majority of aluminum and steel tonnage, with EV battery enclosures and electric motor laminates driving lithium-grade and oriented electrical steel demand. Tesla and BYD procurement teams have qualified Indonesian nickel sulfate for NCM cathode formulations.
- Construction:Rebar, structural beams, and cladding systems absorb high-volume ferrous and aluminum output, with green building certifications beginning to embed recycled content thresholds into project specifications.
- Aerospace:Wing spars, fuselage skins, and turbine disks require 7xxx-series aluminum and titanium-aluminide intermetallics with full batch traceability and NADCAP heat treatment certification.
- Electronics:High-purity copper foil for PCB laminates and sputtering targets for semiconductor fabrication demand 5N+ purity with controlled oxygen content below 10 ppm.
Construction maintains volume dominance. Automotive delivers the steepest expansion trajectory as electrification reconfigures material intensity per vehicle.
Form:
Physical processing stage determines logistics economics and customer conversion flexibility, with intermediate forms offering inventory positioning advantages and finished forms capturing fabrication value.
- Ingots:Cast primary metal in standardized shapes for remelting and alloying, serving as the fundamental exchange-traded unit for aluminum and copper pricing benchmarks on the LME and CME.
- Sheets:Rolled flat products ranging from foil gauges below 0.2mm to plate thicknesses exceeding 6mm, with automotive closure panels and can stock representing high-volume applications.
- Bars:Long products extruded or rolled to round, square, or hexagonal cross-sections, supplying machining stock for fasteners, shafts, and structural connectors across industrial equipment.
- Wire:Drawn rod down to micrometer diameters for electrical conductors, welding electrodes, and steel cord reinforcement in tire manufacturing.
Ingots anchor commodity trading liquidity. Sheets capture the widest margin spread between raw material and engineered component.
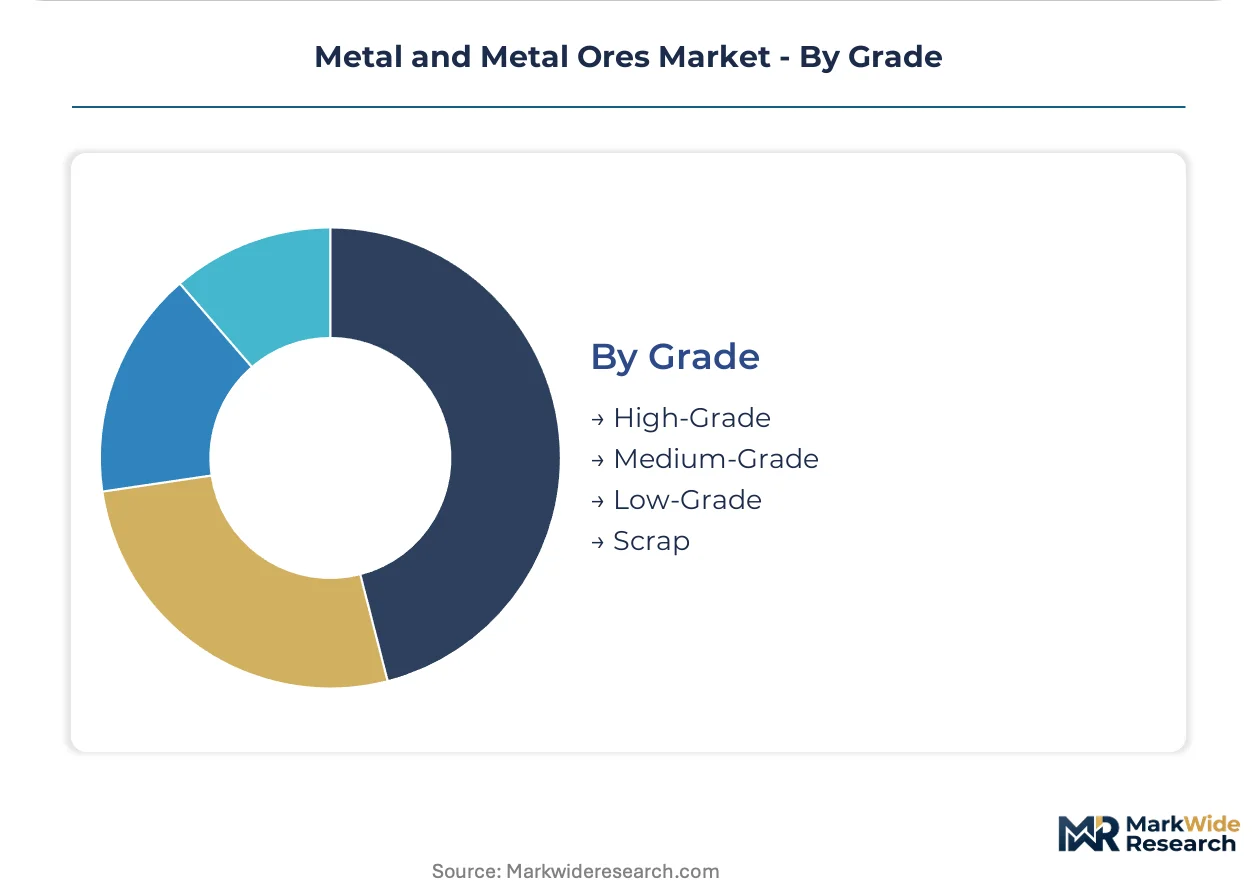
Grade:
Purity and provenance stratification now overlays traditional chemical specifications, with carbon-accounted and conflict-free designations emerging as parallel grading dimensions alongside metallurgical quality.
- High-Grade:Primary metal exceeding 99.9% purity with full smelter traceability and embedded carbon disclosure, mandatory for aerospace qualification and increasingly required by automotive OEMs under EU Battery Regulation due diligence rules.
- Medium-Grade:Standard commercial purity levels serving general industrial applications where performance specifications permit broader compositional tolerances and secondary refining economics.
- Low-Grade:Higher impurity content suitable for foundry applications and bulk alloying where downstream processing can accommodate variable feedstock chemistry.
- Scrap:Recovered metal flows from manufacturing offcuts and post-consumer collection, constrained by metallurgical limits in high-performance applications but expanding in construction and packaging through closed-loop collection systems.
High-Grade commands qualification premiums. Scrap faces substitution ceilings in aerospace and semiconductor applications where primary traceability remains non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical engineers and process technicians concentrate in Australia's Pilbara region, Chile's Atacama Desert, and Indonesia's Sulawesi corridor, anchoring extraction economics to talent density rather than ore grade alone.
Australia
Pilbara iron ore operations supply Chinese blast furnaces through Port Hedland bulk terminals, while direct reduction pellet capacity expands for European hydrogen steelmaking pilots. The country's Clean Energy Regulator administers Safeguard Mechanism reforms tightening baseline emissions intensity for smelting facilities. Perth-based engineering consultancies concentrate hydrometallurgical expertise serving Indonesian nickel joint ventures.
Chile
Escondida and Collahuasi porphyry deposits feed global copper cathode demand through Antofagasta concentrate exports and Codelco's Ventanas smelter complex. The Ministry of Mining enforces glacier protection protocols restricting expansion permits in Andean watershed zones. Calama and Antofagasta host concentrator maintenance clusters serving seawater desalination-dependent operations.
China
Baoshan Iron & Steel and Aluminum Corporation of China anchor domestic ferrous and non-ferrous output, while MEE dual carbon timelines restrict new ferroalloy permits. The 2025-2030 emission intensity benchmarks redirect capital toward Indonesian nickel processing with hydropower offtake agreements. Jiangsu and Shandong provinces concentrate secondary aluminum remelting capacity serving automotive closed-loop collection systems.
Indonesia
Morowali Industrial Park hosts high-pressure acid leaching operations yielding mixed hydroxide precipitate for Korean cathode manufacturers under 5-7 year offtake contracts. The Ministry of Energy and Mineral Resources regulates nickel ore export bans driving downstream processing investment. Sulawesi's Weda Bay corridor attracts integrated mining-smelter operators seeking captive energy supply.
United States
Arizona's Morenci and Utah's Bingham Canyon porphyry deposits supply domestic refined copper for electrical grid infrastructure and semiconductor fabrication. EPA Clean Air Act thresholds enforce emissions caps on primary smelting facilities in Utah and Missouri. Detroit-area automotive stamping plants qualify lithium-grade aluminum suppliers for EV battery enclosure specifications under NHTSA safety protocols.
Metal and Metal Ores Market Vendor Landscape
Capital-heavy integrated miners compete with asset-light concentrate traders and toll-smelting operators across divergent margin structures. The vendor base stratifies into three tiers: diversified majors controlling mine-to-port logistics, national champions with state-backed offtake guarantees, and specialist traders arbitraging regional grade differentials. Dominant competitive moves include brownfield capacity expansion in low-carbon jurisdictions and strategic partnerships binding battery manufacturers to Indonesian HPAL output.
Within the diversified major tier, BHP and Rio Tinto exemplify integrated operators leveraging Pilbara infrastructure and autonomous haulage systems respectively. Glencore occupies a distinct position bridging physical trading dominance with cobalt and nickel stream exposure to energy transition demand. These three entities anchor competitive dynamics across seaborne iron ore, copper concentrate, and battery-grade nickel sulfate procurement hierarchies.
| Leading Market Players |
|---|
| BHP |
| Rio Tinto |
| Glencore |
| Freeport-McMoRan |
| Vale |
| Anglo American |
| Aluminum Corporation of China |
| Baoshan Iron & Steel |
| China Minmetals |
| Others |
Supply Flow & Price Mechanics
Specialized hydrometallurgical engineers concentrated in Australia's Perth basin and Chile's Calama maintenance clusters command wage premiums that compress margin spreads between high-grade battery materials and standard commercial ores. Labor-cost differentials between these talent-dense jurisdictions and emerging processing corridors in Indonesia directly widen pricing-tier spreads for certified versus uncertified metal outputs.
Pricing Analysis
Unbundled concentrate trading dominates spot market liquidity while bundled mine-to-metal service packages capture long-term offtake premiums. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified high-grade nickel from medium-grade commercial cathode feed and low-grade foundry inputs. Price differentiation hinges on carbon intensity disclosure and batch traceability certification under EU Battery Regulation due diligence rules. Cost compression in standard-grade aluminum is intensifying because German smelters face natural gas price volatility that erodes electrolytic production economics. Battery manufacturers exhibit lowest price sensitivity for high-purity nickel sulfate, while construction-sector rebar purchasers drive aggressive volume discounting.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Shanghai function as hub-and-spoke clearing points for seaborne concentrate flows before final smelter delivery. Geographic supply concentrates in Australia, Chile, and Indonesia, with Pilbara iron ore, Atacama copper concentrate, and Morowali nickel laterite anchoring respective commodity streams. Raw material dependencies center on sulfuric acid for HPAL processing, metallurgical coal for reduction furnaces, and flux reagents for smelter fluxing. Single-source vulnerability runs through Indonesia's nickel processing corridor where integrated mining-smelter operators control mixed hydroxide precipitate flows. Distribution runs through long-term offtake contracting with fixed-price escalators displacing spot procurement for battery-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Indonesian processing capacity draws capital away from Chinese ferroalloy expansion restricted by MEE dual carbon timelines, exploiting the regulatory cost differential between jurisdictions.
For Market Incumbents: Anticipate margin compression from Indonesian HPAL operators locking Korean cathode manufacturers into captive supply arrangements. Defensive moves require securing hydropower offtake agreements in Quebec and Iceland to sustain low-carbon aluminum qualification premiums, while investing in autonomous haulage systems across Pilbara and Atacama assets to maintain operating cost leadership against emerging integrated competitors. For New Entrants and Emerging Players: Capture white-space opportunity in blockchain-enabled carbon accounting platforms serving logistics intermediaries seeking digital product passport revenue layers. The most penetrable segment sits with mid-tier aerospace suppliers lacking full batch traceability infrastructure, accessible through partnership-based certification bundling with established Quebec smelters rather than greenfield capacity investment. For Investors and Strategic Acquirers: Battery OEMs are the most active acquirer in this space, with Tesla and BYD procurement teams directly qualifying Indonesian nickel sulfate streams. Long-term viability over a multi-year horizon favors brownfield copper expansion in Chile's Atacama region with existing water rights and infrastructure access. The signal to watch is Korean cathode manufacturer consolidation of 5-7 year offtake terms with HPAL operators, indicating locked-in supply security that forecloses late entrant access.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Korean cathode manufacturers lock Indonesian HPAL output under binding offtake terms with POSCO. |
| Backward Integration | Chinese producers redirect capital toward captive Indonesian nickel processing with hydropower offtake. |
| Green Certification Program | Quebec and Iceland smelters qualify lithium-grade aluminum for Boeing and Airbus supplier tiers. |
| Capacity Expansion | Brownfield copper development in Atacama leverages existing seawater desalination infrastructure. |
| Joint Venture | Integrated mining-smelter operators consolidate Morowali Industrial Park processing corridors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mine operations managers, cathode manufacturer procurement leads, smelter technical directors, and concentrate trading desk heads with secondary validation against customs trade data, SEC 10-K filings, IEA mineral supply reports, and LME warehouse stock disclosures. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume and value estimates.
Segment-weighting across product type, end-use industry, physical form, and grade purity dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of electric vehicle battery chemistry shifts, smelter emission compliance cost pass-throughs, and aerospace qualification timelines. Industry-specific forecast inputs incorporated HPAL project development timelines and EU Carbon Border Adjustment Mechanism tariff phase-in assumptions.
Commodity price volatility, regulatory enforcement divergence between EPA and MEE timelines, and process metallurgist workforce attrition are the dominant revision risks that could shift capacity expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Fabricated Metal Products Market