
 Lithium Ingots Market | 2026-2036
Lithium Ingots Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ingots Market Analytics
The EU Battery Regulation is consolidating sustainability requirements across the European cell supply chain, mandating recycled content thresholds and carbon footprint declarations for lithium inputs. Albemarle Corporation leverages its Chilean brine operations and North Carolina processing assets to sustain a vertically integrated position in battery-grade ingot supply. Tianqi Lithium Inc. anchors its competitiveness through spodumene concentration capabilities in Western Australia and downstream refining partnerships in China.
Lithium ingots are cast or extruded forms of refined metallic lithium, typically exceeding 99.5% purity, produced through molten salt electrolysis of lithium chloride and used primarily as anode precursors and alloy feedstock in high-performance battery systems. The purity grade dimension stratifies across standard, high-purity, and ultra-high purity tiers, with ultra-high purity ingots commanding premium positioning in solid-state battery R&D programs where trace metal tolerances sit below 10 ppm. Among end-user segments, automotive batteries dominate volume offtake while power storage represents the fastest-growing demand pool as grid-scale lithium-metal prototypes advance from laboratory to pilot manufacturing.
The U.S. EPA and OSHA frameworks govern lithium handling and workplace exposure limits, while China's SAMR enforces GB/T 26008 standards for battery-grade lithium metal purity and packaging specifications. These regulatory layers shape demand by disqualifying non-compliant suppliers from qualified vendor lists at major cell manufacturers. Stakeholders must monitor evolving purity specifications from NMPA and ECHA as next-generation battery chemistries redefine acceptable contaminant thresholds.
Market Dynamics
Automotive OEMs are consolidating lithium ingot procurement around battery-grade purity specifications that disqualify legacy metallurgical suppliers, compressing qualified vendor lists and amplifying price premiums for certified producers.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The EU Battery Regulation mandates minimum recycled lithium thresholds and carbon footprint declarations, forcing cell manufacturers to source certified ingots from audited supply chains.
- Solid-state battery R&D acceleration:Ultra-high purity ingots with sub-10 ppm trace metal tolerances are becoming essential precursors for lithium-metal anode prototypes advancing toward pilot manufacturing.
- China's Sichuan-Jiangxi processing corridor:Integrated brine-to-ingot infrastructure in these provinces is reducing logistics costs and lead times for battery-grade material offtake.
Market Restraints
- Spodumene concentrate supply volatility:Hard rock lithium feedstock prices fluctuate with Australian mining output, transmitting cost instability downstream to ingot refiners.
- Chilean brine export licensing:CORFO production quotas and export permit delays create supply uncertainty for non-integrated processors dependent on Atacama feedstock.
- Sodium-ion battery substitution:CATL and BYD are commercializing sodium-ion cells for grid storage applications, threatening lithium ingot demand in price-sensitive stationary segments.
Strategic Opportunities
- US IRA domestic content credits:The Inflation Reduction Act's $35/kWh cell production tax credit creates procurement pull for North American-refined ingots qualifying under domestic content rules.
- Direct lithium extraction technology:DLE methods using selective sorbents and membrane filtration are enabling brine processing without evaporation ponds, opening new feedstock sources in Utah and California.
- Aerospace alloy applications:High-strength lithium-aluminum alloys for satellite structures and aircraft components represent a premium demand channel outside battery markets.
Industry Challenges
- Electrolysis technician scarcity:Molten salt cell operation requires specialized metallurgical expertise that training programs have failed to scale with production capacity expansion.
- GB/T 26008 certification timelines:China's SAMR battery-grade purity testing protocols create 4-6 month vendor qualification delays that block new entrants from qualified supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ingots Market |
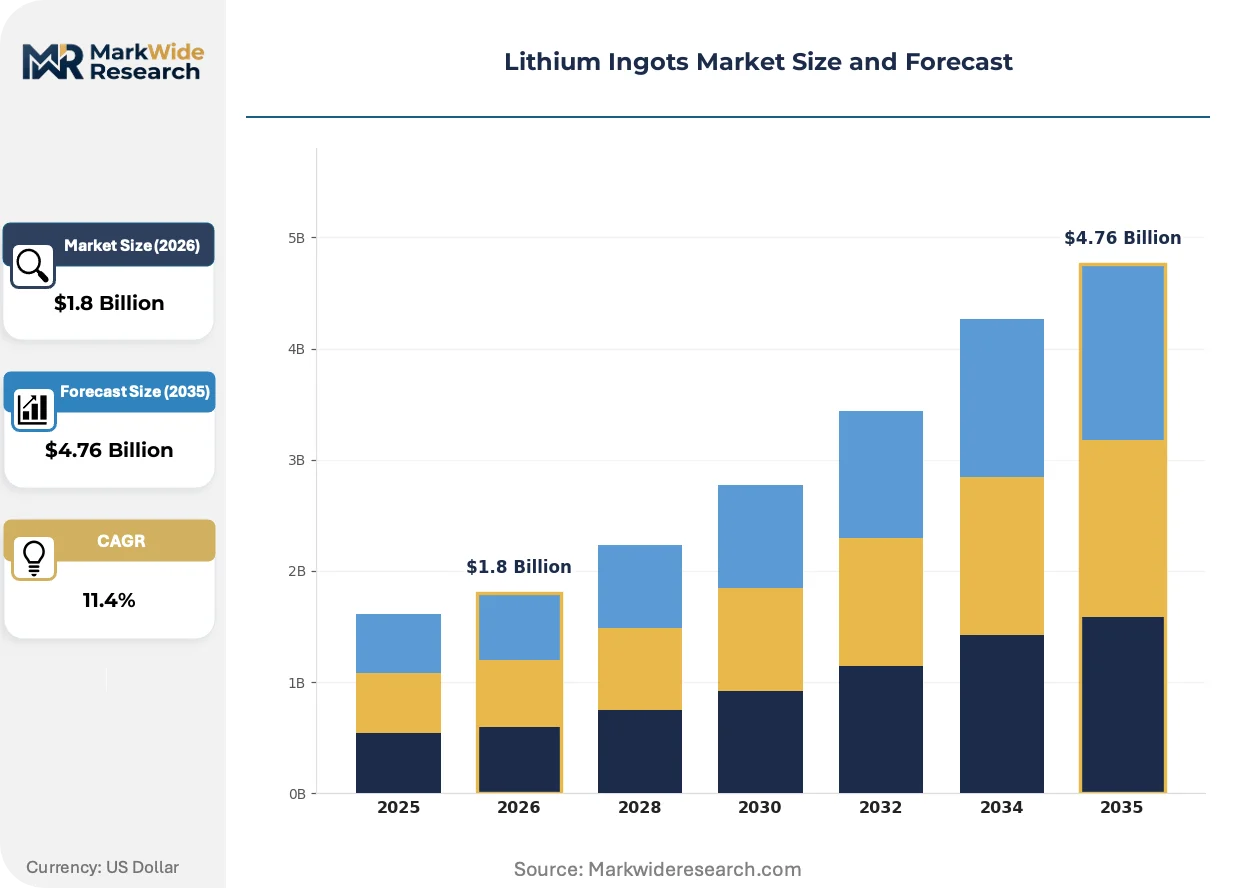
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Spherical, Sheet, Rod End User: Consumer Electronics, Automotive Batteries, Aerospace, Power Storage Purity Grade: Standard, High-Purity, Ultra-High Purity, Technical Grade Application: Batteries, Alloy Production, Ceramics, Lubricants |
| Companies Covered | Ganfeng Lithium Group Co. Ltd., Albemarle Corporation, Tianqi Lithium Inc., Chengxin Lithium Group Co. Ltd., Rio Tinto, Techtone Inorganic Co. Ltd., CNNC Jianzhong Nuclear Fuel Co. Ltd., SQM, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ingots Market Evolving Landscape
Process intensification and regulatory digitization are compressing production cycles while fragmenting procurement authority across sustainability, engineering, and finance functions.
Advanced electrolysis cell designs with segmented electrode configurations are modularizing ingot production scale. Battery cell manufacturers are adopting these systems for captive 500-tonne annual capacity modules rather than centralized megaplants. This distributed architecture is compressing capital deployment timelines and enabling regional supply security strategies.
REACH substance registration requirements for lithium metal are tightening occupational exposure documentation and downstream user communication obligations. The European Chemicals Agency's 2023 update to Annex XVII restrictions is forcing non-EU ingot exporters to establish EU-based only representatives for compliance. High-purity ingot shipments to European battery gigafactories now require full supply chain substance tracking.
Long-term offtake contracting is displacing spot market purchasing for battery-grade material. Tier-one cell manufacturers are securing 5-7 year supply agreements with fixed-volume, indexed-price structures that transfer price risk to refiners. This preference for contract security over price flexibility is most pronounced in South Korean and Japanese procurement desks, where just-in-time inventory models face strain from ocean freight volatility.
Lithium Ingots Market Segmentation
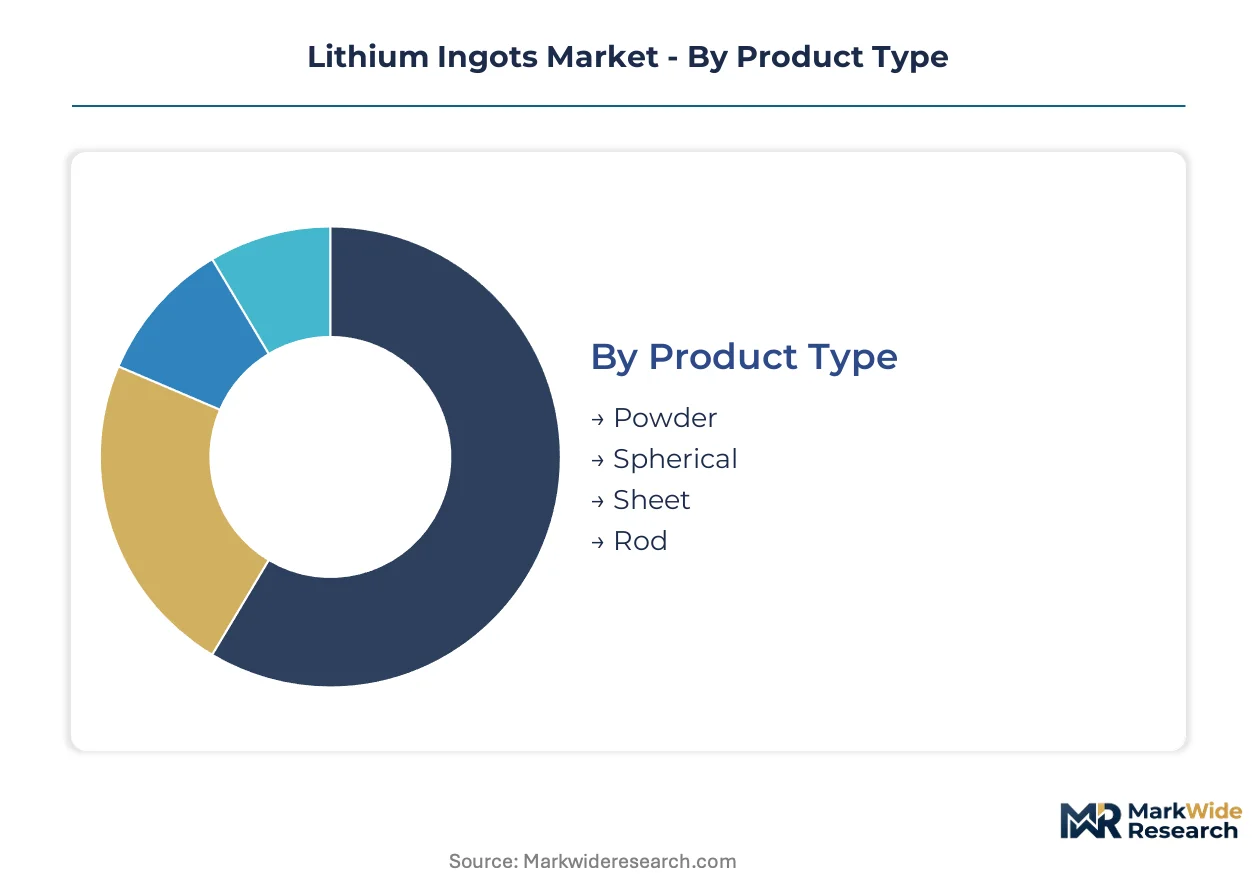
Segmentation in lithium ingots separates commodity-grade material from precision-engineered products commanding certification premiums. Battery manufacturers source across purity tiers while aerospace and alloy producers maintain distinct specification requirements that reshape refinery output allocation.
Product Type:
Physical form selection tracks the customization-standardization spectrum from bulk powder to dimensionally precise rods.
- Powder:Granular lithium metal with high surface area enables rapid dissolution in electrolyte formulations and alloy melts. Demand concentrates at solid-state battery pilot lines in Germany and Japan where powder feedstock feeds thin-film deposition systems. Powder handling complexity limits adoption to facilities with inert atmosphere infrastructure.
- Rod:Extruded cylindrical stock provides consistent feedstock for precision machining and continuous casting operations. Automotive battery manufacturers in South Korea specify rod diameters for automated anode stamping lines. Rod form commands price premiums for dimensional tolerances below 50 microns.
- Spherical:Atomized droplet morphology optimizes packing density in thermal battery assemblies. Military and aerospace contractors in the United States specify spheroidized lithium for reserve power systems.
- Sheet:Rolled foil and plate stock serves lithium-aluminum laminate production for aircraft structural components. Boeing and Airbus Tier-2 suppliers in France and Germany maintain qualified sheet specifications.
Most installed capacity flows through powder and rod forms. Expansion is steepest in spherical material for next-generation thermal batteries.
Purity Grade:
Certification tiers stratify output value from industrial feedstock to semiconductor-grade precision.
- Ultra-High Purity:Sub-10 ppm total trace metal content enables lithium-metal anode integration in solid-state prototypes. Toyota and QuantumScape development programs in California and Japan qualify only ingots with sodium, potassium, and iron each below 2 ppm. Ultra-high purity commands 3-4x pricing multiples over standard material.
- High-Purity:99.9% lithium content with controlled calcium and magnesium levels satisfies NMPA GB/T 26008 battery-grade specifications. CATL and BYD cell lines in Jiangxi and Sichuan provinces source high-purity ingots for cylindrical and prismatic cell formats. High-purity represents the volume anchor for automotive battery procurement.
- Standard:99.5% minimum lithium content serves industrial alloy production and chemical synthesis. Aluminum smelters in Russia and Canada incorporate standard-grade lithium for grain refinement in aerospace plate.
- Technical Grade:Unspecified trace metal tolerances acceptable for metallurgical reducing agents and polymerization catalysts. Chemical processors in India purchase technical grade for pharmaceutical intermediate production.
High-purity ingots absorb the majority of refinery throughput. Ultra-high purity is climbing fastest as solid-state timelines compress.
End User:
Customer concentration varies from fragmented industrial buyers to consolidated automotive procurement desks.
- Automotive Batteries:Cell manufacturers specify ingot purity and form factor against cell chemistry requirements. Tesla's Nevada gigafactory and LG Energy Solution's Michigan plant maintain qualified supplier lists with annual volume commitments exceeding 500 tonnes.
- Power Storage:Grid-scale lithium-metal prototypes for long-duration storage drive emerging demand. Form Energy and ESS Inc. development programs in Massachusetts and Oregon evaluate ingot specifications for multi-day discharge systems.
- Consumer Electronics:Thermal battery producers for smartphones and laptops require precision-cut lithium strips. Panasonic's Japanese facilities source ingots for primary cell assembly in medical and military devices.
- Aerospace:Lockheed Martin and Northrop Grumman suppliers specify lithium-aluminum alloy feedstock for satellite bus structures. Ingots for aerospace applications require full material pedigree documentation.
Automotive battery procurement dominates current volume. Power storage is gaining share fastest as grid-scale prototypes advance.
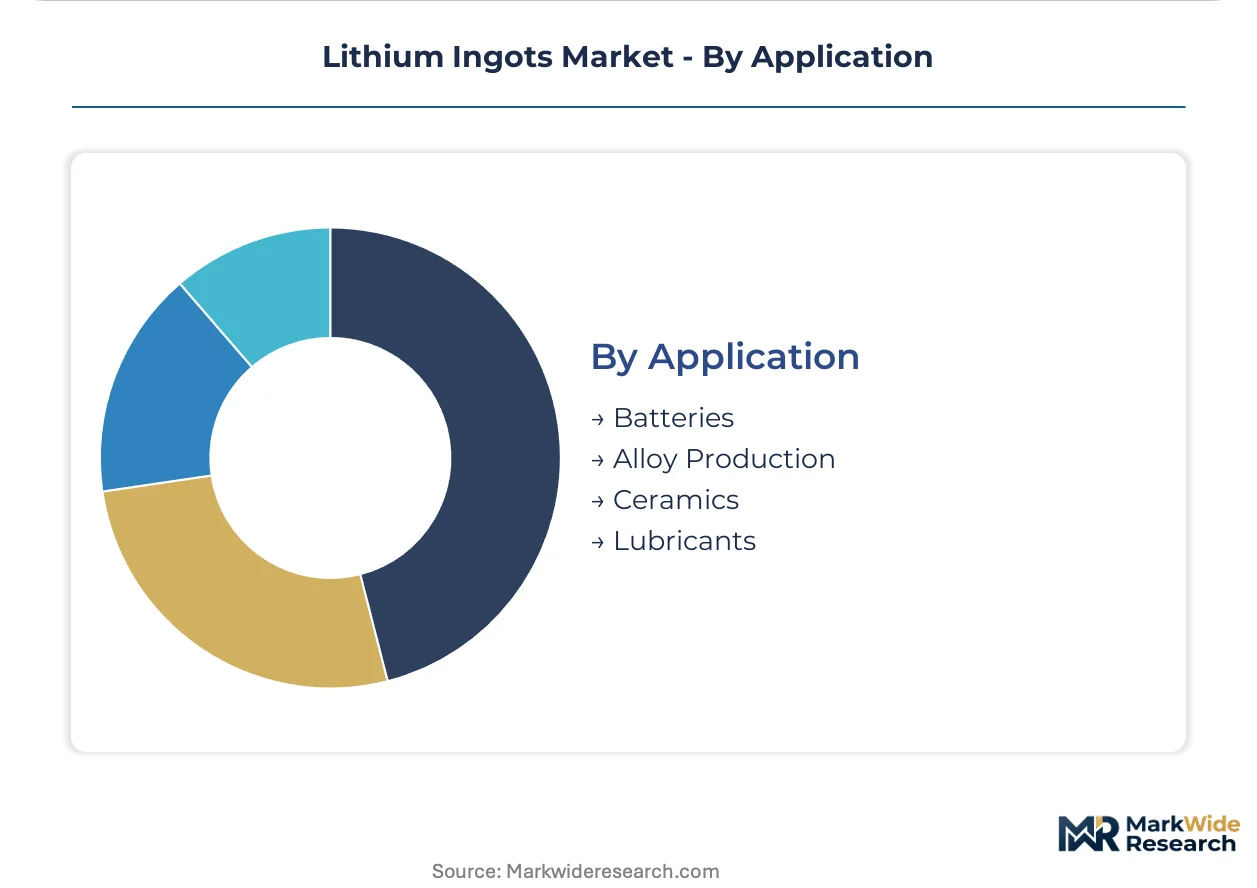
Application:
Downstream use cases span electrochemical systems to metallurgical and ceramic processes with divergent specification requirements.
- Batteries:Primary lithium-metal cells and next-generation rechargeable anodes consume the majority of high-purity output. Solid-state developers in Germany and the United States specify ingot morphology for thin-film lithium deposition.
- Alloy Production:Lithium additions to aluminum and magnesium alloys reduce density while maintaining strength. Airbus A350 wing stringers incorporate lithium-aluminum alloys requiring certified ingot traceability.
- Ceramics:Lithium carbonate and oxide precursors for glass-ceramic cooktops and dental materials originate from technical-grade ingot oxidation. Corning's Kentucky facilities process lithium for glass-ceramic formulations.
- Lubricants:Lithium soap greases for high-temperature bearing applications use lithium hydroxide derived from ingot feedstock. SKF and Timken lubricant divisions specify contaminant limits for grease-grade lithium.
Battery applications command the largest share of high-purity output. Alloy production maintains the steepest expansion trajectory outside electrochemical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium ingot production originated in the Atacama Desert brine operations of Chile during the mid-20th century, establishing the foundational extraction methods that Chinese and Australian processors later scaled to battery-grade purity standards.
China
Domestic EV manufacturers BYD and CATL drive ingot consumption exceeding 500,000 tonnes annually. SAMR enforces GB/T 26008 purity certification that blocks non-compliant imports. Ganfeng Lithium and Tianqi Lithium anchor integrated supply chains across Jiangxi and Sichuan provinces.
United States
Tesla's Nevada gigafactory and emerging solid-state developers in California generate concentrated demand for ultra-high purity material. The IRA's domestic content credits redirect procurement toward North American refining capacity. Albemarle Corporation operates extraction and processing assets in North Carolina.
Germany
Automotive OEMs BMW and Volkswagen specify battery-grade ingots for European cell manufacturing. ECHA's REACH substance registration mandates full supply chain documentation for lithium metal imports. BASF and Merck KGaA maintain qualified supplier relationships for pilot solid-state programs.
Chile
Atacama brine operations supply feedstock to global refiners despite CORFO production quota constraints. Export licensing delays create supply uncertainty for non-integrated processors. SQM and Albemarle Corporation dominate licensed extraction zones.
Australia
Spodumene concentrate from Western Australian hard rock mines feeds Chinese and domestic refiners. Mining output volatility transmits cost instability downstream to ingot producers. Tianqi Lithium Inc. operates concentration facilities in the Greenbushes and Pilbara regions.
Lithium Ingots Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with ultra-high purity specialists commanding 3-4x pricing multiples over standard-grade refiners. The vendor base concentrates around integrated brine-to-ingot operators and hard rock concentrators with downstream partnerships. Three archetypes dominate: vertically integrated majors with captive feedstock, purity-specialized refiners serving solid-state R&D programs, and regional processors dependent on spot concentrate markets. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with Tier-one cell manufacturers locking in 5-7 year supply agreements.
Among integrated majors, Ganfeng Lithium Group Co. Ltd. and Tianqi Lithium Inc. exemplify the Chinese archetype of spodumene concentration married to downstream refining partnerships. Albemarle Corporation occupies a position representing the Western vertically integrated model with Chilean brine assets and North American processing infrastructure. SQM anchors the South American feedstock-specialist tier despite regulatory constraints on export licensing.
| Leading Market Players |
|---|
| Ganfeng Lithium Group Co. Ltd. |
| Albemarle Corporation |
| Tianqi Lithium Inc. |
| Chengxin Lithium Group Co. Ltd. |
| Rio Tinto |
| Techtone Inorganic Co. Ltd. |
| CNNC Jianzhong Nuclear Fuel Co. Ltd. |
| SQM |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Tier-one automotive battery manufacturers concentrate procurement authority among fewer than twenty qualified suppliers globally, creating contract-based long-term offtake structures that transfer price risk to refiners while securing volume certainty for cell producers.
Pricing Analysis
Long-term offtake contracting with fixed-volume, indexed-price structures dominates procurement between refiners and automotive cell manufacturers. Three-tier pricing stratifies across ultra-high purity, high-purity, and standard grades, with certification under China's GB/T 26008 and the EU Battery Regulation commanding substantial premiums. Pricing pressure stems from sodium-ion substitution threats in grid storage segments, where CATL and BYD commercialize alternatives. Power storage buyers exhibit highest price sensitivity, while solid-state R&D programs show lowest sensitivity due to trace-metal tolerance requirements below 10 ppm.
Supply Chain Analysis
Ocean freight volatility and specialized hazmat handling requirements add substantial landed cost differentials between Chilean brine sources and Chinese processing corridors. Supply concentrates in Chile, China, and Australia, with Atacama brine, Sichuan-Jiangxi refining infrastructure, and Western Australian spodumene concentration feeding global output. Raw material dependencies center on lithium chloride feedstock, molten salt electrolysis chemicals, and inert atmosphere packaging systems. Single-source vulnerability runs through Chilean CORFO export licensing delays. Distribution feeds through qualified supplier lists maintained by cell manufacturers in South Korea, Japan, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through ultra-high purity grade premiums as solid-state battery timelines compress, with cost-down drivers emerging from direct lithium extraction technologies reducing brine processing energy intensity.
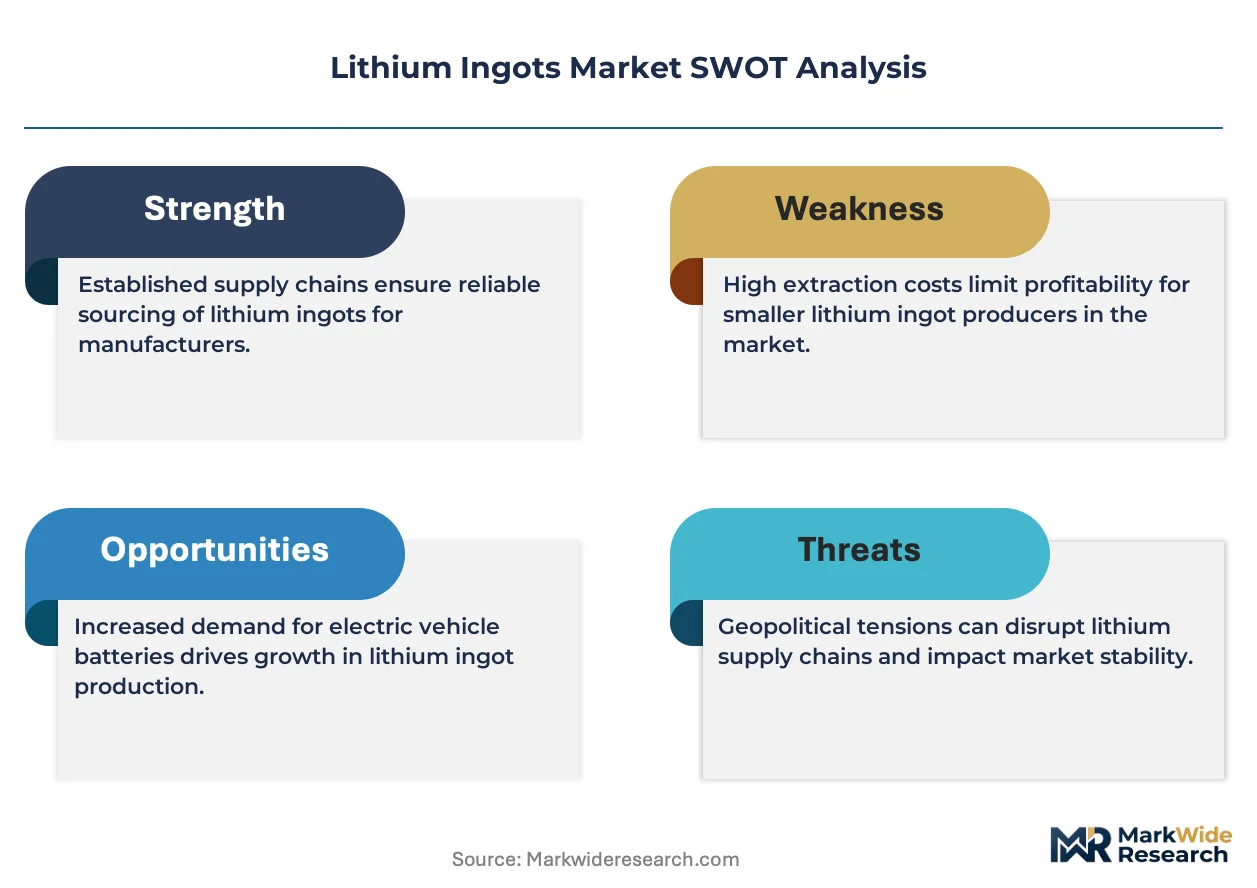
For Market Incumbents: Deploy captive feedstock integration to secure spodumene concentrate offtake from Western Australian mines or Atacama brine quotas under CORFO licenses. Sodium-ion battery substitution from CATL and BYD threatens lithium ingot demand in price-sensitive stationary storage segments. Incumbents should lock in 5-7 year supply agreements with South Korean and Japanese procurement desks before new entrants clear SAMR certification timelines. For New Entrants and Emerging Players: Launch via tolling arrangements with established Chinese refiners lacking GB/T 26008 certification capacity, bypassing 4-6 month vendor qualification delays. North American power storage developers represent the most penetrable segment, with Form Energy and ESS Inc. evaluating lithium-metal prototypes for multi-day discharge systems. Target direct lithium extraction partnerships in Utah and California to establish feedstock differentiation without Chilean licensing exposure. For Investors and Strategic Acquirers: Battery cell manufacturers are the most active acquirer in this space, seeking upstream control over ingot supply to satisfy IRA domestic content requirements. Long-term viability hinges on positioning within solid-state battery supply chains as lithium-metal anode prototypes advance toward pilot manufacturing. Watch for Toyota and QuantumScape development program announcements as inflection indicators for ultra-high purity demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Albemarle's Chilean operations demonstrate captive feedstock security against CORFO quota volatility. |
| GB/T 26008 Certification Investment | SAMR compliance opens qualified supplier access to CATL and BYD cell manufacturing lines. |
| Direct Lithium Extraction Partnership | Selective sorbent technologies in Utah and California bypass evaporation pond constraints. |
| Ultra-High Purity Capacity Addition | Sub-10 ppm trace metal tolerance commands 3-4x pricing multiples from solid-state developers. |
| Long-Term Offtake Contracting | LG Energy Solution and Tesla gigafactories anchor volume commitments exceeding 500 tonnes annually. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolysis technicians, SAMR certification officers, Tier 1 cell manufacturer procurement leads, and molten salt cell equipment suppliers with secondary validation from customs trade databases, SEC 10-K filings, and ECHA REACH substance registration records. Bottom-up refinery capacity modeling and top-down automotive battery demand projections were triangulated against intermediate validation points.
Historical reference periods spanning brine extraction evolution, Chinese processing corridor development, and solid-state battery R&D acceleration anchored forecast assumptions across the projection horizon. Segmentation dimensions modeled include purity grade tier, physical form factor, end-use application, and regional regulatory cluster. CAGRs were derived from slope analysis of installed capacity expansion against qualified supplier list growth, with inputs from spodumene concentrate price indices and CORFO production quota announcements.
Several conditions sit outside the modeled scope, including unannounced sodium-ion battery commercialization timelines, CORFO license renegotiation outcomes, and breakthrough direct lithium extraction scale-up achievements. Forecasts reflect documented assumptions about solid-state battery pilot manufacturing progression and EU Battery Regulation enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Ilmenite Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Selenium Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Chromite Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Zellerite Market