
 Pneumatic Caster Market | 2026-2036
Pneumatic Caster Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Caster Market Analysis
Buyer concentration in the pneumatic caster market is shifting as e-commerce fulfillment networks expand and fragmented third-party logistics providers multiply their equipment orders. Colson Casters leverages its broad distribution network to serve both consolidated retail chains and independent material handling dealers. Blickle Räder+Rollen GmbH u. Co. KG anchors its position through engineering-intensive custom solutions for European industrial OEMs. TENTE International GmbH competes across medical and warehouse segments with modular platform designs that reduce customer inventory complexity.
A pneumatic caster is a wheel assembly that uses an air-filled rubber or synthetic tire mounted on a metal rim and yoke, designed to absorb shock and vibration while rolling across irregular surfaces at load capacities ranging from light-duty furniture to extra heavy-duty industrial transport. Its primary purpose is to protect both cargo and flooring while enabling maneuverability in environments where rigid wheels would transmit damaging impact forces. Swivel and locking configurations dominate specification sheets for medical equipment and industrial applications where directional control and safety braking are mandatory. Heavy-duty and extra heavy-duty load capacity tiers capture the strongest margin pools as mining, aerospace, and defense contractors specify certified components with extended service intervals.
ISO standards for caster testing and load rating provide the baseline technical framework that manufacturers must meet for cross-border equipment sales, while OSHA workplace safety regulations in the United States mandate brake-equipped casters on mobile platforms exceeding defined weight thresholds. The EU Machinery Directive and CE marking requirements enforce minimum performance criteria for casters integrated into exported European equipment, creating compliance barriers for uncertified suppliers. Stakeholders must monitor how evolving sustainability mandates from ECHA and REACH affect rubber compound formulations and supplier qualification timelines.
Market Dynamics
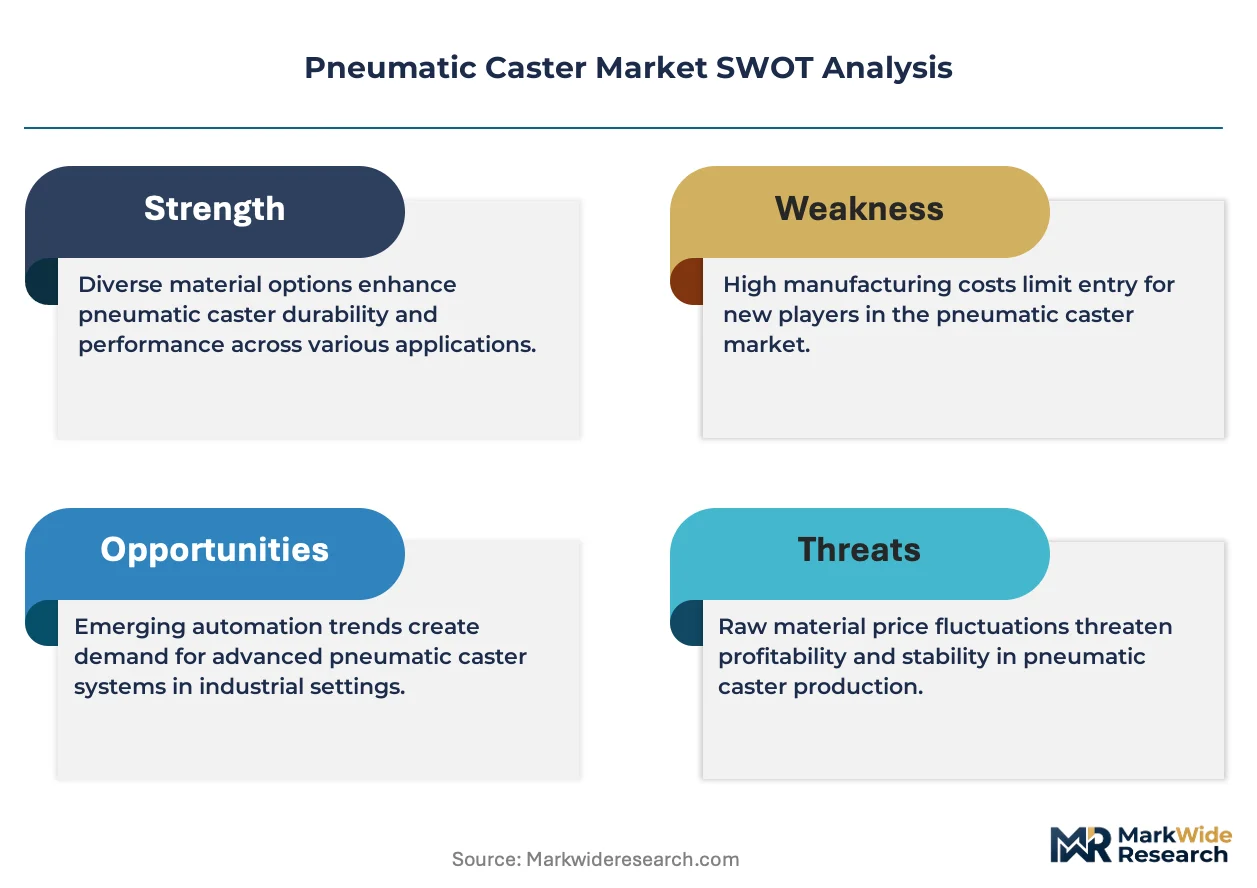
The pneumatic caster market is reconfiguring around e-commerce fulfillment density, where warehouse operators demand vibration-dampening mobility systems capable of protecting sensitive electronics during high-velocity sortation cycles.
Growth Catalysts
- REACH chemical compliance:European rubber compound reformulation is accelerating adoption of advanced polyurethane blends that extend tire service life while meeting ECHA substance restrictions.
- Medical equipment mobility:Hospital bed and imaging system OEMs specify precision swivel casters with central locking mechanisms to satisfy Joint Commission patient safety protocols.
- Automated guided vehicle integration:Casters engineered for continuous duty cycles are penetrating manufacturing floors as AGV fleets expand in automotive assembly plants.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly to tire production costs, compressing margins for standard-duty product lines.
- Steel tariff cascades:Rim and yoke fabrication faces input cost pressure from trade policy friction affecting Chinese and Turkish mill suppliers.
- Polyurethane formulation patents:Proprietary load-bearing compound recipes held by specialized chemical suppliers limit backward integration options for caster assemblers.
Strategic Opportunities
- India warehouse infrastructure:Third-party logistics operators in Mumbai and Bangalore corridors are retrofitting manual handling equipment with pneumatic casters to reduce floor damage claims.
- Renewable energy maintenance:Wind turbine service platforms require corrosion-resistant caster assemblies rated for offshore salt exposure and extreme temperature cycling.
- CE-MDR medical device alignment:Casters integrated into patient transport equipment can capture premium positioning through notified body certification for EU hospital procurement.
Industry Challenges
- ISO 22878 test protocol complexity:Accelerated life verification for dynamic load ratings demands capital-intensive rig investment that smaller foundries struggle to justify.
- Legacy fleet retrofit coordination:Industrial maintenance teams face downtime scheduling conflicts when upgrading caster hardware across multi-site distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Caster Market |
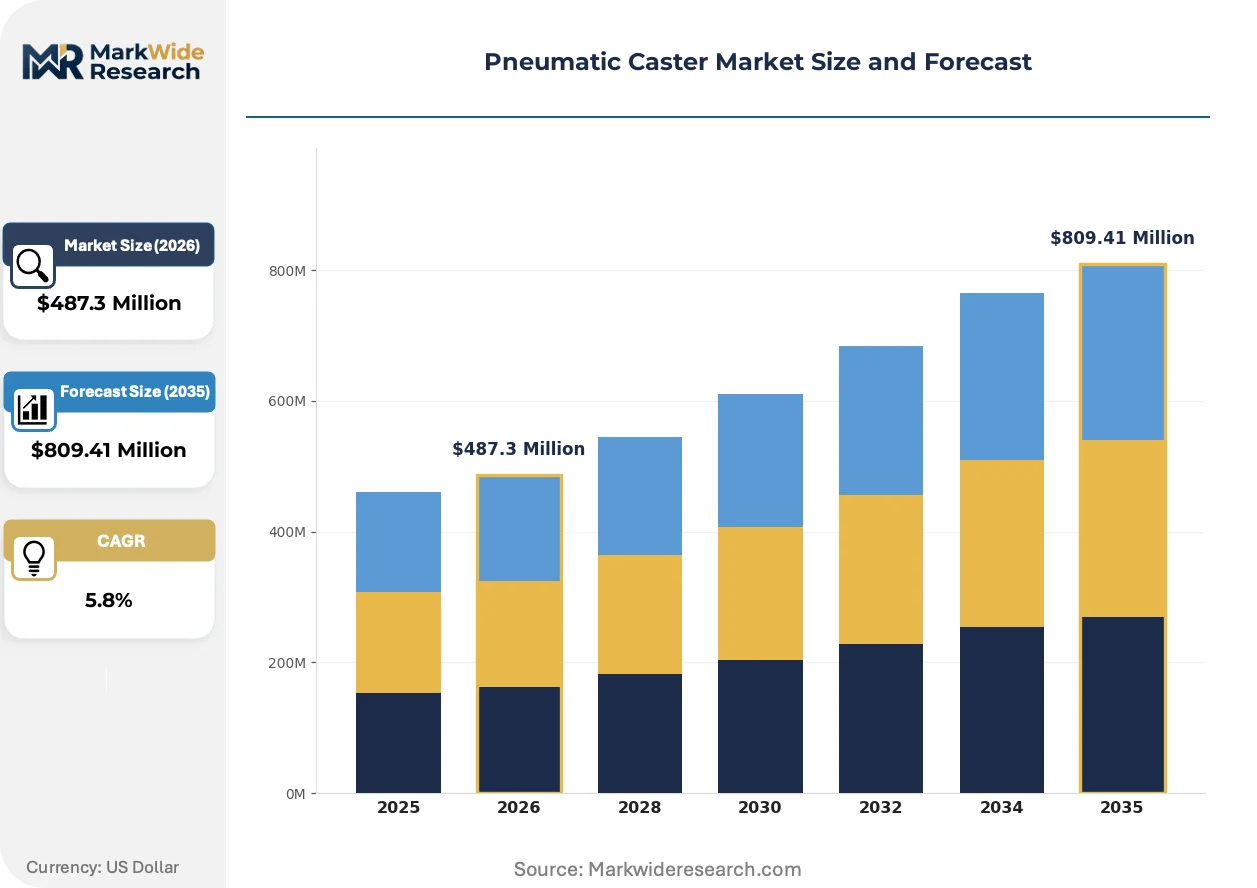
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
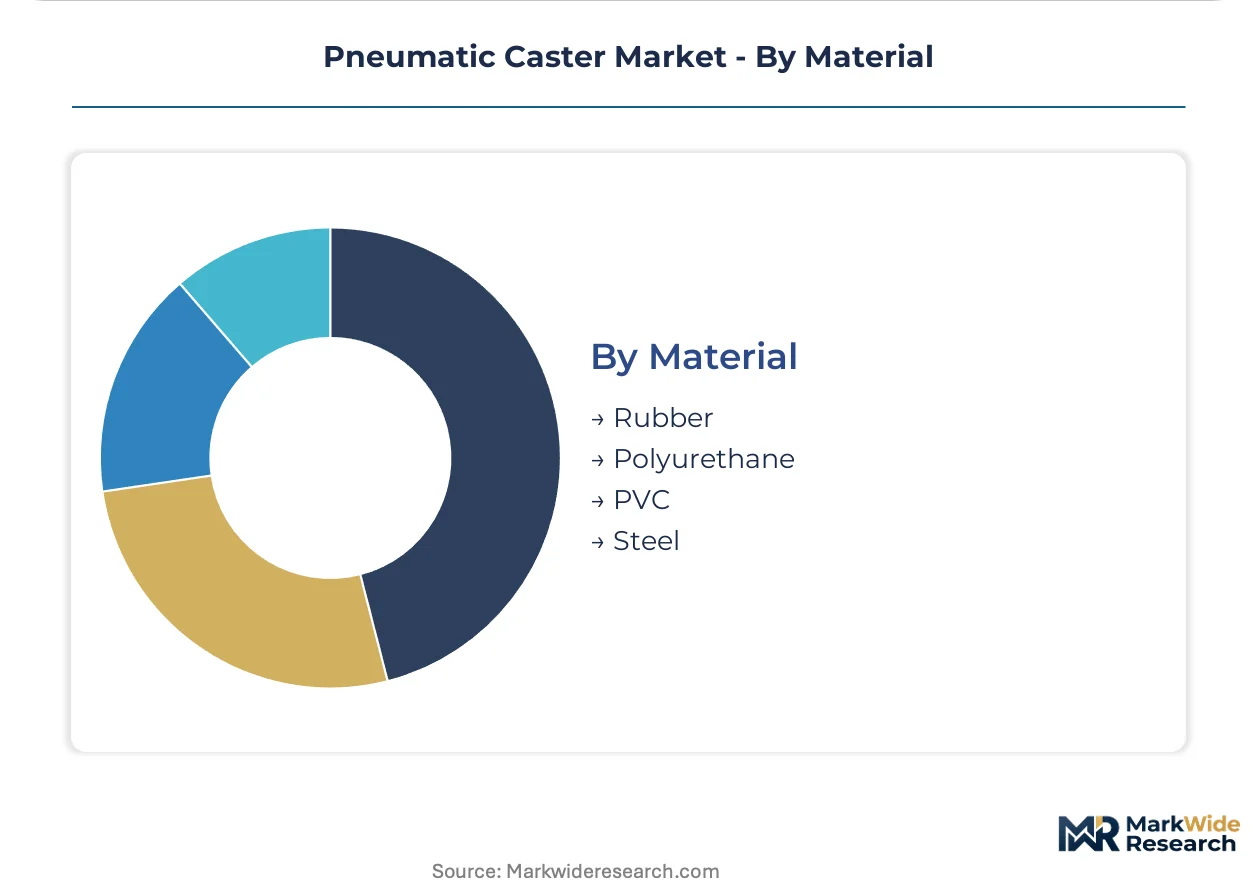
| Segmentation | Type: Swivel, Rigid, Locking, Braking Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty Application: Industrial Equipment, Medical Equipment, Furniture, Warehouse Applications Material: Rubber, Polyurethane, PVC, Steel |
| Companies Covered | Colson Casters, Blickle Räder+Rollen GmbH u. Co. KG, TENTE International GmbH, Hamilton Caster & Mfg. Co., Caster Concepts Inc., RWM Casters, Jarvis Casters, Albion Industries, Flywheel Caster Manufacturing Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Caster Market Emerging Trajectories
Material science convergence and procurement digitization are compressing specification cycles while elevating performance verification standards across industrial mobility equipment.
Smart caster assemblies embedding torque sensors and RFID tracking chips are unifying predictive maintenance protocols with real-time fleet management systems. Mining and aerospace ground support equipment operators in Germany and Australia pilot these connected units to schedule replacement before fatigue failure. This unifying architecture collapses the traditional separation between hardware procurement and asset management software, forcing caster manufacturers to develop firmware competencies or cede margin to systems integrators.
REACH authorization requirements for polycyclic aromatic hydrocarbons in rubber processing are compelling compounders to validate alternative curing agents through ECHA-recognized laboratories. Tire manufacturers serving European OEM export markets must maintain dual formulation inventories until 2028 transition deadlines expire. Medical caster suppliers face the steepest compliance burden, as biocompatibility testing overlays chemical safety documentation for CE-MDR technical files.
Consolidated retail chains and parcel carriers are compressing supplier panels to single-source framework agreements with multi-year volume commitments. Amazon Robotics and DHL Supply Chain operations in the United States now mandate caster interchangeability across equipment generations to simplify spare parts logistics. This concentration pattern marginalizes independent distributors and rewards manufacturers with sufficient capacity to absorb demand spikes during peak fulfillment seasons.
Pneumatic Caster Market Segmentation
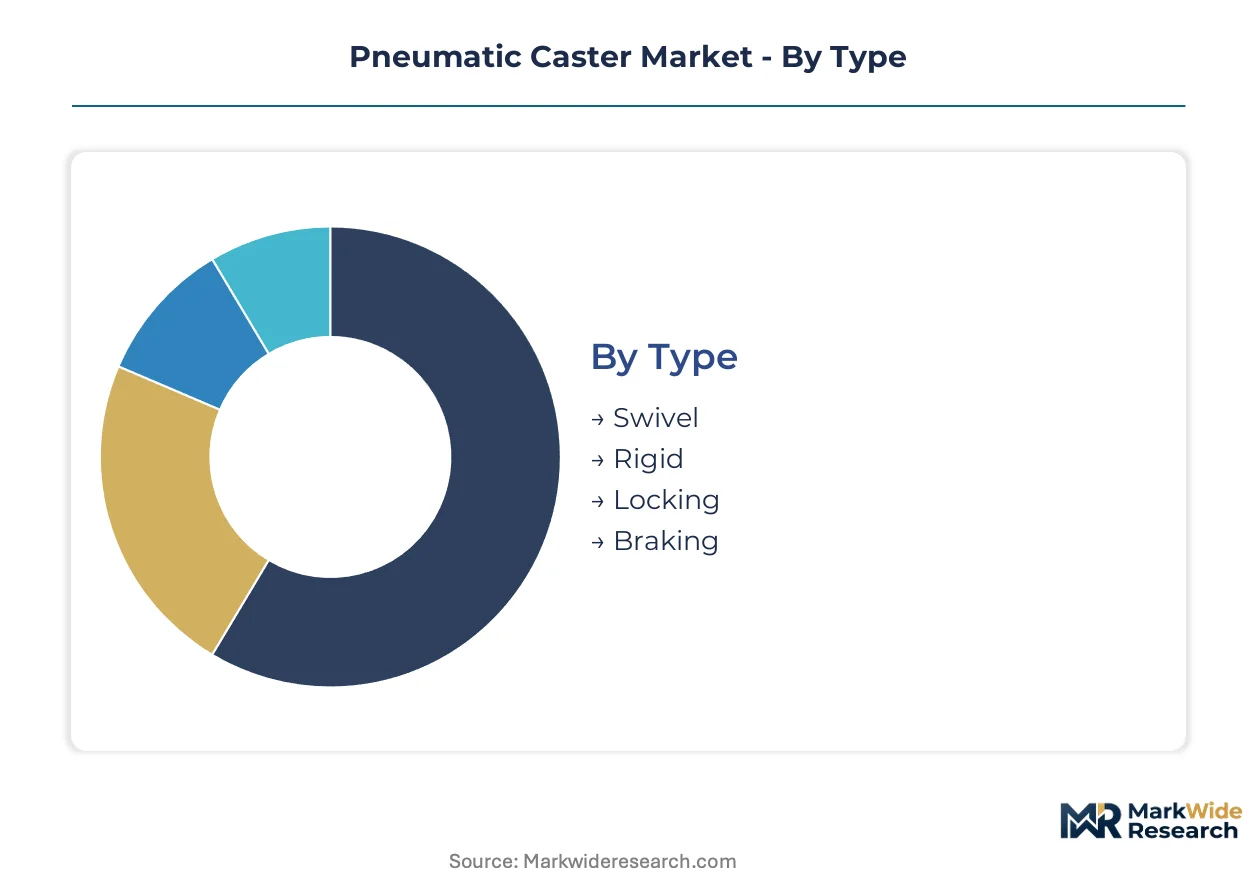
Pneumatic caster specification splits sharply between cost-optimized commodity tiers and performance-driven premium configurations. Procurement teams in warehouse and medical verticals weight load capacity and material composition differently, creating distinct margin pools across segment intersections.
Type:
Volume concentrates in standard swivel and rigid configurations, while premium pricing accrues to safety-critical braking variants.
- Swivel:360-degree rotation capability enables maneuverability in tight warehouse aisles and hospital corridors. Amazon Robotics fulfillment centers in the United States specify precision-bearing swivel casters for AGV fleets navigating high-density storage racks.
- Locking:Central or directional locking mechanisms satisfy OSHA mobile platform regulations and Joint Commission patient safety protocols. Medical equipment OEMs in Germany pay 40-60% premiums for positive-lock casters certified to CE-MDR requirements.
- Rigid:Fixed-direction wheels provide directional stability on long transport runs across distribution center floors.
- Braking:Foot-activated or wheel-contact brake systems integrate with automated safety interlocks on industrial carts.
Today's leader: Swivel. Tomorrow's challenger: Locking.
Load Capacity:
Application severity determines specification tier, with mining and aerospace contractors driving extra heavy-duty adoption.
- Heavy Duty:Rated for 1,000-2,500 lb loads, these casters use reinforced yoke construction and high-ply pneumatic tires. Wind turbine maintenance platforms in Denmark and Germany specify corrosion-resistant heavy-duty casters for offshore salt exposure.
- Extra Heavy Duty:Exceeding 2,500 lb ratings with forged steel components and dual-wheel configurations. Mining equipment manufacturers in Australia and Canada require certified casters with documented dynamic load testing per ISO 22878 protocols.
- Light Duty:Furniture and retail display applications using single-ply tires and stamped steel construction.
- Medium Duty:Commercial equipment and institutional carts balancing cost with moderate load requirements.
Heavy Duty commands current procurement volume. Extra Heavy Duty captures the steepest expansion trajectory as resource extraction automation intensifies.
Application:
End-use diversification spreads risk across cyclical industrial investment and stable healthcare replacement demand.
- Industrial Equipment:Manufacturing carts, assembly platforms, and material handling systems in automotive plants. BMW and Volkswagen assembly lines in Germany specify casters rated for continuous duty cycles exceeding 16 hours daily operation.
- Warehouse Applications:E-commerce fulfillment networks drive specification for vibration-dampening casters protecting electronics during high-velocity sortation. DHL Supply Chain operations in the United States mandate interchangeable caster designs across equipment generations.
- Medical Equipment:Hospital beds, imaging systems, and patient transport devices requiring biocompatibility documentation.
- Furniture:Office and hospitality seating with aesthetic and mobility requirements.
Industrial Equipment anchors manufacturer backlogs. Warehouse Applications are gaining share fastest as third-party logistics expands in India and Southeast Asia.
Material:
Compound selection balances floor protection, chemical resistance, and REACH compliance timelines.
- Polyurethane:Load-bearing elastomer with superior abrasion resistance and non-marking properties. ECHA authorization requirements for polycyclic aromatic hydrocarbons are compelling European compounders to validate alternative curing agents through recognized laboratories.
- Rubber:Natural and synthetic compounds providing maximum shock absorption on uneven surfaces. Southeast Asian supply disruptions transmit directly to tire production costs, compressing margins for standard-duty lines.
- PVC:Cost-competitive option for light-duty indoor applications with limited chemical exposure.
- Steel:Solid wheel construction for extreme load conditions where pneumatic cushioning is unnecessary.
Polyurethane leads specification for premium segments. Rubber retains cost-sensitive volume despite volatility exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEM demand for certified heavy-duty casters contrasts with India's warehouse retrofit surge, illustrating how mature manufacturing economies and emerging logistics markets drive divergent specification priorities.
United States
Amazon Robotics fulfillment centers and DHL Supply Chain operations mandate interchangeable caster designs across equipment generations. OSHA workplace safety regulations require brake-equipped casters on mobile platforms exceeding defined weight thresholds. The Midwest industrial corridor spanning Ohio and Michigan anchors heavy-duty procurement for automotive assembly automation.
Germany
BMW and Volkswagen assembly lines specify casters rated for continuous duty cycles exceeding sixteen hours daily operation. The EU Machinery Directive and CE marking requirements enforce minimum performance criteria for casters integrated into exported European equipment. Bavaria's precision engineering cluster drives demand for ISO 22878-certified components with documented dynamic load testing.
China
E-commerce logistics infrastructure expansion in Yangtze River Delta and Pearl River Delta corridors accelerates replacement cycles for vibration-dampening mobility systems. GB standards and MIIT industrial automation directives shape procurement specifications for manufacturing floor equipment. Shenzhen and Shanghai warehouse operators prioritize floor protection features to reduce damage claims in high-density fulfillment environments.
India
Third-party logistics operators in Mumbai and Bangalore corridors retrofit manual handling equipment with pneumatic casters to reduce floor damage claims. The PLI scheme for logistics infrastructure incentivizes automation investments in material handling systems. Maharashtra and Karnataka industrial zones concentrate demand from fragmented logistics providers multiplying equipment orders.
Australia
Mining equipment manufacturers require certified casters with extended service intervals for resource extraction automation. The country's national workplace safety regulator mandates performance verification for mobile platforms in hazardous environments. Western Australia's Pilbara region drives extra heavy-duty adoption as autonomous haulage systems expand.
Pneumatic Caster Market Vendor Landscape
German producers anchor one tier; United States specialists hold another, creating a bifurcated structure where engineering-intensive custom solutions compete against scale-driven standardized lines. The vendor base splits between consolidated manufacturers with captive distribution networks and regional fabricators serving independent dealers. Three archetypes dominate: broad-line distributors, application-specific engineers, and commodity assemblers. Competitive moves concentrate on multi-year framework agreements with consolidated retail chains and strategic partnerships with automated guided vehicle OEMs.
Within the engineering-intensive tier, Blickle Räder+Rollen GmbH u. Co. KG and TENTE International GmbH represent German precision manufacturers serving European industrial OEMs with modular platform designs. Colson Casters exemplifies the broad-line distribution archetype, leveraging extensive networks to serve both consolidated retail chains and independent material handling dealers across North American markets. Hamilton Caster & Mfg. Co. occupies a position among United States-based fabricators specializing in heavy-duty and extra heavy-duty configurations for mining and aerospace ground support applications.
| Leading Market Players |
|---|
| Colson Casters |
| Blickle Räder+Rollen GmbH u. Co. KG |
| TENTE International GmbH |
| Hamilton Caster & Mfg. Co. |
| Caster Concepts Inc. |
| RWM Casters |
| Jarvis Casters |
| Albion Industries |
| Flywheel Caster Manufacturing Ltd |
| Others |
Supply Flow & Price Mechanics
Polyurethane formulation patent concentration among specialized chemical suppliers simultaneously elevates compound licensing costs and constrains backward integration options for caster assemblers seeking margin control. This technological dependency creates asymmetric pricing power where raw material innovators capture value upstream while finished goods manufacturers absorb volatility.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-duty pneumatic casters as regional fabricators expand stamped steel yoke production. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22878-certified heavy-duty units from uncertified commodity imports. Cost compression in light-duty tiers is intensifying because Southeast Asian natural rubber supply disruptions transmit directly to tire production economics. Third-party logistics operators in India exhibit the highest price sensitivity, while German automotive OEMs prioritize certification tier over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian natural rubber processors who feed tire compounders serving cost-optimized product lines. Component fabrication concentrates in China, Germany, and the United States, where rim and yoke manufacturing draws from steel mill networks exposed to trade policy friction. Supply chain risk centers on tariff exposure affecting Turkish and Chinese steel suppliers. Distribution runs through captive networks of broad-line manufacturers and independent material handling dealers serving fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumatic caster market functions as a stable compounder anchored by replacement cycle predictability in healthcare and logistics infrastructure. E-commerce fulfillment density sustains steady equipment refresh demand across warehouse networks.
For Market Incumbents: Deepen captive supply of polyurethane compounds through exclusive licensing arrangements with ECHA-recognized laboratories to offset REACH compliance cost inflation. Expand ISO 22878 testing capacity in Bavaria and Ohio to defend premium positioning against uncertified Asian imports threatening certified heavy-duty margins.
For New Entrants and Emerging Players: Launch via direct procurement partnerships with Indian third-party logistics operators retrofitting manual handling equipment in Mumbai and Bangalore corridors. Target medical caster segments requiring CE-MDR biocompatibility documentation where incumbent compliance burdens create white-space for specialized entrants.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking captive distribution networks but holding precision engineering capabilities. Five-to-ten year viability favors targets with demonstrated ECHA compound validation and automotive OEM qualification history. Monitor REACH authorization timelines for polycyclic aromatic hydrocarbon alternatives as inflection indicator for compound cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Validation | ECHA-recognized laboratory certification unlocks European medical and automotive OEM procurement channels. |
| AGV Fleet Integration Partnership | Amazon Robotics and DHL Supply Chain mandates for interchangeable caster designs secure multi-year volume commitments. |
| India Distribution Network Expansion | PLI scheme incentives for logistics infrastructure concentrate demand in Maharashtra and Karnataka industrial zones. |
| ISO 22878 Testing Rig Investment | Dynamic load verification capacity differentiates premium heavy-duty offerings in German mining and aerospace procurement. |
| Smart Caster Firmware Development | Torque sensor and RFID integration collapses hardware-software boundaries for predictive maintenance revenue streams. |
Methodological Framework
Bottom-up warehouse and medical equipment modeling reconciled against top-down tire compound and steel rim supply tracking forms the analytical core. Primary interviews with maintenance directors at German automotive plants, biomedical engineers specifying hospital casters, procurement leads at Indian third-party logistics operators, and aftermarket service heads at mining equipment OEMs combined with secondary validation from SEC filings of listed material handling equipment manufacturers, ECHA substance restriction databases, OSHA workplace safety enforcement records, and customs trade data for pneumatic tire imports.
Input-output matrices mapped load capacity tier, caster type configuration, application vertical, and regional regulatory cluster against compound material and manufacturing geography across the projection horizon. CAGRs derived from segment-level replacement cycle analysis and automation penetration curves. Forecast inputs incorporated e-commerce fulfillment square footage expansion trajectories and REACH authorization transition deadlines for rubber processing chemicals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Southeast Asian rubber supply disruption or accelerated steel tariff escalation scenarios. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Low Clearance Loaders Market