
 Immunity Support Ingredients Market | 2026-2036
Immunity Support Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Immunity Support Ingredients Market Insights
Direct-to-consumer e-commerce channels for immunity ingredients is fragmenting as specialized wellness platforms and pharmacy marketplaces multiply entry points. Royal DSM anchors its position through backward integration into fermentation-derived vitamins. Glanbia competes on dairy and plant-protein fortification systems for functional food brands. Herbalife Nutrition controls a global direct-sales network that bypasses traditional retail intermediaries entirely.
Immunity support ingredients comprise bioactive compounds including vitamins, minerals, probiotics, and botanical extracts formulated to modulate immune cell activity and cytokine response, typically standardized to minimum potency thresholds such as colony-forming units for probiotics or percentage marker compounds for herbal extracts. These inputs serve manufacturers of dietary supplements, functional foods, and clinical nutrition products seeking substantiated health claims. Vitamins and probiotics occupy the largest volume positions due to decades of clinical documentation and consumer familiarity. Herbal extracts represent the fastest-growing ingredient type as adaptogenic positioning gains traction in premium formulations. Gummies among form categories are capturing margin pools by converting adult pill-averse users into repeat purchasers.
FDA oversees structure-function claim substantiation under DSHEA while EFSA enforces health claim authorization through centralized scientific assessment, compelling suppliers to invest in human intervention trials. China's SAMR and NMPA impose dual registration requirements for imported functional ingredients, creating compliance bottlenecks for Western suppliers. India's FSSAI and CDSCO are tightening contaminant limits and GMP enforcement for domestic ayurvedic immunity extracts. Stakeholders must monitor evolving substantiation thresholds across jurisdictions to determine whether clinical investment priorities align with regional market access timelines.
Market Dynamics
Clinical substantiation requirements from FDA and EFSA are compressing formulation timelines as manufacturers scramble to generate human intervention trial data before label claims expire. This regulatory tightening is forcing ingredient suppliers to choose between capital-intensive research programs and market exit.
Growth Catalysts
- Fermentation-derived bioactives:Precision fermentation platforms now deliver standardized vitamins at costs competitive with petrochemical synthesis. Functional food brands in Germany and China are accelerating procurement of these inputs.
- DSHEA structure-function pathway:The US regulatory framework permits immune health claims without pre-market authorization when substantiation files remain audit-ready. Dietary supplement manufacturers exploit this efficiency versus EFSA's centralized assessment bottleneck.
- Preventive wellness pivot:Post-pandemic consumer behavior in the United States prioritizes daily immune maintenance over acute symptom response. Gummy and functional beverage formats capture this demand shift.
Market Restraints
- Clinical trial cost inflation:Human intervention studies for EFSA health claim authorization now exceed $2 million per endpoint. Mid-tier botanical extract suppliers lack balance sheet capacity for this investment.
- Dual registration requirements:China's SAMR and NMPA impose parallel safety and functional assessments on imported ingredients. Western suppliers face 18-24 month approval timelines versus domestic competitors.
- Marker compound volatility:Herbal extract potency varies with harvest conditions and geographic origin. Standardization to percentage thresholds requires costly purification steps that erode margin.
Strategic Opportunities
- Direct-to-consumer pharmacy platforms:Specialized wellness marketplaces bypass traditional retail intermediaries. Immunity ingredient brands gain margin control and first-party data access.
- Adaptogenic positioning:Stress-immune axis marketing opens premium pricing for ashwagandha and reishi extracts. Clinical documentation for cortisol-immunoglobulin links remains underdeveloped.
- India PLI scheme:Production-linked incentives for domestic ayurvedic extract manufacturing reduce import dependency. FSSAI-compliant suppliers capture cost advantages for export markets.
Industry Challenges
- Human trial design expertise:Qualified investigators for immune biomarker studies concentrate in academic medical centers. Contract research organizations with relevant capabilities command premium pricing.
- Cross-jurisdictional dossier alignment:FDA, EFSA, and NMPA demand incompatible clinical endpoints. Suppliers must run parallel studies or accept geographic market exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunity Support Ingredients Market |
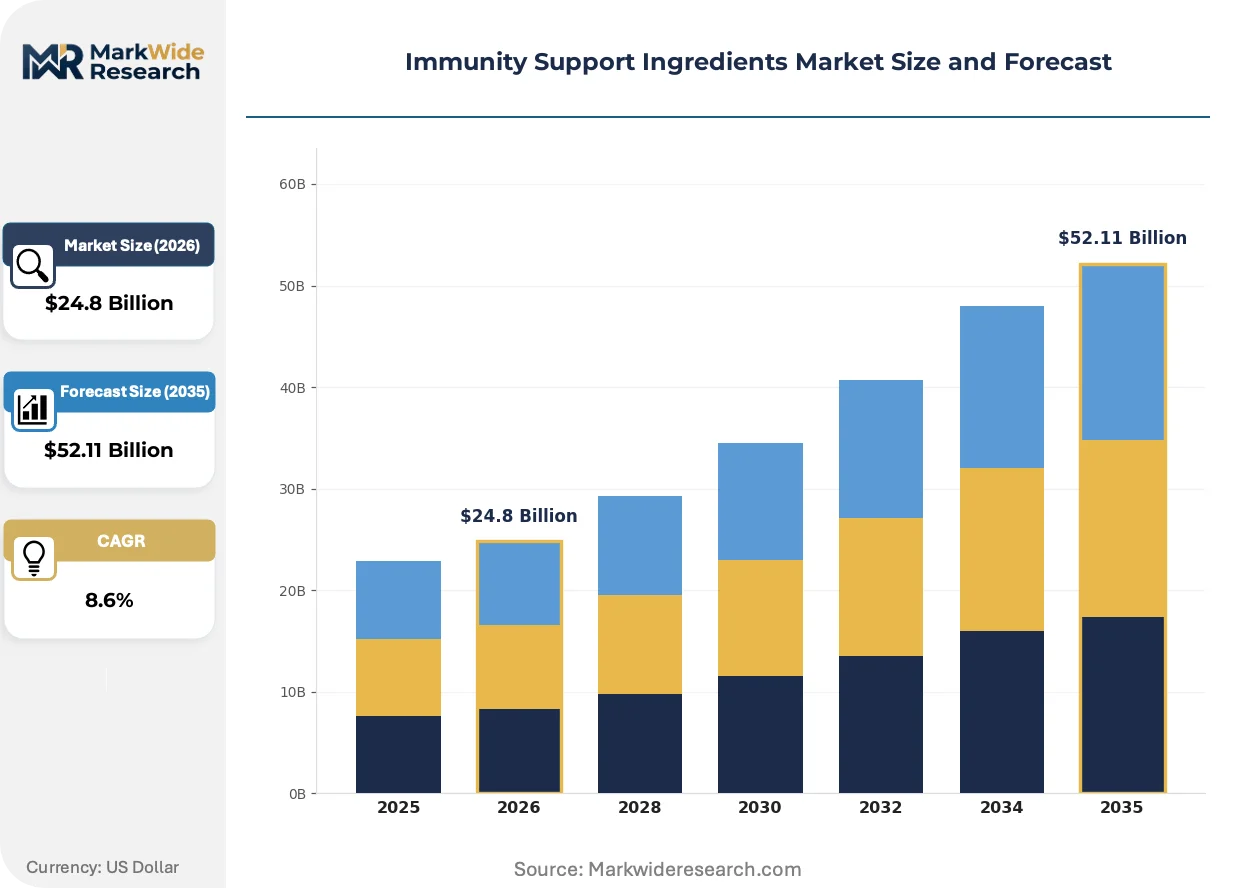
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Vitamins, Minerals, Probiotics, Herbal Extracts Form: Pills, Powders, Liquids, Gummies Application: Dietary Supplements, Functional Foods, Beverages, Nutraceuticals End User: Adults, Seniors, Children, Athletes |
| Companies Covered | Blackmores Limited, Royal DSM, Herbalife Nutrition, USANA Health Sciences, Alticor, Nutramax Laboratories, Glanbia, Bayer AG, BioGaia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunity Support Ingredients Market Trends and Innovations
Bioprocessing advances and regulatory data requirements are compressing traditional ingredient supply models. Manufacturers now compete on clinical evidence depth rather than commodity scale.
Precision fermentation of vitamin C and B-complex compounds is rendering obsolete petrochemical-derived synthetic routes. Functional food brands in Germany and the United States now specify fermentation origin in procurement contracts. This technology shift is compressing margins for legacy chemical manufacturers while rewarding backward-integrated biotechnology firms.
EFSA's 2024 guidance on immune health claim substantiation tightens biomarker acceptance criteria. The regulation now requires cytokine response data from randomized controlled trials rather than observational studies. Botanical extract suppliers targeting European markets face portfolio rationalization or capital-intensive clinical redevelopment.
Specialized wellness platforms disintermediate traditional supplement retail. Consumers in the United States now discover immunity products through algorithmic curation rather than pharmacy shelf browsing. This channel shift concentrates marketing spend on digital acquisition and subscription retention mechanics.
Immunity Support Ingredients Market Segmentation
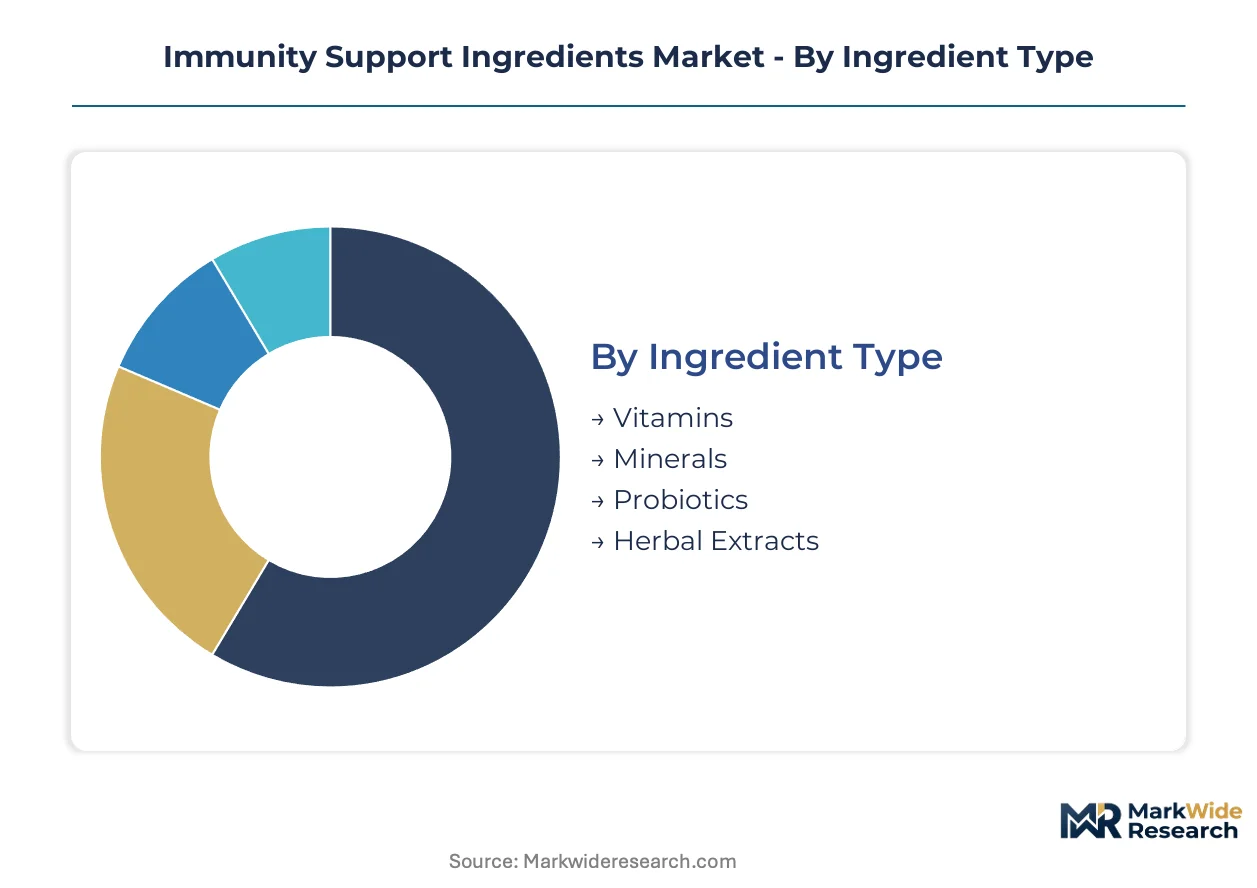
Ingredient suppliers configure production capacity around distinct demand cycles across form factors and user demographics. Procurement patterns vary sharply between clinical nutrition buyers seeking standardized bioactives and functional food brands prioritizing sensory-compatible delivery systems.
Ingredient Type:
Vitamins and probiotics turn inventory fastest due to decades of established supply chains and regulatory familiarity, while herbal extracts face elongated procurement cycles driven by harvest variability and marker compound standardization.
- Vitamins:Fermentation-derived and synthetic water-soluble and fat-soluble compounds standardized to USP or EP monographs. Demand concentrates in Germany and the United States where functional food brands specify fermentation origin in procurement contracts to meet clean-label positioning.
- Probiotics:Live microbial cultures quantified in colony-forming units with strain-specific dossiers for regulatory substantiation. Chinese and US dietary supplement manufacturers drive volume for Lactobacillus and Bifidobacterium strains with documented cytokine modulation.
- Minerals:Chelated and inorganic forms including zinc, selenium, and iron with defined bioavailability thresholds.
- Herbal Extracts:Botanical concentrates standardized to percentage marker compounds including adaptogens and traditional immune tonics.
Vitamins anchor the volume base while herbal extracts gain share at the steepest rate.
Form:
Cost tier stratification separates premium-positioned delivery systems from commodity bulk formats, with gummies commanding manufacturing complexity premiums over established pill and powder routes.
- Gummies:Gelatin and pectin-based matrices incorporating heat-stable bioactives with defined shelf-life specifications. Adult pill-averse consumers in the United States convert to repeat purchase through flavor-forward formulations that bypass traditional supplement rituals.
- Pills:Compressed tablets and two-piece hard capsules with established excipient compatibility and dissolution profiles. German and Chinese manufacturers prioritize pill formats for clinical nutrition and mass-market dietary supplement lines where cost efficiency dominates.
- Powders:Free-flowing granules and micronized particles for bulk fortification and beverage premix applications.
- Liquids:Aqueous and oil-based suspensions with emulsion stability requirements for pediatric and geriatric compliance.
Pills retain the installed manufacturing base while gummies expand most quickly through direct-to-consumer subscription models.
Application:
Customer type differentiation separates institutional clinical nutrition procurement from brand-driven functional food development, with beverage applications demanding the most intensive sensory masking R&D investment.
- Dietary Supplements:Capsule, tablet, and softgel products positioned for structure-function claims under DSHEA or equivalent frameworks. US and European specialized wellness platforms bypass retail intermediaries to capture margin and first-party data.
- Functional Foods:Fortified dairy, bakery, and snack matrices with bioactive stability through processing conditions. German brands accelerate procurement of fermentation-derived vitamins for clean-label positioning in yogurt and cereal applications.
- Beverages:Ready-to-drink and concentrate formats requiring flavor system compatibility and thermal stability.
- Nutraceuticals:Medical food and clinical nutrition products with health claim substantiation for targeted patient populations.
Dietary supplements dominate current revenue while functional foods climb the fastest on CPG brand fortification commitments.
End User:
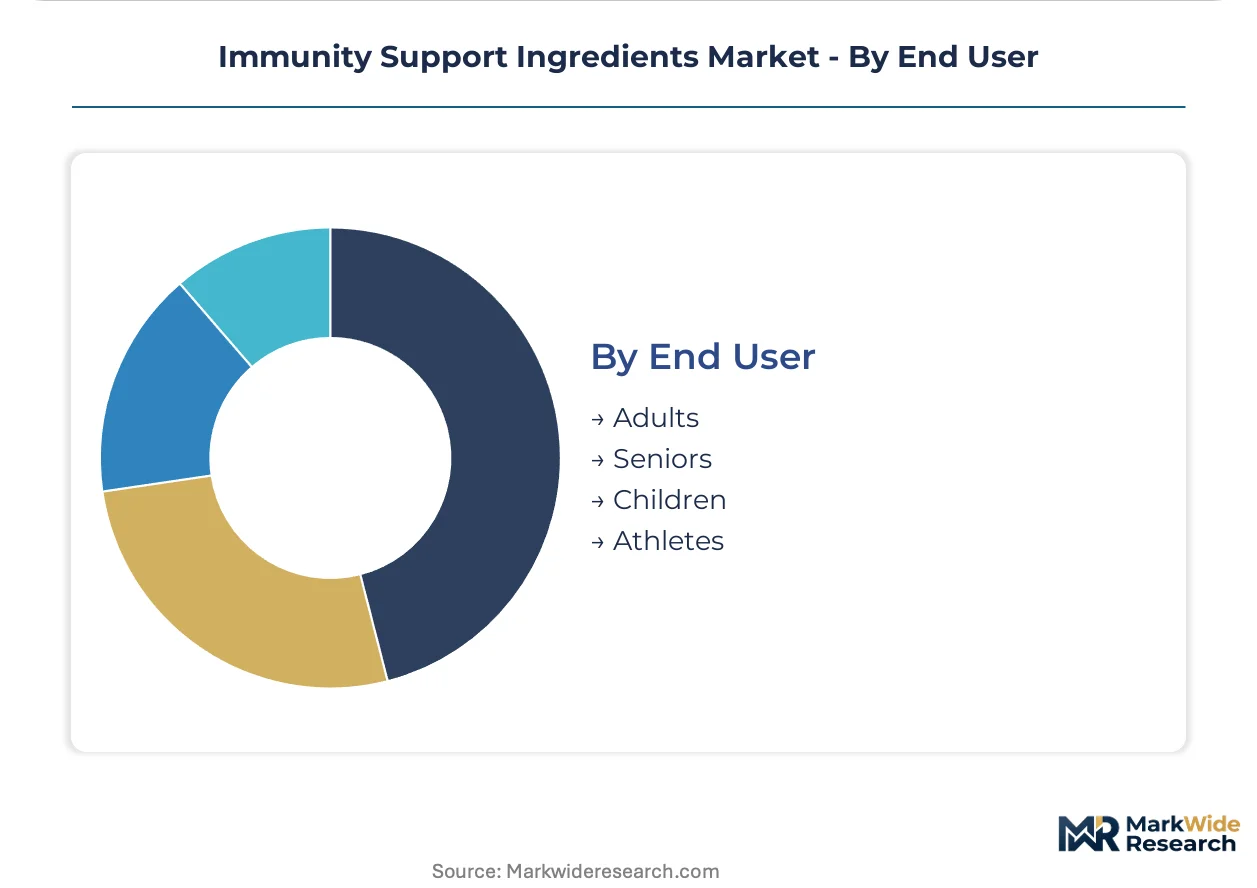
Volume concentration tracks demographic scale, with adult maintenance segments outpacing specialized pediatric and athletic formulations in raw tonnage despite lower per-unit premiums.
- Adults:General wellness consumers seeking daily immune maintenance through accessible delivery formats. Post-pandemic behavior in the United States prioritizes preventive regimens over acute response, concentrating demand in gummy and beverage formats.
- Seniors:Age-related immune decline drives demand for bioavailable forms with documented absorption in compromised gastrointestinal function. Chinese and German clinical nutrition brands develop specialized formulations for institutional and home-care channels.
- Children:Palatability-driven formats with age-appropriate dosing and safety profiles.
- Athletes:Performance-positioned products with anti-inflammatory and recovery claims targeting exercise-induced immune suppression.
Adults provide the volume foundation while seniors demonstrate the steepest expansion trajectory on aging population demographics and clinical nutrition penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European ingredient distribution for fermentation-derived vitamins, while Shanghai Yangshan深水港 handles Asia-Pacific probiotic concentrate imports. These maritime nodes determine regional procurement velocity.
United States
Post-pandemic preventive wellness behavior concentrates demand for gummy and functional beverage formats. FDA's DSHEA framework permits structure-function immune claims without pre-market authorization, accelerating formulation timelines. Chicago and New Jersey host contract manufacturing clusters serving direct-to-consumer wellness platforms.
Germany
Functional food brands drive procurement of fermentation-derived vitamins for clean-label yogurt and cereal fortification. EFSA's centralized health claim authorization requires cytokine response data from randomized controlled trials, compressing supplier margins. Bavaria and North Rhine-Westphalia concentrate biotechnology fermentation capacity.
China
SAMR and NMPA impose dual registration requirements on imported functional ingredients, creating 18-24 month approval bottlenecks for Western suppliers. Domestic probiotic manufacturers capture volume for Lactobacillus and Bifidobacterium strains. Yangtze River Delta clusters specialize in botanical extract standardization.
India
FSSAI and CDSCO tighten contaminant limits and GMP enforcement for domestic ayurvedic immunity extracts. Production-linked incentives for domestic manufacturing reduce import dependency. Maharashtra and Gujarat concentrate ayurvedic processing infrastructure for export markets.
Immunity Support Ingredients Market Competitive Landscape
On the supply side, the industry is consolidating around biotechnology firms with backward integration into fermentation platforms and diversified ingredient portfolios. Three archetypes dominate: fermentation-derived vitamin specialists, dairy and plant-protein fortification system providers, and global direct-sales network operators. Capacity expansion and clinical substantiation investment constitute the primary competitive vectors.
Within the fermentation-specialist tier, Royal DSM exemplifies backward-integrated biotechnology positioning through captive vitamin production. Glanbia occupies the dairy and plant-protein fortification system space, serving functional food brand procurement. Herbalife Nutrition anchors the direct-sales archetype, bypassing retail intermediaries entirely through its global network infrastructure.
| Leading Market Players |
|---|
| Blackmores Limited |
| Royal DSM |
| Herbalife Nutrition |
| USANA Health Sciences |
| Alticor |
| Nutramax Laboratories |
| Glanbia |
| Bayer AG |
| BioGaia |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta fermentation clusters anchor global vitamin C and B-complex capacity, concentrating pricing power among backward-integrated biotechnology firms while compressing margins for legacy petrochemical-derived synthetic routes. Contract manufacturers in Chicago and New Jersey convert these inputs into gummy and pill formats, with procurement costs feeding directly into finished-product tiering.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on fermentation-origin certification and EFSA health claim substantiation status. Price differentiation hinges on clinical trial documentation depth and geographic delivery cost from Yangtze River Delta or Bavarian fermentation hubs. Pricing pressure stems from EFSA's cytokine response data requirements forcing portfolio redevelopment. Mass-market dietary supplement brands exhibit highest price sensitivity, while specialized wellness platforms absorb premiums for audit-ready substantiation files.
Supply Chain Analysis
Contract manufacturing concentration sits with Chicago and New Jersey clusters serving US direct-to-consumer platforms, alongside Bavarian and North Rhine-Westphalia fermentation specialists. Raw material dependencies include fermentation feedstocks, botanical harvests from Indian ayurvedic regions, and strain-specific probiotic cultures. Supply chain risk centers on China's SAMR-NMPA dual registration bottlenecks creating 18-24 month approval delays for Western suppliers. Distribution runs through specialized wellness platforms and pharmacy marketplaces disintermediating traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms threaten incumbent petrochemical-derived vitamin suppliers with cost-parity and clean-label positioning, forcing substitution defense through clinical evidence depth and backward integration.
For Market Incumbents: Insulate market position through captive fermentation capacity in Bavaria or North Rhine-Westphalia, converting petrochemical legacy assets before cost parity erodes margins. Deepen clinical trial investment for EFSA cytokine response endpoints to maintain European market access against emerging fermentation specialists. Prioritize direct-to-consumer platform partnerships to capture first-party data and subscription retention mechanics. For New Entrants and Emerging Players: India's Maharashtra and Gujarat ayurvedic processing infrastructure presents underpenetrated white space for FSSAI-compliant extract standardization targeting export markets. Stress-immune axis positioning for ashwagandha and reishi extracts remains clinically underdocumented, offering premium pricing entry before incumbent trial completion. Deploy production-linked incentive alignment with domestic Indian manufacturing to bypass import dependency cost structures. For Investors and Strategic Acquirers: Long-term, this sits as a clinical-evidence moat play because regulatory substantiation thresholds across FDA, EFSA, and NMPA concentrate value in dossier-heavy suppliers. Target acquisition profiles emphasize fermentation-backward-integrated mid-caps with strain-specific probiotic libraries or botanical extract standardization capabilities. Monitor EFSA health claim authorization timelines as inflection indicator for European portfolio viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cytokine response data generation satisfies EFSA's tightened biomarker acceptance criteria for immune claims. |
| Backward Integration | Fermentation platform ownership secures cost parity against petrochemical synthetic routes for vitamin production. |
| Regulatory Approval Pathway | SAMR-NMPA dual registration navigation unlocks 18-24 month approval bottlenecks for China market access. |
| Direct-to-Consumer Launch | Specialized wellness platform partnerships bypass retail intermediaries and capture subscription retention economics. |
| Geographic Expansion | Maharashtra and Gujarat production bases leverage India's PLI scheme for ayurvedic extract cost advantages. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings for this immunity ingredients assessment. Conversations with dietary supplement formulators, fermentation platform engineers, regulatory affairs directors at EFSA and FDA, and procurement leads at functional food brands informed supply-side dynamics. Secondary validation drew from DSHEA structure-function claim databases, EFSA health claim authorization registers, SAMR-NMPA import registration records, and FSSAI contaminant limit notifications. Bottom-up ingredient volume modeling and top-down market sizing triangulated across these sources.
Calibration against historical CAGRs for vitamins, probiotics, and herbal extracts shaped the projection framework across the analysis window. Segmentation dimensions modeled include ingredient type, delivery form, application category, and end-user demographic. Growth rate derivation incorporated fermentation technology adoption curves, regulatory approval timeline distributions, and direct-to-consumer channel penetration patterns. Clinical trial cost inflation and dual registration bottleneck durations served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic probiotic manufacturers or accelerated EFSA guidance revision would shift outcomes. Quarterly review of health claim authorization queues, fermentation platform commissioning announcements, and PLI scheme uptake metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Encapsulated Ingredients Market
Ingredients
Global Malt Ingredients Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Orange Powder Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Self-Rising Flour Market
Ingredients
Cognitive Ingredients Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Egg Albumin Protein Market