
 Augmented Analytics Market | 2026-2036
Augmented Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Analytics Market Analysis
North American cloud infrastructure providers is broadening the accessible supply base for enterprise-grade augmented analytics platforms. Microsoft Corporation leverages its Azure ecosystem to anchor consumption of natural language query tools across Fortune 500 accounts. SAP SE sustains deep integration into European manufacturing ERP stacks, competing on workflow embeddedness rather than standalone visualization. Salesforce, Inc. differentiates through CRM-native analytics that controls the front-end data pipeline for sales operations teams.
Augmented analytics fuses machine learning, natural language generation, and automated insight detection to transform raw enterprise data into narrated, actionable recommendations without requiring specialized statistical expertise. The technology stack typically processes structured and semi-structured inputs through pretrained models that surface anomalies, correlations, and predictive signals in conversational formats. Cloud-based deployment captures the dominant share of new implementations as enterprises prioritize elastic compute scaling and reduced on-premises maintenance overhead. Natural language processing represents the fastest-expanding solution layer, with vendors racing to embed conversational interfaces that flatten the skills barrier for business users. Large enterprises remain the core revenue pool, though medium enterprises are emerging as the most contested growth segment as packaged offerings lower entry costs.
The EU AI Act imposes risk-tiered compliance obligations on algorithmic decision systems deployed within European member states, directly affecting how augmented analytics vendors design explainability features and audit trails. The US FDA and HIPAA frameworks shape analytics deployment in healthcare settings, where diagnostic and patient-facing tools must demonstrate validated, traceable outputs. China's SAMR and MIIT coordinate data localization and algorithmic recommendation rules that constrain cross-border model training. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting architecture partners and geographic rollout sequences.
Market Dynamics
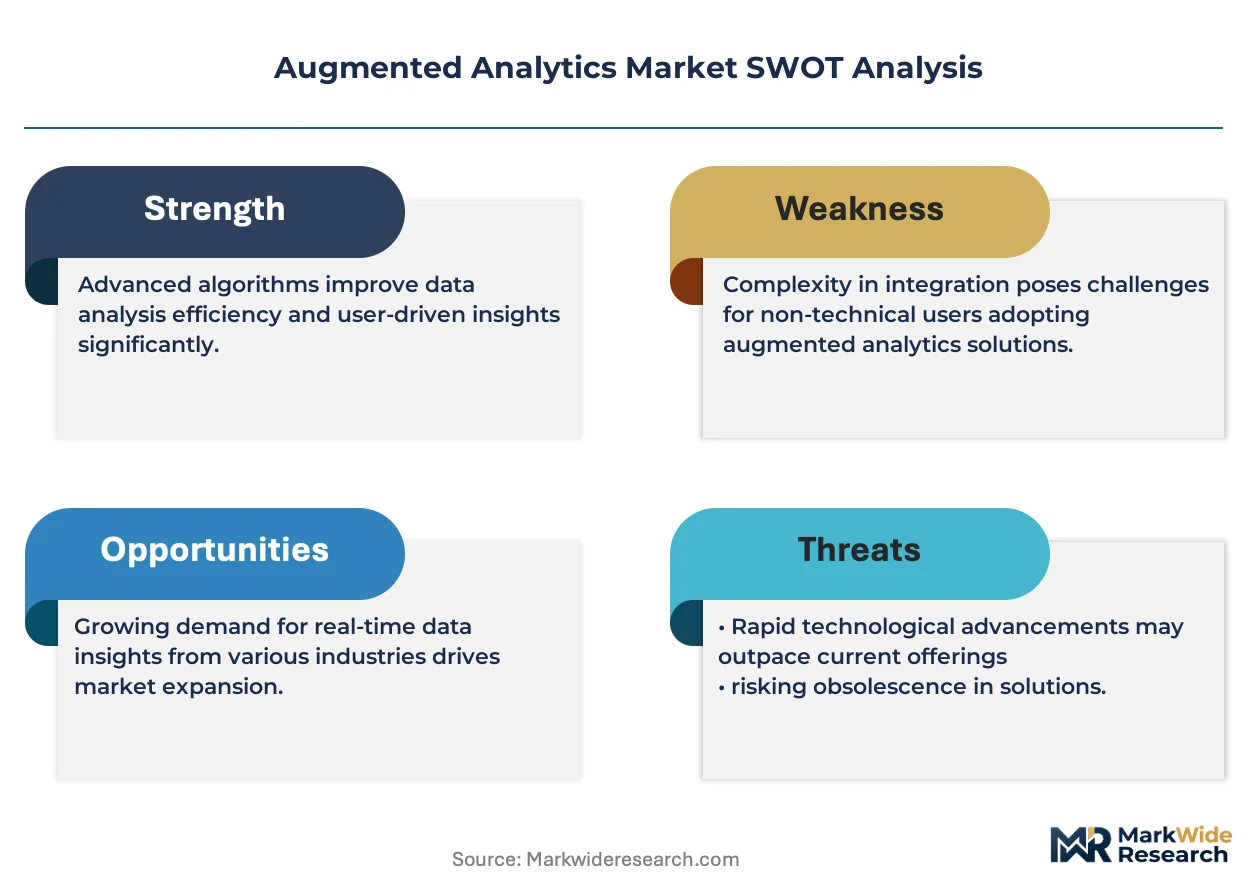
Natural language processing interfaces are compressing the skills barrier for business intelligence, pulling medium enterprises into augmented analytics deployments that previously required dedicated data science teams.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered algorithmic transparency requirements are forcing European enterprises to upgrade legacy BI systems toward explainable, auditable augmented platforms.
- Healthcare diagnostic automation:US FDA and HIPAA frameworks validate clinical decision support tools, accelerating hospital system procurement of automated insight detection for radiology and pathology workflows.
- Germany's industrial automation corridor:Manufacturing ERP integration demand concentrates in Baden-Württemberg and Bavaria, where predictive maintenance analytics command premium deployment budgets.
Market Restraints
- Cross-border model training constraints:China's SAMR and MIIT data localization rules fragment cloud infrastructure, forcing vendors to maintain separate training environments for PRC deployments.
- GPU compute cost volatility:Elastic scaling of transformer-based NLP workloads exposes enterprises to unpredictable cloud expenditure spikes during peak analytical query periods.
- Substitution by embedded BI:Native analytics within Salesforce, Workday, and ServiceNow platforms satisfies basic user needs without standalone augmented analytics procurement.
Strategic Opportunities
- India's PLI scheme for IT hardware:Domestic data center infrastructure incentives reduce latency costs for cloud-based analytics delivery to South Asian manufacturing hubs.
- Convergence of graph neural networks with NLP:Relationship-aware recommendation engines unlock supply chain and fraud detection applications previously unreachable by tabular ML alone.
- Edge deployment architectures:Federated learning on factory-floor devices enables real-time quality analytics without transmitting sensitive production data to centralized clouds.
Industry Challenges
- Prompt engineering talent scarcity:Enterprises struggle to hire specialists capable of tuning large language model outputs for domain-specific analytical accuracy.
- Legacy data warehouse integration:Decades-old on-premises SAP and Oracle ERP instances resist API-native connectivity, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Analytics Market |
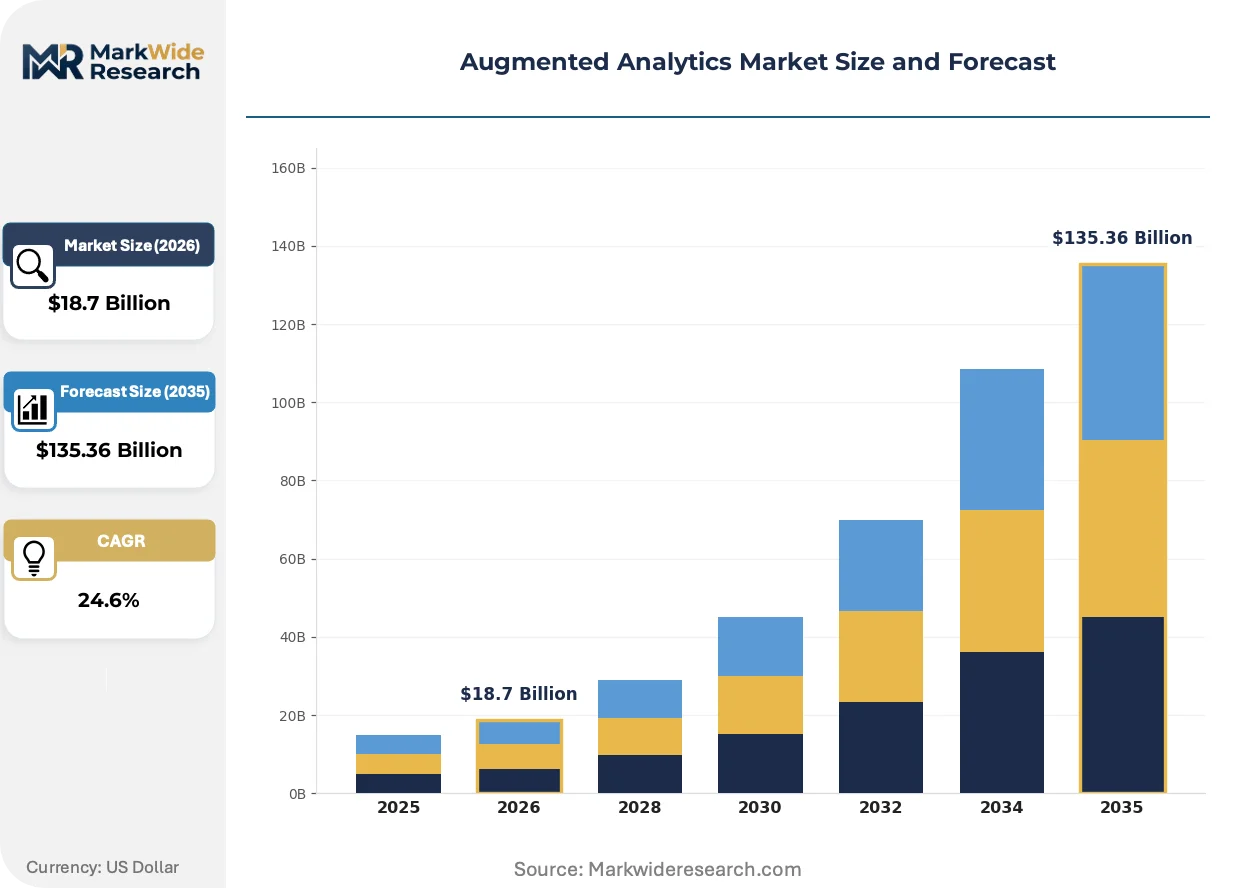
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Solution: Data Visualization, Data Mining, Machine Learning, Natural Language Processing Application: Financial Analysis, Market Forecasting, Retail Analytics, Customer Insights |
| Companies Covered | Salesforce, Inc., SAP SE, International Business Machines Corporation, Microsoft Corporation, Oracle Corporation, SAS Institute Inc., QlikTech International A.B., TIBCO Software Inc., Domo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Analytics Market Emerging Trajectories
Conversational interfaces are flattening organizational hierarchies for data access, while regulatory pressure and compute economics reshape how vendors architect their delivery models.
Retrieval-augmented generation is electrifying enterprise knowledge management by grounding large language model outputs in proprietary document corpora. Financial services compliance teams in London and Singapore are deploying RAG-based systems to automate regulatory interpretation at scale. This architecture compresses time-to-insight for legal and risk functions that previously relied on manual research across fragmented policy databases.
The EU AI Act's risk classification framework is mandating human-in-the-loop overrides for high-stakes algorithmic decisions. Healthcare and credit scoring deployments face mandatory explainability documentation that legacy black-box models cannot satisfy. German automotive suppliers are restructuring their quality analytics stacks to embed counterfactual explanation modules before 2025 enforcement deadlines.
Consumption-based pricing for analytical compute is displacing perpetual license models among mid-market buyers. Channel partners in the US Midwest and Nordic regions are bundling managed services with usage-metered platforms to capture recurring revenue. Manufacturing verticals with seasonal demand patterns prefer this structure to avoid stranded capacity during low-utilization quarters.
Augmented Analytics Market Segmentation
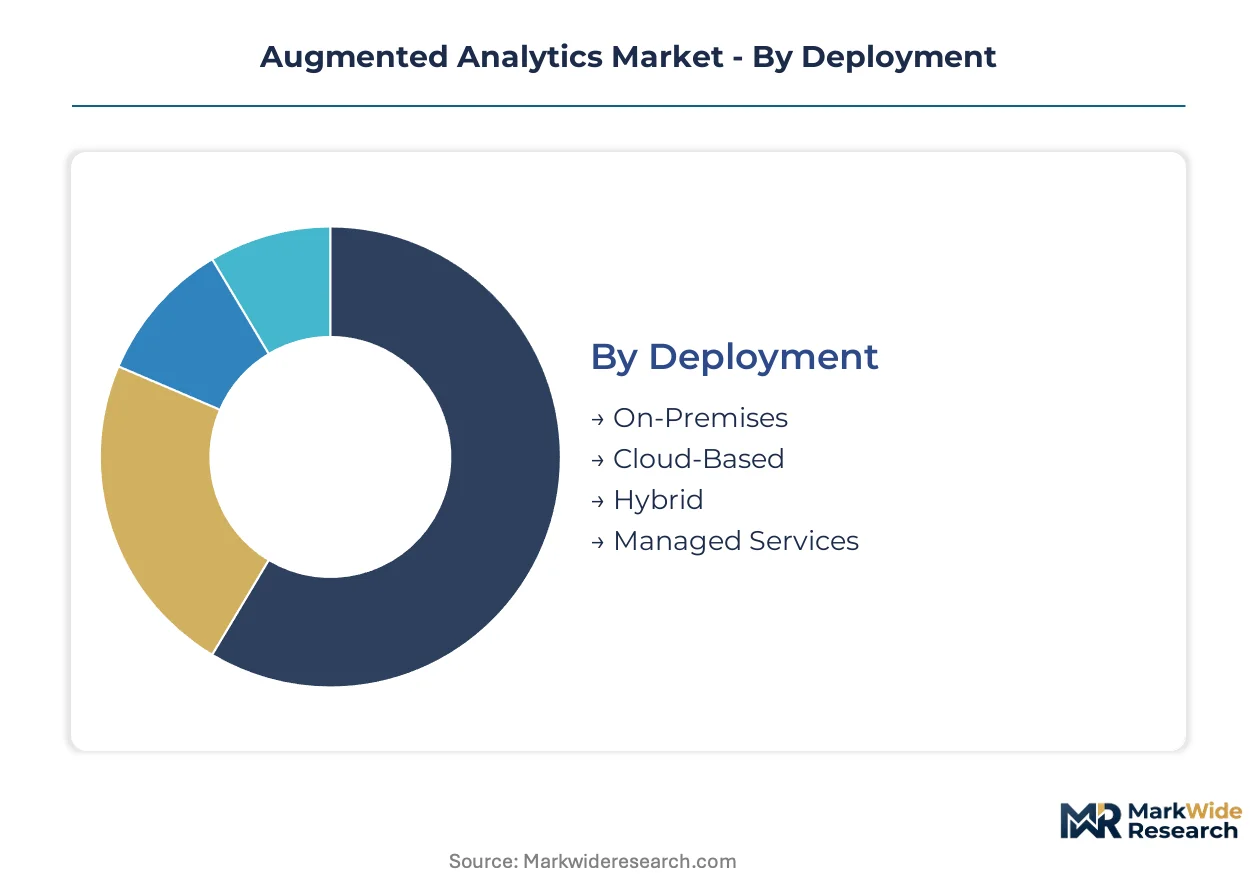
Deployment architecture, enterprise scale, solution stack, and application domain each reshape vendor go-to-market economics and R&D allocation. Understanding where demand concentrates within these dimensions clarifies which capabilities command premium positioning versus commodity substitution risk.
Deployment:
Supply concentration in hyperscale cloud infrastructure has tilted vendor development roadmaps toward elastic, API-native delivery models.
- Cloud-Based:Elastic compute scaling enables transformer-based NLP workloads without capital-intensive GPU procurement. Healthcare providers in the US and manufacturing clusters in Germany prioritize consumption-metered platforms to align analytics spend with diagnostic or predictive maintenance volume.
- Hybrid:Federated architectures partition sensitive production data on-premises while pushing model training to centralized clouds. German automotive suppliers facing EU AI Act audit requirements deploy hybrid stacks to maintain data sovereignty without sacrificing algorithmic sophistication.
- On-Premises:Legacy ERP integration in regulated industries retains stranded capacity in financial services and defense contracting.
- Managed Services:Channel partners bundle operational support with usage-based platforms to capture recurring revenue in mid-market manufacturing.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid architectures are expanding most quickly as compliance complexity fragments infrastructure decisions.
End User:
Customer type determines pricing architecture and sales cycle length, with procurement authority concentrating in procurement functions below $500M revenue thresholds.
- Large Enterprises:Fortune 500 accounts demand workflow-embedded analytics with SAP or Salesforce-native integration. Microsoft Azure anchors natural language query consumption through existing enterprise licensing agreements.
- Medium Enterprises:Packaged offerings with reduced configuration overhead flatten the skills barrier previously requiring dedicated data science teams. India's PLI scheme for IT hardware reduces latency costs for cloud delivery to South Asian manufacturing hubs in this segment.
- Small Enterprises:Native BI within Workday and ServiceNow satisfies basic needs without standalone augmented analytics procurement.
- Government:HIPAA and FDA frameworks in the US validate clinical decision support tools for hospital system procurement.
Large Enterprises command the dominant share of current revenue; Medium Enterprises are climbing the fastest as standardized NLP interfaces compress deployment friction.
Solution:
Technology layer maturity varies sharply, with conversational interfaces attracting disproportionate vendor investment relative to back-end infrastructure.
- Natural Language Processing:Pretrained models surface anomalies and predictive signals in conversational formats without statistical expertise. Financial services compliance teams in London and Singapore deploy retrieval-augmented generation to automate regulatory interpretation.
- Machine Learning:Automated insight detection powers predictive maintenance analytics in Baden-Württemberg and Bavaria manufacturing corridors.
- Data Visualization:Standalone dashboarding faces substitution pressure from CRM-native analytics controlling front-end data pipelines.
- Data Mining:Relationship-aware recommendation engines unlock supply chain and fraud detection applications through graph neural network convergence.
NLP solutions capture the steepest expansion trajectory; Machine Learning retains the largest installed base across industrial automation deployments.
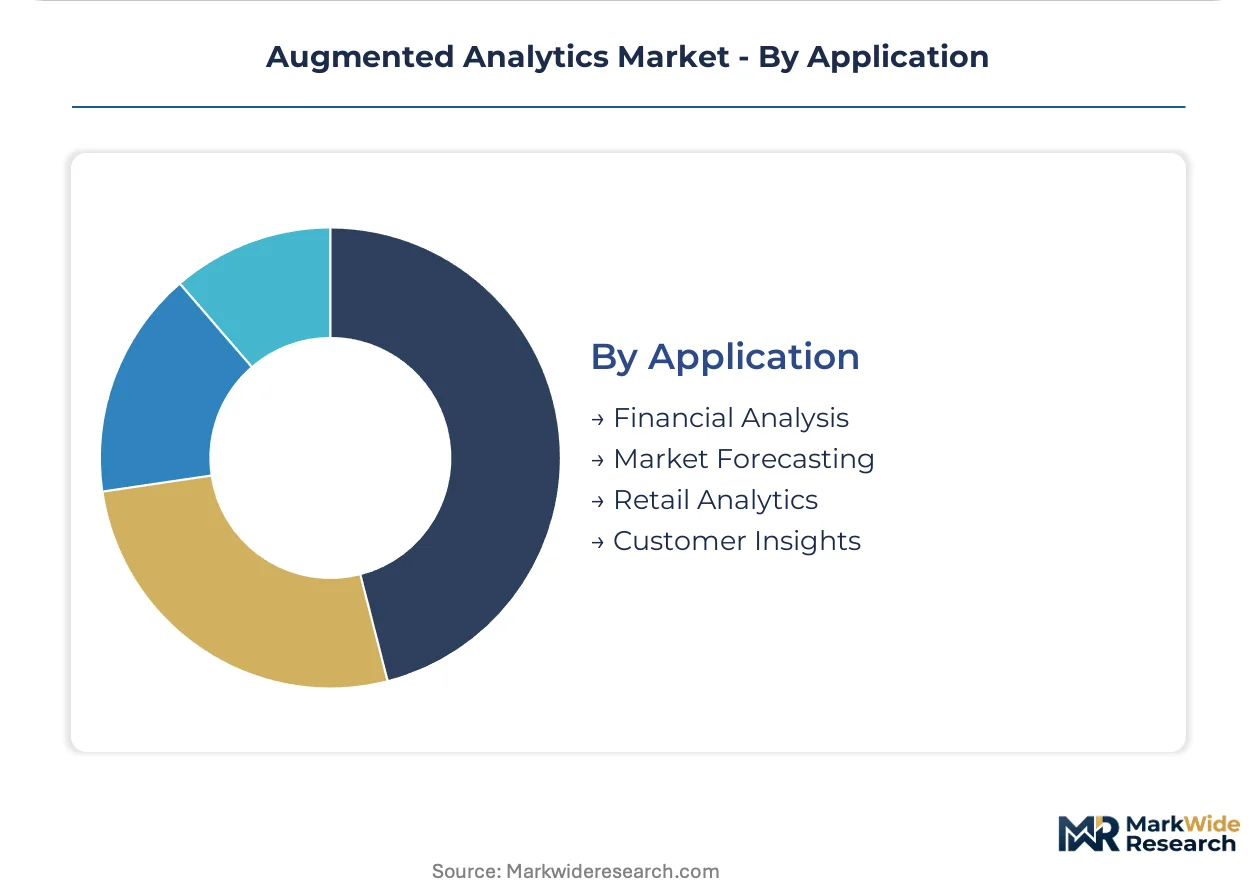
Application:
Use-case specificity determines explainability requirements and regulatory exposure, with high-stakes decisions mandating human-in-the-loop overrides.
- Financial Analysis:Credit scoring deployments face mandatory explainability documentation under EU AI Act risk classification frameworks. German automotive suppliers restructure quality analytics stacks to embed counterfactual explanation modules.
- Customer Insights:CRM-native analytics from Salesforce controls front-end data pipelines for sales operations teams.
- Retail Analytics:Seasonal demand patterns favor consumption-based pricing to avoid stranded capacity during low-utilization quarters.
- Market Forecasting:Elastic scaling exposes enterprises to unpredictable cloud expenditure spikes during peak analytical query periods.
Financial Analysis commands premium deployment budgets due to compliance complexity; Customer Insights is gaining share fastest as embedded BI displaces standalone procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure locality anchors geographic deployment patterns for augmented analytics, with hyperscale data center density determining latency-sensitive NLP workload distribution.
United States
Healthcare providers and financial services firms drive enterprise NLP adoption. FDA validation requirements for clinical decision support tools shape procurement timelines for hospital systems. The Greater Boston corridor concentrates diagnostic automation startups targeting radiology workflows.
Germany
Automotive suppliers and industrial manufacturers command premium budgets for predictive maintenance analytics. EU AI Act risk-tiered compliance mandates force restructuring of quality assurance stacks before enforcement deadlines. Baden-Württemberg and Bavaria host manufacturing ERP integration clusters requiring embedded explainability modules.
China
Domestic cloud providers serve state-owned enterprises under data localization constraints. SAMR and MIIT algorithmic recommendation rules fragment cross-border model training environments. Yangtze River Delta manufacturing hubs deploy edge analytics for real-time quality control without centralized cloud transmission.
United Kingdom
Financial services compliance teams automate regulatory interpretation through retrieval-augmented generation systems. GDPR and emerging AI governance frameworks impose documentation burdens on algorithmic credit decisions. London anchors European headquarters for US cloud vendors serving Fortune 500 accounts.
India
IT services exporters and domestic manufacturing hubs accelerate cloud analytics adoption. PLI scheme incentives for IT hardware reduce latency costs for South Asian delivery. Karnataka and Telangana data center clusters support consumption-metered platforms for mid-market enterprises.
Augmented Analytics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue workflow-embedded specialization and vertical-specific explainability modules. The vendor base stratifies across three tiers: hyperscale cloud platforms with enterprise licensing leverage, ERP-native incumbents competing on integration depth, and standalone analytics specialists defending through domain expertise. Three strategic archetypes dominate: infrastructure-anchored ecosystems, workflow-embedded suites, and best-of-breed point solutions. Competitive moves concentrate on M&A for NLP talent acquisition and strategic partnerships for edge deployment architectures.
Within the infrastructure-anchored tier, Microsoft Corporation and Oracle Corporation exemplify platform leverage through existing enterprise cloud contracts. SAP SE occupies a position representing ERP-native embeddedness, competing on manufacturing workflow integration rather than standalone visualization capabilities. Salesforce, Inc. anchors the CRM-native archetype, controlling front-end data pipelines for sales operations teams through acquisition-built analytics layers.
| Leading Market Players |
|---|
| Salesforce, Inc. |
| SAP SE |
| International Business Machines Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAS Institute Inc. |
| QlikTech International A.B. |
| TIBCO Software Inc. |
| Domo, Inc. |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's risk-tiered compliance mandates gate qualified supply for augmented analytics platforms, reserving premium-tier pricing access to vendors with embedded explainability modules and auditable algorithmic pipelines. Cloud infrastructure providers with certified EU data residency capabilities command 20-40% pricing premiums over uncertified competitors, while buyers in Germany's automotive corridor absorb these costs to meet enforcement deadlines.
Pricing Analysis
Warranty and service bundling separates consumption-metered SaaS tiers from bare-metal infrastructure rentals, with managed support packages capturing 15-25% of total contract value across mid-market manufacturing buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU AI Act-compliant deployments commanding the top tier. Pricing pressure stems from embedded BI substitution within Salesforce and Workday platforms, which satisfies basic visualization needs without standalone procurement. Medium enterprises exhibit highest price sensitivity, while Fortune 500 accounts prioritize workflow integration over per-seat costs.
Supply Chain Analysis
GPU compute capacity rests on Taiwanese semiconductor foundries, US hyperscale cloud operators, and South Korean memory suppliers for transformer-based NLP workload acceleration. NVIDIA A100/H100 clusters, high-bandwidth memory modules, and specialized AI training silicon constitute critical input dependencies. Single-source vulnerability concentrates in advanced node GPU fabrication, where geopolitical export controls threaten supply continuity. Distribution runs through direct enterprise sales teams for large accounts and channel partner networks for mid-market manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU compute scarcity props pricing power for cloud-based augmented analytics platforms, as transformer model training demands outstrip foundry expansion timelines across the analysis window.
For Market Incumbents: To counter embedded BI substitution from Salesforce and Workday, Microsoft and SAP should deepen API-native connectivity into legacy Oracle ERP instances while embedding counterfactual explanation modules for EU AI Act compliance. Certification investment in HIPAA-validated healthcare deployments creates defensive moats against standalone analytics specialists. For New Entrants and Emerging Players: Graph neural network convergence with NLP offers a technology-first wedge into supply chain fraud detection applications previously unreachable by tabular ML alone. India's PLI scheme-supported data center clusters present the most penetrable geography, with consumption-metered platforms targeting mid-market manufacturing in Karnataka and Telangana through channel partner bundling. For Investors and Strategic Acquirers: FDA 510(k) clearance submissions for clinical decision support tools are the leading indicator that healthcare-focused augmented analytics vendors are approaching enterprise scalability. Long-term viability favors acquisition targets with proprietary retrieval-augmented generation architectures and established hospital system procurement relationships. Watch for EU AI Act enforcement actions against non-compliant legacy BI vendors as the inflection signal for compliance-tech consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | NLP talent scarcity drives premium valuations for prompt engineering teams with healthcare domain expertise. |
| Platform Integration | SAP-native embedded analytics capture manufacturing ERP workflows in Baden-Württemberg without standalone procurement friction. |
| Geographic Expansion | India's PLI scheme reduces latency costs for cloud delivery to South Asian manufacturing hubs. |
| Strategic Partnership | Federated learning alliances with German automotive suppliers enable edge deployment without centralized cloud data transmission. |
| Product Launch | Retrieval-augmented generation systems automate regulatory interpretation for London financial services compliance teams. |
Methodological Framework
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory databases formed the secondary backbone, supplemented by primary interviews with CTOs, IT procurement officers, and healthcare informatics directors across the US, Germany, and India. Bottom-up triangulation combined vendor revenue disclosures with top-down cloud infrastructure spend analysis to validate market sizing.
Historical trendline analysis tracked NLP interface adoption curves and compliance-driven replacement cycles across enterprise BI installed bases. Segmentation modeling incorporated deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory framework dimensions. CAGRs derived from elastic compute pricing trajectories and healthcare diagnostic automation procurement velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GPU export control expansion or EU AI Act enforcement acceleration. Assumptions reflect sustained cloud migration momentum and transformer model capability advancement. A small set of named triggers—including SAMR data localization rulings and FDA validation pathway changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
US Video Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Video Analytics Market
Analytics
Data Analytics Market
Analytics
Global Systems of Insight Market
Analytics
APAC Operational Intelligence Market
Analytics
Audio and Video Analytics Software Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Analytics Sandbox Market
Analytics
Europe Edge Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Voice Analytics Market
Analytics
Speech and Voice Analytics Market