
 Behavior Analytics Market | 2026-2036
Behavior Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Behavior Analytics Market Analysis
The behavior analytics software stack is repositioning around a sharp divergence between premium enterprise suites with native machine learning pipelines and commodity log-analysis tools sold on seat-based pricing. Splunk Inc. dominates the high-end segment through its data-to-everything platform architecture. Varonis Systems Inc. specializes in metadata-driven threat detection for unstructured data stores. Securonix competes on cloud-native security operations center automation.
Behavior analytics encompasses the computational discipline of capturing, processing, and interpreting human and machine activity patterns to detect anomalies, predict outcomes, or optimize operational decisions. The field relies on streaming event processing at sub-second latency, statistical baseline modeling, and graph-based relationship mapping across digital identities. Machine learning solutions currently anchor the largest revenue pool, while edge analytics represents the fastest-expanding technology layer as manufacturing and logistics operators push inference closer to sensor origins. Predictive modeling within the solution layer is capturing disproportionate R&D investment from vendors seeking differentiated forecasting accuracy.
The EU AI Act, GDPR, and HIPAA in the United States impose strict auditability and explainability mandates on automated decision systems, directly elevating procurement standards for behavior analytics platforms in regulated sectors. ISO 27001 and SOC 2 Type II certifications have become baseline requirements for vendor qualification in financial services and healthcare procurement cycles. Stakeholders must weigh the trade-off between cloud deployment agility and the data residency constraints that hybrid architectures are engineered to address.
Market Dynamics
The behavior analytics market is restructuring around explainable AI mandates from the EU AI Act and GDPR, forcing vendors to rebuild algorithmic transparency into core architecture rather than retrofit compliance as an afterthought.
Growth Catalysts
- EU AI Act Article 14:Mandates human oversight and audit trails for high-risk AI systems, creating procurement pull for platforms with built-in explainability dashboards.
- Financial Services:Basel III operational risk frameworks and SEC cybersecurity disclosure rules are accelerating deployment of insider threat detection in investment banks and asset managers.
- Edge Computing Convergence:Manufacturing operators in Germany and Japan are pushing behavioral inference to factory-floor sensors, reducing cloud egress costs and latency.
Market Restraints
- GPU Compute Costs:Real-time streaming analytics for behavioral baselining requires sustained NVIDIA A100/H100 allocation, squeezing margins for mid-tier vendors.
- Talent Concentration:Machine learning engineers with security domain expertise cluster in Silicon Valley and Tel Aviv, creating geographic hiring friction.
- False Positive Fatigue:SOC analysts at Fortune 500 enterprises report alert desensitization from poorly tuned statistical models, slowing renewal cycles.
Strategic Opportunities
- India BFSI Sector:RBI's 2024 guidelines on digital payment fraud detection create greenfield demand for behavioral biometrics in Mumbai and Bangalore.
- Healthcare IoT:HIPAA-covered entities are expanding from network monitoring to patient device behavior analytics for medical equipment compromise detection.
- Federated Learning Architectures:Cross-institutional behavioral modeling without raw data sharing is opening consortium opportunities among EU banking cooperatives.
Industry Challenges
- SOC 2 Type II Timeline:Six-to-twelve month audit cycles delay vendor qualification in financial services procurement, compressing competitive windows.
- Legacy SIEM Integration:Enterprises with decade-old Splunk or QRadar deployments face data schema fragmentation when layering behavioral analytics atop existing correlation engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behavior Analytics Market |
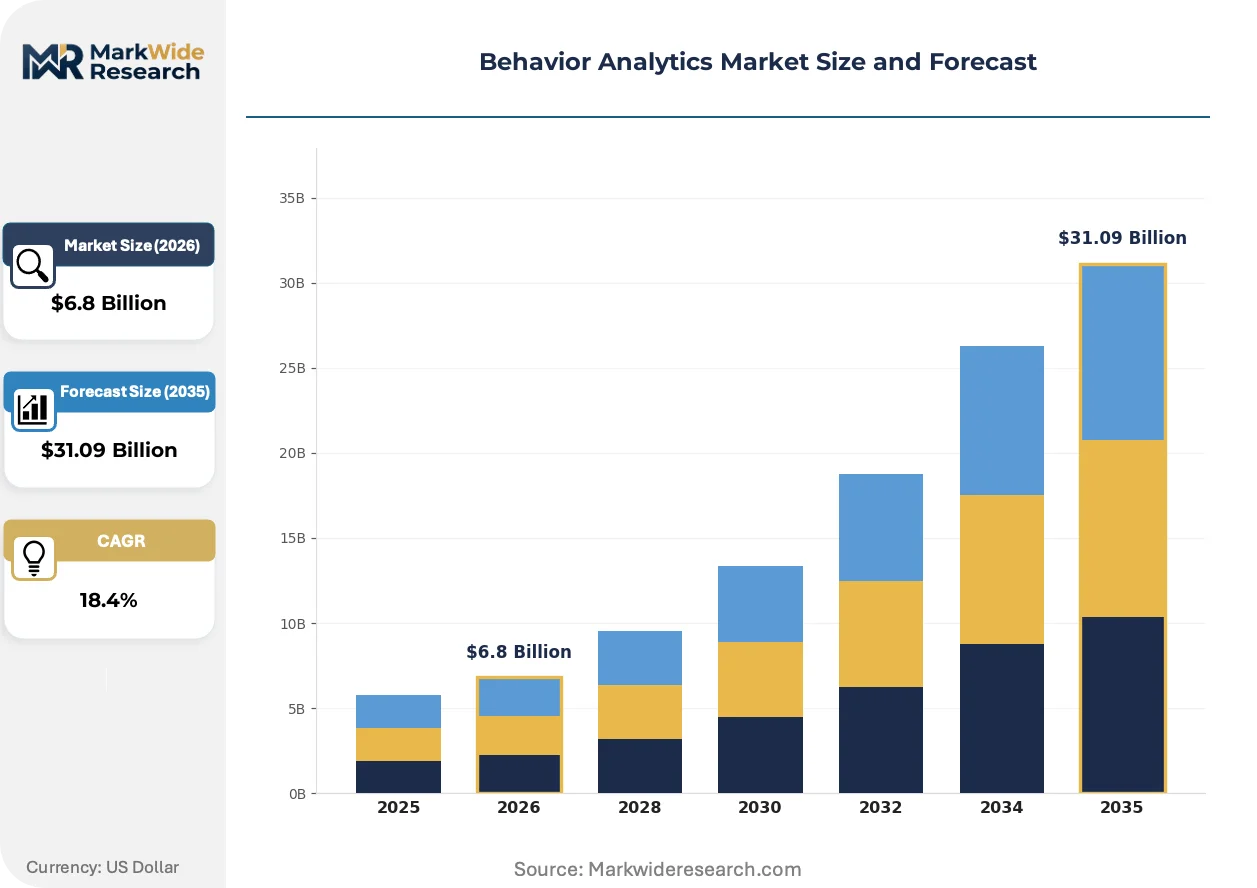
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Analytics, Predictive Modeling, Reporting Tool, Visualization Platform Technology: Machine Learning, Cloud Computing, Edge Analytics, Natural Language Processing End User: E-Commerce, Retail, Healthcare, Financial Services Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application |
| Companies Covered | Splunk Inc., Securonix, Varonis Systems Inc., Exabeam LLC, Rapid7 Inc., IBM Corporation, Qualtrics, Oracle Corporation, Fortinet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behavior Analytics Market Emerging Trajectories
Behavioral analytics is pivoting from retrospective forensics to predictive intervention, with vendors racing to compress detection-to-response latency while regulators demand algorithmic accountability.
Graph neural networks for identity relationship mapping are automating the discovery of compromised credentials through anomalous access patterns. Financial institutions in London and Singapore are deploying these models for privileged account monitoring. The technology is automating threat hunting workflows that previously required manual correlation across Active Directory, VPN, and cloud access logs.
The EU AI Act's risk classification system is forcing vendors to reengineer high-risk behavioral scoring algorithms with built-in human-in-the-loop checkpoints. Industrial consequence includes mandatory conformity assessments for insider threat platforms before EU market entry. Healthcare and critical infrastructure operators in France and Germany are prioritizing vendors with pre-certified explainability frameworks.
Enterprise procurement of behavior analytics is fragmenting from monolithic platform purchases to modular API consumption. Security teams at technology firms in Austin and Berlin are unbundling detection, investigation, and response functions across best-of-breed vendors. This pattern is most visible in mid-market enterprises seeking to avoid vendor lock-in while maintaining interoperability with existing SOAR investments.
Behavior Analytics Market Segmentation
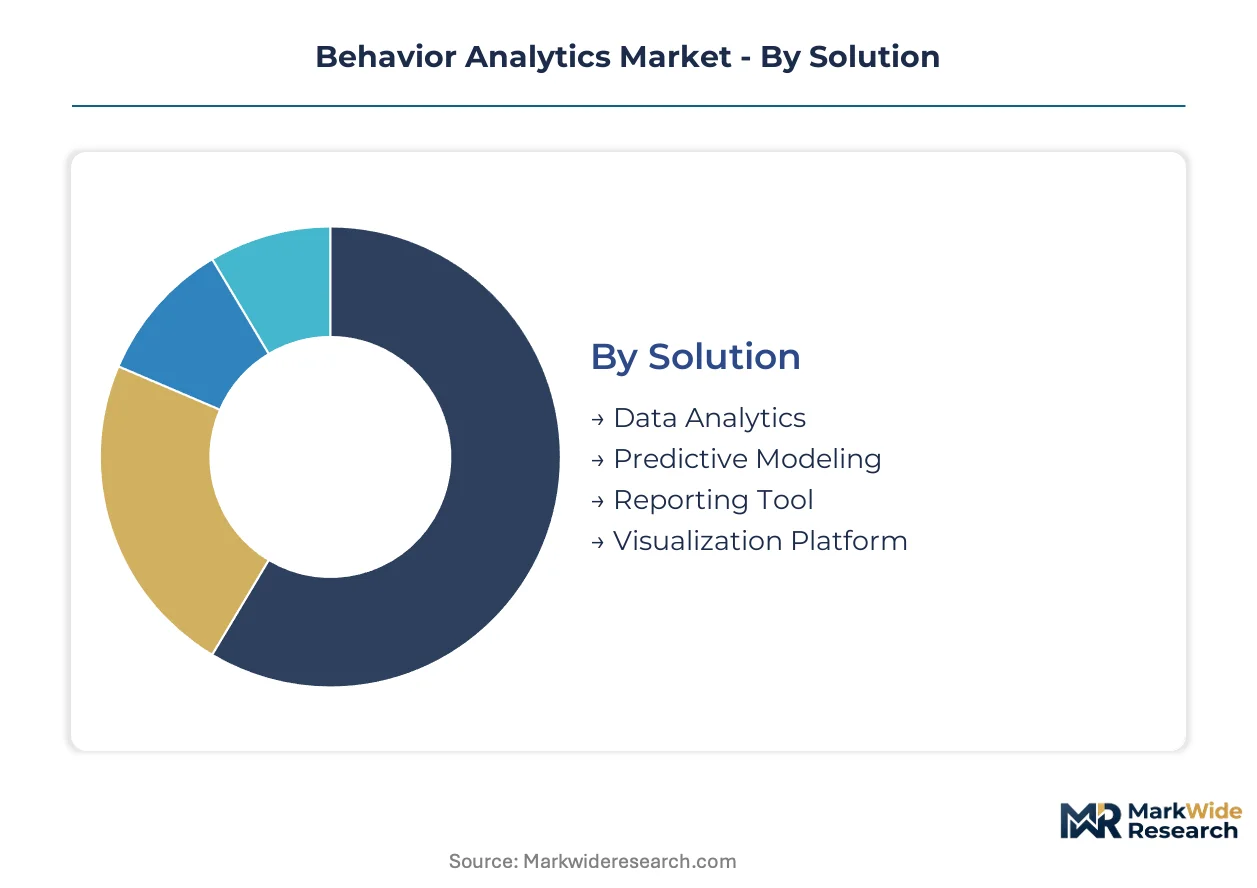
Behavior analytics procurement fragments across four critical dimensions: solution architecture, underlying technology, end-use vertical, and deployment topology. Each axis carries distinct margin profiles, compliance burdens, and integration complexity that reshape vendor positioning.
Solution:
Supply concentrates in predictive modeling platforms as financial institutions demand forecasting precision for fraud detection and insider threat scenarios.
- Predictive Modeling:Statistical and machine learning algorithms generate forward-looking risk scores from historical behavior baselines. Investment banks in London and Singapore allocate disproportionate procurement budgets here for privileged account anomaly detection.
- Data Analytics:Streaming event processing engines ingest and correlate multi-source telemetry at sub-second latency. Healthcare networks in Germany deploy these for medical device compromise detection under EU AI Act oversight requirements.
- Reporting Tool:Audit-ready dashboards with explainable decision trails for GDPR Article 22 compliance.
- Visualization Platform:Interactive graph-based relationship mapping for SOC analyst investigation workflows.
Today's leader: Predictive Modeling. Tomorrow's challenger: Data Analytics.
Technology:
Cost tier stratification separates GPU-intensive machine learning deployments from lightweight edge inference architectures.
- Machine Learning:Deep learning pipelines for behavioral baselining require sustained NVIDIA A100/H100 allocation, anchoring premium pricing tiers. Cloud-native vendors compete on model training efficiency and inference latency reduction.
- Edge Analytics:Distributed inference engines execute on factory-floor sensors and IoT gateways. Manufacturing operators in Germany and Japan push behavioral computation to sensor origins, minimizing cloud egress costs.
- Cloud Computing:Elastic compute for burst behavioral processing during security incidents.
- Natural Language Processing:Text analytics for email and chat behavior anomaly detection in insider threat programs.
Machine Learning commands current revenue concentration. Edge Analytics climbs the fastest as operational technology convergence accelerates.
End User:
Application maturity varies sharply: financial services run production-grade deployments while healthcare remains in pilot-to-scale transition.
- Financial Services:Basel III operational risk frameworks and SEC cybersecurity disclosure rules mandate insider threat detection. Investment banks and asset managers in New York and London represent the most sophisticated procurement segment with native ML pipeline requirements.
- Healthcare:HIPAA-covered entities expand from network monitoring to patient device behavior analytics. French and German hospital systems prioritize vendors with pre-certified EU AI Act explainability frameworks.
- E-Commerce:Real-time transaction behavior scoring for payment fraud detection.
- Retail:Customer journey analytics for loss prevention and supply chain integrity.
Financial Services dominates contract value. Healthcare presents the steepest expansion trajectory as medical IoT attack surfaces widen.
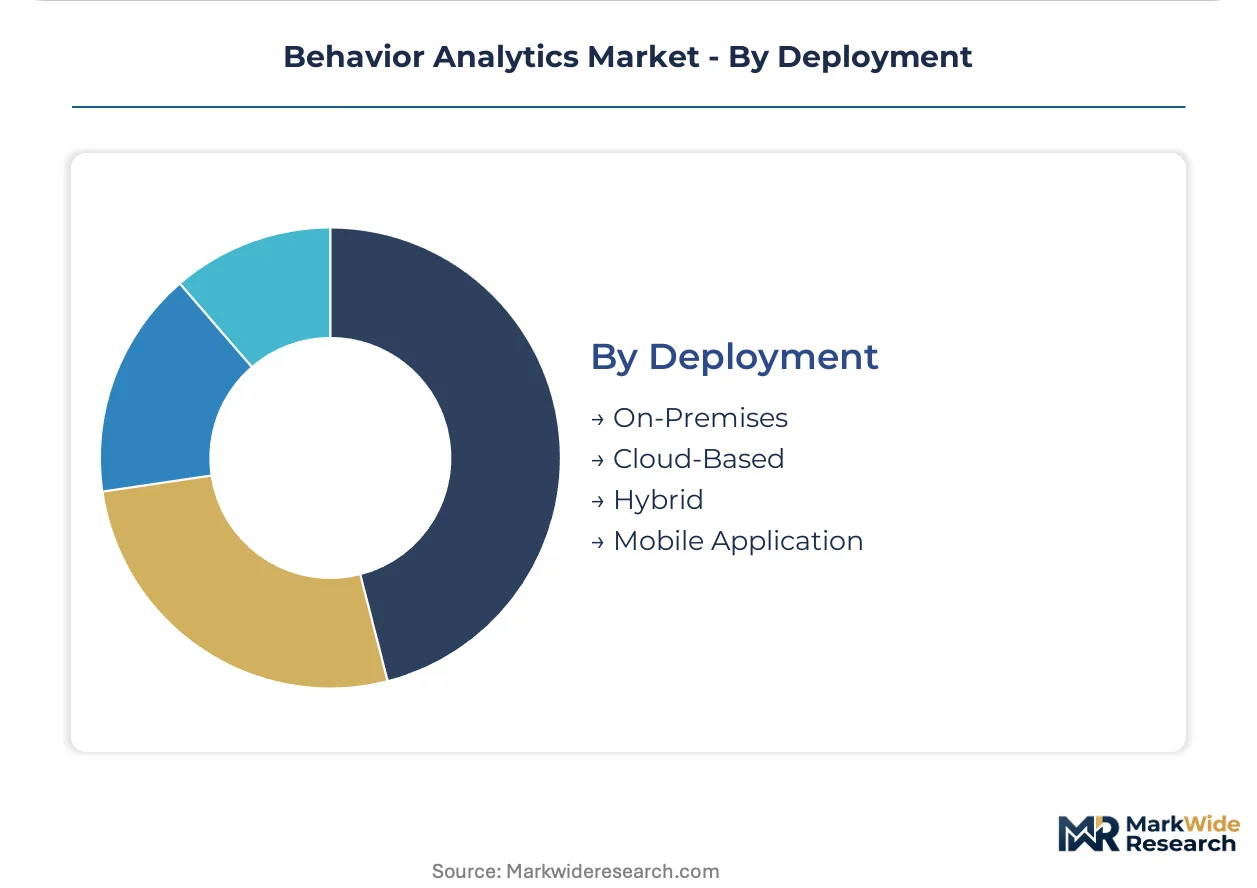
Deployment:
Customer type bifurcation separates regulated enterprises demanding data residency from cloud-native firms prioritizing agility.
- Hybrid:Split architectures route sensitive behavioral data to on-premises infrastructure while pushing anonymized analytics to cloud. EU banking cooperatives favor this topology for GDPR compliance without sacrificing scalability.
- Cloud-Based:Fully managed SaaS platforms with API-first consumption models. Technology firms in Austin and Berlin unbundle detection, investigation, and response functions across best-of-breed vendors.
- On-Premises:Air-gapped deployments for classified government and defense environments.
- Mobile Application:Endpoint behavioral biometrics for BYOD threat detection in distributed workforces.
Hybrid architectures capture regulated sector preference. Cloud-Based deployments gain share fastest among mid-market enterprises avoiding vendor lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers with security domain expertise cluster in Silicon Valley and Tel Aviv, creating geographic hiring friction that shapes vendor headquarters decisions and R&D investment patterns across the behavior analytics market.
United States
Fortune 500 enterprises in New York and Austin modernize security operations centers with native ML pipeline requirements. SEC cybersecurity disclosure rules mandate insider threat detection for investment banks and asset managers. The San Francisco Bay Area anchors cloud-native vendor development for SOAR-integrated behavioral platforms.
Germany
Manufacturing operators in Bavaria and Baden-Württemberg push behavioral inference to factory-floor sensors under EU AI Act oversight. The country's national data protection authority enforces GDPR Article 22 explainability mandates for automated decision systems. Frankfurt's banking cooperatives pilot federated learning architectures for cross-institutional behavioral modeling.
United Kingdom
Investment banks in the City of London allocate disproportionate procurement budgets to privileged account anomaly detection. Basel III operational risk frameworks drive deployment of graph neural networks for identity relationship mapping. Cambridge security startups compete with established vendors on model training efficiency.
India
RBI's 2024 guidelines on digital payment fraud detection create greenfield demand for behavioral biometrics. Mumbai and Bangalore BFSI operators seek vendors with pre-certified explainability frameworks. Hyderabad's technology corridor attracts mid-tier vendors establishing delivery centers for API-first platform development.
Japan
Manufacturing conglomerates in the Chubu region reduce cloud egress costs by executing behavioral analytics on IoT gateways. METI industrial security standards accelerate edge analytics adoption for operational technology convergence. Tokyo financial institutions balance HIPAA-equivalent data residency requirements with hybrid deployment agility.
Behavior Analytics Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where premium enterprise suites with native machine learning pipelines separate from commodity log-analysis tools. The vendor base stratifies around three strategic archetypes: data-to-everything platform architects, metadata-driven threat detection specialists, and cloud-native SOC automation vendors. Dominant competitive moves include portfolio diversification into edge analytics modules and strategic partnerships with NVIDIA for GPU compute allocation.
Within the platform architecture tier, Splunk Inc. and IBM Corporation occupy positions defined by enterprise data pipeline integration. Cloud-native specialists Securonix and Exabeam LLC exemplify the API-first consumption model gaining share among mid-market enterprises. Varonis Systems Inc. anchors the metadata-centric archetype for unstructured data stores. Each represents distinct architectural bets on where behavioral inference computation executes—centralized cloud, hybrid edge, or air-gapped premises.
| Leading Market Players |
|---|
| Splunk Inc. |
| Securonix |
| Varonis Systems Inc. |
| Exabeam LLC |
| Rapid7 Inc. |
| IBM Corporation |
| Qualtrics |
| Oracle Corporation |
| Fortinet Inc. |
| Others |
Supply Flow & Price Mechanics
NVIDIA H100 GPU spot pricing volatility cascades through behavior analytics vendor cost structures, compressing margins for mid-tier machine learning pipeline providers while entrenching premium pricing power among hyperscaler-aligned platform architects with captive compute allocation.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise procurement patterns sharply. Monolithic platform licensing with native ML pipelines commands premium SaaS tiers, while API-first modular consumption spreads detection, investigation, and response functions across best-of-breed vendors. Price differentiation rests on EU AI Act pre-certification status and SOC 2 Type II audit completion. Cost compression in mid-market seats is intensifying because GPU allocation scarcity favors volume buyers. Fortune 500 security operations centers exhibit lowest price sensitivity; mid-market technology firms in Austin and Berlin show highest.
Supply Chain Analysis
Dual-sourcing requirements for NVIDIA A100/H100 accelerators are now standard in vendor RFPs from financial services procurement teams. Hardware supply concentrates in Taiwan, South Korea, and the United States. Cloud infrastructure draws from hyperscaler data center networks in Frankfurt, Singapore, and Virginia. Single-source GPU dependency creates vulnerability to allocation rationing during demand spikes. Distribution runs through direct enterprise sales with professional services attach for hybrid deployment architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement is shifting toward explainable AI architectures with pre-certified audit trails, rewarding vendors who built algorithmic transparency into core design rather than retrofitting compliance.
For Market Incumbents: Extend explainability framework coverage to edge analytics modules before EU AI Act conformity assessments harden competitive barriers. GPU compute allocation agreements with NVIDIA anchor cost position against mid-tier challengers facing spot market volatility. Certification investment in ISO 27001 and SOC 2 Type II maintenance protects renewal cycles against cloud-native entrants.
For New Entrants and Emerging Players: Enter via federated learning architectures for EU banking cooperatives seeking cross-institutional behavioral modeling without raw data sharing. India BFSI sector presents the most penetrable geography following RBI 2024 digital payment fraud guidelines. API-first platform development with pre-built SOAR connectors accelerates procurement qualification.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native SOC automation vendors possessing pre-certified EU AI Act explainability frameworks and established hyperscaler marketplace distribution. Long-term viability favors platforms with hybrid deployment flexibility across regulated and cloud-native customer archetypes. Watch GPU allocation agreement renewals as inflection indicator for margin compression risk among mid-tier vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Mandatory conformity assessments for insider threat platforms before EU market entry reshape competitive qualification. |
| Edge Analytics Module Launch | Manufacturing operators in Germany and Japan reduce cloud egress costs through factory-floor sensor inference. |
| Hyperscaler Partnership | AWS, Azure, and GCP marketplace distribution accelerates procurement cycles for mid-market enterprise segments. |
| Federated Learning Architecture | Cross-institutional behavioral modeling without raw data sharing opens consortium opportunities among EU banking cooperatives. |
| Acquisition of Specialist Firm | Metadata-driven threat detection capabilities for unstructured data stores complement centralized platform architectures. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with chief information security officers, SOC directors, vendor product managers, and financial services procurement leads with secondary validation from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, RBI circulars on digital payment fraud, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulate against top-down market sizing from platform revenue disclosures.
Rate-of-change decomposition separates baseline growth from regulatory acceleration effects and technology substitution patterns across the projection horizon. Segmentation dimensions modeled include solution architecture, underlying technology, end-use vertical, and deployment topology. CAGRs derive from weighted average of vendor guidance, procurement pipeline visibility, and regulatory timeline impacts. Forecast inputs incorporate GPU allocation pricing trajectories and EU AI Act enforcement phase transitions.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time SOC deployment metrics introduce uncertainty bands around edge analytics adoption velocity. Forecasts reflect documented assumptions on regulatory enforcement timing and hyperscaler infrastructure expansion plans. Deviation in EU AI Act audit intensity or NVIDIA GPU supply allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Middle East Geospatial Analytics Market
Analytics
Israel ICT Market
Analytics
Sentiment Analytics Market
Analytics
Europe Operational Intelligence Market
Analytics
Europe Predictive Analytics Market
Analytics
Active Data Warehousing Market
Analytics
CSP Network Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Voice Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Speech Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Patent Analytics Market
Analytics
Assortment Analytics Market