
 Contact Center Analytics Market | 2026-2036
Contact Center Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Center Analytics Market Intelligence
The capital-intensity divergence between cloud-native platforms and legacy on-premises incumbents is bifurcating competitive dynamics across the sector. NICE leverages its installed base in regulated industries to sustain premium positioning for workforce optimization suites. Genesys anchors its growth through open-API cloud architecture that competes directly with point-solution specialists. Five9 differentiates through native CRM integrations that dominate mid-market replacement cycles.
Contact center analytics encompasses software systems that capture, process, and interpret multimodal interaction data—voice, chat, email, and screen activity—using natural language processing engines that typically operate at sub-200-millisecond latency for real-time guidance. These systems serve the commercial purpose of converting unstructured customer conversations into structured intelligence for agent coaching, compliance verification, and revenue retention. Speech analytics and interaction analytics command the deepest margin pools as enterprises prioritize sentiment detection and automated quality scoring over basic reporting dashboards. Cloud-based deployment is expanding fastest as telecom and BFSI end users retire capital-heavy premises equipment, while hybrid configurations retain share among healthcare providers with segmented data sovereignty requirements.
The Federal Communications Commission shapes demand through robocall mitigation rules that mandate call authentication analytics, while the EU AI Act imposes risk-classification requirements on automated decision systems in customer interactions. India's TRAI QoS regulations and Germany's GDPR-aligned Bundesdatenschutzgesetz further constrain cross-border data architectures. Stakeholders must weigh compliance tooling investments against the operational flexibility of multi-tenant cloud stacks as jurisdictional fragmentation intensifies.
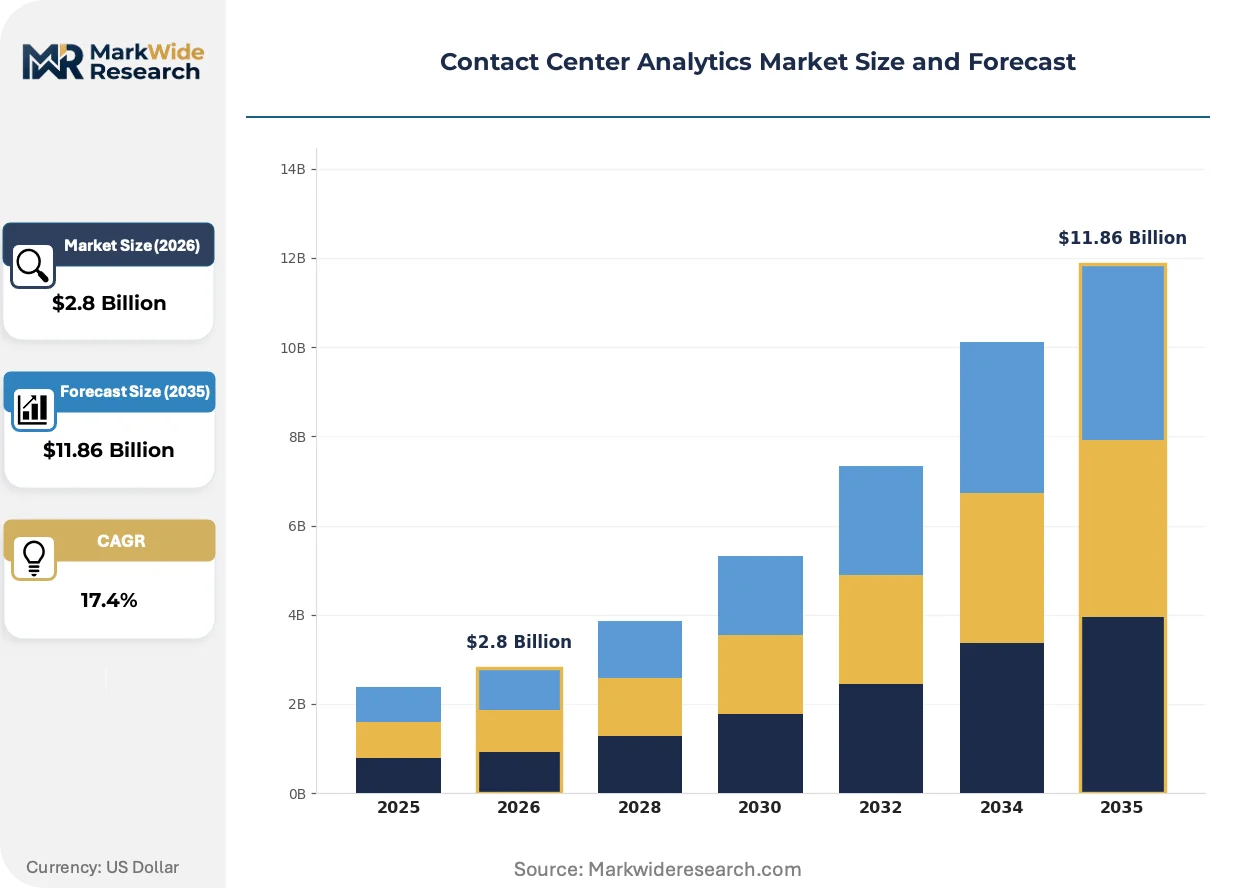
Market Dynamics
Cloud migration is fragmenting competitive positioning between legacy on-premises incumbents and API-native challengers, forcing incumbents to defend installed bases through hybrid deployment architectures while point-solution specialists capture greenfield cloud workloads.
Growth Catalysts
- AI Act compliance mandates:The EU AI Act's risk-classification requirements for automated customer interaction systems are accelerating procurement of sentiment detection and automated quality scoring modules across European banking and telecom operators.
- TRAI QoS enforcement:India's Telecom Regulatory Authority quality-of-service regulations are compelling domestic BFSI and telecom providers to deploy real-time speech analytics for call authentication and robocall mitigation.
- Real-time NLP latency thresholds:Sub-200-millisecond natural language processing engines are enabling live agent guidance during active customer conversations, converting post-call analytics into revenue retention tools.
Market Restraints
- Cross-border data sovereignty:Germany's Bundesdatenschutzgesetz and segmented healthcare data requirements are constraining multi-tenant cloud architectures, forcing redundant infrastructure investments.
- Legacy capital lock-in:Premises-based workforce optimization suites in regulated industries carry sunk costs that delay cloud replacement cycles despite superior unit economics of cloud-native platforms.
- Skills scarcity in conversational AI:Shortage of engineers capable of tuning NLP models for domain-specific sentiment detection is extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Mid-market CRM-native replacement cycles:Native Salesforce and Microsoft Dynamics integrations are creating entry points for cloud specialists to displace legacy reporting dashboards in sub-1,000-agent deployments.
- Healthcare hybrid configurations:Segmented data sovereignty requirements in US HIPAA-regulated providers and German healthcare systems are sustaining demand for on-premises speech analytics with cloud-based business intelligence layers.
- FCC robocall authentication:STIR/SHAKEN mandate implementation is generating incremental demand for call authentication analytics as a standalone compliance module.
Industry Challenges
- Integration complexity with CTI infrastructure:Legacy computer-telephony integration protocols require custom middleware development, extending deployment timelines and elevating project risk.
- Agent resistance to real-time surveillance:Workforce pushback against screen recording and live sentiment monitoring is elevating change management costs and depressing utilization rates.
- Jurisdictional compliance tooling fragmentation:Divergent regulatory requirements across US FCC, EU AI Act, and India TRAI are forcing vendors to maintain parallel product roadmaps, elevating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Center Analytics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Tenant Technology: Speech Analytics, Predictive Dialing, Workforce Management, Quality Monitoring End User: Telecom, Retail, BFSI, Healthcare Solution: Reporting & Analytics, Customer Experience Management, Performance Management, Interaction Analytics |
| Companies Covered | NICE, Genesys, Cisco Systems, Five9, Verint Systems, Oracle Corporation, 8x8, CallMiner, Talkdesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Center Analytics Market Strategic Shifts & Innovations
Real-time inference architectures are compressing the latency window between customer utterance and agent guidance, converting analytics from retrospective reporting into live intervention systems.
Multimodal interaction analytics is bifurcating competitive positioning between voice-centric incumbents and omnichannel-native platforms. The technology synthesizes voice, chat, email, and screen activity into unified agent scoring models. Banking and financial services institutions are adopting these platforms fastest to meet customer experience mandates. This convergence is bifurcating vendor strategies between depth in speech analytics and breadth across digital channels.
The EU AI Act's risk-classification framework for automated decision systems is mandating algorithmic audit trails in customer-facing analytics. Industrial consequence includes forced disclosure of sentiment model training data and decision logic to regulators. BFSI deployments in Germany and France are most affected, with institutions pre-emptively deploying explainable AI overlays to preempt compliance friction.
Consumption-based pricing models are displacing perpetual licenses in mid-market procurement. Buyers now prefer agent-month subscriptions with usage tiers over upfront capital commitments. This shift is most visible in United States and India, where cloud-native vendors are capturing replacement cycles through lower initial outlays and faster time-to-value metrics.
Contact Center Analytics Market Segmentation
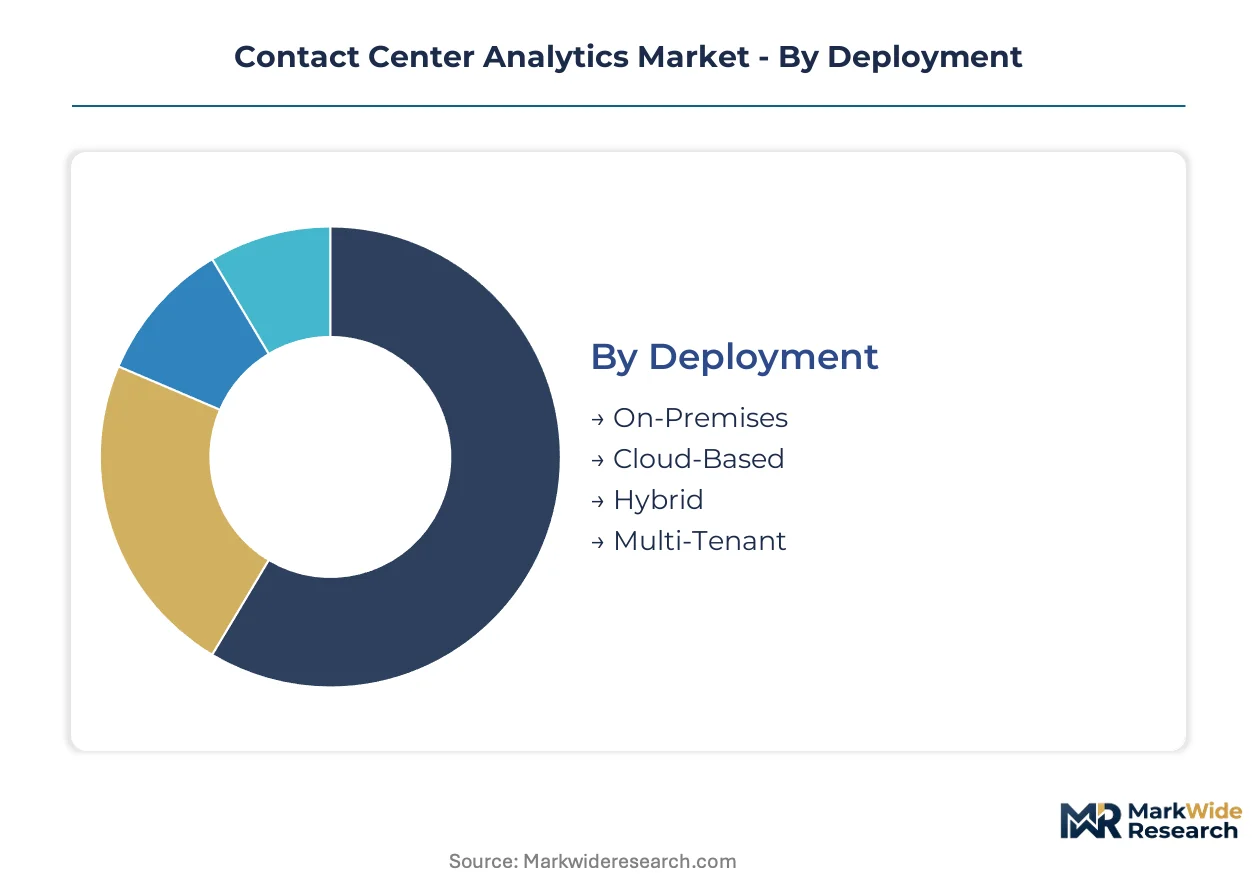
Contact center analytics vendors must navigate divergent buyer priorities across deployment models, technology stacks, and regulatory environments. Segmentation reveals where cloud-native substitutes threaten legacy incumbents and which solution bundles command premium positioning.
Deployment:
Cloud-based platforms face substitution pressure from hybrid architectures in regulated verticals where data sovereignty constrains pure SaaS adoption.
- Cloud-Based:Multi-tenant architectures with sub-200-millisecond NLP latency enable real-time agent guidance. Demand concentrates among United States mid-market enterprises retiring capital-heavy premises equipment for consumption-based pricing.
- Hybrid:Segmented configurations separate sensitive voice data on-premises from cloud-based business intelligence layers. German healthcare providers and US HIPAA-regulated systems deploy these to satisfy Bundesdatenschutzgesetz and state-level privacy mandates.
- On-Premises:Legacy workforce optimization suites in banking and telecom carry sunk costs that delay replacement despite superior cloud unit economics.
- Multi-Tenant:Shared infrastructure models reduce per-agent costs for sub-1,000-seat deployments in India and Southeast Asia.
Cloud-Based retains volume leadership; Hybrid holds the steepest expansion curve among regulated European and North American healthcare providers.
Technology:
Speech analytics commands the deepest margin pools as sentiment detection supersedes basic quality monitoring in procurement priorities.
- Speech Analytics:Natural language processing engines transcribe and analyze voice interactions for emotion detection and compliance scoring. EU AI Act risk-classification requirements are accelerating algorithmic audit trail deployments across French and German banking networks.
- Workforce Management:Scheduling and forecasting modules integrate with CRM platforms to optimize agent utilization. Native Salesforce and Microsoft Dynamics connectors dominate mid-market replacement cycles in the United States.
- Predictive Dialing:FCC STIR/SHAKEN mandates for call authentication are reshaping outbound campaign compliance requirements.
- Quality Monitoring:Automated scoring of recorded interactions faces workforce resistance that elevates change management costs.
Speech Analytics captures the largest revenue share; Workforce Management is gaining share fastest through CRM-native integration demand.
End User:
BFSI institutions generate the most complex procurement requirements as customer experience mandates collide with algorithmic transparency regulations.
- BFSI:Banking and financial services deploy multimodal analytics to unify voice, chat, and email into agent coaching workflows. India's TRAI QoS regulations compel real-time speech analytics adoption for call authentication.
- Telecom:Robocall mitigation rules from the FCC and similar authorities drive authentication analytics procurement.
- Healthcare:Segmented data sovereignty requirements sustain hybrid deployment demand across German and US systems.
- Retail:Seasonal volume volatility favors consumption-based pricing models for customer experience management.
BFSI dominates current procurement value; Healthcare is expanding most quickly as hybrid configurations penetrate regulated providers.
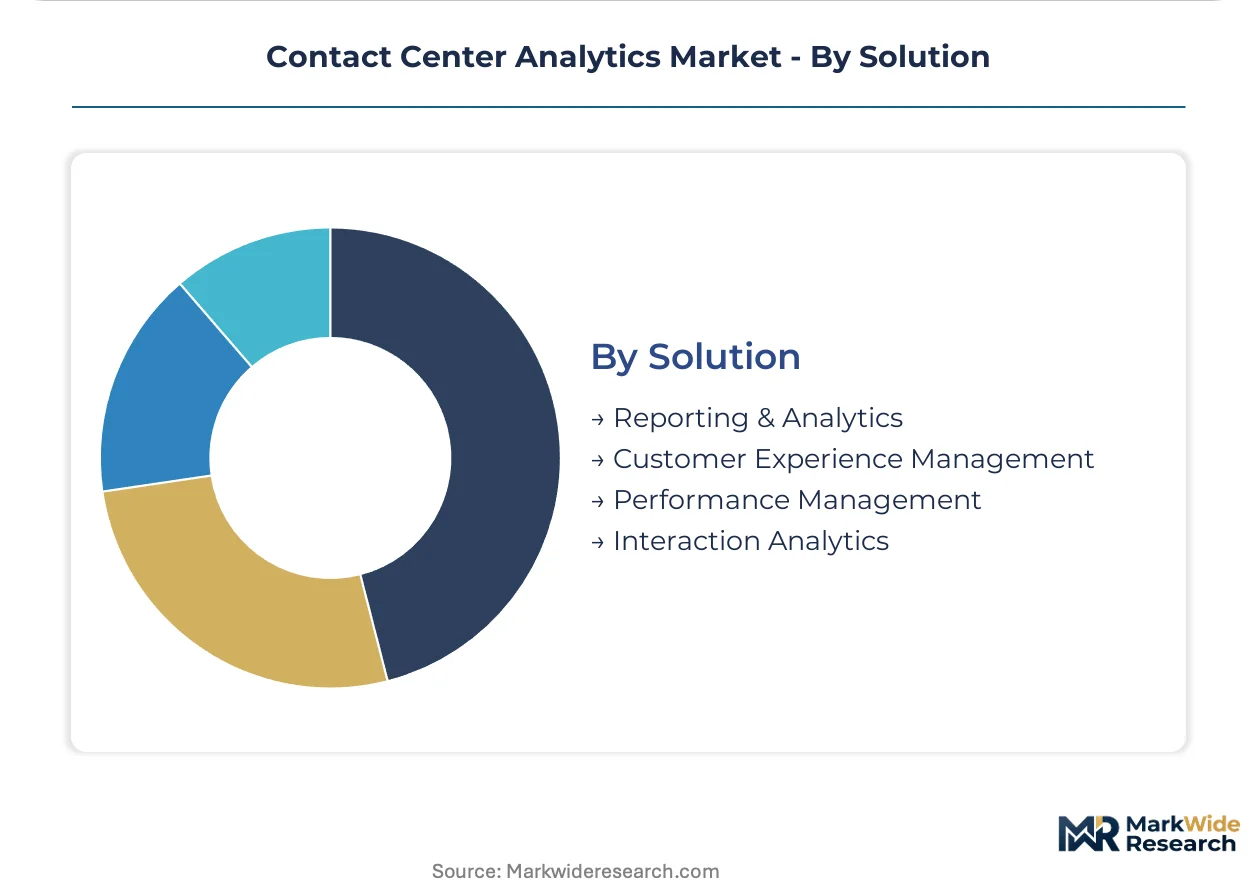
Solution:
Interaction analytics bundles face margin compression from point-solution specialists offering narrower but deeper channel-specific capabilities.
- Interaction Analytics:Omnichannel platforms synthesize voice, chat, email, and screen activity into unified scoring models. Banking networks in Germany and France prioritize these for EU AI Act compliance.
- Customer Experience Management:Journey orchestration tools integrate sentiment data with CRM records for revenue retention. United States and India mid-market buyers favor agent-month subscriptions over perpetual licenses.
- Performance Management:Agent coaching dashboards convert analytics into structured feedback loops for quality improvement.
- Reporting & Analytics:Basic visualization modules face displacement by embedded BI in CRM platforms.
Interaction Analytics leads solution category revenue; Customer Experience Management shows the steepest trajectory as journey orchestration demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a substantial margin, reflecting divergent cloud maturity and regulatory complexity. German buyers command premium positioning for compliance-heavy deployments. Japanese procurement concentrates on latency-sensitive real-time architectures.
United States
Mid-market enterprises retiring premises equipment drive consumption-based pricing adoption for cloud-native platforms. FCC robocall mitigation rules mandate STIR/SHAKEN call authentication analytics across telecom and BFSI operators. Silicon Valley and Austin clusters host the densest concentration of AI-native contact center startups competing with established incumbents.
Germany
Banking networks prioritize explainable AI overlays to preempt EU AI Act compliance friction in sentiment detection deployments. Bundesdatenschutzgesetz data sovereignty requirements sustain hybrid architecture demand among healthcare providers. Frankfurt's financial services corridor generates the most complex procurement requirements for algorithmic audit trail capabilities.
India
Domestic BFSI and telecom providers deploy real-time speech analytics to satisfy TRAI QoS regulations for call authentication. Multi-tenant cloud models reduce per-agent costs for sub-1,000-seat deployments across Mumbai and Bengaluru. India's IT services hubs export conversational AI engineering talent to Western markets, extending implementation timelines domestically.
United Kingdom
GDPR-aligned privacy mandates shape procurement preferences for on-premises voice data retention with cloud BI layers. London's insurance and fintech clusters drive demand for multimodal interaction analytics unifying voice, chat, and email. Post-Brexit regulatory divergence from EU AI Act creates uncertainty in automated decision system deployments.
Japan
Enterprises prioritize sub-200-millisecond NLP latency for live agent guidance during active customer conversations. METI industrial digitization programs accelerate cloud migration in legacy-heavy telecom and banking sectors. Tokyo-Osaka corridor concentrates demand for workforce optimization suites with native CRM integrations.
Contact Center Analytics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. The market consolidates around three strategic tiers: legacy on-premises incumbents defending installed bases, cloud-native specialists capturing greenfield workloads, and API-first platforms enabling ecosystem integration. Dominant competitive moves include hybrid deployment architecture development to bridge on-premises and cloud environments, and native CRM connector investments to accelerate mid-market replacement cycles.
Within the legacy incumbent tier, NICE and Genesys exemplify vendors leveraging regulated industry relationships to sustain premium positioning for workforce optimization suites. Five9 occupies a position among cloud-native specialists competing through native CRM integrations that dominate mid-market replacement cycles in the United States and India. Verint Systems represents the hybrid architecture approach, bridging on-premises voice data retention with cloud-based business intelligence layers to satisfy German and US healthcare data sovereignty requirements.
| Leading Market Players |
|---|
| NICE |
| Genesys |
| Cisco Systems |
| Five9 |
| Verint Systems |
| Oracle Corporation |
| 8x8 |
| CallMiner |
| Talkdesk |
| Others |
Cost & Logistics Intelligence
Consumption-based pricing models displacing perpetual licenses simultaneously redraw supply geography toward cloud infrastructure hubs and compress margin structures for on-premises incumbents. This substitution dynamic concentrates vendor investment in multi-tenant architectures while fragmenting downstream channel economics across agent-month subscription tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order deployments for German banking networks from standard SaaS tiers for United States mid-market buyers. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with EU AI Act compliance tooling commanding premium positioning and multi-tenant Indian deployments anchoring economy tiers. Price differentiation rests on latency-grade certification and vertical integration depth in NLP engine development. Cost compression in standard tiers is intensifying because cloud-native entrants compete on faster time-to-value metrics. Healthcare providers with segmented data requirements show least price sensitivity; Southeast Asian sub-1,000-seat buyers exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs for GPU clusters and specialized AI accelerators hinge on container availability through Shanghai-Singapore trade lanes and port congestion at Los Angeles-Long Beach. Component supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductors powering sub-200-millisecond inference engines. Raw material dependencies span high-bandwidth memory modules, custom ASICs, and optical transceivers for data center interconnects. Single-source vulnerability in advanced node fabrication presents structural risk for real-time NLP latency guarantees. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with professional services overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud migration fragmenting buyer preferences between real-time guidance and retrospective reporting creates specialized vendor niches across deployment models and compliance intensity tiers.
For Market Incumbents: Shield installed base relationships in regulated BFSI verticals through hybrid architecture investments that bridge on-premises voice retention with cloud BI layers. Fortify against API-native challengers by embedding explainable AI audit trails preemptively for EU AI Act risk-classification requirements. Prioritize certification depth over feature breadth to sustain premium positioning. For New Entrants and Emerging Players: Lead with native CRM connectors targeting Salesforce and Microsoft Dynamics ecosystems in United States and India mid-market replacement cycles. Capture white-space in healthcare hybrid configurations satisfying HIPAA and Bundesdatenschutzgesetz data sovereignty mandates. Penetrate through consumption-based pricing with sub-90-day implementation guarantees. For Investors and Strategic Acquirers: The EU AI Act's full risk-classification enforcement reshapes the acquisition landscape toward explainable AI specialists with algorithmic audit trail capabilities. Long-term viability centers on vendors bridging real-time inference latency with cross-border compliance tooling. Target acquisition archetypes include conversational AI engineering teams with domain-specific sentiment tuning expertise. Monitor TRAI QoS enforcement intensity as inflection indicator for Indian market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Development | Bridges on-premises voice data with cloud BI for German healthcare providers. |
| Native CRM Platform Integration | Captures mid-market replacement cycles through Salesforce and Dynamics connectors. |
| Explainable AI Overlay Investment | Preempts EU AI Act compliance friction in French and German banking networks. |
| Real-Time NLP Latency Optimization | Enables sub-200-millisecond agent guidance for revenue retention use cases. |
| Multi-Tenant Cloud Infrastructure Expansion | Reduces per-agent costs for Indian and Southeast Asian sub-1,000-seat deployments. |
Research Approach
Cross-validation between primary interviews with contact center operations directors, CTOs at BFSI institutions, and compliance officers anchors the qualitative findings against secondary validation through FCC rulemaking dockets, EU AI Act implementation guidance, and TRAI QoS enforcement records. Bottom-up triangulation against top-down market sizing incorporates hyperscaler capex disclosures and enterprise software procurement databases. Conversations with workforce optimization vendors, systems integrators, and channel partners inform deployment model adoption patterns.
Sensitivity analysis across deployment model, organization size, vertical regulatory intensity, and regional cloud maturity shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include cloud-native versus hybrid architectures, real-time versus retrospective analytics modes, and BFSI versus healthcare versus telecom end-use concentrations. CAGRs derive from agent-seat expansion rates, pricing model transition velocities, and compliance-driven replacement cycle timing. Industry-specific inputs encompass NLP engine latency benchmarks and algorithmic audit trail deployment costs.
Forecasts assume regulatory continuity in FCC STIR/SHAKEN mandates, EU AI Act risk-classification frameworks, and TRAI QoS enforcement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Streaming Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Practice Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Content Analytics Market
Analytics
Network Analytics Services Market
Analytics
Capacity Management Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Product Analytics Market
Analytics
Social Business Intelligence Market
Analytics
Global in-Store Analytics Market
Analytics
Legal Analytics Market
Analytics
Cyprus ICT Market