
 Europe HR Payroll Software Market | 2026-2036
Europe HR Payroll Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HR Payroll Software Market Analytics
The EU Green Deal's corporate sustainability reporting obligations is rebalancing how European employers track workforce carbon footprints alongside compensation data. Personio leverages its Munich headquarters to dominate DACH-region mid-market deployments. ADP sustains competitive positioning through its multi-country payroll engine spanning eurozone and non-eurozone jurisdictions. Sage Payroll anchors UK and Ireland market presence with deep tax compliance modules.
Europe HR Payroll Software encompasses cloud-native and on-premise platforms that automate wage calculation, statutory deductions, and regulatory filing across national tax regimes, typically integrating with ERP systems through standardized APIs to ensure real-time ledger reconciliation. Cloud-based deployment leads segment value as German and French employers retire legacy on-premise installations, while tax compliance functionality captures disproportionate R&D investment due to recurring regulatory churn across EU member states. Hybrid architectures serve multinational corporations requiring localized payroll sovereignty with centralized analytics.
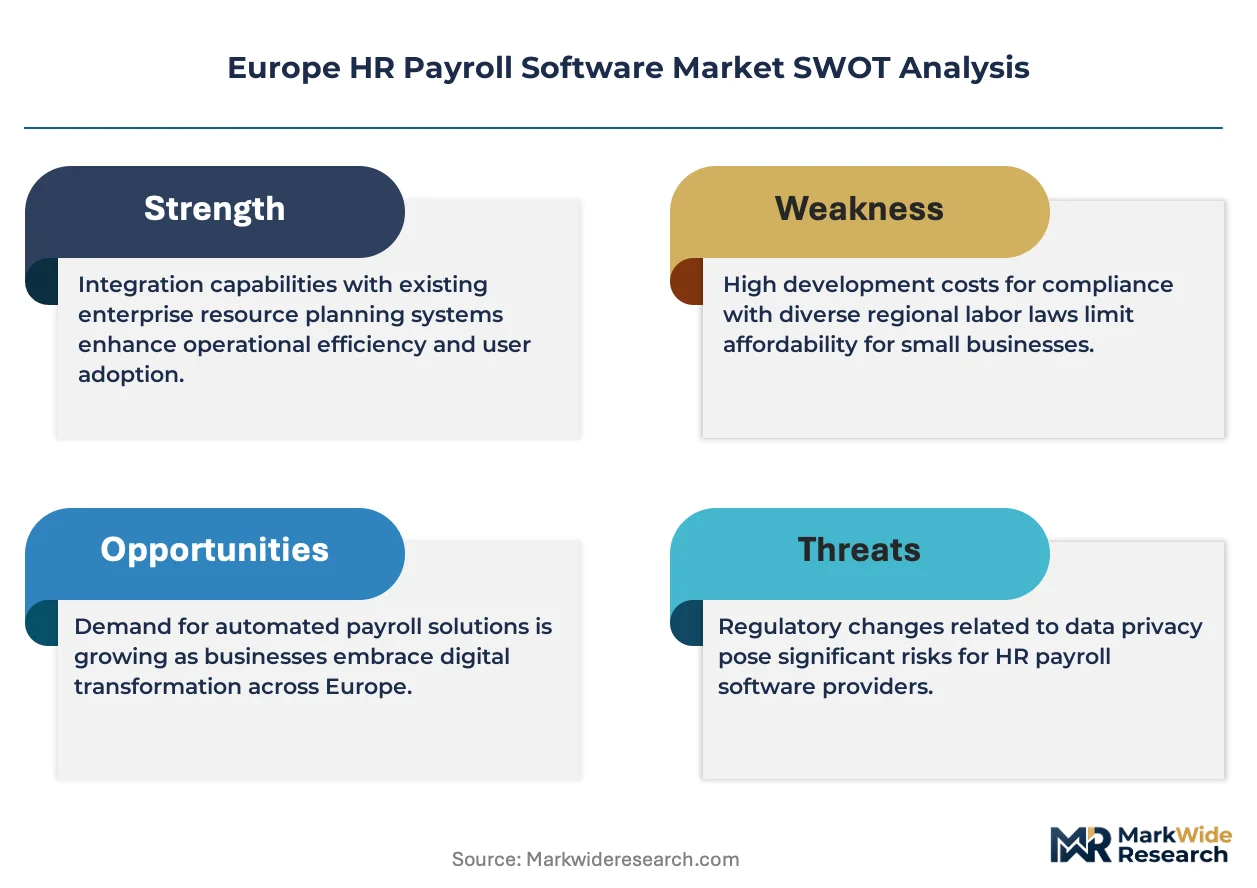
GDPR data residency rules, CSRD sustainability disclosure standards, and ECHA worker safety directives collectively elevate compliance automation from feature to procurement prerequisite for European HR technology buyers. The EU AI Act's risk classification framework for automated employment decision systems will further tighten algorithmic transparency requirements in payroll and benefits administration. Stakeholders must monitor divergence between EU-wide standards and member state labor code implementations that fragment platform configuration requirements.
Market Dynamics
The EU AI Act's risk classification framework for automated employment decision systems is compressing vendor development cycles while elevating compliance automation from feature to procurement prerequisite across German and French mid-market buyers.
Growth Catalysts
- CSRD Reporting Mandates:The EU Green Deal's corporate sustainability disclosure standards require workforce carbon footprint tracking alongside compensation data, forcing platform upgrades across Benelux employers.
- Cloud Migration Acceleration:German and French mid-sized enterprises are retiring legacy on-premise installations in favor of cloud-native architectures with real-time ledger reconciliation capabilities.
- Cross-Border Payroll Complexity:Multinational employers spanning eurozone and non-eurozone jurisdictions require multi-country payroll engines that automate statutory deductions across divergent national tax regimes.
Market Restraints
- GDPR Data Residency Compliance:Strict data localization requirements limit vendor flexibility in cloud infrastructure placement, increasing operational costs for platforms serving multiple EU member states.
- Fragmented Labor Code Implementation:Divergence between EU-wide standards and member state labor laws fragments platform configuration requirements, stretching R&D resources across jurisdiction-specific modules.
- Legacy System Entrenchment:Deep integration of existing payroll systems with national tax filing portals creates high switching costs for established employers in France and Germany.
Strategic Opportunities
- ECHA Worker Safety Directive Integration:Platforms that unify payroll data with occupational health reporting capture expanding compliance budgets from industrial employers in the DACH region.
- Hybrid Architecture Demand:Multinational corporations seek localized payroll sovereignty with centralized analytics, creating white space for vendors offering federated cloud deployments.
- Benelux Cross-Border Services:Complex multi-jurisdictional employment arrangements in Belgium, Netherlands and Luxembourg drive demand for specialized employer-of-record functionality.
Industry Challenges
- Algorithmic Transparency Requirements:The EU AI Act mandates explainability for automated wage and benefits decisions, forcing engineering teams to retrofit black-box machine learning models with auditable decision trails.
- API Standardization Gaps:Inconsistent ERP integration protocols across SAP, Oracle and Microsoft environments prolong implementation timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HR Payroll Software Market |
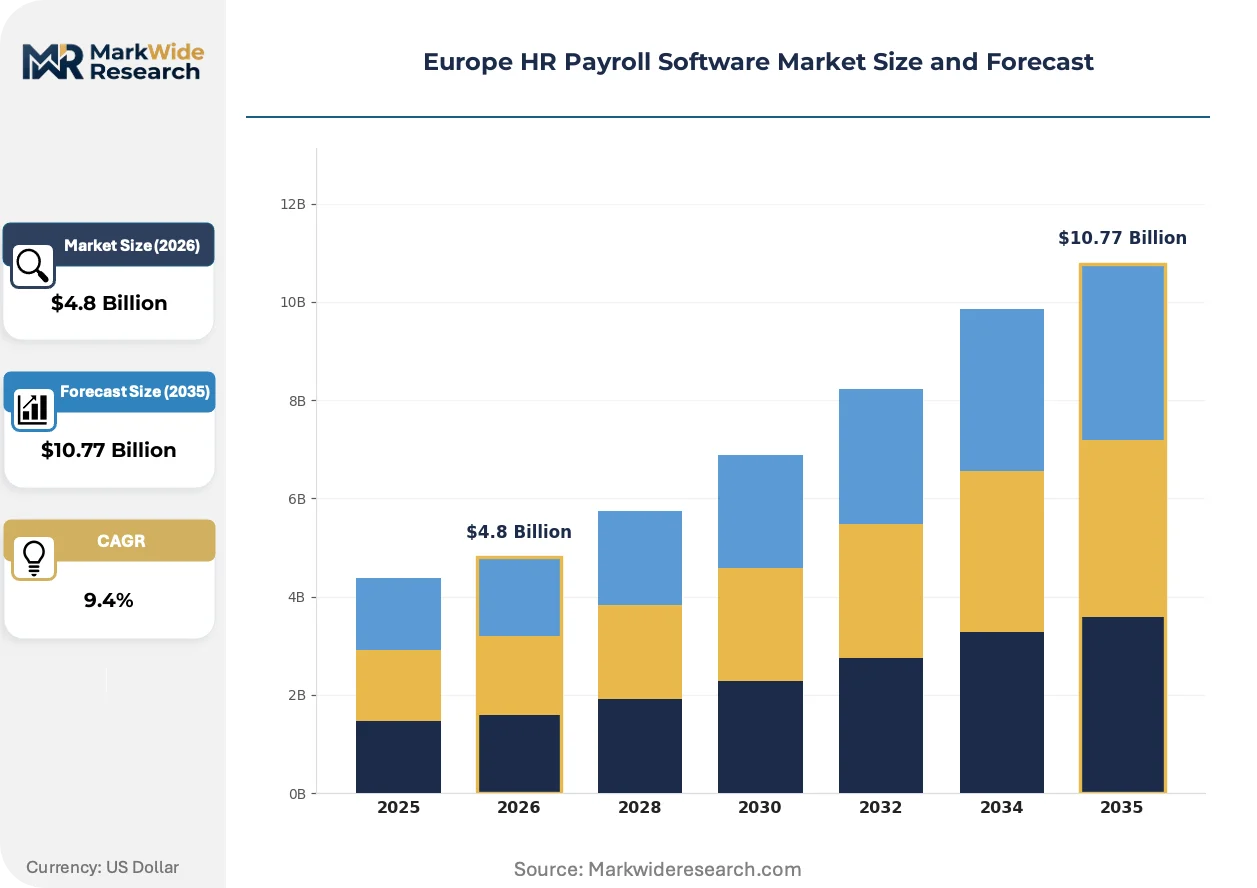
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, SaaS End User: Small Businesses, Medium Enterprises, Large Corporations, Startups Functionality: Time Tracking, Payroll Processing, Tax Compliance, Reporting Integration: APIs, ERP Systems, HRIS, Third-party Applications |
| Companies Covered | WorkMotion, BambooHR, ADP (Automatic Data Processing Inc.), TMF Group, Personio, Sage Payroll, Lano, BPiON, Zellis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HR Payroll Software Market Evolving Landscape
European HR payroll platforms are converging around embedded compliance engines that preempt regulatory churn rather than react to it, compressing the traditional patch-and-upgrade cycle into continuous policy synchronization.
Native AI-powered anomaly detection is overtaking rule-based validation engines in wage calculation modules. German automotive and French pharmaceutical employers are deploying these systems at scale to flag statutory deduction errors before regulatory filing. This capability is compressing audit remediation cycles from quarterly to real-time, reshaping how mid-market buyers evaluate platform maturity.
The EU AI Act's automated decision system provisions are mandating algorithmic impact assessments for payroll and benefits administration tools. Vendors must now document training data provenance and model drift metrics to maintain CE marking eligibility. French regulators at CNIL are enforcing these requirements most aggressively, creating a compliance template other member states are adopting.
Subscription-based platform access is displacing perpetual license models among mid-sized enterprises. French and German buyers now prioritize vendors offering usage-scaled pricing with embedded tax compliance updates rather than upfront capital expenditure. This rotation is most visible in the 500-5,000 employee segment, where CFOs favor operational expenditure classification for software procurement.
Europe HR Payroll Software Market Segmentation
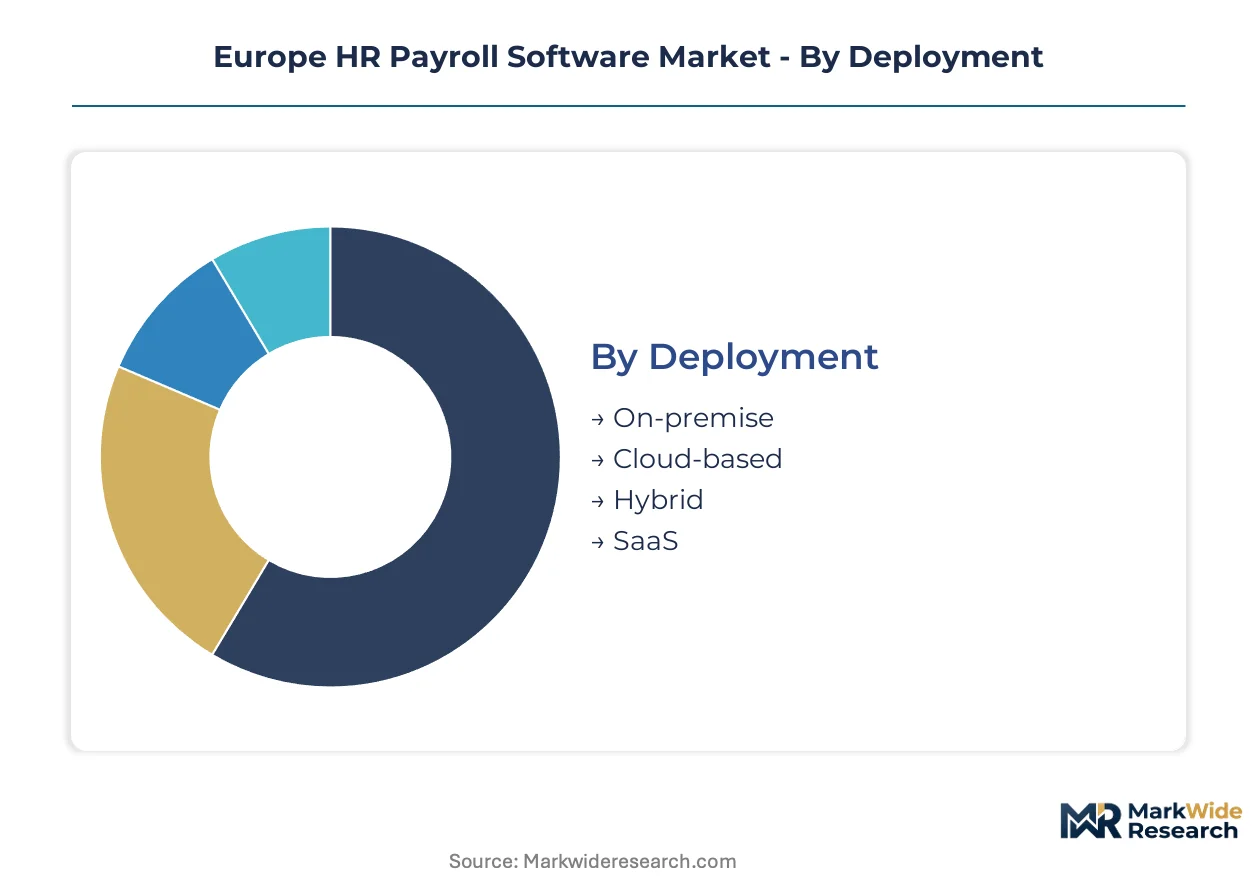
Payroll software segmentation in Europe reflects divergent compliance burdens and IT maturity across employer types. Cloud deployment models now dominate procurement decisions as GDPR data residency rules reshape infrastructure choices. Functional specialization varies sharply between mid-market buyers seeking bundled solutions and large corporations demanding modular architectures.
Deployment:
Customization versus standardization tension peaks in deployment architecture, where regulatory complexity collides with IT governance preferences across German, French, and Benelux employers.
- Cloud-based:Multi-tenant architectures with EU-region data residency certification capture mid-market demand in France and Germany. Real-time ledger reconciliation and automatic tax table updates drive replacement of legacy installations. German automotive suppliers and French pharmaceutical firms prioritize vendors with ISO 27001 and SOC 2 Type II attestations.
- SaaS:Subscription pricing with embedded compliance updates displaces perpetual licenses among 500-5,000 employee segments. French CFOs favor operational expenditure classification for software procurement, accelerating vendor transitions from on-premise models.
- Hybrid:Federated deployments serve multinational corporations requiring localized payroll sovereignty with centralized analytics. Belgium-Luxembourg cross-border employers deploy hybrid stacks to satisfy divergent national tax filing portal requirements.
- On-premise:Remains entrenched in German public sector and French state-owned enterprises with stringent data classification regimes.
Leading the category by volume: Cloud-based. Growing fastest: Hybrid architectures gaining share among eurozone multinationals.
End User:
Cost tier stratification separates self-service platforms from enterprise-grade implementations with dedicated compliance engineering.
- Medium Enterprises:500-5,000 employee organizations across Germany and France drive cloud migration velocity. These buyers demand pre-configured tax compliance modules for multi-jurisdictional operations without dedicated payroll IT staff. CSRD reporting mandates force platform upgrades as workforce carbon footprint tracking becomes mandatory.
- Large Corporations:Multi-country payroll engines spanning eurozone and non-eurozone jurisdictions require API-first architectures. Benelux-headquartered multinationals prioritize vendors with localized tax engines for Belgium, Netherlands, and Luxembourg administered through unified interfaces.
- Small Businesses:Personio and similar DACH-region platforms dominate with standardized workflows for sub-200 employee organizations.
- Startups:Employer-of-record functionality gains traction among venture-backed firms with distributed European workforces.
Volume concentration: Medium Enterprises. Steepest expansion trajectory: Large Corporations upgrading from fragmented country-specific systems.
Functionality:
Application criticality elevates tax compliance from feature to procurement prerequisite as regulatory churn accelerates across EU member states.
- Tax Compliance:Automated statutory deduction engines with real-time updates for national tax regime changes capture disproportionate R&D investment. German and French vendors allocate engineering resources to jurisdiction-specific modules addressing divergence between EU-wide standards and member state labor codes. CNIL-enforced algorithmic transparency requirements under the EU AI Act mandate auditable decision trails in automated wage calculations.
- Payroll Processing:Core wage calculation engines with native AI-powered anomaly detection overtake rule-based validation. German automotive employers deploy these systems to flag statutory deduction errors before regulatory filing, compressing audit remediation cycles.
- Time Tracking:Integration with ECHA worker safety directives expands compliance automation budgets from industrial employers in the DACH region.
- Reporting:CSRD-aligned sustainability disclosure templates embed workforce carbon footprint metrics alongside compensation data.
Dominant by procurement priority: Tax Compliance. Expanding most quickly: Reporting modules with CSRD sustainability integration.
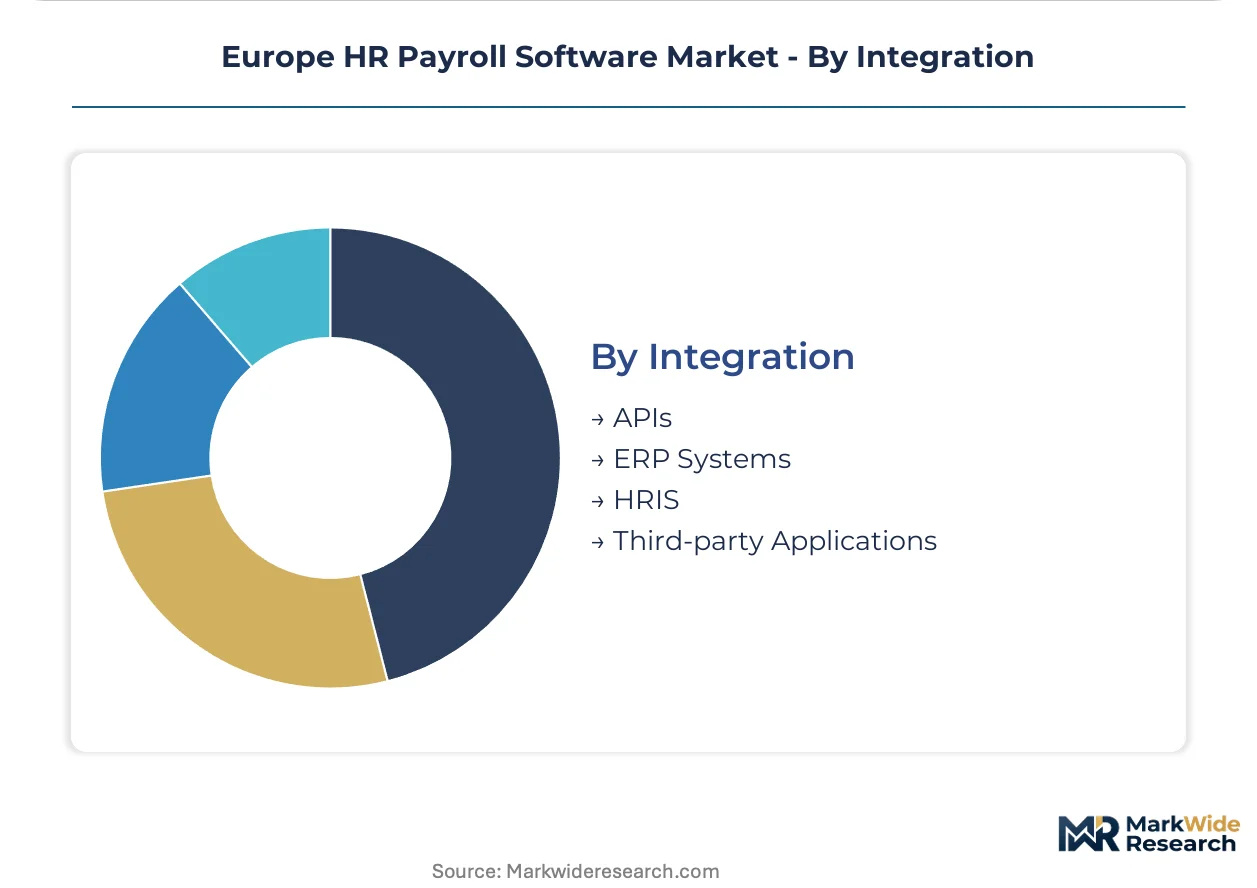
Integration:
Supply concentration among ERP incumbents creates interoperability bottlenecks that prolong implementation timelines.
- ERP Systems:SAP, Oracle, and Microsoft environments demand vendor-specific connector development, inflating professional services costs. German mid-market buyers prioritize pre-built SAP S/4HANA integrations. French employers with Oracle Cloud ERP deployments require localized payroll adapters.
- APIs:Standardized REST and GraphQL interfaces enable real-time data exchange between payroll platforms and financial planning systems. Benelux fintech integrations drive demand for open banking-compatible payroll APIs.
- HRIS:Bi-directional synchronization with talent management platforms supports workforce planning analytics.
- Third-party Applications:Benefits administration and pension platform connectors address French and German mandatory occupational scheme requirements.
Highest implementation complexity: ERP Systems. Gaining adoption fastest: API-first architectures decoupling payroll from monolithic enterprise stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European HR payroll software development through its dense concentration of enterprise software engineering talent and proximity to DAX-listed industrial employers demanding sophisticated compliance automation.
Germany
Automotive suppliers in Baden-Württemberg and pharmaceutical manufacturers in Bavaria drive cloud migration of payroll systems. The KBA enforces strict data residency requirements for workforce management platforms processing employee information. Berlin-Brandenburg hosts emerging SaaS vendors targeting mid-sized enterprises with subscription-based compliance solutions.
France
CNIL's aggressive enforcement of EU AI Act algorithmic transparency provisions compresses vendor development cycles for automated wage calculation engines. Pharmaceutical clusters in Île-de-France and industrial employers in Auvergne-Rhône-Alpes prioritize platforms with auditable decision trails. The Paris metropolitan area concentrates employer-of-record services for cross-border workforce arrangements.
United Kingdom
Post-Brexit divergence from EU labor standards fragments payroll platform configuration requirements for multinational employers maintaining continental operations. London's financial services sector demands real-time ledger reconciliation with multi-jurisdictional tax compliance. The Midlands manufacturing corridor sustains demand for hybrid architectures integrating legacy on-premise installations with cloud analytics.
Netherlands
Randstad's concentration of European headquarters for multinational corporations drives demand for multi-country payroll engines spanning eurozone and non-eurozone jurisdictions. The Dutch Data Protection Authority enforces GDPR data localization requirements that limit vendor cloud infrastructure flexibility. Eindhoven's high-tech industrial employers prioritize platforms with embedded CSRD sustainability reporting templates.
Belgium
Brussels-based EU institutions and lobbying organizations create specialized demand for cross-border employer services managing complex multi-jurisdictional employment arrangements. The Belgian Data Protection Authority coordinates with French and Dutch regulators on harmonized enforcement of automated decision system provisions. Flanders' logistics and pharmaceutical clusters deploy hybrid payroll architectures to satisfy divergent national tax filing portal requirements.
Europe HR Payroll Software Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with deep jurisdictional tax expertise. Consolidation pressure concentrates among mid-market platforms serving 500-5,000 employee organizations, while fragmentation persists in the employer-of-record segment addressing distributed workforces. Two strategic archetypes dominate: DACH-region platforms leveraging proximity to industrial compliance demand, and Anglo-American vendors with multi-country payroll engines. Competitive moves center on API-first architecture development and federated cloud deployment capabilities for hybrid infrastructure requirements.
Within the DACH-region specialist tier, Personio and BPiON exemplify platforms built around German-speaking market compliance complexity. ADP represents the multi-country engine archetype with established positioning across eurozone and non-eurozone jurisdictions. Sage Payroll anchors UK and Ireland market presence through deep tax compliance module development.
| Leading Market Players |
|---|
| WorkMotion |
| BambooHR |
| ADP (Automatic Data Processing Inc.) |
| TMF Group |
| Personio |
| Sage Payroll |
| Lano |
| BPiON |
| Zellis |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ISO 27001-attested cloud platforms and uncertified alternatives bifurcates European HR payroll software procurement, with compliance-heavy German automotive suppliers absorbing premium pricing while Benelux mid-market buyers gravitate toward standardized SaaS tiers. This tier split feeds back into vendor infrastructure choices, compelling multi-tenant architectures with EU-region data residency over cost-optimized global cloud deployments.
Pricing Analysis
Value-based pricing anchored to compliance automation outcomes dominates European HR payroll software procurement, with French CFOs prioritizing operational expenditure classification for subscription models with embedded tax table updates. Price differentiation hinges on GDPR data residency certification and real-time ledger reconciliation capabilities, with certified platforms commanding substantial premiums over uncertified alternatives. Pricing pressure stems from subscription fatigue among 500-5,000 employee segments seeking usage-scaled alternatives to per-seat models. Small businesses exhibit highest price sensitivity, while multinational corporations with cross-border payroll complexity demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Freight and data sovereignty costs concentrate software development gravity in Germany, France, and the Netherlands, where proximity to DAX and CAC-listed industrial employers reduces implementation travel and regulatory interpretation overhead. Engineering talent pipelines draw from Munich, Paris, and Amsterdam metropolitan clusters, with cloud infrastructure sourcing tethered to EU-region hyperscaler availability zones. Single-source vulnerability manifests in concentrated SAP S/4HANA integration specialist pools. Distribution runs through direct enterprise sales teams serving large corporations, supplemented by channel partners addressing mid-market velocity in the DACH region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European HR payroll software functions as a cost-of-compliance market where the EU AI Act's algorithmic transparency mandates erect formidable barrier-to-entry moats, favoring incumbents with established CE marking pathways and documented model governance infrastructure.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by accelerating federated hybrid architecture development for multinational sovereignty requirements. Defensive consolidation should prioritize jurisdiction-specific tax engine acquisitions in Belgium and Luxembourg, where cross-border complexity outstrips organic R&D velocity. Vertical integration into embedded CSRD reporting modules captures expanding compliance budgets from Eindhoven high-tech industrial employers. For New Entrants and Emerging Players: Enter via employer-of-record functionality white space serving venture-backed distributed workforces with complex multi-jurisdictional arrangements. The Benelux cross-border services segment offers lowest competitive density relative to compliance complexity, particularly for Brussels-based EU institutions with specialized employment structures. Go-to-market positioning should emphasize API-first architectures with open banking-compatible payroll interfaces. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multi-country payroll engine vendors seeking DACH-region tax compliance depth. Long-term viability favors platforms with demonstrated CNIL algorithmic audit resilience and continuous policy synchronization engines rather than patch-reactive architectures. Watch CNIL enforcement intensity against non-compliant automated decision systems as inflection indicator for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU AI Act compliance secures market access for automated wage calculation engines across member states. |
| API-First Architecture Development | REST and GraphQL interfaces decouple payroll from monolithic SAP and Oracle ERP stacks. |
| Hybrid Cloud Deployment | Federated architectures satisfy Belgian and Luxembourg divergent tax filing portal requirements. |
| CSRD Reporting Module Integration | Workforce carbon footprint tracking captures sustainability disclosure budgets from Eindhoven employers. |
| Jurisdiction-Specific Tax Engine Acquisition | Belgium-Luxembourg compliance modules accelerate multi-country payroll engine completeness. |
Research Methodology
Document review covered regulatory filings with CNIL and KBA, vendor ISO certification databases, and CSRD implementation guidance, complemented by interviews with HR technology procurement officers, payroll operations directors at German automotive suppliers, French pharmaceutical compliance leads, and Benelux fintech integration specialists. Secondary validation drew from ECHA worker safety directive updates, EU AI Act delegated acts, and cloud infrastructure hyperscaler region disclosures. Bottom-up deployment model sizing and top-down regulatory impact assessment were triangulated against primary field intelligence.
Cross-referencing historical adoption curves against panel input from CTOs and CFOs across the 500-5,000 employee segment shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, organization size tier, functionality specialization, and regional regulatory cluster complexity. CAGRs were derived from iterative reconciliation of vendor pipeline data with macroeconomic labor market indicators. Industry-specific forecast inputs encompassed GDPR enforcement variance across national data protection authorities and EU AI Act implementation timeline uncertainty.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged member state labor code divergence. Forecasts reflect documented assumptions regarding cloud migration velocity and compliance budget allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Visitor Identification Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Media Editing App Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Global Decision Support Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
School Timetable Software Market
Software & Services
Mobile Application Development Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
HSM-As-A-Service Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Enterprise Mobility Software Market