
 Advanced Process Control Software Market | 2026-2036
Advanced Process Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Process Control Software Market Analysis
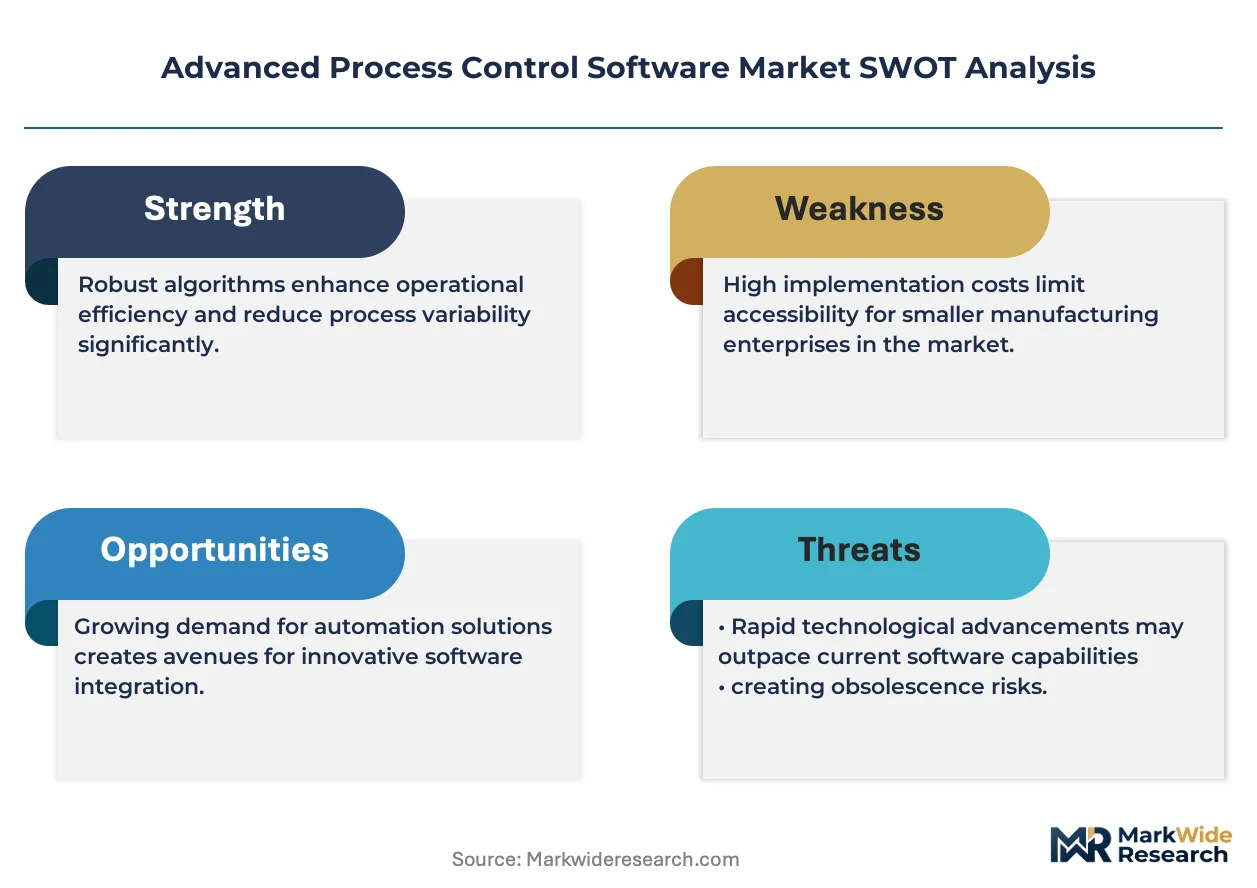
Germany's chemical corridor is reconfiguring how European process manufacturers evaluate control software procurement. Emerson Electric Co. leverages deep vertical expertise in hydrocarbon processing to sustain long-term contracts with major refiners. Honeywell International Inc. anchors its position through backward integration into sensor hardware and distributed control system architectures. Siemens AG competes by bundling advanced process control with digital twin platforms for pharmaceutical manufacturing.
Advanced Process Control Software encompasses model-predictive algorithms, statistical process control modules, and real-time optimization engines that adjust manufacturing variables within operational constraints to maximize yield and minimize energy consumption. The software typically interfaces with distributed control systems through OPC-UA or proprietary protocols, executing setpoint changes every 1-60 seconds depending on process dynamics. Chemical Processing applications generate the deepest margin pools due to complex reaction kinetics and strict quality specifications, while Cloud-Based deployment is expanding fastest as energy providers seek remote diagnostics for geographically dispersed assets. System Integrators represent a concentrated channel for vendor access to mid-sized manufacturers lacking in-house automation expertise.
The US EPA mandates continuous emissions monitoring under Clean Air Act protocols, forcing oil and gas operators to upgrade from basic regulatory control to advanced multivariable systems that predict and prevent exceedances. The EU F-Gas Regulation and REACH compliance frameworks require chemical processors to document process conditions with auditable data trails, elevating software with embedded electronic batch recording. Germany's KBA and France's ANSM enforce sector-specific traceability standards that shape product requirements for pharmaceutical and automotive suppliers. Stakeholders must weigh cloud dependency risks against the operational resilience of hybrid architectures as cyber insurance underwriters tighten coverage terms for critical infrastructure software.
Market Dynamics
The US EPA's methane emissions rules are compressing upgrade cycles for oil and gas operators, forcing replacement of basic regulatory control with predictive systems that anticipate exceedances rather than react to them. This regulatory pressure is reshaping procurement priorities across downstream processing.
Growth Catalysts
- REACH compliance frameworks:The EU's chemical documentation mandates require auditable process data trails, elevating demand for software with embedded electronic batch recording capabilities.
- Permian Basin throughput optimization:Oil and gas operators are expanding multivariable predictive control deployment to maximize refinery output amid volatile feedstock quality.
- Cloud-based remote diagnostics:Energy providers with geographically dispersed assets are adopting hosted platforms to centralize monitoring and reduce on-site engineering headcount.
Market Restraints
- Specialized engineering talent scarcity:Model-predictive control implementation requires expertise in process dynamics and optimization mathematics that remains concentrated among system integrators.
- Legacy DCS integration friction:Proprietary protocols from established automation vendors create technical barriers when connecting advanced optimization layers to existing distributed control infrastructure.
- Cyber insurance coverage tightening:Underwriters are restricting policy terms for critical infrastructure software, raising total cost of ownership for cloud-dependent architectures.
Strategic Opportunities
- Pharmaceutical digital twin convergence:Regulatory pressure from FDA process analytical technology initiatives is opening demand for integrated control and simulation platforms in drug manufacturing.
- Mid-sized manufacturer channel access:System integrators represent a concentrated pathway to reach manufacturers lacking in-house automation expertise for APC deployment.
- Hybrid architecture resilience:Cyber-physical segmentation between edge optimization and cloud analytics addresses insurer concerns while preserving remote diagnostic benefits.
Industry Challenges
- OPC-UA protocol standardization gaps:Interoperability between multivendor control layers remains inconsistent, complicating multi-site rollout programs.
- Process model maintenance burden:Empirical models require continuous recalibration as catalysts degrade and equipment fouls, consuming engineering resources.
- Real-time optimization latency:Setpoint execution windows of 1-60 seconds strain network infrastructure when consolidating sensor feeds from geographically separated units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Process Control Software Market |
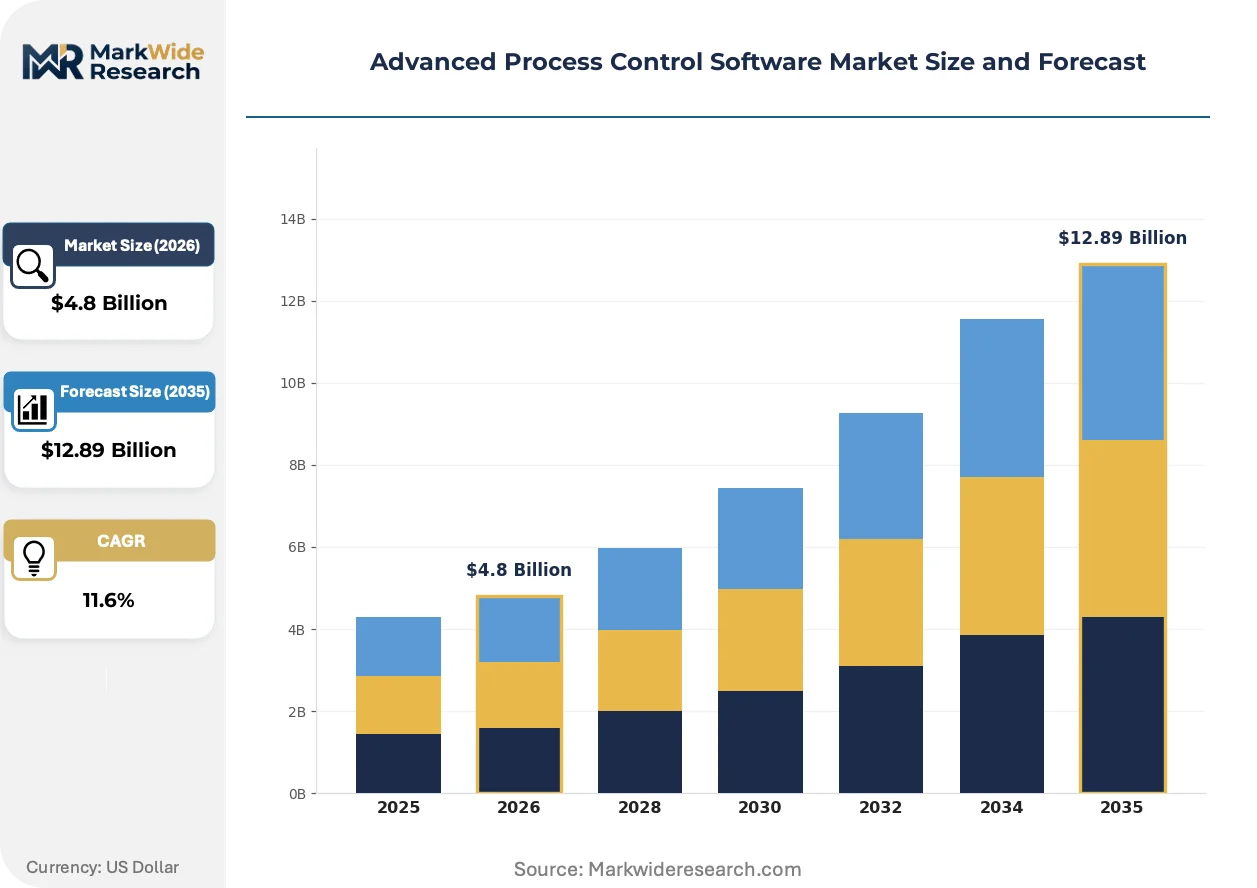
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Chemical Processing, Oil & Gas, Food & Beverage, Pharmaceuticals Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service End User: Manufacturers, Energy Providers, Research Labs, System Integrators Functionality: Real-Time Monitoring, Data Analysis, Control Optimization, Performance Management |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., Aspen Technology Inc., ABB Ltd., Schneider Electric SE, Rockwell Automation Inc., Siemens AG, General Electric Company, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Process Control Software Market Emerging Trajectories
Artificial intelligence is compressing the traditional model-building cycle, enabling adaptive control strategies that self-tune to shifting process conditions without manual engineering intervention.
Digital twin platforms are digitizing the validation workflow for pharmaceutical batch processes, allowing virtual commissioning of control strategies before physical deployment. FDA process analytical technology guidelines are accelerating adoption among sterile injectable manufacturers. The structural consequence is collapsing the traditional six-month startup timeline for new production lines.
The EU F-Gas Regulation is mandating leak detection and repair protocols for fluorinated gas handling, forcing chemical processors to upgrade from periodic manual inspection to continuous automated monitoring. BASF and Bayer operations in Ludwigshafen and Leverkusen are deploying integrated sensor networks with embedded regulatory reporting. This is elevating software procurement decisions to site-wide architecture choices rather than unit-level upgrades.
Service unbundling is fragmenting the traditional bundled maintenance model, with operators separating control optimization from hardware support contracts. Mid-sized refiners in the US Gulf Coast are engaging specialized APC consultants on outcome-based terms rather than incumbent DCS vendor packages. Germany's chemical corridor exhibits the most advanced procurement sophistication, with detailed performance guarantees written into software licensing agreements.
Advanced Process Control Software Market Segmentation
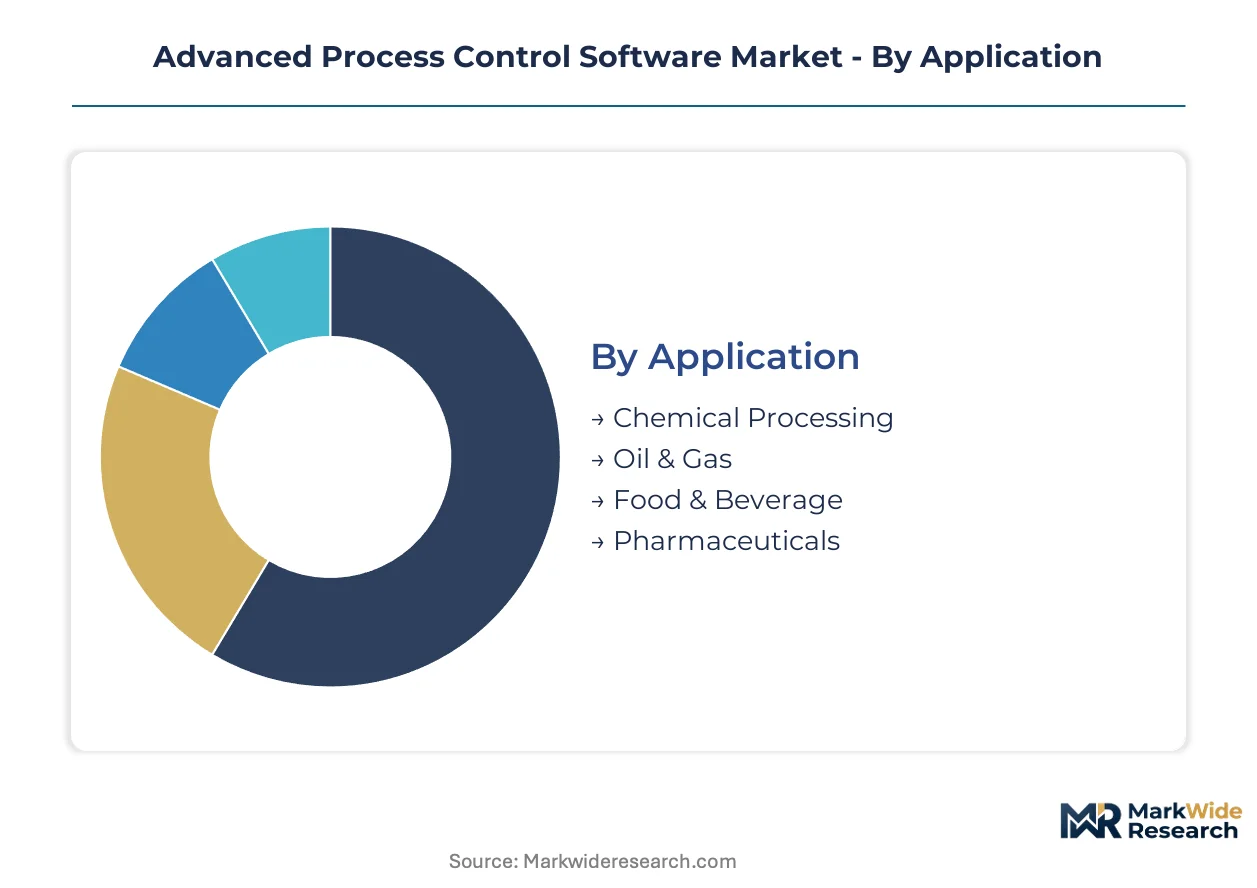
Advanced process control software segments diverge sharply by technical complexity and buyer sophistication. Chemical processors demand multivariable predictive algorithms with embedded regulatory compliance, while energy providers prioritize remote diagnostic architectures for dispersed assets.
Application:
Mature process industries anchor procurement volumes, while emerging sectors accelerate adoption as regulatory pressure intensifies.
- Chemical Processing:Complex reaction kinetics and strict quality specifications drive demand for model-predictive control with embedded electronic batch recording. Demand concentrates in Germany's Ludwigshafen and Leverkusen corridor, where BASF and Bayer operations require REACH-compliant auditable data trails.
- Oil & Gas:Multivariable predictive control optimizes refinery throughput amid volatile Permian Basin feedstock quality. US EPA methane emissions rules force upgrades from basic regulatory control to anticipatory systems that predict exceedances rather than react to them.
- Food & Beverage:HACCP-aligned process control with automated deviation logging for perishable production lines.
- Pharmaceuticals:FDA process analytical technology guidelines accelerate digital twin adoption for sterile injectable manufacturing.
Chemical Processing handles the majority of throughput; Pharmaceuticals is expanding most quickly on share.
Deployment Model:
Cost tier stratification separates capital-intensive on-site installations from operational-expense-driven hosted alternatives.
- On-Premise:Full hardware ownership with dedicated server infrastructure for latency-sensitive setpoint execution. Major refiners favor this architecture for cyber-physical segmentation that satisfies tightening cyber insurance underwriter requirements.
- Cloud-Based:Centralized hosting enables remote diagnostics for geographically dispersed energy assets without on-site engineering headcount. Fastest expansion trajectory among deployment options as mid-sized manufacturers seek to bypass in-house automation expertise gaps.
- Hybrid:Edge optimization layers combined with cloud analytics address insurer concerns while preserving remote monitoring benefits.
- Managed Service:Outcome-based contracts with specialized APC consultants replacing traditional bundled DCS vendor maintenance packages.
On-Premise retains the largest installed base; Cloud-Based is gaining share fastest.
End User:
Customer type determines procurement channel and implementation complexity, from direct enterprise sales to integrator-mediated deployments.
- Manufacturers:Integrated chemical and pharmaceutical producers with captive engineering teams capable of model maintenance and continuous recalibration.
- Energy Providers:Oil and gas operators with geographically dispersed assets seeking centralized monitoring platforms.
- Research Labs:Pilot-scale facilities requiring flexible control architectures for experimental process development.
- System Integrators:Concentrated channel for vendor access to mid-sized manufacturers lacking in-house automation expertise for APC deployment.
Manufacturers dominate current procurement; System Integrators are climbing the fastest as channel intermediation deepens.
Functionality:
Margin concentration follows technical depth, with optimization engines commanding premium pricing against basic monitoring modules.
- Real-Time Monitoring:Continuous sensor data aggregation with 1-60 second execution windows for dynamic process variables.
- Data Analysis:Statistical process control modules identifying deviation patterns for quality assurance documentation.
- Control Optimization:Model-predictive algorithms adjusting manufacturing variables within operational constraints to maximize yield and minimize energy consumption. Demand concentrates where empirical model maintenance burden can be absorbed by specialized engineering teams.
- Performance Management:Enterprise dashboards consolidating multi-site KPIs with embedded regulatory reporting for EU F-Gas and REACH frameworks.
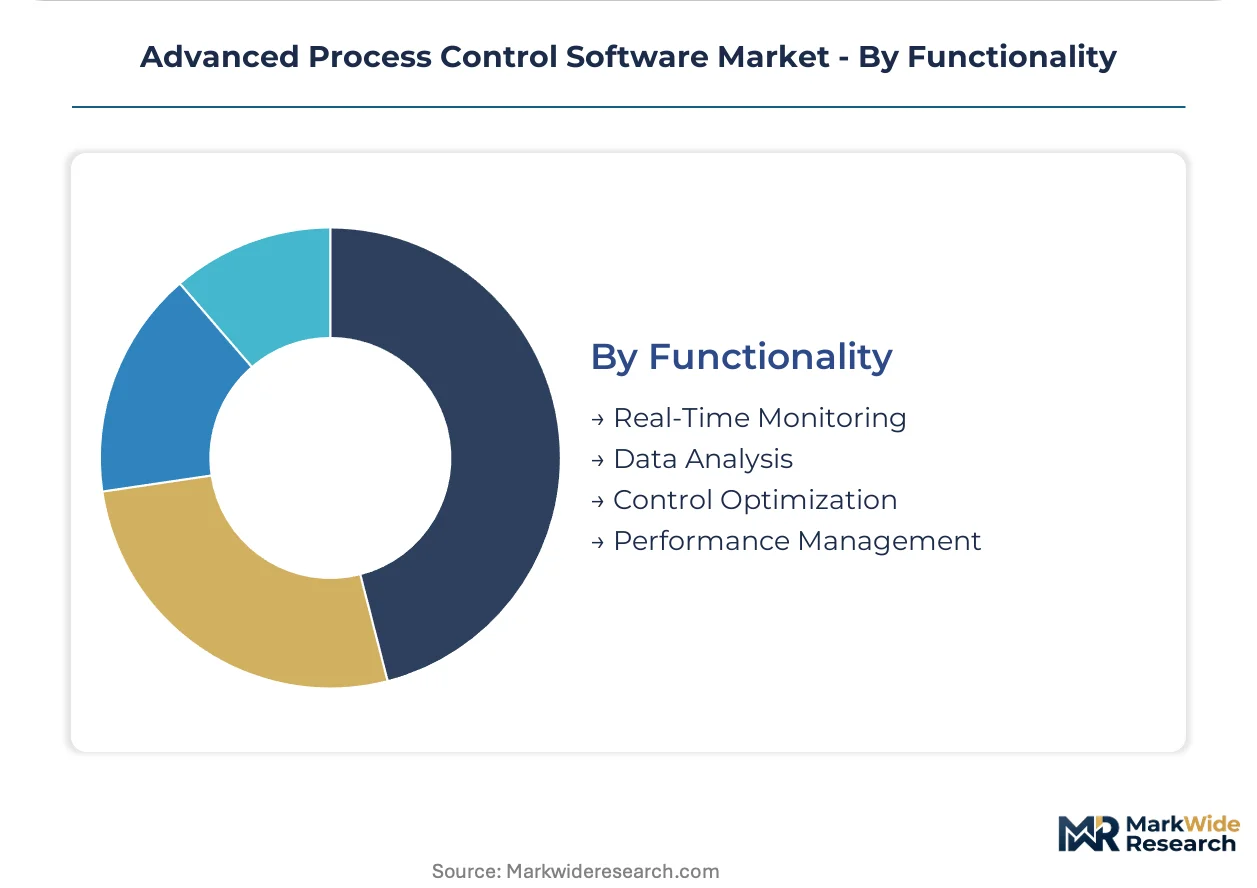
Control Optimization generates the deepest margin pools; Performance Management is expanding most quickly as compliance documentation requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US operators prioritize emissions-driven control upgrades, while German chemical processors anchor procurement around REACH compliance documentation. Asian markets concentrate deployment in electronics manufacturing corridors.
United States
Permian Basin refiners and Gulf Coast petrochemical operators drive multivariable predictive control adoption amid volatile feedstock quality. EPA methane emissions rules under the Clean Air Act compress upgrade cycles from basic regulatory systems to anticipatory exceedance prevention. Houston and Beaumont host concentrated deployment of remote diagnostic platforms for geographically dispersed upstream assets.
Germany
BASF and Bayer operations in Ludwigshafen and Leverkusen anchor European demand for integrated process control networks with embedded electronic batch recording. REACH compliance frameworks mandate auditable data trails for chemical documentation. The country's KBA enforces automotive sector traceability standards that shape supplier software requirements across Baden-Württemberg manufacturing clusters.
China
State-owned refiners and private chemical conglomerates deploy advanced process control across Yangtze River Delta and Pearl River Delta manufacturing bases. NMPA pharmaceutical regulations and MIIT industrial standards accelerate digital twin adoption for sterile drug manufacturing. Sinopec operations in Shandong and Zhejiang provinces represent concentrated demand for real-time optimization engines.
Saudi Arabia
Saudi Aramco and SABIC operations in the Eastern Province drive deployment of model-predictive algorithms for complex refinery and petrochemical integration. The country's national environmental regulator enforces escalating emissions monitoring requirements for continuous automated systems. Jubail Industrial City hosts the most sophisticated integrated control deployments outside Western markets.
Japan
Precision chemical and pharmaceutical manufacturers in the Kanto and Kansai regions prioritize statistical process control modules for strict quality specifications. METI industrial policy supports digital twin validation workflows under PMDA pharmaceutical guidelines. Osaka-based electronics materials producers represent specialized demand for sub-second setpoint execution in semiconductor precursor manufacturing.
Advanced Process Control Software Market Vendor Landscape
Capability concentration sits with specialized optimization software vendors; scale advantage sits with diversified automation conglomerates. The market structures around three tiers: pure-play algorithm developers, integrated hardware-software platforms, and system integrators delivering outcome-based deployment. Dominant competitive moves include backward integration into sensor hardware and strategic unbundling of maintenance contracts from traditional bundled DCS vendor packages.
Within the diversified automation tier, Emerson Electric Co., Honeywell International Inc., and Siemens AG exemplify contrasting geographic and vertical positioning strategies. Emerson leverages hydrocarbon processing expertise through long-term refinery relationships. Honeywell anchors market presence through captive sensor hardware and distributed control system architectures. Siemens competes by bundling advanced process control with pharmaceutical-focused digital twin platforms, reflecting divergent bets on sectoral growth vectors.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| Aspen Technology Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Siemens AG |
| General Electric Company |
| Yokogawa Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Sensor hardware concentration in Japan and Germany anchors margin capture for control optimization software vendors, with precision instrumentation sourcing costs determining competitive positioning across deployment tiers. Licensing structures downstream reflect this upstream dependency, embedding hardware-software bundling premiums into enterprise contracts.
Pricing Analysis
Long-term enterprise licensing contracts dominate revenue capture for major automation vendors, with multi-year offtake agreements securing recurring maintenance streams. Price differentiation rests on OPC-UA certification tier and embedded regulatory compliance modules for EPA methane monitoring or REACH batch recording. Pricing pressure stems from service unbundling trends, as Gulf Coast refiners separate optimization consulting from hardware support. Mid-sized manufacturers lacking captive engineering teams exhibit highest price sensitivity, while integrated chemical producers with model maintenance capabilities accept premium tiers.
Supply Chain Analysis
Export control regimes limiting semiconductor and sensor technology flows from the US, Japan, and Germany constrain hardware-software integration capabilities for certain downstream markets. Control system architectures draw from precision sensor components, industrial-grade server infrastructure, and specialized OPC-UA protocol stacks. Single-source vulnerability concentrates in distributed control system hardware where proprietary protocols lock buyers into incumbent ecosystems. Distribution runs through system integrators for mid-market penetration and direct enterprise sales for major refinery and chemical complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping competitive positioning as digital twin convergence collapses traditional boundaries between simulation and control layers, with FDA process analytical technology guidelines accelerating ecosystem interoperability demands.
For Market Incumbents: Entrench hydrocarbon processing relationships through backward integration into methane emissions monitoring hardware, countering specialized APC consultants unbundling optimization from DCS maintenance. Prioritize hybrid architecture certification investments to address tightening cyber insurance coverage terms for critical infrastructure software. For New Entrants and Emerging Players: Mid-sized pharmaceutical manufacturers in the US Midwest represent the most penetrable entry point, with sterile injectable producers lacking digital twin deployment expertise. Cloud-native remote diagnostic platforms for geographically dispersed energy assets offer secondary white-space, with outcome-based contracting as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play algorithm developers with demonstrated FDA process analytical technology validation workflows, positioned for pharmaceutical digital twin consolidation. Monitor EPA methane enforcement intensity as the signal indicating upgrade cycle acceleration for anticipatory control systems.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Certification | Cyber insurance underwriters tighten coverage terms for cloud-dependent critical infrastructure software. |
| Digital Twin Platform Integration | FDA process analytical technology guidelines accelerate adoption among sterile injectable manufacturers. |
| Specialized APC Consultant Acquisition | Service unbundling fragments traditional bundled maintenance models across Gulf Coast refiners. |
| OPC-UA Protocol Stack Development | Interoperability gaps between multivendor control layers complicate multi-site rollout programs. |
| REACH-Compliant Batch Recording Module Launch | BASF and Bayer operations in Ludwigshafen require auditable data trails for chemical documentation. |
Methodological Framework
A spread of perspectives from refinery control engineers, system integrators, chemical plant managers, and pharmaceutical manufacturing directors converged on the working assumptions governing model-predictive control adoption trajectories. Primary fieldwork combined with secondary validation from SEC 10-K automation vendor disclosures, EPA enforcement action databases, and EU ECHA REACH registration data supported bottom-up and top-down triangulation across deployment models and vertical applications.
Demand-supply balance framing anchored the analytical framework, with segmentation across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster modeled throughout the projection horizon. CAGRs derived from historical adoption curve analysis and regulatory mandate timing, incorporating process model maintenance burden estimates and cloud infrastructure capex disclosures as industry-specific forecast inputs.
Practitioners should monitor EPA methane rule enforcement intensity, EU F-Gas Regulation expansion scope, and cyber insurance coverage term revisions for early signals of upgrade cycle acceleration or architecture preference shifts. Forecasts reflect assumptions around regulatory mandate implementation timelines and engineering talent availability. Material shifts in OPC-UA standardization progress or hybrid cloud security certification pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Brain Training Software Market
Software & Services
Lending Software Market
Software & Services
3D Animation Software Market
Software & Services
Computer Engineering Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Car-Hailing Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
App Uninstall Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Web Scraping Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Forestry Software Market
Software & Services
Global AR Game Engine Software Market