
 Electric Oil Pump Market | 2026-2036
Electric Oil Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Oil Pump Market Insights
Brushless DC motor integration is rewriting electric oil pump architectures across automotive thermal management. Robert Bosch GmbH leverages its powertrain electronics heritage to anchor high-voltage pump platforms for hybrid drivetrains. DENSO Corporation sustains manufacturing scale through captive motor winding operations in Japan and Thailand. Nidec Corporation dominates compact brushless DC designs that serve engine-off lubrication cycles in start-stop vehicles.
An electric oil pump is an electromechanical fluid transfer device comprising a brushless DC or AC induction motor coupled to a positive-displacement or dynamic pumping element, typically operating at voltages from 12V to 800V depending on vehicle architecture; its primary function is to deliver pressurized lubricant or coolant to rotating machinery independent of crankshaft speed. Gear pumps occupy the largest share of automotive applications due to their tolerance for high-viscosity fluids and tolerance stack simplicity. Brushless DC technology leads growth trajectories as automakers eliminate brush wear failures and extend service intervals beyond 300,000 kilometers. Vehicle powertrain applications command the deepest margin pools where pump suppliers integrate motor control electronics and CAN bus diagnostics into single assemblies.
The EPA, Euro 7 framework, and China's MIIT shape product standards through fuel economy mandates that penalize parasitic mechanical pump losses. REACH and RoHS constrain material selections for seals and motor windings, pushing suppliers toward halogen-free insulation systems. Stakeholders must monitor how 800V platform proliferation alters insulation class requirements and supplier qualification timelines for next-generation thermal modules.
Market Dynamics
Powertrain electrification is compressing design cycles for thermal management components as automakers eliminate belt-driven ancillaries in favor of electrically actuated systems. This shift forces pump suppliers to requalify products for 800V architectures while maintaining backward compatibility with 12V micro-hybrid platforms.
Growth Catalysts
- Euro 7 emissions framework:Tightening CO2 limits for light-duty vehicles mandate on-demand lubrication systems that reduce parasitic losses from mechanical pumps during low-load operation.
- China's MIIT dual carbon goals:Domestic EV production quotas accelerate procurement of localized electric oil pump assemblies for battery thermal management and e-axle lubrication.
- Brushless DC motor topology:Elimination of commutator wear extends service intervals beyond 300,000 kilometers, reducing total cost of ownership for fleet operators.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings compress margins on high-torque brushless DC pump motors sourced from concentrated Chinese refining operations.
- 800V insulation qualification timelines:Extended validation cycles for Class H winding systems delay platform launches by 18-24 months versus 400V predecessors.
- Mechanical pump residual demand:Internal combustion engine production in emerging markets sustains incumbent supplier revenue streams and slows electrification capex conversion.
Strategic Opportunities
- Commercial vehicle electrification:Battery-electric and fuel-cell trucks require high-flow thermal management pumps for e-axles and power electronics cooling.
- India PLI scheme for auto components:Localized manufacturing incentives attract pump suppliers to establish motor winding and final assembly operations for domestic OEM supply.
- Digital twin integration:Model-based pump control algorithms enable predictive maintenance contracts that unbundle hardware from recurring software revenue.
Industry Challenges
- Embedded software talent scarcity:Motor control firmware development for automotive ASIL-D safety requirements competes with broader semiconductor industry hiring.
- Multi-voltage platform complexity:Simultaneous engineering for 12V, 48V, 400V and 800V architectures fragments R&D resources and extends program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Oil Pump Market |
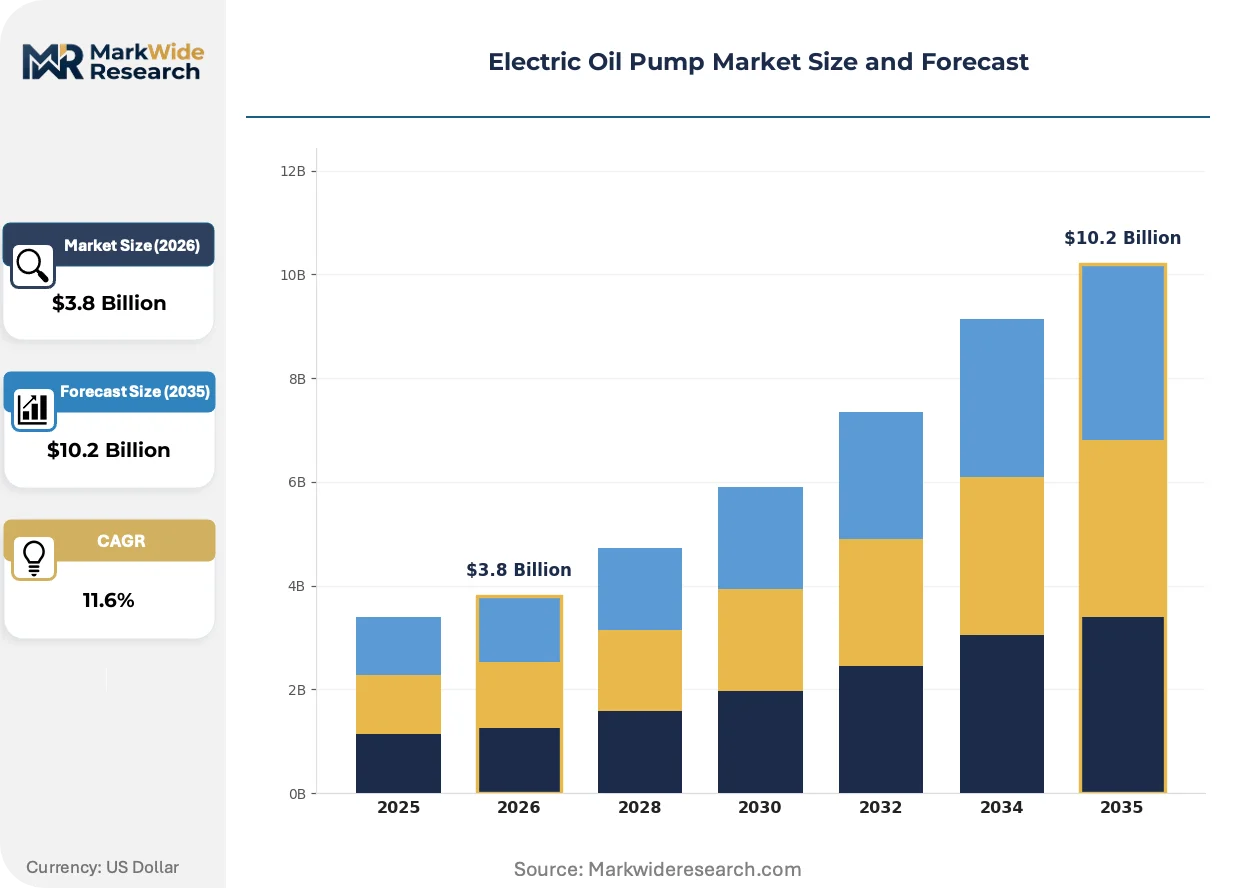
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Gear Pumps, Vane Pumps, Diaphragm Pumps Application: Hydraulic Systems, Vehicle Powertrains, Engine Lubrication, Industrial Machinery End User: Automotive, Aerospace, Marine, Construction Equipment Technology: Electric Motors, Brushless DC, AC Induction, Magnetic Drive |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, AISIN SEIKI, Nidec Corporation, BorgWarner Inc., MAHLE Group, ZF Friedrichshafen AG, Johnson Electric, Rheinmetall Automotive AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Oil Pump Market Trends and Innovations
Intelligent actuation is replacing fixed-displacement pumping across electrified powertrains. Variable-speed brushless DC systems now modulate flow based on real-time thermal load rather than crankshaft speed, enabling precise energy management.
Integrated motor-drive electronics is digitizing pump control architectures by embedding gate drivers and microcontrollers within the pump housing. Tier 1 suppliers are adopting these mechatronic assemblies for transmission lubrication in hybrid SUVs. The technology is digitizing supplier value capture by shifting margin from commodity hardware to proprietary firmware.
REACH substance restrictions are constraining seal material selections for high-temperature coolant exposure. The regulation bans specific phthalate plasticizers used in fluorocarbon elastomers, forcing reformulation of shaft seals for 800V inverter cooling loops. European pump manufacturers are accelerating validation of perfluoroelastomer alternatives to maintain chemical compatibility with new dielectric fluids.
Fleet operators are consolidating supplier relationships around vertically integrated pump-motor assemblies rather than discrete component sourcing. Automotive OEMs now specify single-source responsibility for thermal module performance, displacing traditional tiering structures. This concentration is most visible in German premium vehicle programs where pump suppliers assume warranty liability for complete lubrication circuits.
Electric Oil Pump Market Segmentation
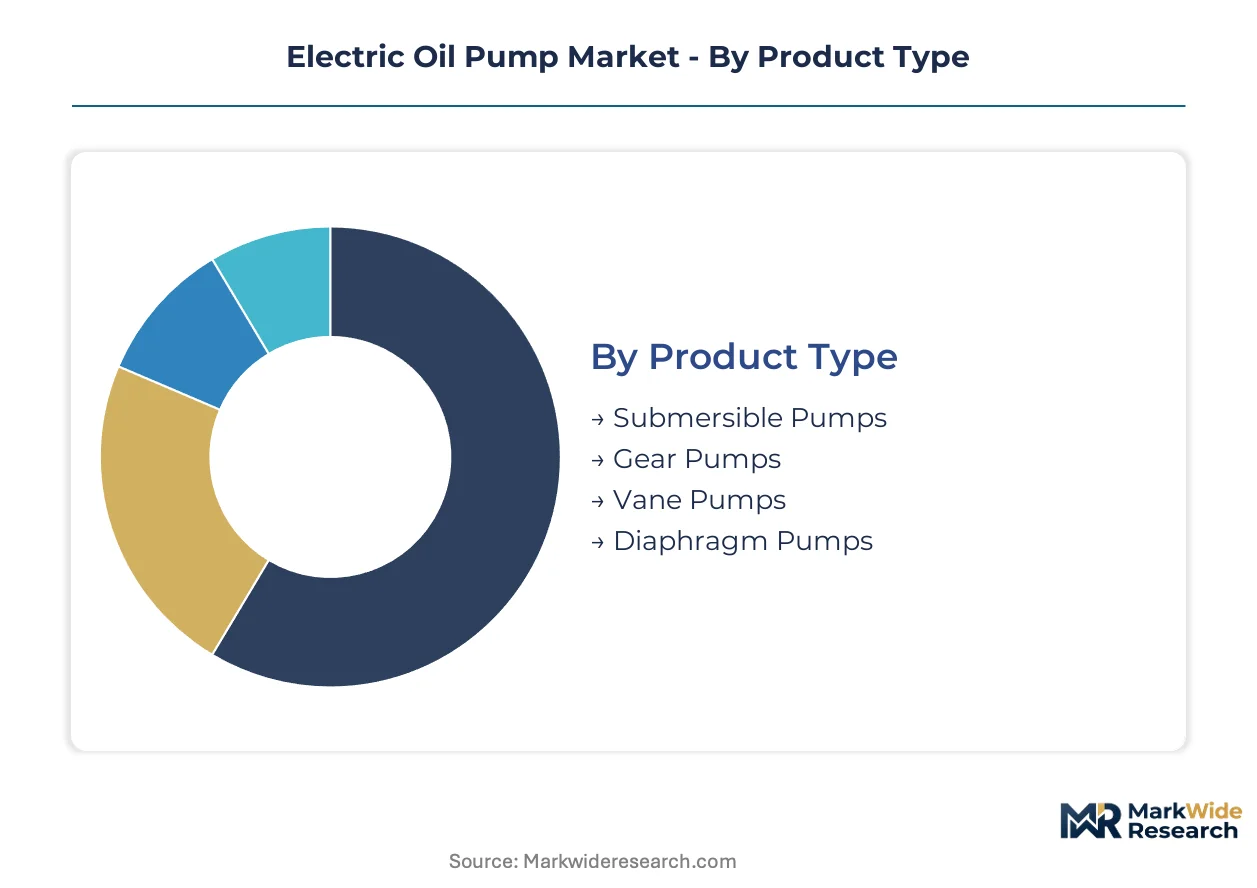
Electric oil pump procurement patterns diverge sharply across technical specifications and duty cycles. After-sales service intensity varies from sealed-for-life automotive units to rebuildable industrial systems requiring scheduled maintenance protocols.
Product Type:
After-sales service intensity separates disposable automotive pump cartridges from industrial rebuild programs. Field serviceability determines warranty cost structures and supplier margin retention across replacement cycles.
- Gear Pumps:Positive-displacement architecture with intermeshing rotors delivers consistent flow against variable viscosity. Demand concentrates in vehicle powertrain applications where tolerance stack simplicity reduces assembly cost. EPA fuel economy mandates accelerate displacement of mechanical alternatives in start-stop systems.
- Submersible Pumps:Motor and pump share a common housing immersed in fluid, eliminating shaft seal failure modes. Marine and aerospace thermal management systems specify these units for redundant cooling loops where external leakage is unacceptable.
- Vane Pumps:Sliding vanes maintain contact with an eccentric cam ring for medium-pressure hydraulic circuits. Construction equipment OEMs specify these for implement control systems requiring rapid response.
- Diaphragm Pumps:Flexible membrane isolates fluid from motor elements, enabling aggressive coolant chemistry compatibility. Battery thermal management modules specify these for dielectric fluid circulation in 800V architectures.
Gear pumps hold the largest share; momentum sits with submersible designs gaining share in electrified powertrains.
Application:
Cost tier stratification separates commodity engine lubrication from precision hydraulic servo systems. Specification grade determines supplier qualification barriers and pricing leverage.
- Vehicle Powertrains:Integrated e-axle lubrication and transmission cooling demand variable-speed flow modulation. China's MIIT dual carbon goals accelerate procurement of localized assemblies for domestic EV production.
- Hydraulic Systems:Closed-loop servo controls require pressure-compensated flow for precision positioning. Construction equipment electrification expands demand for electrically actuated hydraulic power units.
- Engine Lubrication:On-demand oil delivery eliminates belt-driven parasitic losses during low-load operation. Euro 7 emissions frameworks mandate these systems for CO2 reduction credits.
- Industrial Machinery:Continuous-duty bearing lubrication and coolant circulation specify robust thermal margins. Machine tool OEMs prioritize mean-time-between-failure metrics over first cost.
Vehicle powertrains command the deepest margin pools; industrial machinery applications are climbing the fastest as predictive maintenance contracts expand.
End User:
Volume concentration in automotive production drives scale economies that subsidize development costs for niche segments. Fleet standardization programs consolidate supplier relationships around platform-common pump families.
- Automotive:Passenger vehicle and commercial truck electrification consumes the majority of brushless DC pump output. Powertrain thermal modules integrate motor control electronics and CAN diagnostics into single assemblies.
- Aerospace:Federal Aviation Administration certification requirements impose rigorous validation protocols for fuel and hydraulic pump redundancy. More electric aircraft architectures expand electrically actuated thermal management.
- Marine:Classification society rules for redundant lubrication drive specification of dual pump configurations. Battery-electric propulsion systems require high-flow cooling for power electronics enclosures.
- Construction Equipment:Severe-duty cycle profiles prioritize seal durability and contamination tolerance. Equipment rental fleets drive demand for extended service interval designs.
Automotive absorbs the highest unit volumes; aerospace commands the steepest expansion trajectory as more electric aircraft programs advance.
Technology:
Supply concentration in rare earth magnet processing shapes cost structures for high-performance motor topologies. Insulation system qualification timelines fragment competitive positioning across voltage classes.
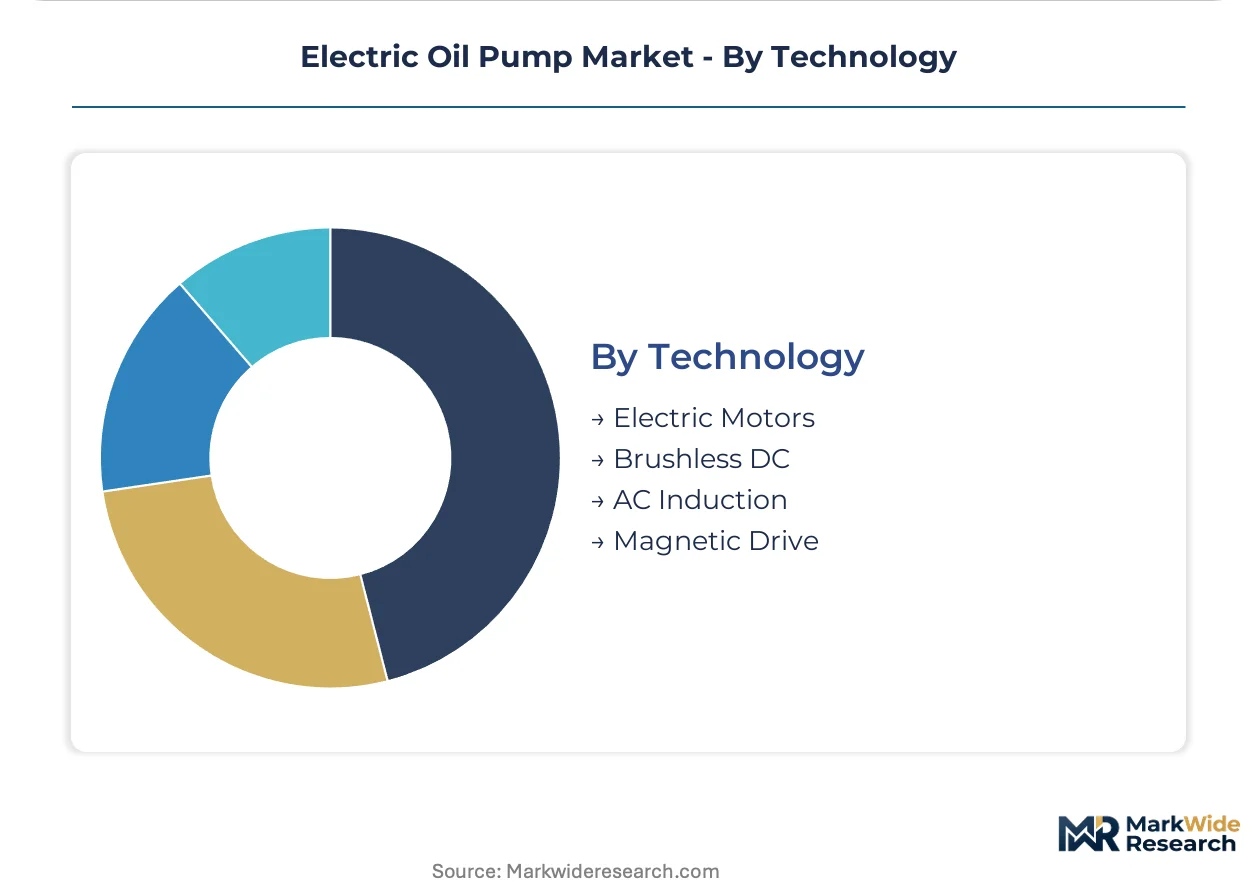
- Brushless DC:Electronically commutated permanent magnet motors eliminate brush wear and enable precise speed control. REACH substance restrictions constrain magnet sourcing while extending service intervals beyond 300,000 kilometers.
- AC Induction:Squirrel-cage rotor designs operate without rare earth materials, insulating against magnet price volatility. Industrial machinery OEMs specify these for cost-sensitive continuous-duty applications.
- Electric Motors:Brushed DC architectures persist in 12V auxiliary systems where cost minimization dominates. Emerging market vehicle production sustains residual demand for mature motor technologies.
- Magnetic Drive:Coupled magnetic fields transmit torque through containment shells, achieving hermetic sealing. Chemical processing and battery thermal management specify these for aggressive fluid compatibility.
Brushless DC dominates new program awards; magnetic drive systems are gaining share fastest in 800V battery cooling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams concentrate electric oil pump sourcing decisions in manufacturing clusters tied to EV powertrain assembly. Supplier qualification timelines favor established production geographies with mature motor winding and electronics integration capabilities.
China
Domestic EV production volumes dominate global output, with MIIT dual carbon goals accelerating localized pump assembly procurement. Shanghai and Shenzhen manufacturing clusters host tiered supplier networks serving BYD and NIO e-axle programs. Local pump suppliers are scaling brushless DC motor winding capacity to displace imported subsystems.
Germany
Premium vehicle electrification mandates from KBA emission protocols drive demand for integrated thermal modules. Stuttgart and Munich engineering centers specify single-source warranty responsibility for complete lubrication circuits. Suppliers assume liability for transmission cooling performance in hybrid SUV platforms.
United States
EPA Corporate Average Fuel Economy standards penalize parasitic mechanical pump losses in light-duty trucks. Detroit and Tennessee assembly plants source variable-speed pumps for start-stop system integration. Tier 1 suppliers embed motor control electronics and CAN diagnostics into pump housings for domestic OEM programs.
Japan
METI carbon neutrality roadmaps accelerate powertrain electrification across kei-car and commercial vehicle segments. Nagoya and Tokyo supplier networks leverage captive motor winding operations for hybrid transmission cooling. Domestic pump manufacturers prioritize service interval extension beyond 300,000 kilometers for export markets.
South Korea
Ministry of Environment emission credits incentivize on-demand lubrication systems for domestic EV platforms. Gyeonggi-do and Ulsan production bases integrate electric oil pumps into battery thermal management modules. Hyundai and Kia supply chains qualify localized suppliers for 800V architecture compatibility.
Electric Oil Pump Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Consolidation pressure intensifies as automotive OEMs reduce supplier counts for thermal module responsibility. Three archetypes dominate: diversified powertrain conglomerates with captive electronics, dedicated motor-pump specialists with rare earth magnet supply chains, and diversified automotive component suppliers with transmission heritage. Competitive moves center on backward integration into motor winding and firmware development for 800V qualification timelines.
Within the diversified conglomerate tier, Robert Bosch GmbH and DENSO Corporation anchor positions through powertrain electronics heritage and captive manufacturing scale. Nidec Corporation exemplifies the motor-specialist archetype with compact brushless DC designs. These three entities represent distinct strategic postures: Bosch leverages high-voltage platform development, DENSO sustains cost leadership through integrated production, and Nidec captures engine-off lubrication cycles in micro-hybrid applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| AISIN SEIKI |
| Nidec Corporation |
| BorgWarner Inc. |
| MAHLE Group |
| ZF Friedrichshafen AG |
| Johnson Electric |
| Rheinmetall Automotive AG |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor absorbs 23% of global automotive component freight costs, compressing margins on European-bound electric oil pump assemblies while amplifying price differentiation between captive-production suppliers and contract-manufacturing dependent competitors. Rare earth magnet price volatility feeds directly into tiered quotations, with buyers in premium vehicle programs absorbing neodymium cost pass-throughs that economy-segment purchasers reject.
Pricing Analysis
Cost-plus contracts with London Metal Exchange rare earth indexation dominate procurement for brushless DC pump motors, insulating Japanese suppliers against magnet price swings while exposing European tier 2 vendors to margin erosion. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified assemblies with embedded diagnostics from commodity 12V auxiliary units. Pricing pressure stems from Chinese domestic suppliers undercutting import quotations by 15-20% for MIIT-compliant EV thermal modules. Fleet operators exhibit lowest price sensitivity, prioritizing 300,000-kilometer service intervals over first cost.
Supply Chain Analysis
Contract manufacturing concentrates in Foxconn and BYD Electronics facilities across Shenzhen and Chongqing, with captive motor winding operations at DENSO Thailand and Nidec Vietnam absorbing high-volume automotive programs. Magnet processing draws from Chinese rare earth refining clusters, copper winding feeds from Chilean concentrate, and semiconductor gate drivers from Taiwanese foundries. Single-source vulnerability concentrates in dysprosium separation capacity held by three state-owned entities. Distribution runs through Tier 1 thermal module integrators rather than discrete component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs consolidating supplier counts around single-source warranty responsibility for complete lubrication circuits, fragmenting tier 2 pump manufacturers into price-taker positions. This concentration rewards vertically integrated competitors while squeezing component-specialist margins.
For Market Incumbents: Build firmware moats around ASIL-D motor control algorithms to defend against Chinese suppliers offering hardware-only quotations. Bosch and DENSO should deepen backward integration into rare earth magnet recycling to offset Chinese refining concentration. Prioritize 800V qualification timelines to capture premium platform awards before second-tier competitors complete validation cycles. For New Entrants and Emerging Players: India's PLI scheme for auto components offers underpenetrated manufacturing capacity with 15-year fiscal incentives for localized motor winding operations. Target commercial vehicle electrification in North American battery-electric truck programs, where incumbent suppliers lack established relationships with emerging OEMs like Rivian and Nikola. Lead with predictive maintenance software bundles to differentiate from commodity hardware incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates divesting non-core thermal management units amid portfolio rebalancing toward battery cell manufacturing. Five-to-ten year viability favors suppliers with captive 800V insulation qualification capabilities and embedded software revenue streams. Monitor MIIT dual carbon goal enforcement intensity as inflection indicator for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Qualification | Captures premium hybrid SUV thermal module awards ahead of second-tier validation completion. |
| Rare Earth Magnet Recycling | Insulates margin structures against Chinese state-owned refinery pricing volatility. |
| Predictive Maintenance Software | Transforms hardware-only suppliers into recurring-revenue thermal management service providers. |
| India PLI Manufacturing Footprint | Qualifies localized assemblies for domestic OEM supply chains under 15-year fiscal incentive windows. |
| Commercial Vehicle Thermal Module Integration | Addresses battery-electric truck e-axle lubrication demand underserved by passenger-vehicle specialists. |
Research Methodology
Desk research of SEC 10-K filings, EPA fuel economy compliance databases, and MIIT new energy vehicle production statistics preceded structured interviews with Tier 1 supplier procurement directors, OEM platform thermal engineers, and aftermarket distribution channel managers. Primary fieldwork validated secondary estimates through bottom-up bill-of-materials costing and top-down vehicle production forecast reconciliation across the analysis window.
Assumptions held Euro 7 CO2 limits and China's dual carbon enforcement intensity at announced regulatory levels while varying rare earth magnet price trajectories and 800V platform adoption rates across sensitivity scenarios. Segmentation modeling captured product type, application duty cycle, end-user industry, and voltage architecture dimensions. CAGRs derived from unit-volume projections mapped to average selling price deflation curves informed by historical automotive component cost-down patterns.
Practitioners should monitor MIIT subsidy phase-out schedules and Euro 7 implementation delays for early signals of demand trajectory revision. Forecasts reflect these documented assumptions alongside rare earth supply concentration and semiconductor gate driver availability constraints. Quarterly review of OEM platform launch timelines and thermal module supplier qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market