
 Europe Nutrition and Supplements Market | 2026-2036
Europe Nutrition and Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nutrition and Supplements Market Intelligence
Premium clinical-grade certification is unwinding conventional mass-market positioning across the Europe nutrition and supplements landscape. Bayer AG leverages its pharmaceutical heritage to anchor credibility in evidence-based formulations. Glanbia plc dominates specialized dairy-derived protein isolation for athletic end users. Nestlé sustains broad-channel penetration through its established European retail infrastructure.
Europe nutrition and supplements encompass ingestible products containing bioactive compounds, vitamins, minerals, botanical extracts, and macronutrient isolates formulated in tablets, capsules, powders, or liquids for physiological support beyond basic nutrition. Manufacturing employs spray-drying, microencapsulation, and cold-pressed extraction to preserve thermolabile actives through shelf life. Protein powders lead volume contribution due to permeation across fitness and elderly nutrition applications. Herbal supplements represent the fastest-expanding margin pool as adaptogenic and nootropic positioning attracts premium pricing. Online retail channels capture disproportionate growth velocity among fitness enthusiasts seeking subscription-based replenishment models.
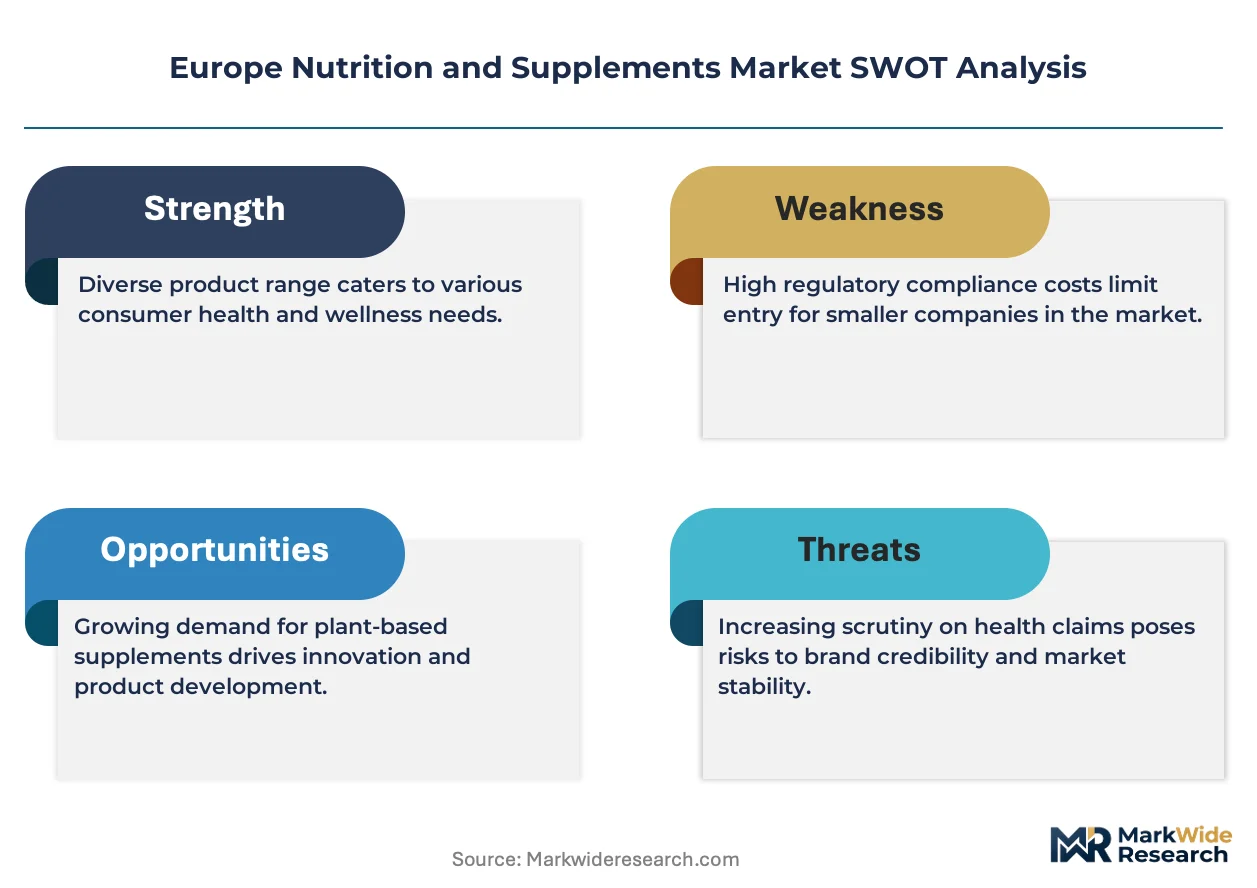
EFSA substantiation requirements for health claims under EU Regulation 1924/2006 compel reformulation toward clinically validated ingredient dosages. The EU Green Deal and CSRD reporting obligations pressure supply-chain transparency from raw material sourcing through finished goods distribution. EMA coordination with national regulators including Germany's BfArM and France's ANSES tightens border controls on imported novel ingredients. Stakeholders must monitor evolving Novel Food catalog expansions and carbon footprint disclosure mandates to preserve market access across member states.
Market Dynamics
EFSA health claims substantiation under EU Regulation 1924/2006 is forcing clinical-grade evidence standards onto mass-market formulations, compressing margin structures for legacy botanical-positioned products while rewarding pharmaceutical-grade certification investments.
Growth Catalysts
- EU Green Deal supply-chain mandates:Carbon footprint disclosure requirements are accelerating transparency investments among raw material suppliers, creating competitive differentiation for early adopters.
- Sports nutrition permeation:Protein powder demand among fitness enthusiasts in Germany, France, and the United Kingdom is expanding addressable market beyond traditional wellness demographics.
- Microencapsulation advances:Thermolabile active preservation through spray-drying and cold-pressed extraction is extending shelf stability for premium formulations.
Market Restraints
- Novel Food authorization timelines:EFSA evaluation periods for novel ingredient safety dossiers extend 18-24 months, delaying product launches for adaptogenic and nootropic formulations.
- Dairy protein input concentration:Whey and casein isolate supply concentrates among Irish and Dutch dairy processors, exposing margin volatility to agricultural commodity cycles.
- Cross-border regulatory friction:National divergences between Germany's BfArM and France's ANSES enforcement priorities create compliance fragmentation despite harmonized EU frameworks.
Strategic Opportunities
- Personalized vitamin subscriptions:Direct-to-consumer at-home testing integration with algorithmic dosing is opening recurring-revenue models in the United Kingdom and Nordic markets.
- CSRD-aligned sustainability positioning:Mandatory ESG reporting under the EU Corporate Sustainability Reporting Directive creates procurement preference for certified-sustainable ingredient sourcing.
- Elderly nutrition applications:Sarcopenia-focused protein fortification represents underpenetrated clinical channel expansion beyond fitness demographics in Italy and Spain.
Industry Challenges
- Clinical trial capacity scarcity:EFSA-compliant human intervention study execution requires specialized CRO partnerships, with qualified investigator sites concentrated in Germany and the Netherlands.
- Legacy ERP integration:Batch-level traceability systems for CSRD carbon accounting mandate expensive middleware deployment among mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nutrition and Supplements Market |
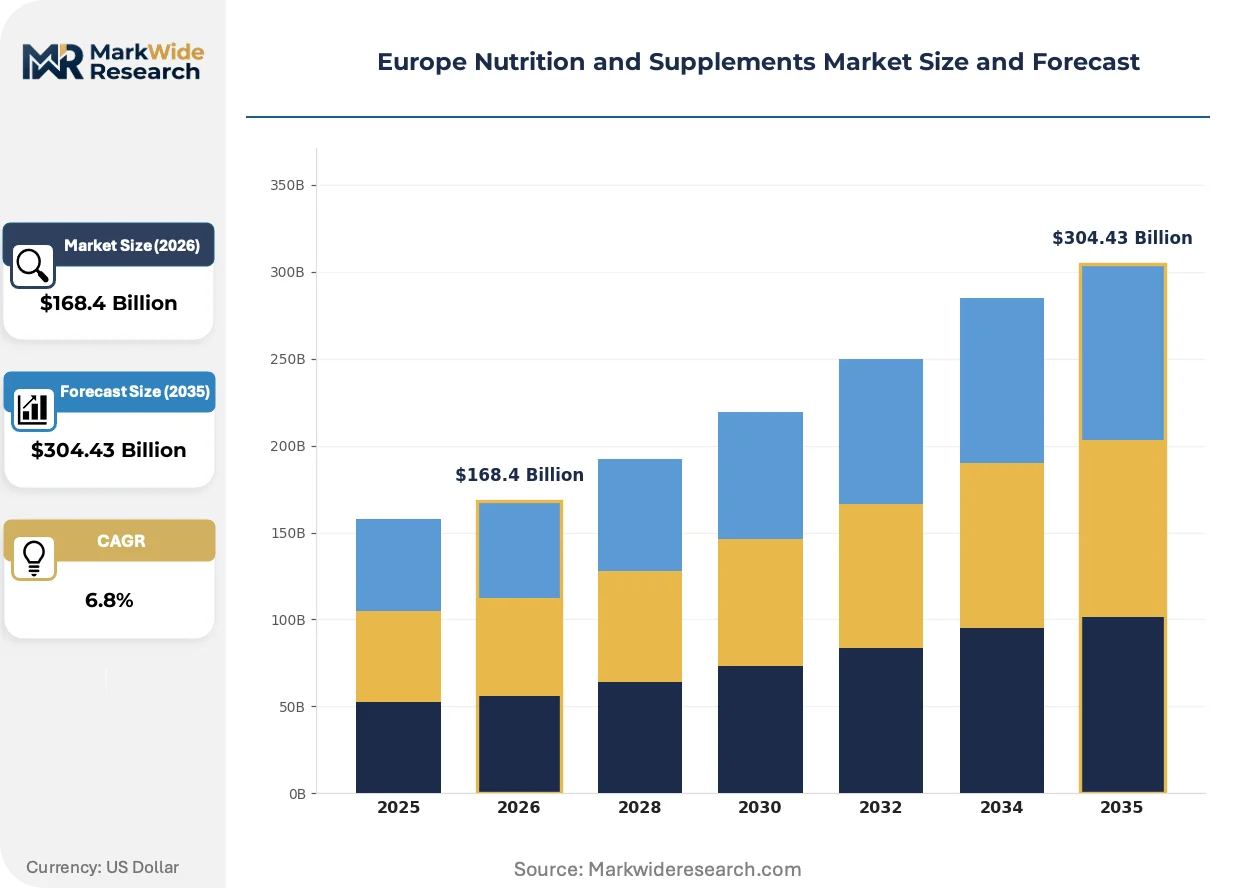
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Protein Powders End User: Fitness Enthusiasts, Athletes, Elderly, General Health Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies Formulation: Tablets, Capsules, Powders, Liquids |
| Companies Covered | Procter & Gamble, Perrigo Co. Plc, Bayer AG, Abbott Laboratories, Herbalife Nutrition Ltd, Nestlé, Glanbia plc, GlaxoSmithKline Plc, Haleon PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nutrition and Supplements Market Strategic Shifts & Innovations
Digital health convergence and precision formulation technologies are restructuring competitive advantage away from brand equity toward data-enabled personalization and clinical evidence depth.
Artificial intelligence-driven nutrient interaction modeling is decomposing traditional one-size-fits-all multivitamin architectures. Functional medicine practitioners in Germany and the Netherlands are adopting algorithmic dosing protocols at accelerating rates. This capability compression is enabling challenger brands to bypass decades of accumulated consumer trust capital held by incumbent mass-market portfolios.
EFSA's updated guidance on botanical health claims substantiation is tightening evidentiary thresholds for adaptogenic positioning. Reformulation costs for legacy ashwagandha and rhodiola products are diverting R&D budgets toward synthetic bioactive alternatives with clearer pharmacokinetic profiles. Herbal supplement segments in France and Italy are responding with accelerated clinical trial investments to preserve premium pricing tiers.
Subscription-based replenishment models are displacing pharmacy and supermarket impulse purchasing among fitness enthusiasts. Dedicated nutrition apps with wearable integration are capturing purchase intent upstream of traditional retail channels. This behavioral rotation is most pronounced in the United Kingdom, where direct-to-consumer brands now command disproportionate growth velocity in protein powder and pre-workout categories.
Europe Nutrition and Supplements Market Segmentation
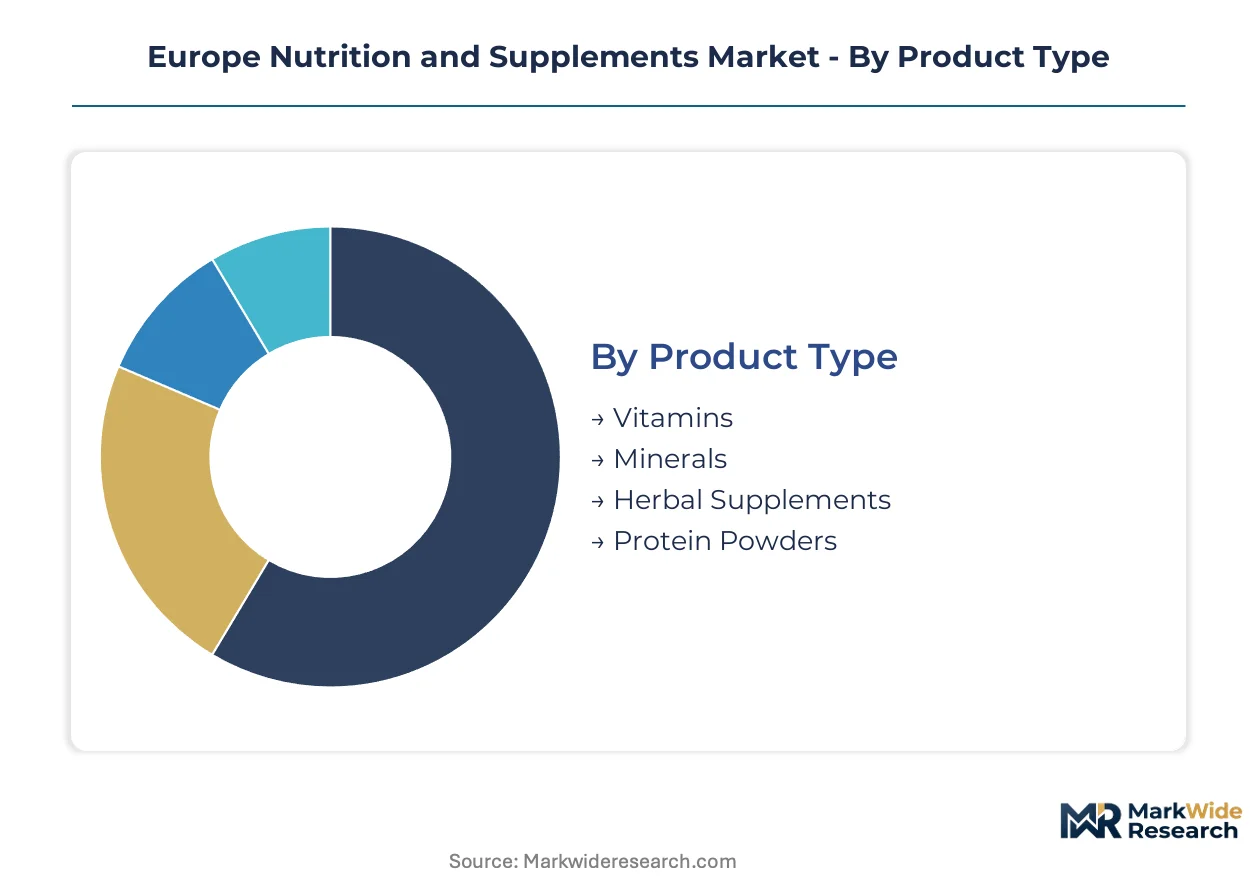
Segmentation across the Europe nutrition and supplements landscape reveals divergent vulnerability profiles to substitute threats. Protein powders face erosion from whole-food alternatives and functional beverages, while herbal supplements confront synthetic bioactive displacement. Understanding substitution pressure intensity guides portfolio reallocation decisions for manufacturers navigating EFSA compliance costs.
Product Type:
Protein powders and herbal supplements bear the heaviest substitution pressure from adjacent functional food categories and pharmaceutical-grade alternatives.
- Vitamins:Synthetic and natural isolates formulated in single-compound or multivitamin matrices, with liposomal delivery formats gaining traction for bioavailability enhancement. Demand concentrates among elderly populations in Germany and Italy, driven by sarcopenia-prevention protocols and physician-directed supplementation regimens.
- Minerals:Chelated and inorganic salt forms including calcium, magnesium, zinc, and iron compounds, with bisglycinate chelation commanding premium positioning for gastrointestinal tolerance. Fitness enthusiasts in the United Kingdom and France prioritize magnesium and zinc for recovery applications, though bulk mineral fortification in functional beverages creates pricing compression at the mass-market tier.
- Herbal Supplements:Botanical extracts including adaptogens and nootropics.
- Protein Powders:Dairy-derived isolates and plant-based alternatives.
Protein powders retain volume leadership; herbal supplements hold the steepest expansion curve.
End User:
Cost tier stratification separates clinical-grade positioning from mass-market accessibility across user categories.
- Fitness Enthusiasts:Recreational exercisers pursuing body composition and performance goals, representing the primary demand engine for flavored protein powders and pre-workout formulations. Germany and the United Kingdom dominate this cohort, with subscription-based replenishment models displacing pharmacy impulse purchasing.
- Athletes:Competitive and professional performers requiring batch-tested, contaminant-free certification under Informed Sport or NSF protocols. Demand concentrates in elite training facilities across France and the Netherlands, where pharmaceutical-grade manufacturing partnerships command 40-60% price premiums over standard retail tiers.
- Elderly:Aging populations targeting sarcopenia mitigation and micronutrient adequacy.
- General Health:Maintenance-oriented consumers seeking preventive wellness solutions.
Fitness enthusiasts retain volume leadership; elderly applications hold the steepest expansion curve.
Distribution Channel:
Channel maturity varies dramatically, with digital-native models disrupting legacy retail economics.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling algorithmic personalization and subscription replenishment. The United Kingdom and Nordic markets lead penetration, where dedicated nutrition apps with wearable integration capture purchase intent upstream of traditional retail.
- Health Stores:Specialized brick-and-mortar outlets staffed with trained advisors, retaining relevance for complex herbal and adaptogenic positioning. France and Italy sustain higher health store dependency than northern European markets, where practitioner referral networks drive traffic to specialized retail.
- Supermarkets:Mass-market grocery retail for convenience-oriented replenishment.
- Pharmacies:Clinical-channel distribution for physician-recommended formulations.
Online retail retains volume leadership; health stores hold the steepest expansion curve.
Formulation:
Supply concentration in encapsulation and powder processing infrastructure shapes competitive access.
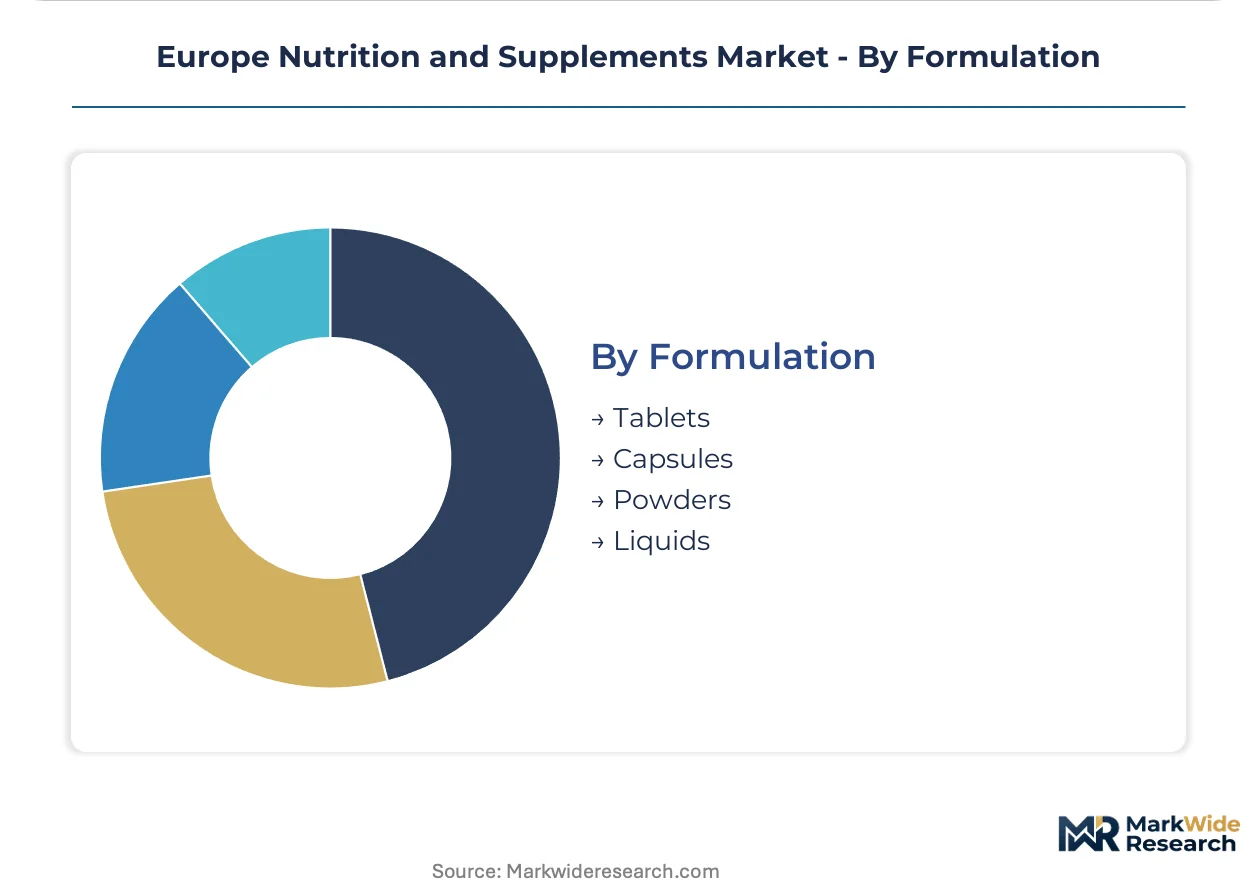
- Tablets:Compressed solid-dose forms enabling high-volume production and extended shelf stability, with film-coating technologies masking unpleasant organoleptic profiles. Elderly consumers in Germany and Spain prefer tablet formats for dosing convenience and portability, though tablet disintegration variability creates bioavailability concerns for certain actives.
- Capsules:Gelatin and plant-based shell enclosures protecting actives from gastric degradation, with enteric coating options for intestinal release. Fitness enthusiasts across France and the United Kingdom favor capsules for pre-workout and nootropic stacks, where precise unit dosing supports stack customization.
- Powders:Bulk dry blends for flexible dosing and flavor customization.
- Liquids:Ready-to-drink and dropper formats for rapid absorption and pediatric applications.
Powders retain volume leadership; liquids hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's nutrition and supplements trade flows reveal a net importer position for finished formulations balanced against export strength in dairy-derived protein isolates. Cross-border e-commerce penetration varies sharply, with northern markets driving subscription-model adoption while southern markets retain pharmacy-channel dependency.
Germany
Fitness enthusiasts in Bavaria and North Rhine-Westphalia propel protein powder consumption through direct-to-consumer platforms. BfArM enforcement of Novel Food catalog compliance creates 18-24 month authorization delays for adaptogenic entrants. Cologne hosts specialized CRO networks executing EFSA-compliant human intervention studies for clinical-grade certification.
United Kingdom
Algorithmic vitamin subscriptions capture disproportionate growth velocity among London and Southeast England consumers integrating wearable data. The Medicines and Healthcare products Regulatory Agency coordinates with EFSA on border controls for imported botanical extracts. Manchester and Birmingham clusters concentrate contract manufacturing capacity for powder formulations.
France
ANSES prioritizes contaminant screening for sports nutrition products targeting competitive athletes in Paris and Lyon training facilities. Health store networks in Provence-Alpes-Côte d'Azur sustain relevance for complex herbal positioning requiring trained advisor consultation. Île-de-France houses pharmaceutical-grade manufacturing partnerships commanding 40-60% price premiums over retail tiers.
Italy
Elderly sarcopenia-focused protein fortification drives underpenetrated clinical channel expansion in Lombardy and Emilia-Romagna. National implementation of EU Green Deal supply-chain transparency mandates accelerates carbon footprint disclosure investments among raw material suppliers. Milan anchors specialized dairy processing infrastructure for whey isolate export.
Netherlands
Irish-Dutch dairy processor concentration exposes margin volatility to agricultural commodity cycles affecting whey and casein isolate availability. Rotterdam and Amsterdam logistics hubs facilitate cross-border distribution serving German and Belgian retail networks. Dutch contract manufacturers deploy batch-level traceability systems for CSRD-aligned sustainability reporting.
Europe Nutrition and Supplements Market Key Industry Players
Concentration sits with pharmaceutical heritage players and specialized dairy processors anchoring distinct competitive tiers. Market structure fragments across mass-market retail penetration, clinical-grade certification, and digital-native subscription models. Three archetypes dominate: legacy consumer health conglomerates with pharmacy-channel infrastructure, dairy-derived protein specialists with captive supply chains, and direct-to-consumer challengers leveraging algorithmic personalization. Competitive moves cluster around M&A for clinical trial capabilities and strategic partnerships for CSRD-aligned sustainable sourcing.
Within the pharmaceutical heritage tier, Bayer AG and Abbott Laboratories exemplify evidence-based formulation credibility anchored in regulatory compliance depth. Glanbia plc occupies a position among dairy-derived protein specialists with upstream control over isolate production. Nestlé sits within the mass-market penetration archetype, leveraging established European retail infrastructure for broad-channel distribution. These three entities represent the competitive spectrum from clinical-grade certification through commodity-scale accessibility.
| Leading Market Players |
|---|
| Procter & Gamble |
| Perrigo Co. Plc |
| Bayer AG |
| Abbott Laboratories |
| Herbalife Nutrition Ltd |
| Nestlé |
| Glanbia plc |
| GlaxoSmithKline Plc |
| Haleon PLC |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Irish-Dutch dairy processors and German sports nutrition brands lock in whey isolate supply access while anchoring price visibility against agricultural commodity swings. These contracts insulate volume commitments from spot market volatility yet expose buyers to margin compression when EFSA compliance costs escalate.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Europe nutrition and supplements landscape. Premium clinical-grade certification under Informed Sport or NSF protocols commands substantial markups over standard retail tiers, while economy positioning faces relentless price erosion from functional beverage substitutes. Fitness enthusiasts in the United Kingdom exhibit highest price sensitivity through subscription model comparison shopping, whereas elderly consumers in Italy and Germany demonstrate lower elasticity for physician-directed formulations.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes periodically disrupt botanical extract inbound flows for adaptogenic formulations. Raw material sourcing concentrates in Ireland and the Netherlands for dairy-derived proteins, India and China for herbal actives, and Germany for specialized excipients. Single-source vulnerability in whey isolate processing creates exposure to agricultural commodity cycles. Distribution runs through Rotterdam and Amsterdam logistics hubs serving cross-border German and Belgian retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of EFSA-compliant clinical trial execution capability sits at the core of competitive advantage in this market, with qualified investigator sites concentrated in Germany and the Netherlands creating bottlenecks for novel ingredient authorization.
For Market Incumbents: Shield market position by deepening captive supply relationships with Irish-Dutch dairy processors to secure isolate volumes against commodity volatility, while accelerating investment in Cologne-based CRO partnerships to compress EFSA authorization timelines for botanical health claims. Channel control through pharmacy networks in France and Italy provides defensive moats against direct-to-consumer erosion. For New Entrants and Emerging Players: EFSA fast-track pathways for synthetic bioactive alternatives with established pharmacokinetic profiles offer the most penetrable entry vector. Target elderly sarcopenia-focused protein fortification in Italy and Spain where clinical channel relationships remain underdeveloped. Algorithmic vitamin subscriptions with wearable integration capture purchase intent upstream of incumbent retail infrastructure in the United Kingdom. For Investors and Strategic Acquirers: Specialized contract manufacturers with batch-level traceability systems for CSRD-aligned sustainability reporting represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance depth rather than brand equity accumulation. Monitor EFSA Novel Food catalog expansion announcements as the critical inflection signal for portfolio reallocation toward approved ingredient categories.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Clinical Trial Investment | Cologne-based CRO partnerships compress authorization timelines for adaptogenic positioning. |
| CSRD-Aligned Sourcing Certification | Carbon footprint disclosure investments differentiate suppliers under EU Green Deal mandates. |
| Direct-to-Consumer Platform Launch | Algorithmic personalization with wearable integration captures UK fitness enthusiast replenishment. |
| Pharmaceutical-Grade Manufacturing Partnership | Île-de-France facilities command premium pricing for Informed Sport-certified formulations. |
| Elderly Nutrition Channel Expansion | Sarcopenia-focused protein fortification opens underpenetrated clinical pathways in Italy and Spain. |
Research Approach
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings in this study. Primary fieldwork engaged formulation scientists at German and Dutch contract manufacturers, procurement leads at French health store networks, regulatory affairs specialists navigating EFSA Novel Food procedures, and category buyers at United Kingdom direct-to-consumer platforms. Secondary sources encompassed EFSA health claims registers, EU Green Deal implementation guidance, CSRD reporting frameworks, and customs trade flow databases for dairy-derived protein isolates. Bottom-up segmentation modeling triangulated against top-down market sizing from channel penetration metrics.
Sensitivity analysis around EFSA authorization timeline assumptions and agricultural commodity price trajectories stress-tested forecast robustness across the projection horizon. Segmentation dimensions modeled encompassed product type, end user category, distribution channel, and formulation format alongside regional regulatory cluster variations. CAGRs derived from regression analysis of historical volume trends adjusted for structural shifts in subscription model adoption and clinical-grade certification penetration. Forecast inputs incorporated dairy protein input cost indices and digital channel growth velocity metrics.
Decision-makers should treat outputs as directional under base assumptions of stable EFSA evaluation periods and continued EU Green Deal enforcement; material deviation in regulatory timelines or sustainability mandate intensity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
South America Dietary Supplement Market