
 Autonomous Underwater Gliders (AUG) Market | 2026-2036
Autonomous Underwater Gliders (AUG) Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Underwater Gliders (AUG) Market Outlook
Defense procurement agencies is collapsing the historical research-institution dominance that shaped early AUG adoption. Kongsberg Maritime leverages its Nordic naval heritage to anchor long-endurance platform contracts. Teledyne Webb Research sustains technology leadership in buoyancy-driven propulsion architectures. Saab AB competes through integrated seabed warfare system offerings.
Autonomous Underwater Gliders are self-propelled, buoyancy-driven vehicles that execute long-duration transects by cyclically altering ballast to generate forward motion through hydrofoils, typically achieving ranges exceeding one thousand kilometers on alkaline or lithium primary battery packs. Their primary purpose centers on persistent subsurface data collection for oceanographic, environmental, and defense intelligence missions. Deep-Water Gliders command premium positioning owing to pressure-rated hull requirements and limited qualified supplier bases. Acoustic Sensors generate the dominant technology revenue stream as anti-submarine warfare and seabed mapping applications expand. Environmental Monitoring represents the fastest-growing application segment driven by climate baseline establishment mandates.
The United States Navy and NOAA impose operational certification standards that constrain non-domestic platform access to federal contracts. ISO 9001 quality management and ITAR export control frameworks further shape competitive participation requirements. Stakeholders must monitor evolving seabed sovereignty claims and associated national security classification protocols that increasingly restrict cross-border data sharing and platform deployment permissions.
Market Dynamics
Defense procurement agencies are collapsing the historical research-institution dominance that shaped early AUG adoption, redirecting capital toward long-endurance platforms with integrated seabed warfare capabilities.
Growth Catalysts
- Naval Modernization Mandates:The United States Navy accelerates fleet expansion through operational certification standards that favor domestic platform suppliers. Contract vehicles now prioritize multi-month endurance thresholds.
- ITAR Export Control Frameworks:These regulations create protected demand pools for qualified suppliers. Non-domestic manufacturers face systematic exclusion from federal procurement channels.
- Lithium Primary Battery Chemistries:Extended mission ranges exceeding one thousand kilometers enable persistent subsurface data collection. Energy density improvements compress operational cost structures.
Market Restraints
- Pressure-Rated Hull Manufacturing:Deep-water glider production concentrates among limited qualified suppliers. Titanium and composite fabrication capacity constraints extend lead times.
- Acoustic Sensor Miniaturization Costs:Precision hydrophone arrays require specialized foundry access. Input cost volatility affects platform economics.
- Cross-Border Data Classification:Seabed sovereignty claims restrict international deployment permissions. National security protocols fragment operational theaters.
Strategic Opportunities
- Climate Baseline Establishment Mandates:Environmental monitoring applications expand as NOAA funding prioritizes oceanographic transect density. Research institutions seek extended-duration platforms.
- Anti-Submarine Warfare Integration:Acoustic sensor convergence with seabed mapping creates new mission profiles. Defense agencies demand networked glider swarms.
- ISO 9001 Quality Certification:Quality management frameworks differentiate suppliers in competitive evaluations. Certification accelerates contract access.
Industry Challenges
- Subsea Robotics Engineering Talent:Buoyancy-driven propulsion expertise concentrates within specialized research centers. Recruitment competition intensifies.
- Operational Certification Timelines:Navy and NOAA validation protocols extend platform qualification cycles. Compliance documentation burdens smaller suppliers.
- Legacy Platform Integration:Existing research vessel networks require interoperability retrofits. Data format standardization lags hardware advancement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Underwater Gliders (AUG) Market |
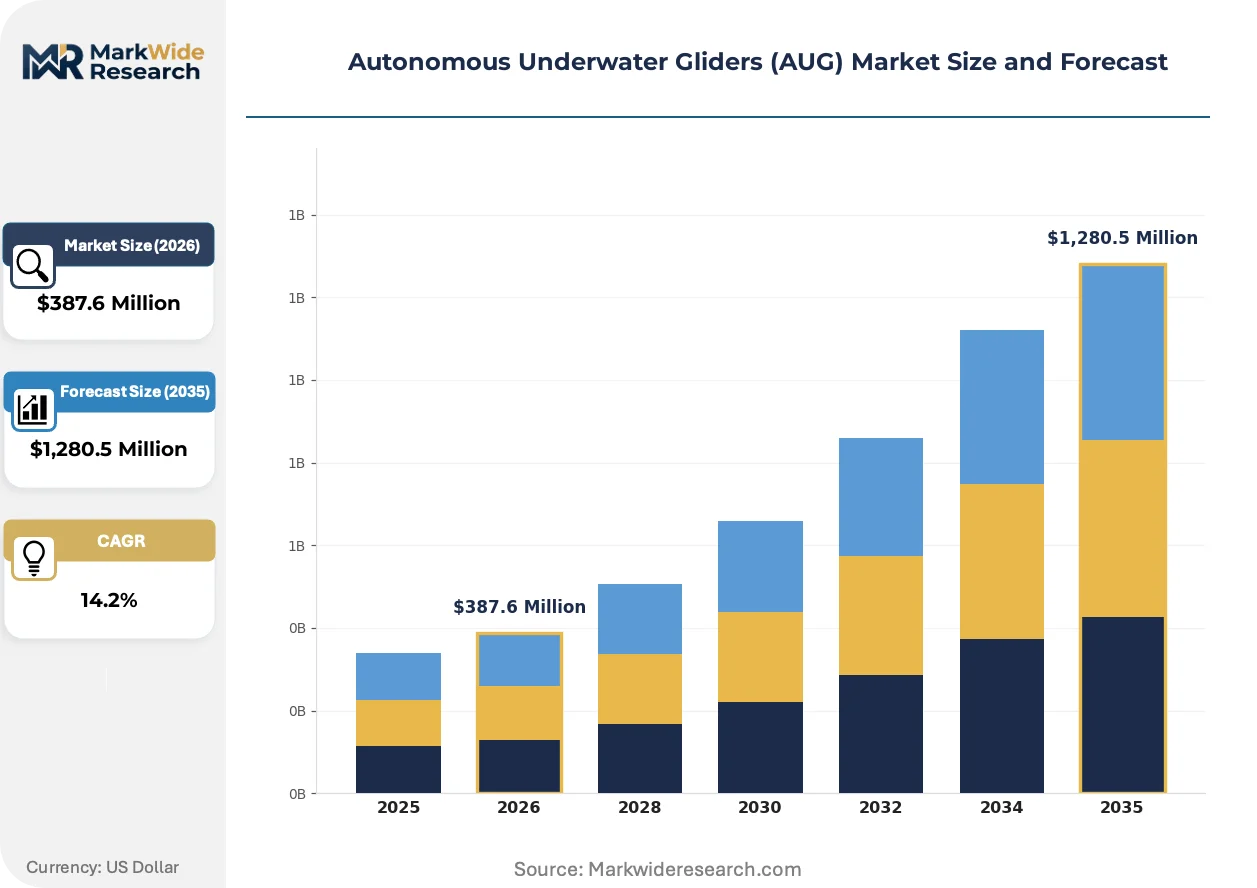
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coastal Gliders, Deep-Water Gliders, Hybrid Gliders, Manned Gliders Technology: Acoustic Sensors, Optical Sensors, Chemical Sensors, GPS Navigation Application: Oceanography, Marine Research, Environmental Monitoring, Defense Operations End User: Research Institutions, Government Agencies, Environmental Organizations, Commercial Entities |
| Companies Covered | Bluefin Robotics, The ECA Group, Teledyne Webb Research, Fugro, Saab AB, Kongsberg Maritime, Boston Engineering Corporation, International Submarine Engineering, L3 OceanServer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Underwater Gliders (AUG) Market Strategic Shifts
Acoustic sensor miniaturization and extended battery chemistries are extending mission endurance thresholds, while procurement concentration among defense agencies reconfigures supplier priorities.
Solid-state lithium-sulfur battery architectures are supplanting alkaline primary cells in next-generation deep-water gliders. The United States Navy now mandates these chemistries for contracts exceeding ninety-day endurance requirements. Energy density gains compress platform weight fractions and extend operational radii.
ITAR export control frameworks are tightening cross-border technology transfer restrictions for acoustic sensor payloads. European defense procurement agencies respond by accelerating indigenous platform development programs. Nordic naval suppliers leverage regional autonomy to capture NATO-adjacent contracts.
Defense agencies now bundle long-endurance platform procurement with integrated seabed warfare system offerings. Research institutions face displacement from prime contract vehicles. This concentration pattern manifests most visibly in United States federal budget allocations.
Autonomous Underwater Gliders (AUG) Market Segmentation
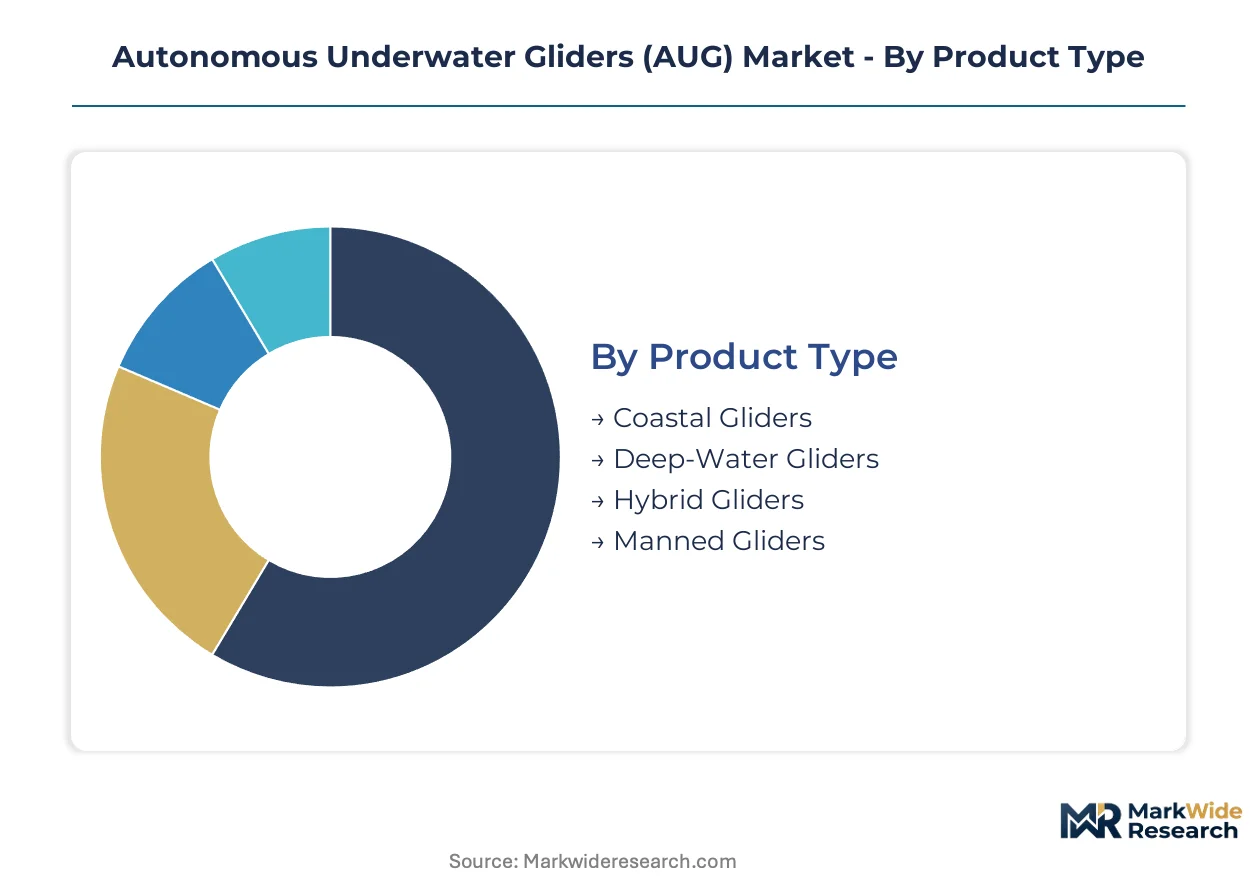
Segmentation in the Autonomous Underwater Gliders market reveals how procurement concentration among defense agencies is redirecting product development priorities. Technology and application boundaries are blurring as multi-mission platforms displace single-purpose systems.
Product Type:
Coastal Gliders dominate domestic procurement channels, while Deep-Water Gliders drive export-led demand through NATO-adjacent defense contracts.
- Deep-Water Gliders:Titanium-composite pressure hulls rated for abyssal depths exceed six thousand meters. United States Navy contracts concentrate here, driven by seabed warfare mandates and ITAR-protected supplier qualifications.
- Coastal Gliders:Shallow-rated aluminum or composite hulls serve continental shelf operations. NOAA and research institutions in the United States fund fleet expansion for climate baseline transects.
- Hybrid Gliders:Propulsion systems combine buoyancy drive with auxiliary thrusters for station-keeping.
- Manned Gliders:Piloted variants serve training and certification roles in naval programs.
Deep-Water Gliders command the established base. The steepest expansion runs through Coastal Gliders.
Technology:
Sensor payload costs stratify platform economics, with acoustic arrays commanding premium positioning against optical alternatives.
- Acoustic Sensors:Miniaturized hydrophone arrays enable anti-submarine warfare and seabed mapping missions. Defense Operations in the United States absorb the dominant procurement volume, constrained by ITAR export controls on precision hardware.
- Chemical Sensors:Dissolved oxygen, pH, and nutrient analyzers support Environmental Monitoring mandates. NOAA transect programs in the United States drive adoption for climate baseline establishment.
- Optical Sensors:Camera and fluorometer payloads serve biological sampling missions.
- GPS Navigation:Surface-fix positioning systems enable drift correction and mission recovery.
Acoustic Sensors anchor the revenue base. Chemical Sensors are climbing the fastest as climate monitoring budgets expand.
Application:
Mission profiles diverge sharply between classified defense intelligence and open-data oceanographic publication requirements.
- Defense Operations:Persistent subsurface intelligence collection and seabed infrastructure survey. United States Navy operational certification standards restrict platform access to domestic suppliers.
- Environmental Monitoring:Long-duration transects for climate baseline establishment and pollution tracking. Government Agencies in the United States prioritize this segment through NOAA fleet modernization.
- Oceanography:Physical and biological process studies by academic consortia.
- Marine Research:Fisheries assessment and ecosystem dynamics investigation.
Defense Operations hold the incumbent position. Environmental Monitoring shows the steepest expansion trajectory.
End User:
Procurement authority concentration shapes contract access, with federal agencies displacing historical research-institution primacy.
- Government Agencies:United States Navy and NOAA impose operational certification standards that systematically exclude non-domestic platforms. Multi-month endurance requirements now dominate specification sheets.
- Research Institutions:Academic oceanographic programs face displacement from prime contract vehicles. Environmental Organizations and university consortia seek extended-duration platforms through secondary funding channels.
- Environmental Organizations:Non-governmental monitoring programs for marine protected areas.
- Commercial Entities:Offshore energy and seabed mining survey contractors.
Government Agencies control the established demand base. Research Institutions are gaining share fastest through climate science foundation funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal's Pacific-Atlantic linkage underwrites United States naval logistics for AUG deployment across two-ocean operations. Submarine cable landing stations in Portugal and Singapore anchor data relay infrastructure for transoceanic glider missions. Deep-water port facilities in Norway and Japan concentrate pressure-hull fabrication and sensor integration capacity.
United States
Naval Station Norfolk and Naval Base San Diego host the largest AUG operational fleets for anti-submarine warfare training and seabed survey missions. The Navy's operational certification standards systematically exclude non-domestic platforms from federal procurement channels under ITAR export control frameworks. Woods Hole Oceanographic Institution in Massachusetts and Scripps Institution of Oceanography in California coordinate NOAA-funded climate baseline transect programs using coastal-rated systems.
Norway
Kongsberg's naval heritage anchors NATO-adjacent defense contracts for deep-water glider platforms with integrated seabed warfare capabilities. The country's national defense procurement agency prioritizes lithium-sulfur battery chemistries for Arctic endurance missions exceeding ninety days. The Kongsberg industrial cluster concentrates titanium-composite pressure hull fabrication and miniaturized acoustic sensor assembly.
Japan
The Japan Agency for Marine-Earth Science and Technology operates sustained deep-water transect programs across the Pacific plate boundary for earthquake precursor monitoring. METI funding channels support indigenous platform development to reduce dependency on ITAR-restricted sensor imports. The Kobe-Osaka maritime engineering corridor hosts specialized foundries for precision hydrophone array production.
United Kingdom
The Royal Navy's seabed infrastructure protection mandates drive demand for persistent subsurface intelligence collection in North Atlantic transit corridors. UK Ministry of Defence procurement frameworks increasingly require ISO 9001 quality certification for competitive evaluation eligibility. The Plymouth marine science cluster integrates academic oceanographic programs with defense contractor sensor payload development.
Australia
The Australian Defence Force accelerates AUG acquisition for Indo-Pacific maritime domain awareness across exclusive economic zone patrol requirements. The national defense regulator mandates operational interoperability with United States Navy data formats and communication protocols. The Perth-Fremantle submarine base complex hosts joint exercise programs validating long-endurance platform performance in southern hemisphere conditions.
Autonomous Underwater Gliders (AUG) Market Competitive Environment
Concentration sits with defense-heritage maritime systems integrators and specialized subsea robotics engineering houses. Tier-one suppliers leverage naval operational certification relationships to secure multi-year platform procurement vehicles. Three archetypes dominate: Nordic naval technology conglomerates with seabed warfare integration capabilities, United States-based buoyancy-drive propulsion specialists, and Canadian subsea engineering firms with Arctic endurance expertise. Competitive moves center on lithium-sulfur battery chemistry integration partnerships and ISO 9001 certification acceleration to meet Navy qualification timelines.
Within the defense-integrated systems tier, Kongsberg Maritime and Saab AB exemplify Nordic suppliers capturing NATO-adjacent contracts through regional autonomy advantages. Teledyne Webb Research occupies a position among United States-based specialists sustaining technology leadership in buoyancy-driven architectures. These three anchors represent distinct competitive vectors: seabed warfare system bundling, long-endurance platform specialization, and operational certification proximity to federal procurement channels.
| Leading Market Players |
|---|
| Bluefin Robotics |
| The ECA Group |
| Teledyne Webb Research |
| Fugro |
| Saab AB |
| Kongsberg Maritime |
| Boston Engineering Corporation |
| International Submarine Engineering |
| L3 OceanServer |
| Others |
Value Chain & Pricing Dynamics
ITAR export control frameworks gate both supplier qualification and price differentiation simultaneously, restricting federal contract access to domestic manufacturers while compressing margins for non-qualified competitors. United States Navy procurement standards concentrate buying power among certified vendors, enabling premium pricing for deep-water platforms while coastal systems face cost compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and endurance specification. Premium tiers command substantial markups for ITAR-compliant deep-water gliders with lithium-sulfur battery architectures, while economy tiers serve research institutions with alkaline-powered coastal systems. Price differentiation stems from operational certification proximity and sensor payload complexity. Pricing pressure intensifies in coastal segments as NOAA budget constraints compress procurement allowances. Research institutions exhibit highest price sensitivity; defense procurement agencies demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
The United States and Norway anchor titanium-composite pressure hull fabrication, while Japan concentrates precision hydrophone array foundry capacity. Raw material dependencies include lithium-sulfur battery cells, titanium alloy stock, and specialized acoustic sensor substrates. Supply chain risk centers on single-source vulnerability for ITAR-restricted sensor payloads subject to export control tightening. Distribution runs through defense procurement channels for classified systems, with research institutions accessing platforms via academic consortia and secondary funding mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated sharply around United States federal agencies, with Navy and NOAA procurement now displacing historical research-institution primacy and reshaping supplier prioritization.
For Market Incumbents: Fortify ITAR certification maintenance and lithium-sulfur battery chemistry partnerships to defend against emerging Canadian Arctic endurance specialists. Lock in multi-year Navy operational certification renewals before qualification timelines extend further. Prioritize in-house production of miniaturized acoustic sensor arrays to reduce foundry dependency and protect margin structure. For New Entrants and Emerging Players: Differentiate on environmental monitoring applications for European climate science foundations seeking ITAR-free platform alternatives. Target Nordic defense procurement agencies accelerating indigenous development to escape United States export restrictions. Pursue joint development agreements with Japanese METI-funded programs for Pacific plate boundary monitoring missions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed subsea robotics engineering houses holding ISO 9001 certifications but lacking Navy operational qualification proximity. Long-term viability hinges on defense contract conversion rates over climate monitoring foundation funding sustainability. Watch for seabed sovereignty claim escalations as inflection indicators for classified procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Sulfur Battery Integration Partnership | United States Navy mandates these chemistries for ninety-day endurance contracts. |
| ISO 9001 Quality Certification Acceleration | United Kingdom Ministry of Defence procurement frameworks require this for competitive eligibility. |
| Acoustic Sensor Payload Miniaturization R&D | Anti-submarine warfare integration demands drive precision hydrophone array advancement. |
| Indigenous Platform Development Program | European defense agencies respond to ITAR tightening with autonomous capability investment. |
| Climate Baseline Transect Fleet Expansion | NOAA funding prioritizes oceanographic density for environmental monitoring segment growth. |
Study Parameters
Operator-level perspectives from Navy program managers, NOAA fleet directors, subsea robotics engineering leads, and defense procurement officers anchored the qualitative base. Primary interview findings triangulated against secondary sources including SEC contractor filings, United States federal budget appropriation documents, NATO defense procurement databases, and academic oceanographic consortium mission reports. Bottom-up platform shipment estimates and top-down defense budget allocation analysis converged on segment-level sizing.
Sensitivity analysis tested forecast robustness across the projection horizon against battery chemistry transition timelines and ITAR regulatory tightening scenarios. Segmentation modeling incorporated product type, sensor technology, application mission profile, and end-user procurement authority dimensions. CAGRs derived from historical contract award trajectories and announced fleet modernization schedules, with lithium-sulfur adoption curves and seabed warfare mandate expansion as primary demand drivers.
Material uncertainties — seabed sovereignty claim escalations, acoustic sensor export control expansion, and Arctic endurance mission specification changes — sit outside the modeled envelope. Forecasts reflect documented procurement timelines and technology transition assumptions subject to revision from these factors. Recalibration cycles align with material shifts in defense budget appropriations and climate monitoring foundation funding availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Miniature Drone Market
UAV
Auto-Follow Drone Market
UAV
Solar Powered Drones Market
UAV
Global Drone Data Services Market
UAV
Drone Inspection Service Market
UAV
Autonomous Aircraft Cameras Market
UAV
UAV Navigation Systems Market
UAV
Drone Roof Inspection Market
UAV
Europe Tethered Drone Market
UAV
GCC Drone Pilot Training Market
UAV
Global Drone Software Market
UAV
FPV Drone Goggles Market
UAV
Global Aerial Survey Services Market
UAV
Small Drone Market
UAV
Asia Pacific Small UAV Market
UAV
UAV Sense-And-Avoid Systems Market