
 Micro Motor Market | 2026-2036
Micro Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Motor Market Intelligence
OEM-direct procurement is tilting toward brushless architectures as appliance and automotive buyers consolidate supplier lists. Nidec Corporation leverages its vertical integration in hard-drive spindle motors to cross-sell precision brushless units into robotics. Mabuchi Motor sustains dominant channel positions in automotive actuators through dedicated production lines in China and Vietnam. Johnson Electric Holdings Limited differentiates via electromagnetic micro motor portfolios serving power tool brands across North America and Europe.
A micro motor converts electrical energy into mechanical motion in units typically below 100 watts output, employing wound copper armatures, rare-earth or ferrite magnets, and precision-machined housings to deliver controlled torque in confined spaces. Brushless DC motors now command the largest product-type share due to their superior efficiency and reduced maintenance in continuous-duty applications, while piezoelectric variants represent the fastest-expanding technology segment for nanopositioning tasks in semiconductor inspection equipment. Servo motors concentrate margin pools in medical devices and industrial automation where closed-loop feedback commands premium pricing over open-loop stepper alternatives.
Japan's METI enforces Top Runner standards that compel motor efficiency gains in home appliances and HVAC systems, while the EU Ecodesign Directive phases out underperforming brushed motors in power tools and consumer goods. China's GB standards and dual carbon goals from MEE tighten energy-consumption benchmarks for motors deployed in electric vehicles and factory automation. Stakeholders must monitor how REACH compliance on permanent magnet materials and evolving rare-earth supply rules from China's MIIT reshape cost structures and sourcing geography for high-performance micro motor architectures.
Market Dynamics
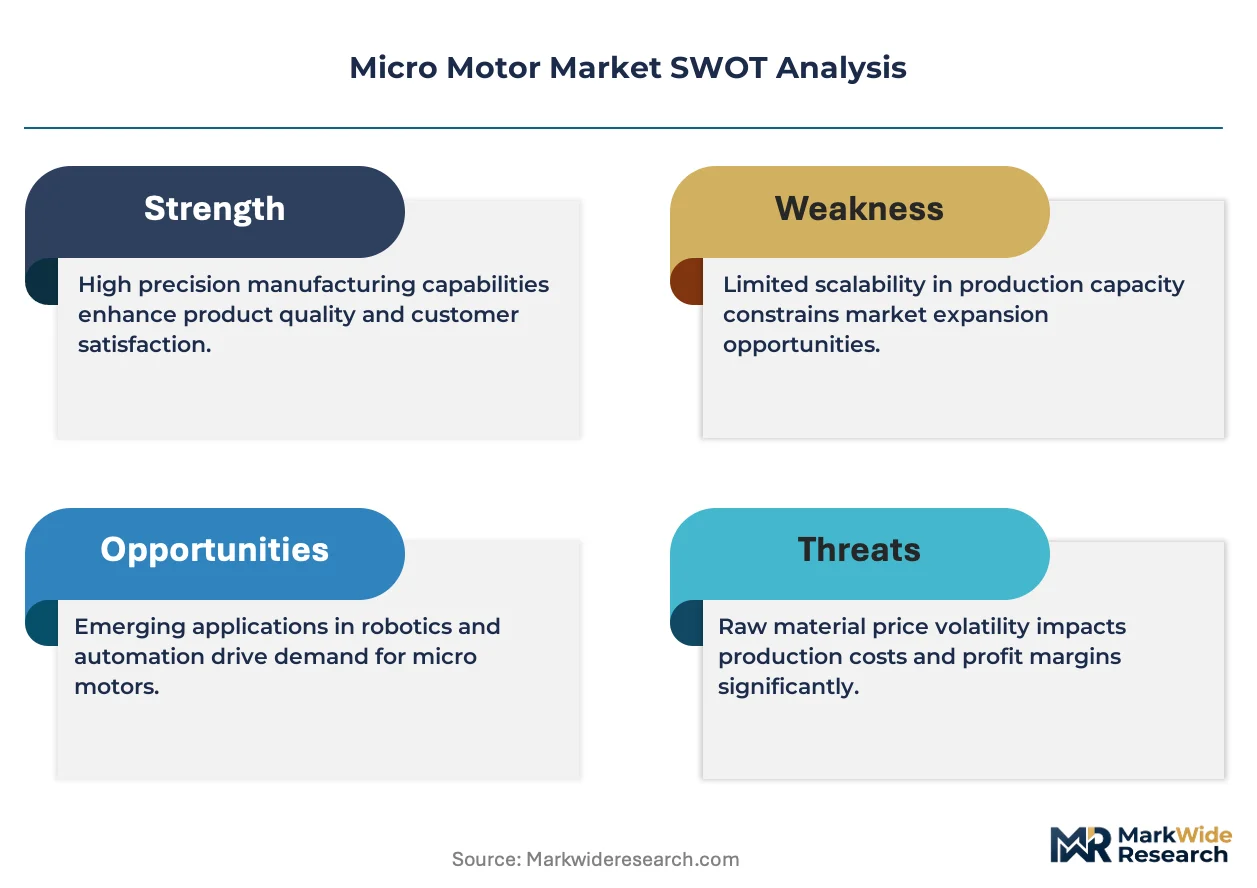
Brushless DC architectures are compressing traditional brushed motor volumes as efficiency mandates from Japan's METI and China's MEE eliminate margin tolerance for legacy designs in appliances and electric vehicles.
Growth Catalysts
- Surgical Robotics Procurement:Medical device OEMs are expanding precision motor orders for minimally invasive surgical platforms and diagnostic imaging gantries, with brushless units specified for torque repeatability.
- EU F-Gas Regulation:The regulation's phase-down of high-GWP refrigerants is accelerating compressor motor upgrades in HVAC systems, forcing adoption of electronically commutated designs.
- Semiconductor Inspection Equipment:Piezoelectric micro motors are penetrating nanopositioning stages for wafer metrology, displacing electromagnetic alternatives in sub-micron alignment tasks.
Market Restraints
- Rare-Earth Magnet Concentration:Neodymium and dysprosium supply chains concentrate in China's mining and processing corridors, exposing cost volatility under MIIT export licensing protocols.
- REACH Compliance Burden:ECHA registration requirements for permanent magnet coatings and rotor alloys are extending qualification timelines for European-bound shipments.
- Copper Winding Cost Exposure:Armature copper represents 15-25% of bill-of-materials for wound-rotor designs, with LME price swings compressing assembler margins.
Strategic Opportunities
- India Manufacturing Localization:PLI scheme incentives for component indigenization are opening captive production opportunities for motors serving domestic appliance and automotive actuator demand.
- Power Tool Cordless Conversion:Lithium-ion battery platforms are creating white space for compact brushless motors in professional-grade cordless equipment, displacing brushed nickel-cadmium legacy systems.
- Automotive Thermal Management:Electric vehicle battery cooling circuits are specifying high-efficiency micro pumps and fans, with China's dual carbon goals mandating efficiency thresholds that favor premium motor architectures.
Industry Challenges
- Electromagnetic Compatibility Certification:FCC Part 15 and CE marking for radiated emissions are extending validation cycles for variable-frequency drive controllers paired with brushless motors.
- Precision Machining Talent Scarcity:Stator lamination stamping and magnet alignment operations require specialized tool-and-die expertise that concentrates in aging workforces across Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Motor Market |
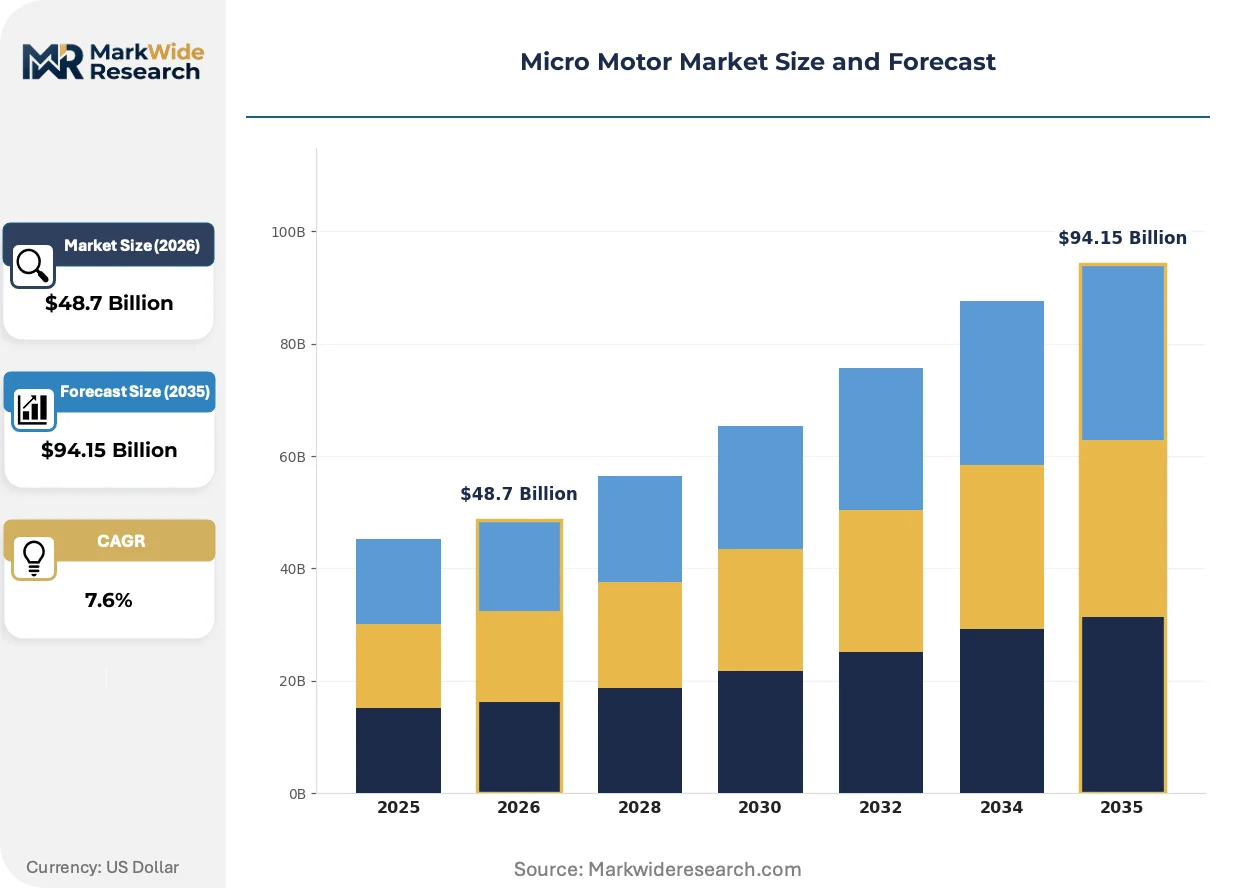
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $94.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushed DC Motors, Brushless DC Motors, Stepper Motors, Servo Motors Technology: Electromagnetic, Piezoelectric, Linear, Rotary End User: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Application: Robotics, HVAC Systems, Home Appliances, Power Tools |
| Companies Covered | Nidec Corporation, Mabuchi Motor, Johnson Electric Holdings Limited, Maxon, Mitsuba Corporation, Bühler Motor, Constar Micromotor Co., Ltd., DENSO Corporation, FAULHABER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Motor Market Strategic Shifts & Innovations
Silicon carbide power electronics and integrated motor-drive units are collapsing the physical separation between controllers and electromechanical cores, compressing system footprints and thermal budgets.
GaN-based inverter modules are collapsing switching losses in brushless motor drives, enabling higher pole counts and finer torque control. Surgical robot manufacturers in Germany and Japan are specifying these integrated packages for haptic feedback systems. The technology is collapsing the traditional boundary between power electronics and mechanical subassemblies.
Japan's METI Top Runner program is mandating efficiency gains in residential air conditioners and refrigerators, compelling motor suppliers to redesign winding configurations and magnetic circuits. Manufacturers are responding by qualifying amorphous metal stators and concentrated windings that reduce core losses. Home appliance OEMs in Osaka and Nagoya industrial corridors are consolidating supplier lists to partners with certified test facilities.
Direct OEM contracting is displacing tiered distribution networks for high-volume automotive actuator programs, with buyers consolidating supplier relationships to capture engineering integration savings. Tier-1 motor suppliers are establishing dedicated application engineering teams at customer technical centers. This pattern is most visible in Stuttgart and Munich automotive clusters, where powertrain electrification is redefining sourcing protocols.
Micro Motor Market Segmentation
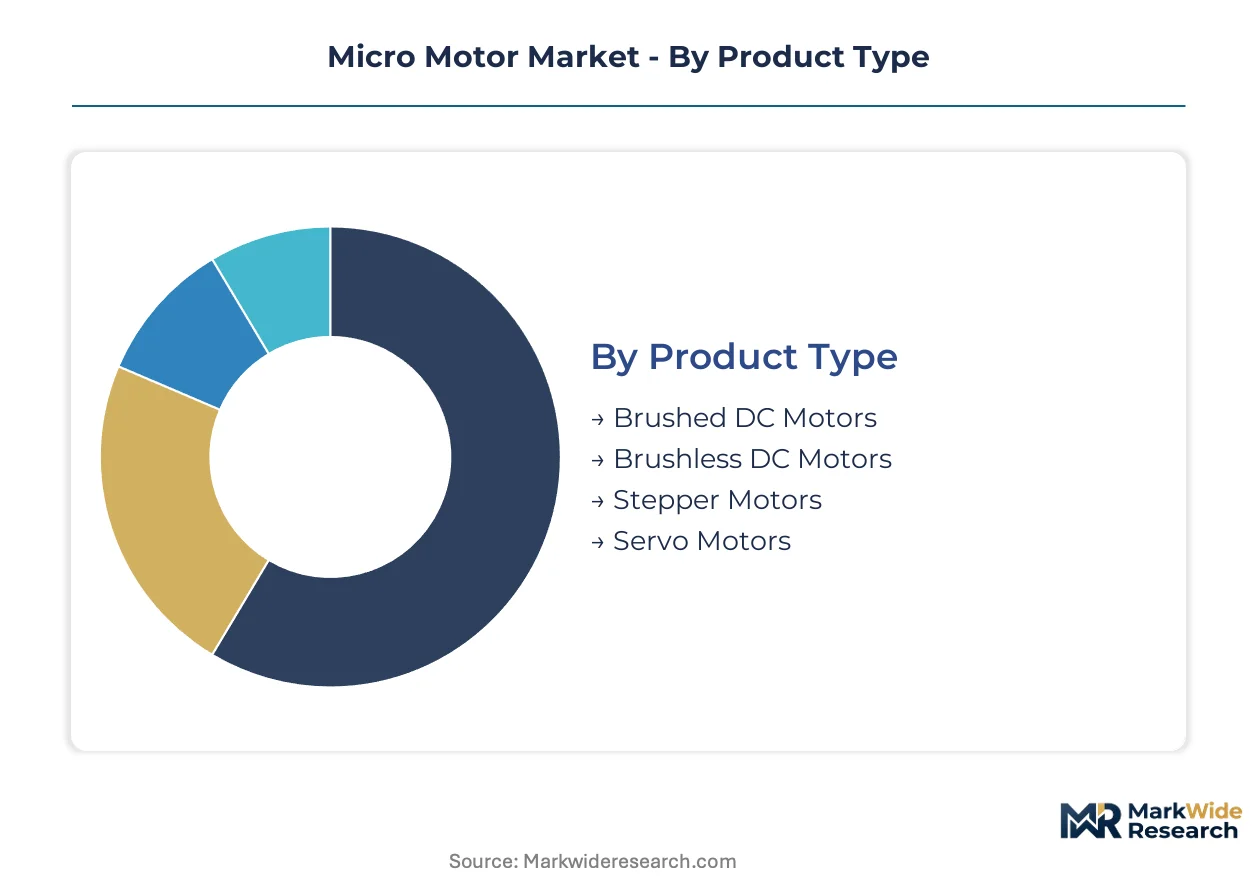
Micro motor procurement patterns diverge sharply across technical architectures and end-use specifications. Buyers in surgical robotics and electric vehicle thermal management impose distinct performance thresholds that reshape supplier priorities within each segment cluster.
Product Type:
Cost tier determines margin capture and qualification burden across motor architectures, with premium brushless designs commanding engineering-intensive procurement cycles.
- Brushless DC Motors:Electronically commutated designs eliminate mechanical brush wear through integrated Hall-effect sensors and permanent magnet rotors. Automotive OEMs in Stuttgart and Munich specify these for battery cooling pumps and seat actuators under China's dual carbon efficiency mandates.
- Brushed DC Motors:Mechanical commutation via carbon brushes against copper commutators delivers cost-optimized torque for intermittent-duty applications. Appliance manufacturers in India and Southeast Asia still specify these for price-sensitive home goods, though METI Top Runner standards are compressing their addressable market in Japan.
- Stepper Motors:Open-loop positioning systems with toothed rotors and pulsed stator excitation serve low-cost automation in Chinese factory floors.
- Servo Motors:Closed-loop feedback architectures with encoder-resolved positioning concentrate in German surgical robotics and Japanese semiconductor equipment.
Brushless DC Motors hold installed capacity. Servo Motors are rotating up the share rankings.
Technology:
Application requirements for precision, force density, and electromagnetic cleanliness determine which physical principle dominates motor selection.
- Piezoelectric:Ceramic crystal deformation under applied voltage generates nanometer-scale displacements without magnetic interference. Wafer metrology equipment manufacturers in Germany and Japan are specifying these for sub-micron alignment stages, displacing electromagnetic alternatives in cleanroom environments.
- Electromagnetic:Lorentz force interaction between current-carrying windings and magnetic fields produces rotary or linear motion across the broadest power range. Industrial automation clusters in China's Pearl River Delta and Germany's Ruhr region anchor volume demand for wound-rotor and permanent magnet variants.
- Linear:Direct electromagnetic thrust eliminates rotary-to-linear conversion losses in precision positioning tables.
- Rotary:Torque-producing architectures dominate where angular displacement meets mechanical load requirements.
Electromagnetic technology holds installed capacity. Piezoelectric is climbing the fastest in revenue contribution.
End User:
Customer type shapes specification intensity, with medical and automotive buyers imposing certification and traceability requirements that consumer electronics purchasers rarely match.
- Medical Devices:Surgical robotics and diagnostic imaging platforms demand torque repeatability, sterilization compatibility, and electromagnetic compatibility under FDA and MDR frameworks. German manufacturers in Tuttlingen and Japanese OEMs in Tokyo are consolidating supplier lists to partners with ISO 13485 certified production lines.
- Automotive:Thermal management actuators, mirror adjusters, and seat positioning systems specify motors across brushed and brushless architectures. China's NEV penetration and EU F-Gas Regulation are forcing efficiency upgrades in compressor and pump applications.
- Industrial Automation:Factory robotics and conveyor systems in China's Yangtze River Delta and Germany's Baden-Württemberg specify motors for continuous-duty cycles.
- Consumer Electronics:Smartphone haptics, camera autofocus, and personal care appliances drive high-volume, low-margin demand concentrated in Chinese assembly corridors.
Automotive holds installed capacity. Medical Devices is gaining share fastest on margin contribution.
Application:
Volume concentration and growth trajectory vary by mechanical task, with robotics and HVAC systems pulling divergent motor specifications.
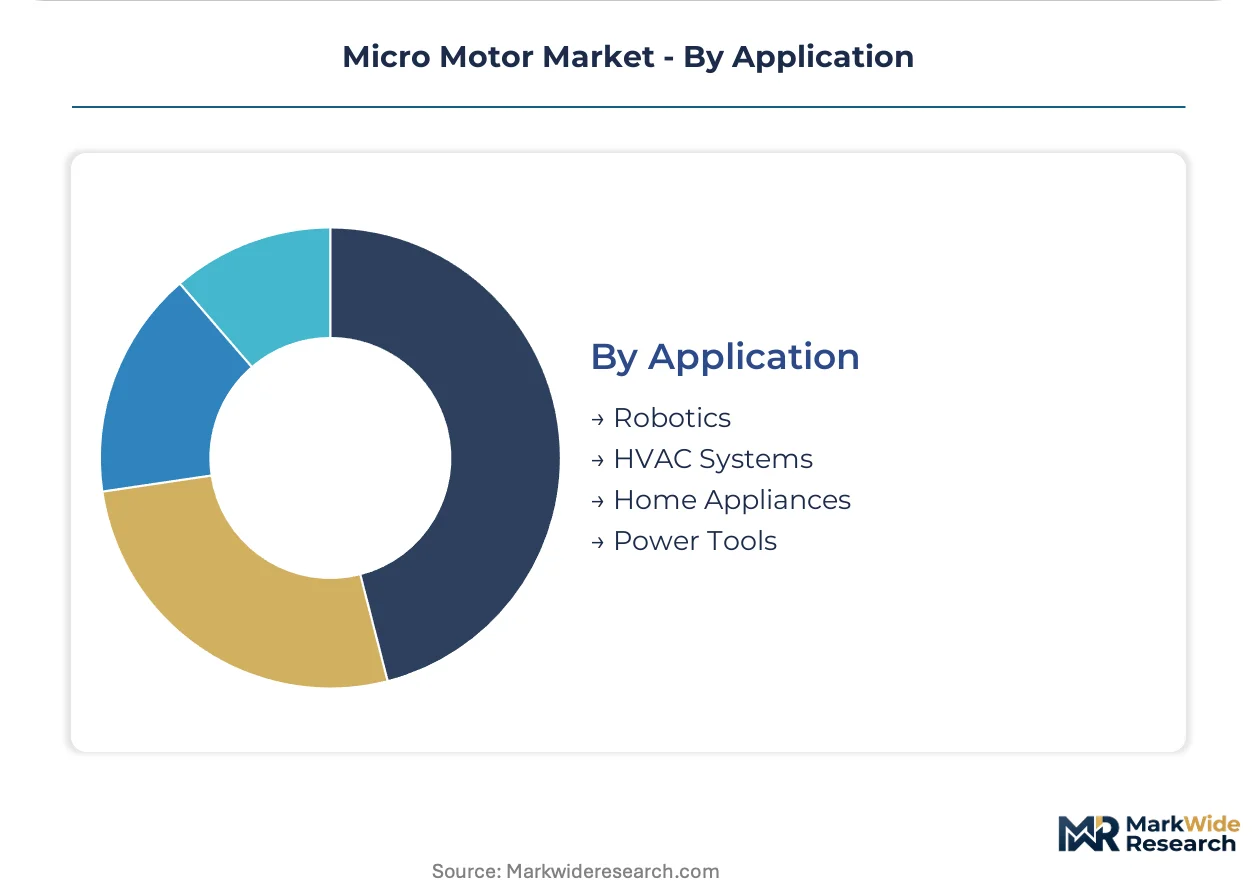
- HVAC Systems:Compressor motors and air handling units face efficiency mandates from Japan's METI Top Runner program and China's GB standards. Electronically commutated designs are displacing shaded-pole induction motors in residential air conditioners across Osaka and Nagoya industrial corridors.
- Robotics:Articulated arms and collaborative platforms specify high-torque-density brushless motors with integrated encoders for position feedback. German automotive suppliers and Japanese electronics assemblers are qualifying GaN-based integrated motor-drive packages for haptic feedback systems.
- Home Appliances:Refrigerator compressors, washing machine drums, and dishwasher pumps specify motors across efficiency tiers.
- Power Tools:Cordless lithium-ion platforms are creating specification space for compact brushless motors in professional-grade equipment.
HVAC Systems hold installed capacity. Robotics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in micro motor component exports, while Germany's Rhine-Danube corridor anchors European distribution networks for precision electromechanical assemblies.
China
Electric vehicle battery cooling systems and factory automation clusters in Shenzhen and Suzhou drive brushless DC motor procurement. MIIT's dual carbon mandates and GB efficiency standards compress tolerance for legacy brushed designs. The Pearl River Delta and Yangtze River Delta industrial corridors concentrate winding and magnet assembly operations serving domestic automotive OEMs.
Germany
Stuttgart and Munich automotive clusters specify high-torque-density motors for thermal management actuators and seat positioning systems. The EU F-Gas Regulation forces compressor motor upgrades in HVAC applications. Tuttlingen's surgical instrument manufacturers consolidate supplier lists to partners with ISO 13485 certified production lines for robotics platforms.
Japan
Home appliance OEMs in Osaka and Nagoya industrial corridors source motors under METI Top Runner efficiency mandates for residential air conditioners and refrigerators. Semiconductor equipment manufacturers in Tokyo specify piezoelectric nanopositioning stages for wafer metrology. Nagoya's robotics integrators qualify GaN-based integrated motor-drive packages for haptic feedback systems.
United States
Power tool manufacturers in the Midwest and Southeast convert lithium-ion battery platforms to brushless architectures for professional-grade cordless equipment. FCC Part 15 electromagnetic compatibility requirements extend validation cycles for variable-frequency drive controllers. Medical device clusters in Minnesota and Massachusetts impose FDA traceability standards on surgical robotics motor suppliers.
India
Domestic appliance and automotive actuator demand accelerates under PLI scheme incentives for component indigenization. BIS efficiency benchmarks and CEA power quality standards reshape procurement specifications for factory automation motors. Gujarat and Maharashtra industrial corridors attract captive production facilities serving local OEM assembly operations.
Micro Motor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base separates into three tiers: multinational conglomerates with captive magnet processing, mid-cap winding houses serving regional appliance clusters, and precision specialists qualified for medical and aerospace specifications. Consolidation pressure concentrates among winding houses as efficiency mandates eliminate margin tolerance for undifferentiated brushed motor production. Geographic expansion and backward integration into rare-earth magnet sourcing represent the dominant competitive vectors.
Among Japanese-headquartered conglomerates, Nidec Corporation and Mabuchi Motor occupy positions spanning hard-drive spindle motor heritage to cross-sold precision brushless architectures. Johnson Electric Holdings Limited exemplifies the Hong Kong-based specialist model with electromagnetic portfolio concentration. These three entities represent distinct archetypes: verticalized magnet-to-system integration, dedicated regional production line deployment, and application-specific electromagnetic specialization.
| Leading Market Players |
|---|
| Nidec Corporation |
| Mabuchi Motor |
| Johnson Electric Holdings Limited |
| Maxon |
| Mitsuba Corporation |
| Bühler Motor |
| Constar Micromotor Co., Ltd. |
| DENSO Corporation |
| FAULHABER Group |
| Others |
Cost & Logistics Intelligence
The Port of Shanghai's container throughput cost dynamics compress margins for rare-earth magnet shipments while amplifying price differentiation between medical-grade certified motors and commodity appliance units. Supply concentration in China's magnet processing corridors concentrates pricing power upstream, forcing downstream assemblers to absorb volatility or pass through costs to efficiency-mandated buyers in Germany and Japan.
Pricing Analysis
Volume-discount tiering structures stratify across premium ISO 13485-certified surgical motor lines, standard industrial automation units, and economy brushed designs for Indian appliance markets. Price differentiation hinges on magnet grade certification and Hall-sensor integration complexity. Cost compression in economy tiers intensifies because China's MIIT export licensing protocols inject neodymium price volatility. Medical device OEMs in Tuttlingen exhibit least price sensitivity; Southeast Asian appliance manufacturers demonstrate highest sensitivity.
Supply Chain Analysis
Extended payment terms from Japanese automotive OEMs and supply-chain finance facilities anchored in Stuttgart compress working capital cycles for mid-tier winding houses. Magnet processing concentrates in China; precision machining clusters in Japan and Germany; final assembly localizes in Vietnam and India under PLI incentives. Copper winding and rare-earth magnet dependencies tether cost structures to LME price corridors and MIIT export protocols. Single-source vulnerability concentrates in dysprosium separation capacity. Distribution runs through direct OEM contracting for automotive programs and tiered electronics distributors for appliance replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as efficiency mandates splinter demand into certifiable premium tiers and cost-optimized economy segments. Surgical robotics procurement and power tool cordless conversion create addressable niches beyond incumbent strongholds.
For Market Incumbents: Build certification moats around ISO 13485 production lines serving German surgical instrument manufacturers. Defensive moves center on backward integration into rare-earth magnet sourcing and dedicated application engineering teams at Stuttgart and Munich technical centers. Threat from GaN-integrated motor-drive specialists demands R&D investment in silicon carbide controller integration. Channel control through direct OEM contracting captures engineering integration savings.
For New Entrants and Emerging Players: India's PLI scheme corridors in Gujarat and Maharashtra present geographic underpenetration for captive production facilities serving domestic appliance OEMs. White-space targets include professional-grade cordless power tool motors and automotive thermal management pumps under China's dual carbon mandates. Go-to-market angle emphasizes BIS efficiency certification and localized winding operations to displace Chinese import dependency.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant precision motor divisions lacking medical or automotive certification traction. Long-term viability frames around 5-10 year efficiency mandate acceleration across Japan's METI Top Runner program and EU Ecodesign Directive phase-outs. Acquisition archetype: mid-cap winding houses with tool-and-die expertise in aging Japanese or German workforces. Signal to watch: MIIT rare-earth export license tightening as inflection indicator for magnet cost volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Processing | Captive neodymium supply insulates margin from MIIT export licensing volatility. |
| ISO 13485 Certification Investment | Medical device OEMs in Tuttlingen consolidate supplier lists to certified production lines. |
| GaN-Based Integrated Motor-Drive Development | German surgical robot manufacturers specify these packages for haptic feedback systems. |
| PLI-Aligned Manufacturing Localization in India | Gujarat and Maharashtra corridors attract captive facilities serving domestic automotive assembly. |
| Direct OEM Application Engineering Deployment | Stuttgart and Munich automotive clusters consolidate supplier relationships for electrification programs. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with motor procurement directors at German automotive OEMs, biomedical engineers at Japanese surgical robotics manufacturers, plant managers at Chinese winding houses, and aftermarket service heads at Indian appliance brands; and secondary validation through MIIT rare-earth export filings, METI efficiency standard disclosures, EU ECHA REACH registration databases, and SEC filings from publicly traded motor suppliers. Bottom-up and top-down triangulation cross-checked unit shipment estimates against rare-earth magnet consumption patterns and copper winding demand.
Forecast inputs considered brushless versus brushed architecture migration rates, piezoelectric penetration in semiconductor equipment, and regional efficiency mandate enforcement timelines across the projection horizon. Segmentation dimensions modeled include product type, technology principle, end-user certification requirements, and regional regulatory cluster. CAGRs derived from slope analysis of historical efficiency standard adoption curves and OEM platform electrification roadmaps. Industry-specific inputs incorporated Hall-sensor integration cost curves and amorphous metal stator qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed magnet processors or GaN semiconductor entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Machine Tool Cooling System Market