
 North America Tank Protection Market | 2026-2036
North America Tank Protection Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tank Protection Market Analytics
Water treatment infrastructure is rebalancing toward advanced corrosion protection as municipal utilities upgrade aging storage assets. PPG Industries leverages its coatings portfolio to anchor positions across industrial end users. Sherwin-Williams Company sustains channel density through distributor networks serving remote oilfield operations. AkzoNobel N.V. differentiates via marine-grade formulations adapted for aggressive chemical environments.
Tank protection encompasses engineered systems and applied materials that prevent structural degradation, leakage, and environmental release from aboveground and underground storage vessels; specifications include epoxy lining thicknesses of 250-500 microns, zinc-rich primers with sacrificial cathodic protection, and polyurethane topcoats rated for immersion service. Passive protection leads material spending due to lower lifecycle costs in chemical processing, while active systems represent the fastest-growing category as remote monitoring integration expands. Composite materials command premium positioning in fiberglass-reinforced applications where steel corrosion rates exceed design tolerances.
EPA Underground Storage Tank regulations, API 653 tank inspection standards, and OSHA process safety management requirements collectively mandate integrity testing intervals and protective coating performance benchmarks across United States facilities. Canadian Environmental Protection Act provisions and provincial spill contingency rules in Ontario and Alberta extend comparable compliance obligations northward. Stakeholders must monitor evolving PFAS restrictions and their implications for conventional coating chemistries.
Market Dynamics
EPA Underground Storage Tank regulations and API 653 inspection standards are tightening compliance cycles across United States facilities, forcing asset owners into accelerated recoating schedules and driving specification upgrades from commodity epoxies toward high-performance polyurethane systems.
Growth Catalysts
- Texas petrochemical corridor expansion:Gulf Coast refinery and terminal capacity additions are generating concentrated demand for immersion-grade lining systems in crude oil and refined product storage.
- EPA spill prevention mandates:The agency's SPCC rule amendments are compelling aboveground tank farms to install secondary containment and corrosion monitoring systems ahead of inspection deadlines.
- Polyurea spray technology:Rapid-cure elastomeric coatings are reducing tank outage windows from weeks to days, enabling maintenance during narrow seasonal shutdown windows.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate pricing fluctuations compress coating applicator margins and deter long-term project commitments.
- Canadian prairie supply concentration:Saskatchewan and Alberta tank fabrication capacity limits create bottlenecks for large-diameter field-erected storage vessels.
- PFAS regulatory friction:State-level restrictions on fluorinated chemistries in Washington and Maine are forcing reformulation of legacy PTFE-enhanced tank linings without proven substitutes.
Strategic Opportunities
- Great Lakes water treatment infrastructure:Michigan and Ohio municipal utilities are replacing century-old cast iron reservoirs with coated steel tanks, opening specification windows for NSF-certified potable water linings.
- Digital twin integration:Remote corrosion monitoring sensors paired with predictive analytics platforms are creating recurring revenue streams beyond initial coating application.
- US Inflation Reduction Act biofuels incentives:Renewable diesel and sustainable aviation fuel tax credits are accelerating tank farm construction for feedstock storage and finished product blending.
Industry Challenges
- NACE-certified inspector scarcity:API 653 and SSPC coating inspection credentials require specialized training pipelines that lag behind retirement-driven workforce attrition.
- Legacy tank substrate variability:Uncharted pitting depths and undocumented prior coating layers complicate surface preparation specifications and warranty underwriting.
- Multi-jurisdictional permitting:California South Coast AQMD, Texas TCEQ, and Ontario MECP each impose distinct VOC emission limits on coating operations, fragmenting contractor mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tank Protection Market |
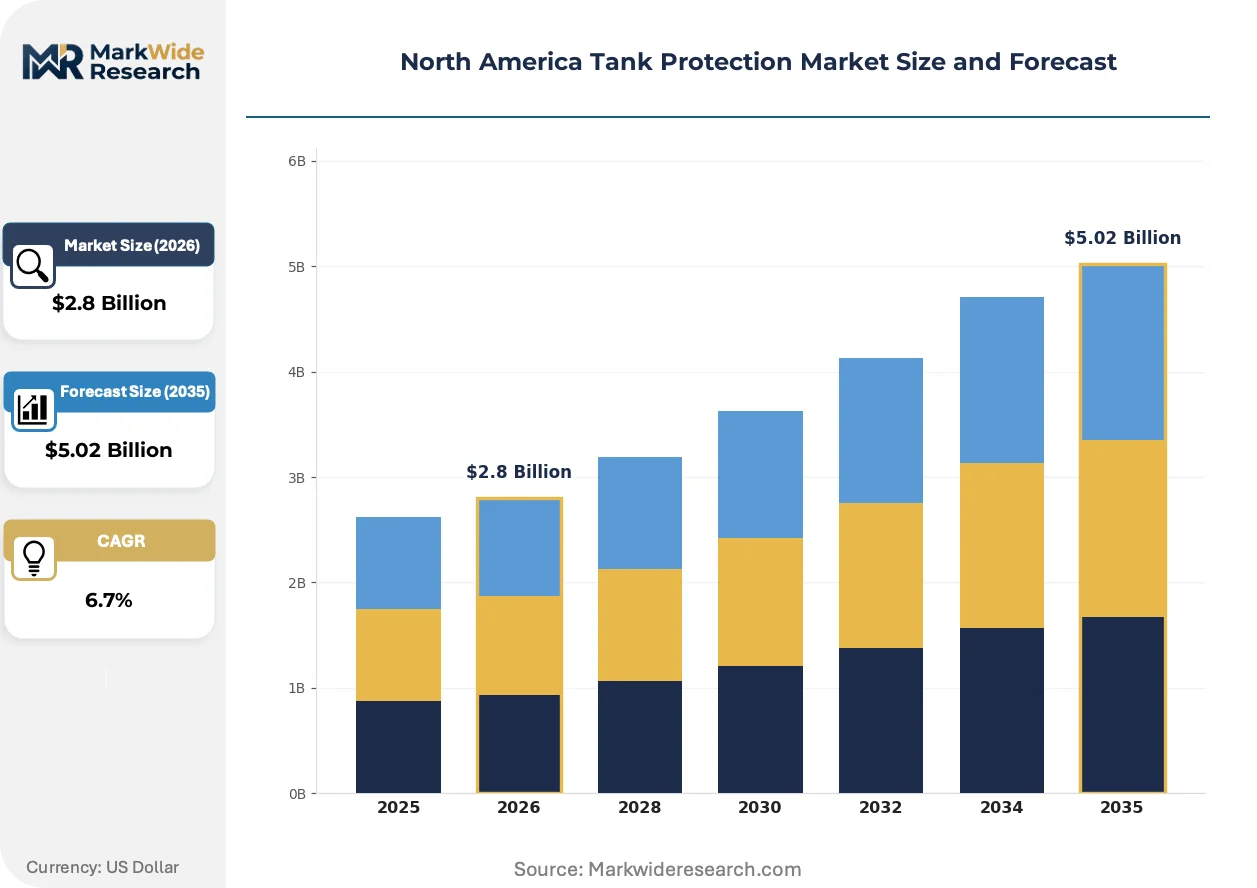
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Protection Type: Active, Passive, Hybrid, Secondary Containment Material: Steel, Fiberglass, Composite, Concrete Application: Oil & Gas, Chemicals, Water Treatment, Agriculture End User: Industrial, Commercial, Municipal, Residential |
| Companies Covered | PPG Industries, Sherwin-Williams Company, AkzoNobel N.V., BASF SE, RPM International Inc., Rockwool International A/S, Owens Corning, Saint-Gobain, Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tank Protection Market Evolving Landscape
Coating chemistry evolution and inspection digitization are compressing maintenance cycles while elevating performance benchmarks across North American tank assets. These shifts are redefining supplier value propositions beyond material supply toward integrated asset protection services.
Glass-flake reinforced vinyl ester linings are overtaking conventional epoxy novolacs in sulfuric acid storage service above 70% concentration. Gulf Coast chemical terminals are specifying these systems for 15-year design lives, displacing rubber-lined steel and hastening the obsolescence of asphaltic coatings in aggressive chemical duty.
OSHA process safety management amendments are mandating real-time emissions monitoring during tank coating operations. Industrial facilities in Houston and Beaumont are deploying portable fenceline detection systems to satisfy Texas Commission on Environmental Quality enforcement protocols, with compliance costs reshaping contractor bidding strategies and project phasing.
Buyers are consolidating coating procurement under multi-site master service agreements with integrated inspection and warranty terms. Large midstream operators across the Permian Basin and Bakken formation are displacing transactional spot purchasing, compressing the vendor base and privileging applicators with captive engineering and in-house QA capabilities.
North America Tank Protection Market Segmentation
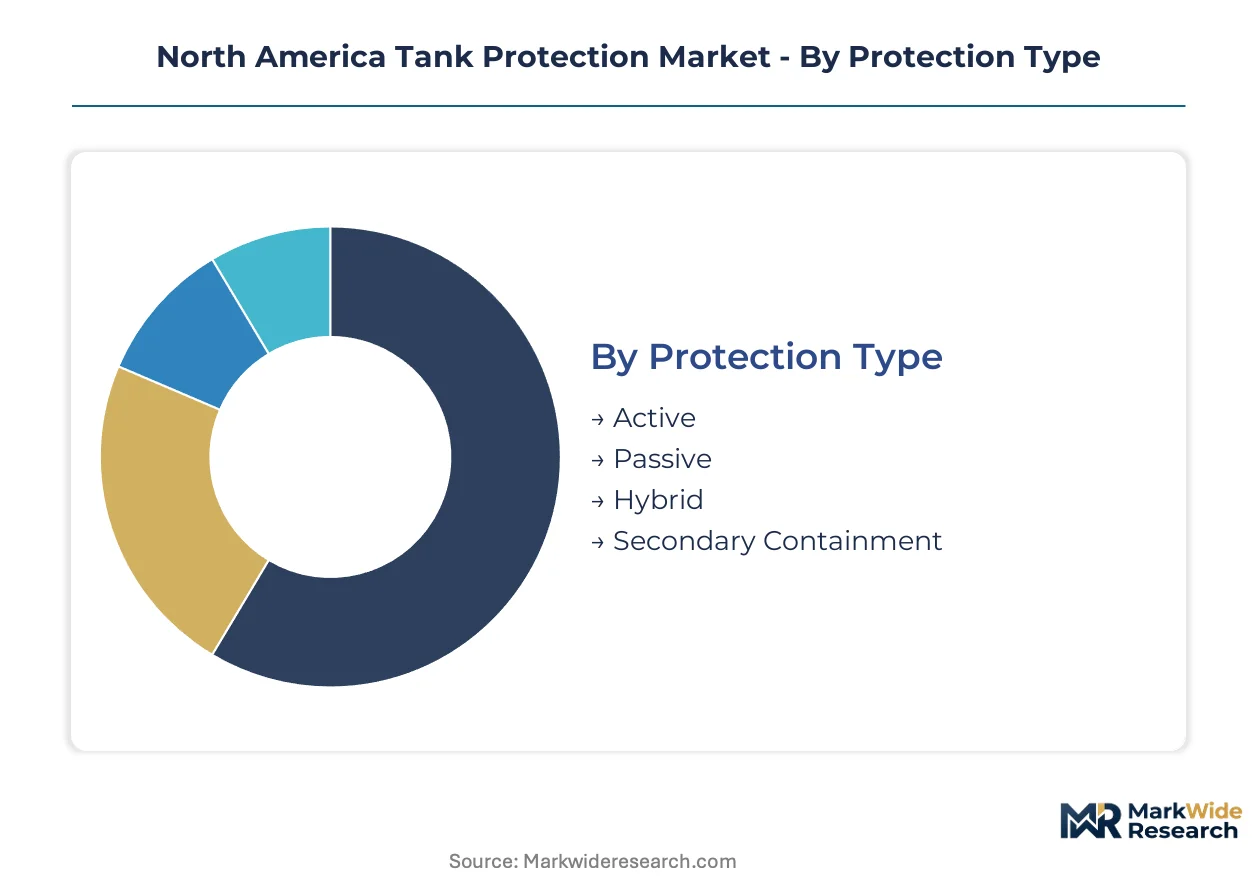
Tank protection procurement patterns diverge sharply across protection mechanisms, substrate materials, and end-use applications. Specification requirements from EPA, API, and provincial regulators fragment demand into distinct technical tiers with incompatible warranty and compliance frameworks.
Protection Type:
Supply concentrates around cathodic protection contractors in Houston and Calgary corridor, with passive coating applicators dominating maintenance spend.
- Passive:Epoxy, polyurethane, and vinyl ester coating systems applied as barrier layers against chemical and environmental degradation. Texas petrochemical terminals specify 500-micron epoxy novolacs for crude storage, driven by API 653 recoating intervals and sulfuric acid vapor exposure.
- Active:Impressed current and sacrificial anode systems delivering electrochemical corrosion inhibition. Gulf Coast salt dome storage facilities deploy remote-monitored rectifier networks, compelled by EPA spill prevention mandates and subsurface leakage liability exposure.
- Hybrid:Combined coating-cathodic protection architectures for high-risk assets. Michigan refinery tank farms specify these systems beneath secondary containment liners.
- Secondary Containment:Impermeable barriers surrounding primary vessels to capture releases. California AQMD jurisdictions mandate double-wall construction for aboveground gasoline storage.
Passive protection absorbs the bulk of installed capacity; active systems are expanding most quickly.
Material:
Cost tiers separate commodity steel from premium composite specifications, with fiberglass commanding 40-60% price premiums in chemical service.
- Steel:Carbon and stainless steel substrates requiring external coating and internal lining systems. Great Lakes municipal water utilities specify epoxy-lined welded steel for potable reservoirs, replacing century-old cast iron infrastructure.
- Fiberglass:Glass-reinforced thermoset vessels with inherent corrosion resistance. Alberta oilfield chemical injection systems specify fiberglass for produced water handling, eliminating external cathodic protection.
- Composite:Advanced fiber-reinforced polymers for extreme chemical and temperature duty. Ohio chemical processors specify vinyl ester composites for concentrated sulfuric acid above 70% concentration.
- Concrete:Prestressed and reinforced concrete for large-volume water and wastewater storage. Texas water authorities specify lined concrete for 5-million-gallon capacity reservoirs.
Steel retains the dominant installed base; composites are gaining share fastest in chemical processing applications.
Application:
Customer type stratification separates specification-intensive industrial procurement from price-sensitive municipal bidding.
- Oil & Gas:Upstream, midstream, and downstream storage for crude, refined products, and natural gas liquids. Permian Basin terminal expansions specify immersion-grade linings for renewable diesel feedstock storage, accelerated by IRA biofuels tax credits.
- Chemicals:Aggressive service storage for acids, caustics, and specialty intermediates. Louisiana chemical corridor demand concentrates around glass-flake vinyl ester systems for sulfuric acid duty.
- Water Treatment:Potable water, wastewater, and industrial process water storage. Ohio and Michigan utilities drive NSF-certified epoxy lining specifications for municipal reservoir rehabilitation.
- Agriculture:Fertilizer, pesticide, and irrigation water storage. Saskatchewan grain terminals specify polyurethane-coated steel for liquid fertilizer containment.
Oil & Gas commands the largest specification volume; water treatment is climbing the fastest on infrastructure replacement cycles.
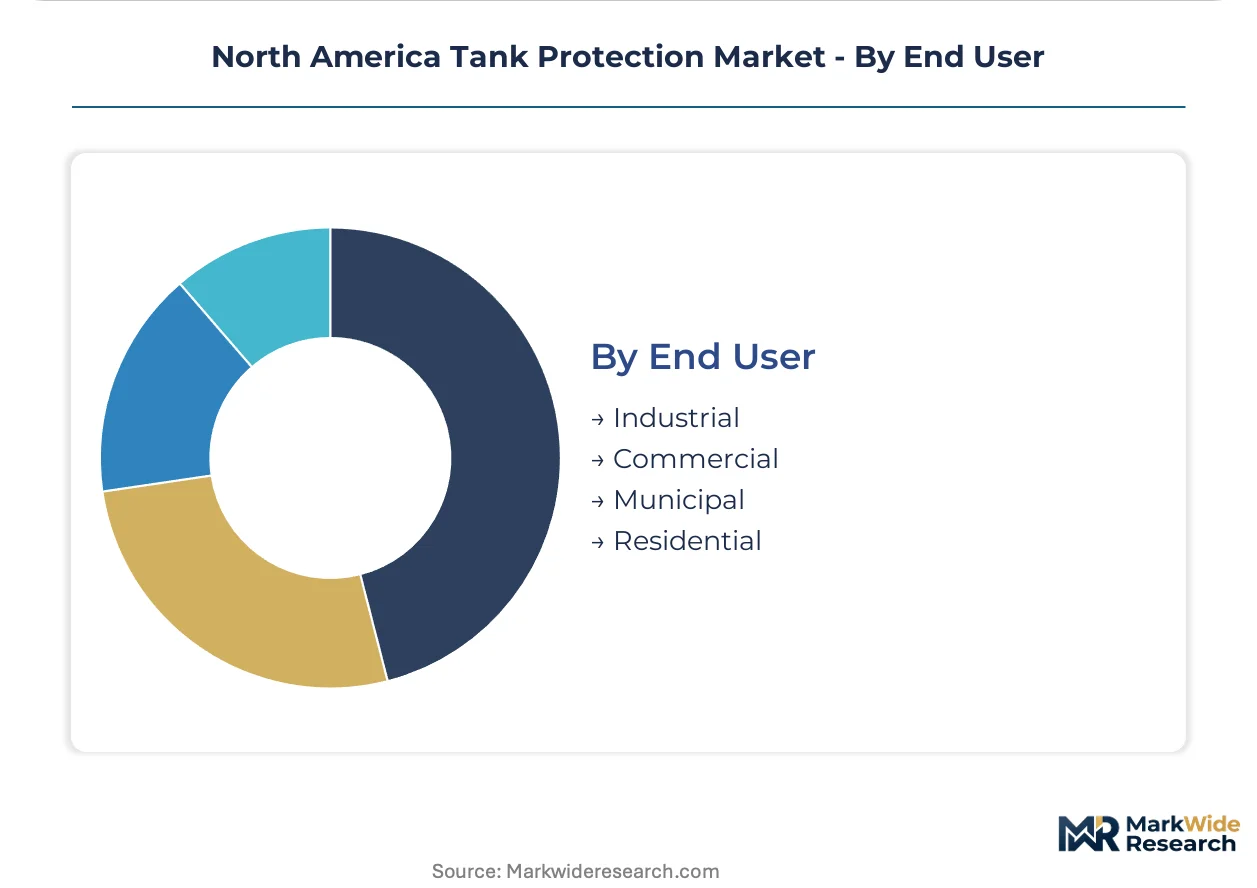
End User:
Volume concentration tilts toward industrial accounts with multi-site master service agreements, displacing transactional procurement.
- Industrial:Petrochemical, refining, chemical manufacturing, and power generation facilities. Houston and Beaumont refineries consolidate coating procurement under integrated inspection-warranty contracts.
- Municipal:City and county water utilities, wastewater authorities, and public works departments. Chicago and Cleveland water departments specify 20-year coating warranties for reservoir rehabilitation.
- Commercial:Fuel retailers, airports, and private storage terminals. Ontario convenience store chains upgrade underground storage to meet provincial spill contingency rules.
- Residential:Home heating oil and propane storage. Northeast US heating oil tank replacement cycles drive demand for corrosion-resistant steel and fiberglass alternatives.
Industrial end users absorb the bulk of high-performance system deployment; municipal utilities are expanding most quickly on aging infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Texas and Louisiana fabrication yards, while consumption spreads across Great Lakes utilities and California refineries. This geographic split shapes supply chain logistics and specification standards. The analysis covers three countries with distinct regulatory frameworks and industrial clustering patterns.
United States
Texas petrochemical corridor expansions drive immersion-grade lining specifications for crude and renewable diesel storage. EPA Underground Storage Tank regulations and API 653 inspection standards mandate accelerated recoating cycles across Gulf Coast facilities. Houston and Beaumont refineries consolidate procurement under integrated inspection-warranty contracts with captive engineering capabilities.
Canada
Alberta oilfield chemical injection systems specify fiberglass-reinforced vessels for produced water handling. Canadian Environmental Protection Act provisions and provincial spill contingency rules in Ontario and Alberta extend compliance obligations comparable to US standards. Saskatchewan grain terminals drive demand for polyurethane-coated steel in liquid fertilizer containment applications.
Mexico
Pemex downstream infrastructure modernization and private terminal expansions create specification windows for corrosion-resistant storage. Energy regulatory reforms under CRE oversight mandate integrity assessments for aged tank farms. Altamira and Tampico port industrial zones attract coating applicators serving petrochemical import and blending operations.
North America Tank Protection Market Competitive Landscape
Top-tier vendors anchor specification-intensive industrial accounts, while regional applicators serve municipal and commercial end users through distributor relationships. The vendor base stratifies across integrated coating manufacturers, specialized lining applicators, and cathodic protection engineering firms. Three archetypes dominate: diversified chemical conglomerates with captive resin production, independent coating specialists with NSF-certified potable water formulations, and integrated service providers combining application with remote monitoring platforms. Competitive moves concentrate on multi-site master service agreements and predictive analytics integration beyond initial coating deployment.
Among diversified chemical conglomerates, PPG Industries and BASF SE exemplify scale-driven positions spanning industrial end users with broad formulation portfolios. Sherwin-Williams Company occupies a position within the distribution-intensive archetype, sustaining channel density through networks serving remote oilfield operations. AkzoNobel N.V. represents the specialty-formulation tier, with marine-grade expertise adapted for aggressive chemical environments. These three anchors illustrate how competitive positioning fragments across coating chemistry depth, channel reach, and application service integration rather than consolidating around单一 dominance vectors.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams Company |
| AkzoNobel N.V. |
| BASF SE |
| RPM International Inc. |
| Rockwool International A/S |
| Owens Corning |
| Saint-Gobain |
| Jotun A/S |
| Others |
Value Network & Pricing Analysis
Epoxy resin spot price volatility cascades through North American tank protection supply chains, compressing applicator margins and forcing tiered pricing stratification across commodity, performance-grade, and specialty coating categories.
Pricing Analysis
Margin tightening in commodity epoxy tiers reflects feedstock benzene and propylene cost swings, while premium polyurethane and vinyl ester formulations command 40-60% markups through NSF potable water certification and API 653 compliance bundling. Municipal utilities in Michigan and Ohio exhibit acute price sensitivity on reservoir rehabilitation bids, whereas Permian Basin midstream operators prioritize outage reduction over unit coating costs. Three-tier pricing separates specification-intensive industrial accounts from distributor-served commercial fuel retailers and price-driven agricultural tank fabricators.
Supply Chain Analysis
Freight cost escalation from Houston and Beaumont coating manufacturing hubs to Great Lakes municipal markets adds 8-12% to delivered project costs, privileging regional applicators with captive blending capacity. Raw material supply concentrates in Texas and Louisiana petrochemical corridors, with isocyanate and epoxy resin production anchored to Gulf Coast crackers. Distribution runs through Sherwin-Williams and PPG distributor networks serving remote Alberta oilfields and Saskatchewan agricultural terminals. Single-source vulnerability in specialty glass-flake vinyl ester feedstocks creates specification risk for sulfuric acid storage contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurea spray technology is displacing conventional epoxy curing cycles, compressing tank outage windows from weeks to days and rewriting maintenance contracting economics across North American industrial facilities.
For Market Incumbents: Cement specification control through captive NACE-certified inspection capabilities and multi-site master service agreements spanning API 653 compliance cycles. Backward integration into specialty resin production defends margin position against epoxy feedstock volatility, while predictive analytics platform deployment creates recurring revenue beyond initial coating application.
For New Entrants and Emerging Players: Begin with NSF-certified potable water lining formulations targeting Ohio and Michigan municipal reservoir replacement cycles, where century-old cast iron infrastructure obsolescence opens specification windows. Digital twin integration partnerships with regional engineering firms provide differentiated entry angles against established distributor networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated coating-applicator hybrids in Alberta and Saskatchewan, where oilfield chemical injection demand and agricultural liquid fertilizer storage expansion converge. Watch PFAS regulatory clarity in Washington and Maine as inflection signal for legacy PTFE-enhanced lining reformulation investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive isocyanate supply shields PPG and BASF from Gulf Coast feedstock volatility. |
| Multi-Site Master Service Agreements | Permian Basin operators consolidate procurement under integrated inspection-warranty contracts. |
| Digital Twin Platform Deployment | Remote corrosion monitoring creates recurring revenue streams beyond initial coating application. |
| NSF Potable Water Certification Investment | Great Lakes utilities specify certified epoxy linings for municipal reservoir rehabilitation. |
| Polyurea Spray Technology Scale-Up | Rapid-cure elastomeric systems reduce tank outage windows from weeks to days. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews spanning coating plant managers, municipal procurement officers at Great Lakes water utilities, NACE-certified inspection contractors, and midstream terminal engineering directors. Bottom-up project pipeline tracking across Texas TCEQ permitting databases and top-down resin consumption analysis from American Chemistry Council reports enabled triangulation. EPA Underground Storage Tank compliance filings and API 653 inspection interval data provided demand-side validation.
Data-stream reconciliation across protection type, substrate material, and end-use application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical coating consumption patterns, regulatory mandate phase-in schedules, and infrastructure replacement cycle timing. Modeled inputs included IRA biofuels tax credit acceleration effects on renewable diesel tank farm construction and PFAS restriction timeline uncertainty across state-level jurisdictions.
Underlying measurement precision varies by segment; passive coating applications carry tighter precision than active cathodic protection systems given standardized material specifications. Forecasts reflect assumptions on regulatory enforcement consistency and feedstock price normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Threat Lifecycle Services Market