
 Middle East and Africa Robotic Vacuum Cleaner Market | 2026-2036
Middle East and Africa Robotic Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Robotic Vacuum Cleaner Market Foresight
Subscription-based firmware and mapping software is realigning how robotic vacuum capabilities get monetized in the Middle East and Africa. Ecovacs Robotics leverages its Deebot ecosystem to sustain recurring revenue through premium navigation feature unlocks. iRobot Corporation anchors its regional position through Roomba's established brand recognition and localized customer support infrastructure. Samsung Electronics differentiates by integrating vacuum robots with its broader SmartThings home automation platform.
A robotic vacuum cleaner is an autonomous mobile robot equipped with suction mechanisms, rotating brushes, and sensor arrays for obstacle detection and path planning, typically operating on lithium-ion battery packs with runtimes between 90 and 180 minutes. These devices serve residential and commercial environments by reducing manual labor for floor maintenance while capturing particulate matter through HEPA-grade filtration systems. Robotic floor cleaners occupy the dominant volume position due to lower entry pricing and established consumer familiarity across Middle Eastern retail channels. Lidar navigation systems command premium positioning as Gulf consumers prioritize precise mapping for large villa layouts. Online retail channels are expanding fastest, though brick-and-mortar stores still control significant transaction volume through hands-on demonstration requirements.
South Africa's National Regulator for Compulsory Specifications enforces electrical safety standards that shape import compliance costs for robotic vacuum manufacturers entering the market. The UAE's Emirates Authority for Standardization and Metrology and Saudi Arabia's Saudi Standards, Metrology and Quality Organization both mandate energy efficiency labeling and electromagnetic compatibility certification, creating a dual-track compliance environment for regional suppliers. Stakeholders must monitor how Gulf standardization convergence between these frameworks affects product homologation timelines and market access strategies.
Market Dynamics
Subscription-based firmware monetization is restructuring revenue models across the Middle East and Africa robotic vacuum cleaner market, shifting manufacturer economics from one-time hardware sales toward recurring software revenue streams.
Growth Catalysts
- Smart home integration mandates:Gulf Cooperation Council luxury residential developments now specify automated cleaning systems as standard amenities, embedding robotic vacuums into property value propositions.
- Lidar navigation adoption:Premium villa layouts across the United Arab Emirates are driving demand for precise room-mapping capabilities that optimize cleaning paths across expansive floorplans.
- Energy efficiency labeling requirements:Saudi Standards, Metrology and Quality Organization directives are accelerating product refresh cycles as older models lose market access.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers exposes regional distributors to shipping cost volatility and extended lead times.
- Dual-track certification burden:Divergent Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization testing protocols force redundant homologation expenditures.
- Manual cleaning labor substitution:Low-cost domestic worker availability in Gulf states dampens household willingness to pay automation premiums.
Strategic Opportunities
- South African commercial hospitality:Hotel chains in Cape Town and Johannesburg are piloting fleet deployments for standardized room turnover protocols.
- Online retail channel expansion:E-commerce platforms are reducing demonstration-dependent purchase friction through augmented reality visualization tools.
- HEPA filtration convergence:Integration with indoor air quality monitoring systems is opening specification pathways for health-conscious buyers.
Industry Challenges
- Localization engineering gaps:Scarce embedded systems talent in the region delays firmware adaptation for Arabic-language voice control interfaces.
- Warranty service infrastructure:Sparse authorized repair networks across secondary Saudi Arabian and Egyptian cities elevate customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Robotic Vacuum Cleaner Market |
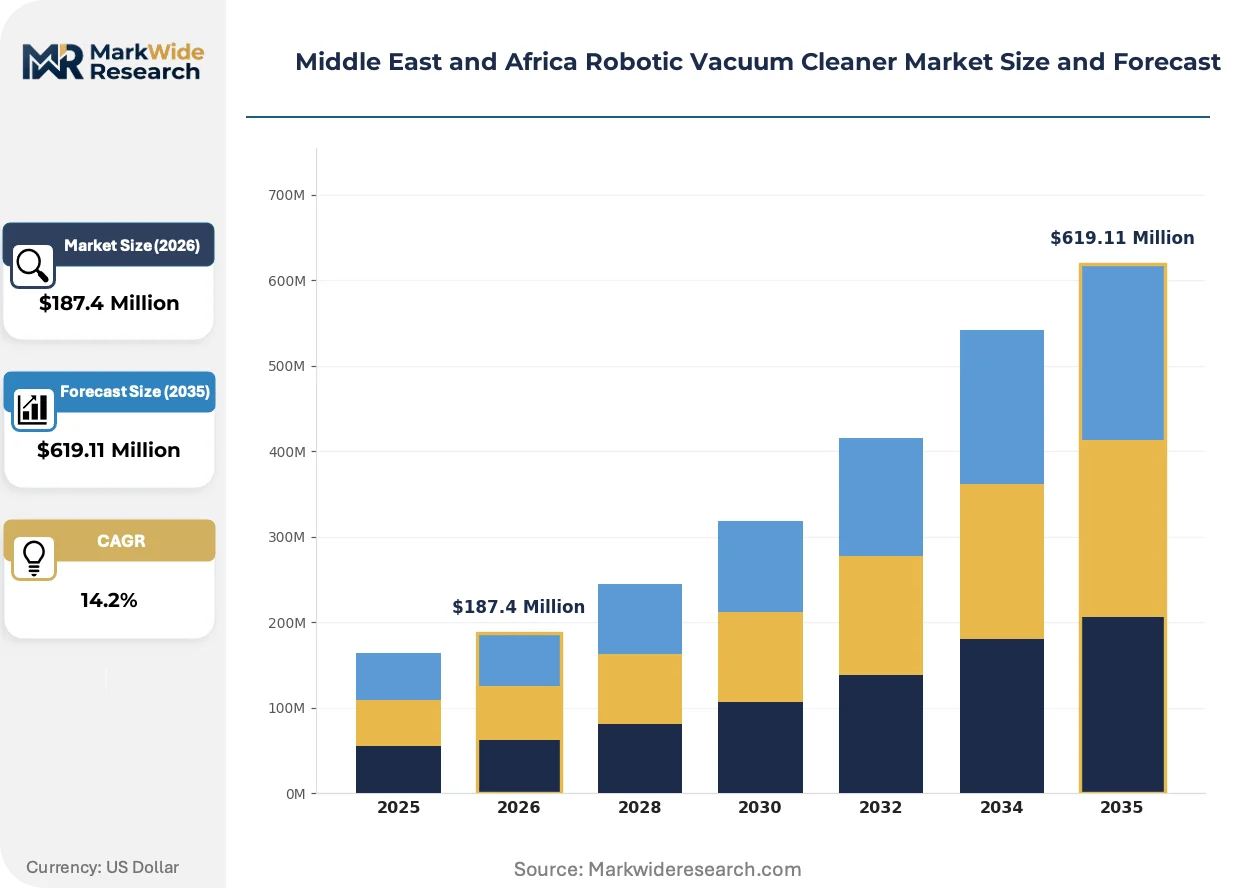
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Floor Cleaners, All-in-One Cleaners, Smart Cleaners, Budget Models Technology: Lidar Navigation, Visual Navigation, Ultrasonic Sensors, Gyroscope End User: Households, Commercial Spaces, Educational Institutions, Healthcare Facilities Sales Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Distributors |
| Companies Covered | Ecovacs Robotics, Roborock, iRobot Corporation, Panasonic Corporation, Neato Robotics, Xiaomi Corporation, Dyson Ltd., SharkNinja Operating LLC, Samsung Electronics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Robotic Vacuum Cleaner Market Shifts & Advancements
Navigation hardware architectures are fragmenting into specialized components that manufacturers can license, assemble, or bypass entirely depending on price-tier targeting.
Lidar sensor arrays is modularizing across the supplier base, allowing mid-tier brands to purchase off-the-shelf simultaneous localization and mapping modules rather than developing proprietary optical systems. Saudi Arabian retail channels are absorbing these subsystems fastest among Gulf markets. The technology is modularizing competitive barriers, compressing the premium positioning window for integrated navigation specialists.
Emirates Authority for Standardization and Metrology electromagnetic compatibility certification timelines are lengthening as testing laboratory capacity fails to match import application volumes. Manufacturers are front-loading documentation preparation to secure seasonal retail placement. Saudi Arabia's parallel Saudi Standards, Metrology and Quality Organization pathway is capturing overflow submissions from frustrated UAE applicants.
After-sales service unbundling is separating hardware warranties from software support contracts across Dubai's electronics retail sector. Premium buyers now encounter annual mapping update fees at point-of-sale. Egyptian and Nigerian distributors are replicating this bifurcation to recover margin on entry-priced units.
Middle East and Africa Robotic Vacuum Cleaner Market Segmentation
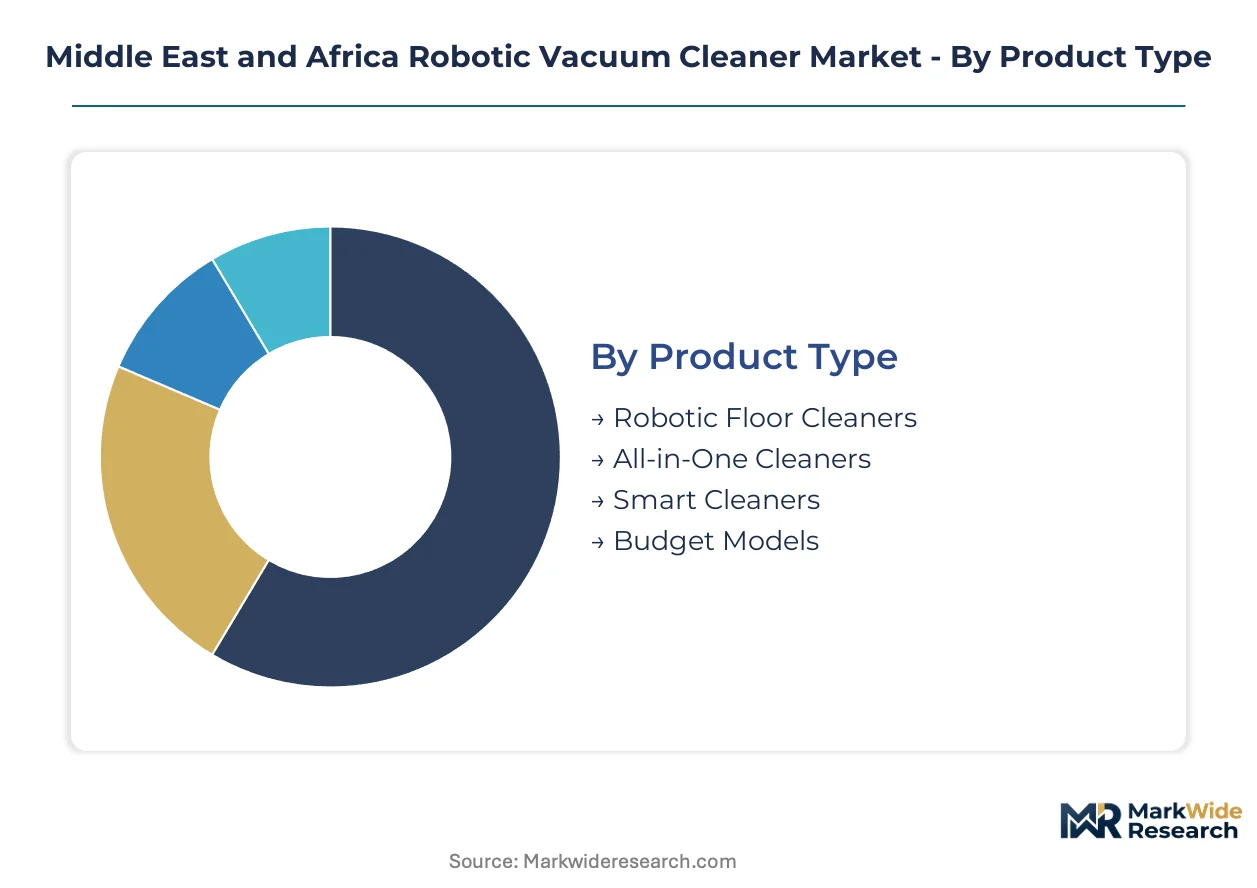
Segmentation in the Middle East and Africa robotic vacuum cleaner market reveals how supply-side capabilities align with divergent buyer requirements across Gulf luxury developments and South African commercial hospitality. Manufacturers configure product portfolios around navigation precision thresholds, certification compliance costs, and channel access constraints rather than uniform global specifications.
Product Type:
Supply concentration among East Asian contract manufacturers favors volume production of established form factors over experimental configurations, locking regional distributors into procurement patterns shaped by Shenzhen and Dongguan assembly capacity.
- Robotic Floor Cleaners:These units deploy suction mechanisms with rotating brush arrays and lithium-ion power systems optimized for hard surface and low-pile carpet maintenance. Demand clusters in United Arab Emirates apartment complexes where Dubai property developers specify automated cleaning as standard amenities. Saudi Arabian distributors report these units constitute the volume foundation of retail assortments due to entry price accessibility.
- All-in-One Cleaners:Integrated mopping and vacuum subsystems operate through dual-chamber water and debris collection with automated pad washing docks. Cape Town hotel chains pilot fleet deployments for standardized room turnover protocols, though water tank capacity limits constrain runtime in large villa layouts across Emirates luxury developments.
- Smart Cleaners:WiFi-connected units with mobile application control and voice assistant integration dominate online retail channels in Nigeria and Egypt where smartphone penetration drives connected home expectations.
- Budget Models:Gyroscope-based navigation with simplified obstacle detection serves price-sensitive segments in secondary Saudi Arabian and Egyptian cities where warranty service infrastructure remains sparse.
Today's leader: Robotic Floor Cleaners. Tomorrow's challenger: All-in-One Cleaners.
Technology:
Cost tier stratification in navigation hardware determines which buyer segments manufacturers can access profitably, with premium optical systems carrying bill-of-materials premiums that compress distributor margins at mid-market price points.
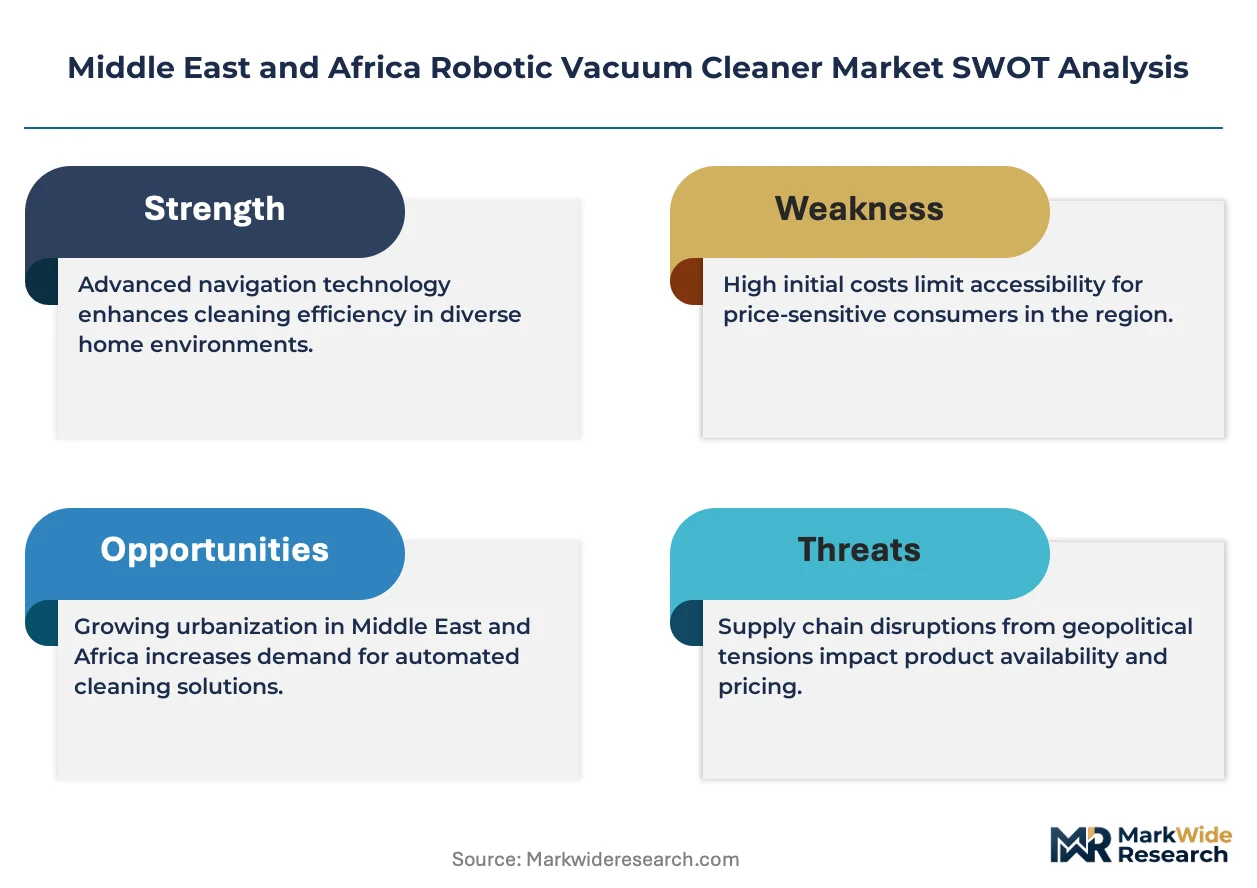
- Lidar Navigation:Rotating laser arrays generate centimeter-accurate room maps through simultaneous localization and mapping algorithms. United Arab Emirates villa owners prioritize this capability for expansive floorplan optimization, though Emirates Authority for Standardization and Metrology electromagnetic compatibility testing extends import timelines. Saudi Arabian retail channels absorb these subsystems fastest among Gulf markets as luxury residential specifications harden.
- Visual Navigation:Camera-based simultaneous localization and mapping leverages onboard image processing for obstacle recognition and path refinement. Johannesburg commercial cleaning contractors favor these units for dynamic furniture rearrangement in hospitality environments where floor layouts shift between events.
- Ultrasonic Sensors:Time-of-flight distance measurement enables basic obstacle avoidance without mapping persistence, serving price-constrained segments in Nigerian and Kenyan urban markets.
- Gyroscope:Inertial measurement units provide dead-reckoning navigation with systematic coverage patterns but accumulated positioning drift, dominating entry-tier shipments where distributor margin recovery depends on software subscription attachments.
Current volume anchor: Gyroscope. Steepest expansion trajectory: Lidar Navigation.
End User:
Application-specific durability requirements and procurement authority structures fragment demand patterns, with commercial buyers prioritizing fleet management capabilities and standardized replacement part availability over residential feature sophistication.
- Households:Individual purchasers operating units in residential environments with 90-180 minute runtime expectations and HEPA filtration for particulate capture. Dubai's luxury residential developments embed these devices into property value propositions as smart home integration becomes standard.
- Commercial Spaces:Hotel chains, retail floors, and office complexes in Cape Town and Johannesburg deploy coordinated fleets with centralized scheduling and maintenance protocols.
- Educational Institutions:University campuses and private schools in Saudi Arabia and UAE evaluate robotic vacuums for after-hours cleaning automation to reduce facilities staffing costs.
- Healthcare Facilities:Hospitals and clinics in South Africa and Gulf states specify HEPA-grade filtration with antimicrobial surface treatments for infection control compliance.
Revenue concentration today: Households. Procurement momentum building: Commercial Spaces.
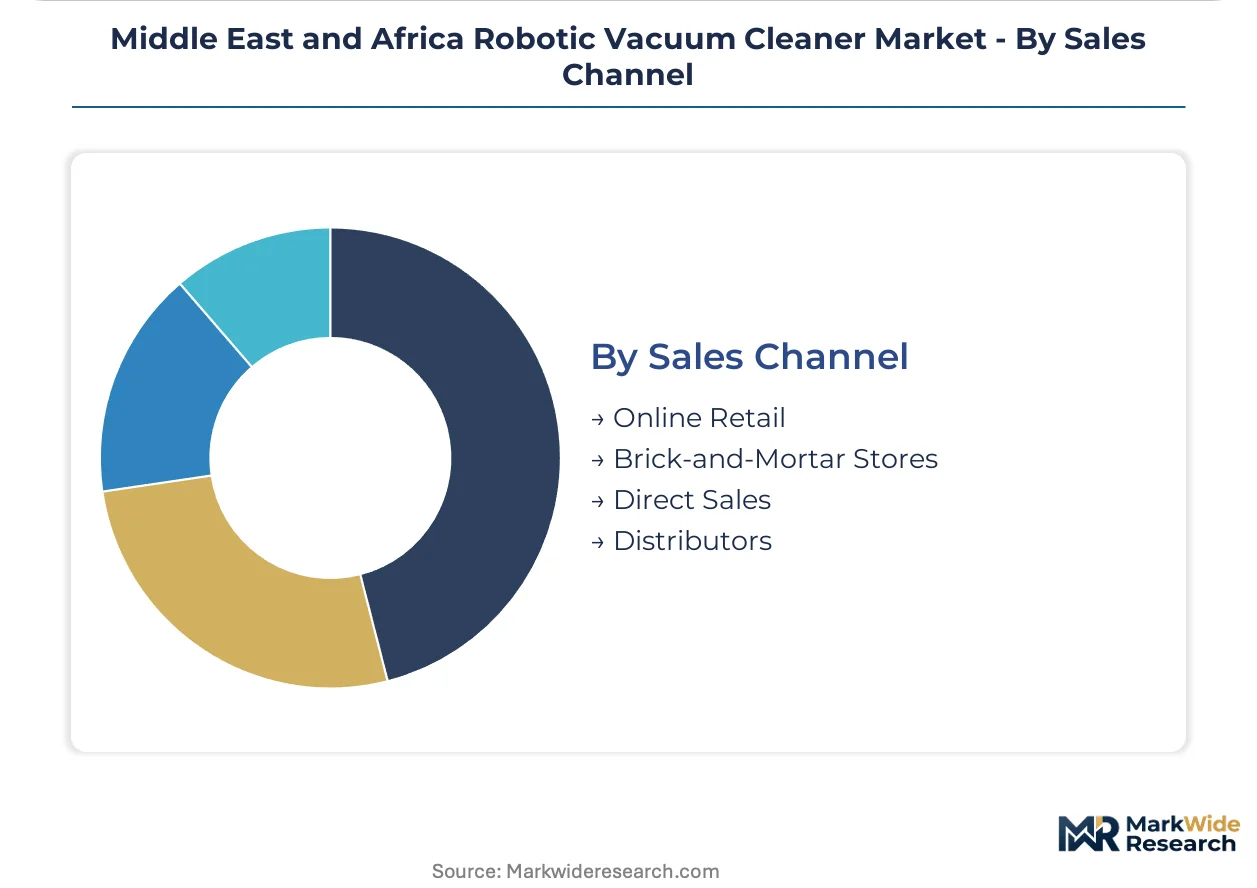
Sales Channel:
Customer type heterogeneity across the region—tech-forward urban professionals versus demonstration-dependent traditional buyers—forces parallel channel strategies that duplicate inventory and marketing expenditures.
- Online Retail:E-commerce platforms including regional marketplaces and global direct-to-consumer sites reduce purchase friction through augmented reality visualization tools. Nigerian and Egyptian distributors replicate warranty unbundling models pioneered in Dubai electronics retail to recover margin on entry-priced units.
- Brick-and-Mortar Stores:Physical demonstration requirements sustain transaction volume in Saudi Arabian and UAE electronics retail where hands-on navigation testing influences purchase decisions for premium lidar-equipped models.
- Direct Sales:Manufacturer-owned channels bypass distributor markups for B2B fleet procurement by hospitality and healthcare institutional buyers.
- Distributors:Authorized regional partners manage import compliance, warranty service infrastructure, and localized firmware adaptation for Arabic-language voice control interfaces.
Fastest channel expansion: Online Retail. Persistent volume control: Brick-and-Mortar Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's hospitality sector pilots fleet deployments while the United Arab Emirates embeds robotic vacuums into luxury property specifications, revealing divergent demand maturities across the region.
United Arab Emirates
Dubai's luxury residential developments specify automated cleaning systems as standard amenities, embedding hardware into property value propositions. The Emirates Authority for Standardization and Metrology mandates electromagnetic compatibility certification with timelines lengthening as testing laboratory capacity fails to match import application volumes. Abu Dhabi's hospitality sector concentrates procurement authority for coordinated fleet deployments across hotel chains.
Saudi Arabia
The Saudi Standards, Metrology and Quality Organization enforces energy efficiency labeling that accelerates product refresh cycles as older models lose market access. Riyadh's retail channels absorb lidar navigation subsystems fastest among Gulf markets as luxury residential specifications harden. Jeddah's electronics retail sustains brick-and-mortar transaction volume through hands-on demonstration requirements for premium navigation testing.
South Africa
Cape Town and Johannesburg hotel chains pilot fleet deployments for standardized room turnover protocols, shifting procurement toward commercial-grade durability requirements. The National Regulator for Compulsory Specifications enforces electrical safety standards that reshape import compliance costs and product certification pathways. Johannesburg commercial cleaning contractors favor camera-based navigation for dynamic furniture rearrangement in hospitality environments.
Egypt
Smartphone penetration drives connected home expectations for WiFi-enabled units with mobile application control across Cairo and Alexandria urban markets. The country's national standards body applies electromagnetic compatibility and electrical safety frameworks that extend homologation timelines for imported electronics. Egyptian distributors replicate warranty unbundling models pioneered in Dubai electronics retail to recover margin on entry-priced units.
Nigeria
Price-sensitive segments in Lagos and Abuja urban markets favor gyroscope-based navigation with simplified obstacle detection where distributor margin recovery depends on software subscription attachments. The country's consumer protection regulator maintains electrical product safety standards that shape import documentation requirements. Nigerian e-commerce platforms reduce purchase friction through augmented reality visualization tools for demonstration-dependent categories.
Middle East and Africa Robotic Vacuum Cleaner Market Competitive Landscape
Top-tier vendors anchor premium positioning through integrated navigation ecosystems, while mid-tier specialists exploit modular lidar subsystems to compress development cycles. The vendor base stratifies across three archetypes: integrated platform owners controlling firmware monetization, component assemblers leveraging Shenzhen supply chains, and subscription-first entrants unbundling hardware from software support. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as manufacturers navigate dual-track UAE-Saudi certification burdens.
Within the integrated platform tier, Ecovacs Robotics and iRobot Corporation exemplify archetypes diverging on revenue model architecture. Ecovacs anchors recurring revenue through firmware ecosystem monetization, while iRobot occupies a position grounded in established brand recognition and localized customer support infrastructure. Samsung Electronics sits within the home automation convergence archetype, leveraging SmartThings platform integration to differentiate vacuum robot positioning. These three represent divergent strategic bets on whether hardware margins, software subscriptions, or ecosystem lock-in will capture value in Gulf luxury residential and South African commercial hospitality procurement.
| Leading Market Players |
|---|
| Ecovacs Robotics |
| Roborock |
| iRobot Corporation |
| Panasonic Corporation |
| Neato Robotics |
| Xiaomi Corporation |
| Dyson Ltd. |
| SharkNinja Operating LLC |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors across Dubai's Deira electronics souks anchor pricing discipline through consolidated procurement from Shenzhen contract manufacturers, compressing margin recovery windows for entrants lacking scale-based supplier leverage. Their ownership structure prioritizes inventory velocity over premium positioning, forcing branded manufacturers to unbundle software subscriptions at point-of-sale to preserve profitability.
Pricing Analysis
Capacity additions in Dongguan assembly corridors are reshaping price floors for gyroscope-based entry units, pressuring distributor margins across Nigerian and Egyptian urban markets. Three-tier pricing structure across premium lidar, standard visual navigation, and economy gyroscope levels separates Emirates villa buyers from Saudi apartment purchasers from Kenyan price-sensitive segments. Cost compression in the budget tier intensifies because East Asian contract manufacturers compete for volume slots. Commercial hospitality buyers in Cape Town show least price sensitivity due to fleet durability requirements, while Lagos residential purchasers demand entry pricing with software subscription attachments.
Supply Chain Analysis
Returns and refurbishment flows from Dubai's electronics retail sector feed secondary channels across Riyadh and Jeddah, extending product lifecycles and compressing new-unit pricing power. Manufacturing concentrates in China, South Korea, and Vietnam, with lithium-ion cells drawing from East Asian cathode suppliers. Supply chain risk centers on single-source vulnerability for lidar sensor modules from specialized optical component vendors. Distribution runs through authorized regional partners managing Emirates Authority for Standardization and Metrology compliance, Saudi Standards, Metrology and Quality Organization certification, and sparse warranty infrastructure across secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between UAE certification bottlenecks and Saudi Arabia's parallel Saudi Standards, Metrology and Quality Organization pathway creates cost differentials for manufacturers front-loading documentation to secure seasonal retail placement.
For Market Incumbents: Deepen firmware ecosystem lock-in through Arabic-language voice control localization, defending against modular lidar subsystem entrants eroding premium navigation positioning. Anchor supplier relationships with Shenzhen contract manufacturers through volume commitments that block mid-tier competitors from assembly slot access. Certification investment in dual-track UAE-Saudi compliance creates switching costs for hospitality fleet buyers. For New Entrants and Emerging Players: Secondary Saudi Arabian cities present underserved buyer archetypes where sparse authorized repair networks elevate customer acquisition costs for incumbents. Cape Town commercial cleaning contractors offer penetrable white-space targeting dynamic furniture rearrangement requirements absent from residential specifications. Direct-to-hospitality fleet procurement bypasses distributor markups and demonstration-dependent retail friction. For Investors and Strategic Acquirers: Valuations sit cheapest among component assemblers leveraging Shenzhen supply chains without proprietary firmware monetization capabilities. Long-term viability across the projection horizon favors integrated platform owners controlling recurring revenue streams over hardware-margin-dependent specialists. Monitor convergence between Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization frameworks as inflection indicator for homologation cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Arabic Firmware Localization | Unlocks voice control penetration across UAE and Saudi residential developments where smart home integration is standard. |
| Dual-Track Certification Investment | Secures parallel UAE-Saudi market access before testing laboratory capacity constraints lengthen import timelines. |
| Commercial Fleet Management Platform | Addresses Cape Town and Johannesburg hotel chain requirements for standardized room turnover protocols. |
| Lidar Sensor Module Licensing | Enables mid-tier brands to compress development cycles as Saudi retail channels absorb subsystems fastest among Gulf markets. |
| Warranty Service Network Expansion | Reduces customer acquisition costs in secondary Saudi Arabian and Egyptian cities where authorized repair presence remains sparse. |
Research Methodology
Bottom-up residential and commercial demand modeling reconciled against top-down East Asian manufacturing output tracking forms the analytical core of this study. Primary interviews with robotics procurement managers at Dubai property developers, hospitality fleet operators in Cape Town, Saudi electronics retail channel heads, and Egyptian distributor principals combined with secondary validation from customs import records, Emirates Authority for Standardization and Metrology certification filings, and Saudi Standards, Metrology and Quality Organization energy efficiency registrations.
Input-output matrices map lithium-ion cell supply from East Asian manufacturers through Shenzhen assembly corridors to regional distributor inventories across the analysis window. Segmentation dimensions include navigation technology tier, product type configuration, end-use application, and sales channel structure. CAGRs derive from installed base growth rates, replacement cycle compression from energy efficiency mandates, and software subscription attachment trajectories. Forecast inputs incorporate hospitality fleet pilot expansion timelines and smart home integration specification hardening in Gulf luxury residential developments.
Underlying measurement precision varies by segment; lidar navigation and commercial end-use carry tighter precision than gyroscope-based entry tiers where distributor reporting fragmentation elevates uncertainty. Forecasts reflect documented assumptions regarding certification timeline convergence and battery supply chain stability. Practitioners should monitor Emirates Authority for Standardization and Metrology testing laboratory capacity expansion and Saudi Standards, Metrology and Quality Organization directive harmonization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Lunch Box Market
Household Items
Smart Shower Market
Household Items
Scouring Pads Market
Household Items
Global Tableware Market
Household Items
Toilet Brush Market
Household Items
Kuwait Gas Hobs Market
Household Items
Dishwasher Tablets Market
Household Items
Smart Pool Skimmer Market
Household Items
Portable Humidifiers Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Electric Brooms Market
Household Items
Trash Can Market
Household Items
Folded Tissues Market
Household Items
Smart Air Purifier Market