
 Global Tableware Market | 2026-2036
Global Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tableware Market Outlook
Multi-source ceramic procurement is broadening as brands reduce dependence on single-origin supply from China's Fujian province. Arc International leverages vertical integration across its French and UAE glassmaking facilities to sustain margin control. Villeroy & Boch AG anchors premium porcelain demand through heritage positioning in European hospitality. Meyer Corporation Group competes on stainless steel flatware scale across North American big-box retail channels.
Tableware encompasses vessels, utensils, and serving implements fabricated from vitrified ceramics, soda-lime or borosilicate glass, food-grade polymers, and austenitic stainless steels, with firing temperatures for porcelain exceeding 1,200°C to achieve full vitrification and mechanical durability. Dinnerware and drinkware in ceramic and glass command the dominant value share, while stainless steel flatware captures volume leadership in commercial foodservice procurement. Luxury price tiers concentrate margin pools in artisan-crafted and designer-licensed collections, whereas mid-range segments face compression from private-label competition and direct-to-consumer ceramic startups.
EU ECHA REACH restrictions on lead and cadmium in ceramic glazes reshape formulation requirements for exporters accessing European markets. FDA's compliance standards for food-contact surfaces govern US import acceptance, while China's GB standards for domestic ceramic safety create dual-certification burdens for cross-border suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification schemes that will determine future sourcing eligibility and premium positioning.
Market Dynamics
EU ECHA REACH restrictions on lead and cadmium in ceramic glazes are forcing reformulation across export-oriented manufacturers, while China's Fujian province concentration creates vulnerability for brands seeking supply diversification.
Growth Catalysts
- EU Green Deal packaging directives:Bio-based material substitution mandates accelerate demand for compostable tableware across European foodservice procurement.
- Luxury hospitality expansion:Southeast Asian resort developments drive artisan-crafted ceramic dinnerware procurement for premium dining experiences.
- FDA food-contact compliance:Stringent US import standards for vitrified ceramics filter out subscale suppliers, consolidating volume with certified exporters.
Market Restraints
- Energy cost volatility:Natural gas price swings directly impact soda-lime glass and porcelain firing economics, compressing margins for energy-intensive producers.
- Single-origin supply risk:China's Fujian province dominance in vitrified ceramic exports exposes brands to concentrated geopolitical and logistics disruption.
- Technical substitution ceiling:Bio-based polymers face heat-resistance limitations above 120°C, restricting deployment in high-temperature foodservice applications.
Strategic Opportunities
- Underpenetrated Indian foodservice:Organized restaurant chains in Mumbai and Bangalore present untapped demand for standardized commercial-grade dinnerware.
- Extended producer responsibility frameworks:France's AGEC law and similar EU national implementations create premium positioning for closed-loop recyclable tableware collections.
- Direct-to-consumer channel emergence:Ceramic startups bypass traditional retail markups through owned e-commerce, capturing margin previously allocated to distributors.
Industry Challenges
- Glaze chemist talent scarcity:Formulation expertise for lead-free, cadmium-free vitrified finishes concentrates with aging specialists in Stoke-on-Trent and Limoges.
- Dual-certification burden:Cross-border suppliers must simultaneously satisfy China's GB standards and FDA compliance, extending product development timelines.
- Legacy kiln infrastructure:Converting traditional tunnel kilns to hydrogen-compatible firing systems requires capital outlays exceeding mid-tier manufacturer balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tableware Market |
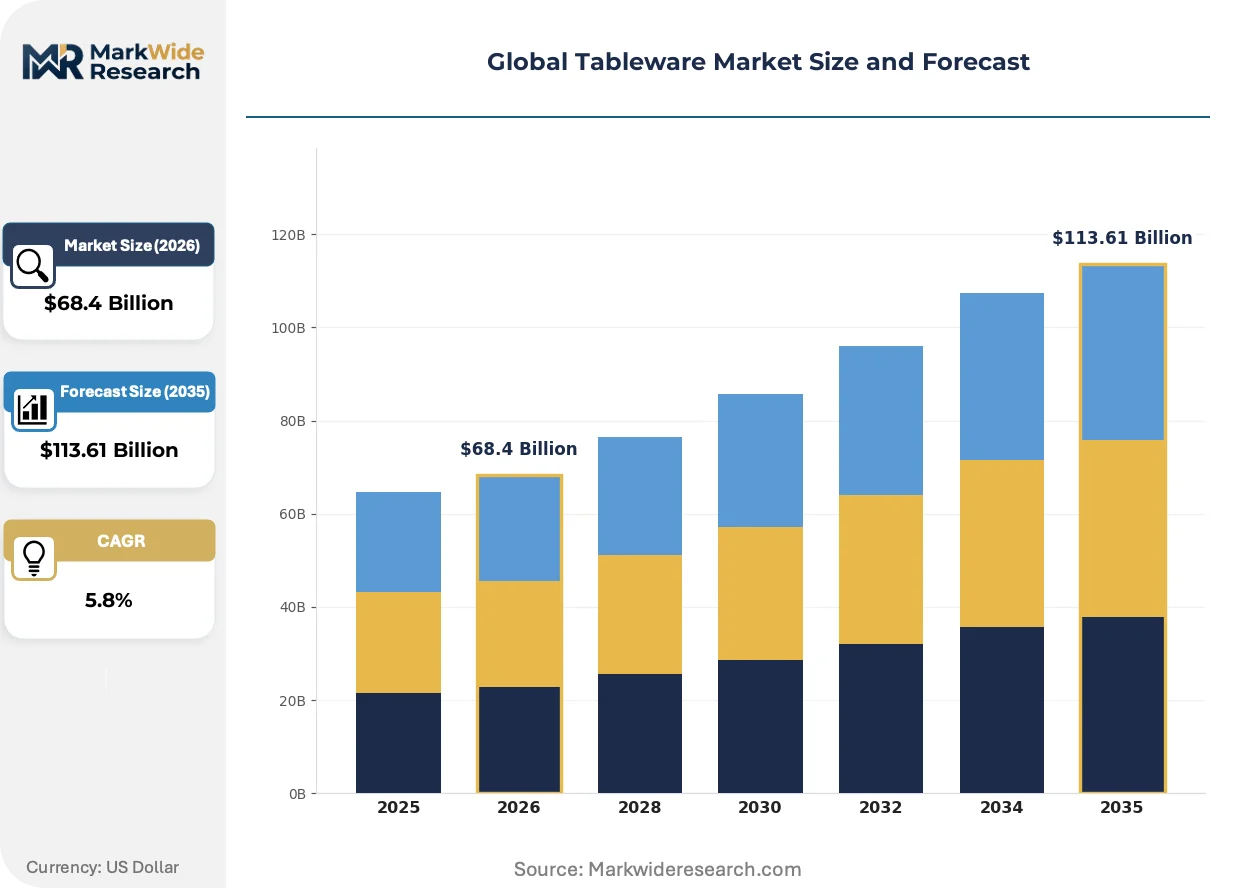
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Serveware, Flatware, Drinkware Material: Glass, Ceramic, Plastic, Stainless Steel Price Tier: Luxury, Mid-Range, Affordable, Budget End User: Households, Restaurants, Hotels, Catering Services |
| Companies Covered | Corelle Brands, Lenox Corporation, Arc International, Libbey, Bormioli Rocco, Villeroy & Boch AG, Rosenthal GmbH, Noritake Co., Ltd., Meyer Corporation Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tableware Market Strategic Shifts
Bio-based material science, regulatory chemistry reformulation, and channel disintermediation are converging to reshape competitive positioning across ceramic, glass, and polymer tableware segments.
Advanced bio-composites incorporating agricultural waste fibers are absorbing market share in single-use and limited-use foodservice applications. European contract caterers and quick-service chains are adopting these materials at accelerating pace to satisfy EU Green Deal procurement mandates. The technology is absorbing volume previously captured by conventional polystyrene and polypropylene disposables, compressing pricing power in commoditized polymer segments.
EU ECHA REACH Annex XVII restrictions on heavy metals in ceramic glazes are mandating systematic reformulation across export-oriented manufacturers. Industrial consequence includes accelerated R&D spend on zirconium-silicate and rare-earth alternative opacifiers to maintain aesthetic performance. Vitrified ceramic exporters to Germany, France, and Benelux markets are responding with dedicated compliance laboratories and third-party certification partnerships.
Buyer concentration among multinational hospitality groups is consolidating procurement authority previously dispersed across property-level purchasing. Third-party group purchasing organizations and centralized sourcing platforms are displacing traditional wholesale-distributor relationships in North American and European hotel chains. This pattern is most visible in the United Arab Emirates and Saudi Arabia, where sovereign wealth-backed hospitality developments negotiate directly with Arc International and Villeroy & Boch AG for estate-wide supply agreements.
Global Tableware Market Segmentation
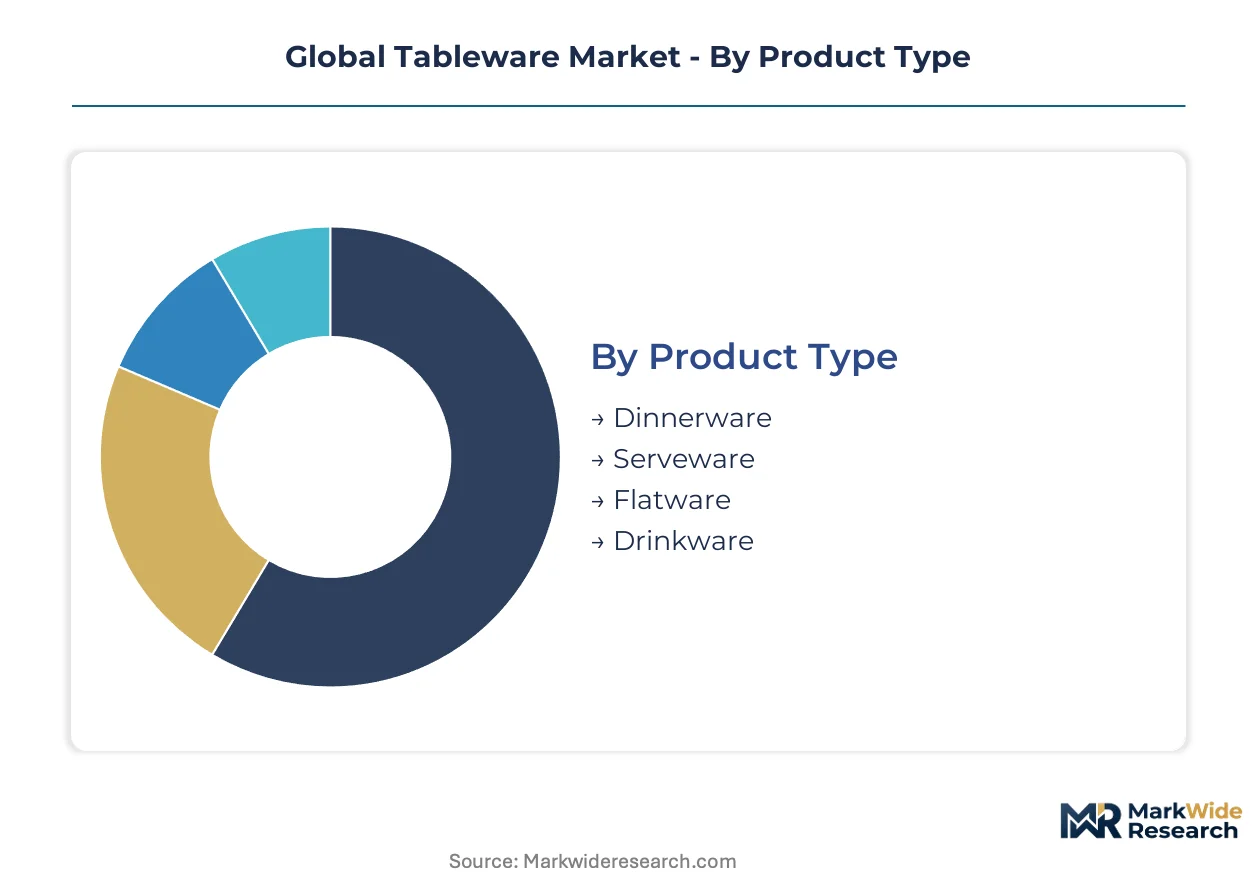
Tableware procurement decisions diverge sharply across material specifications and end-use applications, with certification requirements and firing economics determining supplier eligibility. Understanding segment boundaries clarifies where margin pools concentrate versus where scale advantages dominate.
Product Type:
FDA food-contact compliance applies unevenly across product categories, with vitrified dinnerware facing the most stringent heavy metal testing while flatware encounters surface-finish standards.
- Dinnerware:Vitrified ceramics and porcelain plates, bowls, and serving pieces fired above 1,200°C achieve full density and mechanical durability. Demand concentrates in Southeast Asian luxury hospitality developments in Thailand and Vietnam, where resort developers specify artisan-crafted collections for premium positioning.
- Flatware:Austenitic stainless steel utensils in 18/10 and 18/0 grades balance corrosion resistance against nickel cost volatility. North American big-box retail channels in the United States and Canada drive volume procurement, with Meyer Corporation Group leveraging scale economics against private-label competition.
- Serveware:Large-format platters, tureens, and buffet equipment spanning ceramic, glass, and metal substrates.
- Drinkware:Soda-lime and borosilicate glass vessels for beverage service across hospitality and household channels.
Leading the category by volume: Flatware. Growing fastest: Dinnerware.
Material:
EU ECHA REACH Annex XVII restrictions on lead and cadmium in ceramic glazes impose dual-certification burdens on cross-border suppliers, while bio-based polymer substitution accelerates under EU Green Deal procurement mandates.
- Ceramic:Fully vitrified porcelain and stoneware requiring lead-free, cadmium-free glaze reformulation for European market access. Stoke-on-Trent in the United Kingdom and Limoges in France retain concentrated formulation expertise for compliant finishes.
- Glass:Soda-lime and borosilicate compositions dominate drinkware and serveware, with Arc International's French and UAE facilities sustaining margin control through captive melting capacity. Natural gas price volatility directly impacts firing economics for energy-intensive production.
- Stainless Steel:Austenitic grades for flatware and holloware, with nickel content determining corrosion performance and raw material cost exposure.
- Plastic:Food-grade polymers and emerging bio-composites, facing heat-resistance ceilings above 120°C that restrict high-temperature foodservice deployment.
Highest margin capture: Ceramic. Volume leadership: Glass.
Price Tier:
Three-tier pricing structures separate heritage-positioned collections from standardized commercial-grade supply and commoditized household procurement.
- Luxury:Artisan-crafted and designer-licensed collections commanding premium positioning through heritage narrative and limited production. Villeroy & Boch AG anchors European hospitality demand through estate-wide supply agreements with sovereign wealth-backed developments in Saudi Arabia and the United Arab Emirates.
- Mid-Range:Branded standardized collections facing compression from private-label competition and direct-to-consumer ceramic startups bypassing traditional distributor markups.
- Affordable:Mass-market branded supply for household and casual foodservice replacement cycles.
- Budget:Unbranded and private-label procurement for high-turnover commercial applications and emerging market penetration.
Margin concentration: Luxury. Fastest channel shift: Mid-Range.
End User:
Procurement authority is consolidating among multinational hospitality groups, displacing property-level purchasing with centralized sourcing platforms and direct manufacturer negotiation.
- Hotels:Estate-wide supply agreements negotiated at corporate level, visible in UAE and Saudi Arabia where sovereign wealth-backed developments contract directly with Arc International and Villeroy & Boch AG for standardized property fit-outs.
- Restaurants:Organized chain procurement in India—specifically Mumbai and Bangalore—presents underpenetrated demand for standardized commercial-grade dinnerware as organized foodservice expands.
- Households:Replacement-driven demand and occasion-based gifting, increasingly disintermediated by direct-to-consumer ceramic startups with owned e-commerce channels.
- Catering Services:Volume procurement for event and contract foodservice, with bio-based material adoption accelerating under EU Green Deal packaging directives for single-use and limited-use applications.
Dominant procurement value: Hotels. Steepest expansion trajectory: Catering Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian province's kaolin deposits and tunnel kiln infrastructure anchor global ceramic tableware supply chains, while regulatory divergence across import markets fragments compliance requirements for cross-border manufacturers.
China
Dehua and Jingdezhen ceramic clusters supply vitrified porcelain to North American and European retail channels under FDA and EU ECHA REACH dual-certification protocols. China's GB standards for domestic ceramic safety impose parallel testing burdens that extend product development timelines for export-oriented manufacturers. Fujian province concentration creates single-origin vulnerability as brands seek supply diversification away from concentrated geopolitical exposure.
United States
Big-box retail channels drive stainless steel flatware volume procurement, with FDA food-contact compliance filtering subscale suppliers and consolidating import volume with certified exporters. Natural gas price volatility impacts domestic soda-lime glass production economics. Meyer Corporation Group leverages scale positioning across mass-market distribution networks.
Germany
EU ECHA REACH Annex XVII restrictions on lead and cadmium in ceramic glazes mandate systematic reformulation across import supply chains. Stuttgart and Frankfurt hospitality procurement offices negotiate estate-wide supply agreements directly with heritage manufacturers. Germany's Federal Institute for Risk Assessment enforces stringent heavy metal testing protocols for food-contact ceramics.
France
Limoges retains concentrated glaze chemist expertise for compliant vitrified finishes as EU Green Deal packaging directives accelerate bio-based material substitution. Arc International's French glassmaking facilities sustain margin control through captive melting capacity. France's AGEC law creates premium positioning for closed-loop recyclable tableware collections in contract foodservice procurement.
United Arab Emirates
Sovereign wealth-backed hospitality developments in Dubai and Abu Dhabi negotiate direct supply agreements with premium manufacturers for standardized property fit-outs. Centralized procurement authority displaces traditional wholesale-distributor relationships across hotel chains. MOHAP food-contact regulations govern import acceptance for ceramic and glass tableware.
Global Tableware Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to EU regulatory reformulation requirements and Southeast Asian hospitality demand surges. The vendor base stratifies across heritage-positioned European houses, scale-driven Asian fabricators, and direct-to-consumer ceramic startups. Three archetypes define competitive positioning: vertically integrated glassmakers with captive raw material supply, specialist porcelain houses with concentrated glaze expertise, and stainless steel flatware producers leveraging procurement scale. M&A activity and geographic diversification represent the dominant competitive moves as brands reduce Fujian province dependence.
Among heritage-positioned European houses, Villeroy & Boch AG exemplifies premium-tier anchoring through estate-wide hospitality agreements, while Arc International occupies a position within vertically integrated glassmaking. Meyer Corporation Group represents scale-driven flatware procurement across North American retail channels. These three entities illustrate how competitive positioning diverges across material specializations and channel strategies.
| Leading Market Players |
|---|
| Corelle Brands |
| Lenox Corporation |
| Arc International |
| Libbey |
| Bormioli Rocco |
| Villeroy & Boch AG |
| Rosenthal GmbH |
| Noritake Co., Ltd. |
| Meyer Corporation Group |
| Others |
Value Chain & Pricing Dynamics
EU ECHA REACH Annex XVII restrictions on heavy metals in ceramic glazes gate qualified supply and premium-tier pricing access, forcing exporters to absorb compliance laboratory costs and third-party certification investments that stratify market entry. Brands lacking compliant formulation capabilities face exclusion from German, French, and Benelux procurement channels, concentrating margin capture with heritage manufacturers possessing in-house glaze chemistry expertise.
Pricing Analysis
Warranty and estate-wide service bundling separate luxury hospitality supply agreements from transactional spot procurement, with Villeroy & Boch AG and Arc International commanding premium positioning through multi-year fit-out commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA and EU dual-certified collections capturing 40-60 point spreads over single-certified alternatives. Cost compression in mid-range segments intensifies as direct-to-consumer ceramic startups bypass distributor markups. North American big-box retail channels exhibit highest price sensitivity, while sovereign wealth-backed hospitality developments in the United Arab Emirates prioritize compliance certainty over unit cost.
Supply Chain Analysis
Glaze chemist availability concentrates in Stoke-on-Trent and Limoges, constraining compliant production capacity expansion as aging specialists retire without pipeline replacement. China's Fujian province, France's Limoges basin, and the United Arab Emirates' Jebel Ali free zone anchor global supply, with kaolin deposits and tunnel kiln infrastructure feeding North American and European retail channels. Raw material sourcing draws from Ukrainian titanium dioxide, Australian zirconium silicate, and Chinese rare-earth opacifiers. Single-origin vulnerability in Fujian province exposes brands to geopolitical disruption and logistics congestion. Distribution runs through centralized group purchasing organizations displacing traditional wholesale-distributor relationships in multinational hotel chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU ECHA REACH compliance functions as a cost-of-compliance moat, with heavy metal testing and dual-certification burdens filtering subscale suppliers and consolidating procurement authority with certified heritage manufacturers.
For Market Incumbents: Hedge against Fujian province concentration by qualifying secondary ceramic clusters in Vietnam and India, while capturing retiring glaze chemist expertise through targeted recruitment in Stoke-on-Trent and Limoges. Backward integration into compliant raw material sourcing secures supply continuity as Ukrainian titanium dioxide and Chinese rare-earth channels face volatility.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes offer the most penetrable entry vector, bypassing distributor markups and capturing household replacement demand previously allocated to retail intermediaries. Target India's underpenetrated organized restaurant chains in Mumbai and Bangalore with standardized commercial-grade dinnerware, leveraging lower compliance burdens for domestic-only supply. Lead with sustainability certification and transparent supply chain storytelling to differentiate against opaque incumbent sourcing.
For Investors and Strategic Acquirers: France's AGEC law implementation acceleration is the leading indicator that closed-loop recyclable tableware collections will command premium positioning in contract foodservice procurement. The five-to-ten year viability window favors acquisition targets possessing captive glaze formulation expertise and established EU ECHA REACH compliance infrastructure. Monitor sovereign wealth-backed hospitality development announcements in Saudi Arabia and the United Arab Emirates as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Glaze Chemistry Talent Acquisition | Limoges and Stoke-on-Trent specialists anchor compliant formulation capabilities for EU market access. |
| Dual-Certification Laboratory Investment | In-house testing for China's GB standards and FDA compliance compresses product development timelines. |
| Secondary Ceramic Cluster Qualification | Vietnam and India sourcing reduces single-origin exposure to Fujian province disruption. |
| Direct-to-Consumer Channel Launch | Owned e-commerce captures margin previously allocated to wholesale-distributor relationships. |
| Bio-Based Material Collection Development | EU Green Deal procurement mandates accelerate compostable tableware adoption in contract foodservice. |
Study Parameters
Independent corroboration across hospitality procurement directors, ceramic manufacturing plant managers, glaze chemistry specialists, and retail category buyers underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with supply chain executives at heritage European houses, export-oriented manufacturers in Fujian province, and group purchasing organization leads in North American hotel chains. Secondary validation drew from EU ECHA REACH regulatory filings, FDA import refusal data, French AGEC law implementation guidance, and hospitality development procurement databases. Bottom-up volume estimates triangulated against top-down macroeconomic consumption patterns.
Comparable historical periods anchored the projection framework, with growth trajectories calibrated to regulatory implementation timelines and hospitality development cycles across the analysis window. Segmentation modeling spanned material substrate, price tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from fitted trend extrapolation adjusted for compliance cost absorption and channel shift velocity. Forecast inputs incorporated natural gas price volatility impacts on soda-lime glass firing economics and bio-based polymer heat-resistance limitations above 120°C.
The model holds under stable regulatory enforcement intensity and continued sovereign wealth hospitality investment; deviation in EU ECHA REACH expansion scope or geopolitical disruption severity in Fujian province would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
India POU Water Purifiers Market
Household Items
Commercial Locker Market
Household Items
Replacement Sheets Market
Household Items
North America B2B Air Care Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Smart Fork Market
Household Items
Silicone Soap Mold Market
Household Items
Toilet Paper Market
Household Items
US Air Fresheners Market
Household Items
Air Humidifier Market
Household Items
Candle Jar Market
Household Items
Hand Wash Station Market
Household Items
Wax Removal Aids Market
Household Items
Dosage Spoon Market
Household Items
Scouring Pads Market
Household Items
Nebulizing Diffuser Market