
 Toilet Brush Market | 2026-2036
Toilet Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Brush Market Insights
Market Context
Artisan brush-making labor pools in traditional manufacturing centers is collapsing as younger workers exit manual production roles for service-sector employment. OXO International leverages ergonomic design expertise to sustain premium positioning in North American retail channels. Joseph Joseph anchors European market share through compact, design-forward product lines that command shelf space at specialty homeware retailers. Rubbermaid Commercial Products dominates institutional procurement with durable, antimicrobial-featured offerings that meet stringent facility hygiene standards.
Technical Definition and Segment Structure
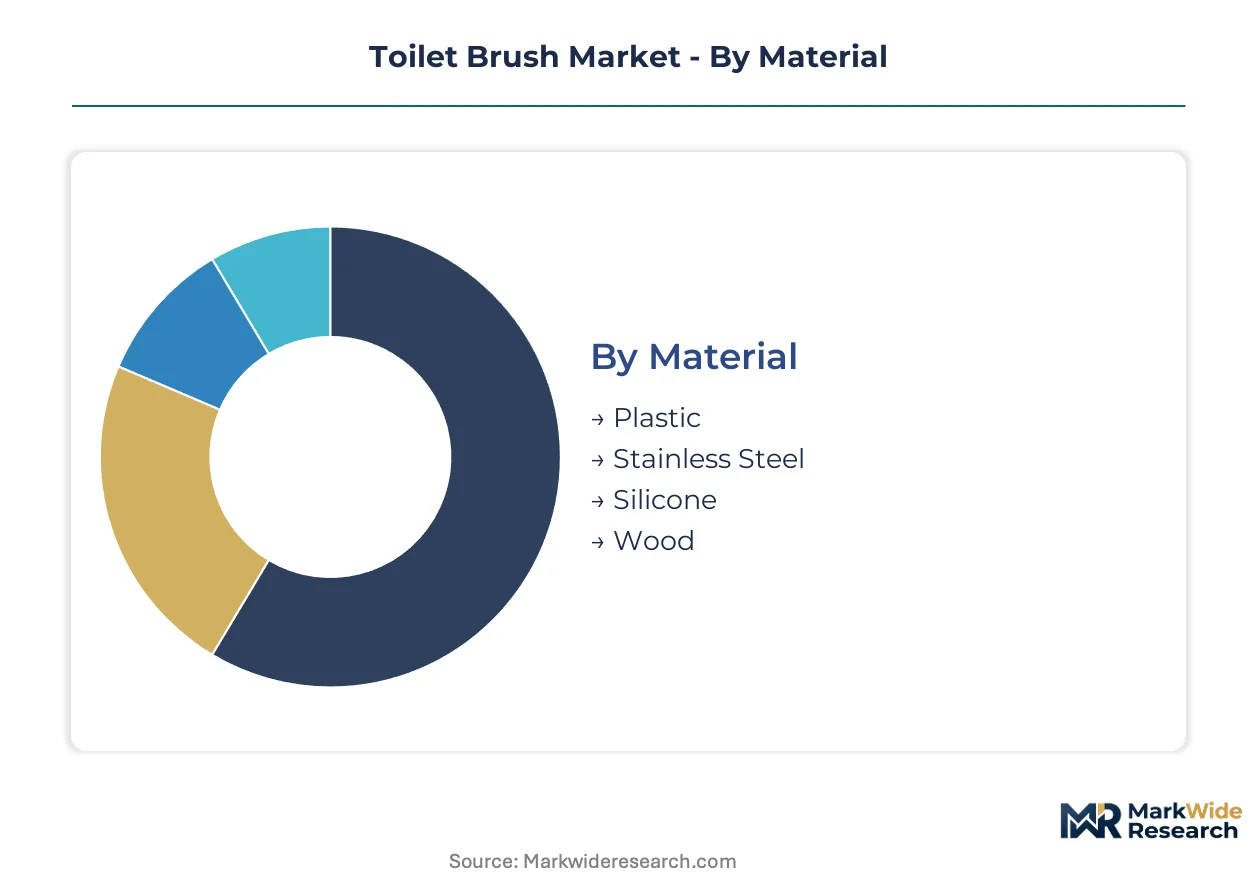
A toilet brush consists of a handle assembly paired with bristle or blade elements—typically polypropylene, silicone, or natural fibers mounted on steel or reinforced plastic shafts—engineered to remove organic residue from ceramic bowl surfaces while minimizing cross-contamination through drainage and drying features. Plastic remains the volume leader across material segments due to cost efficiency, though silicone is gaining fastest as consumers prioritize non-porous, quick-drying alternatives that resist bacterial colonization. The automatic type segment occupies emerging margin pools through battery-powered scrubbing mechanisms, while the hospitality customer type concentrates demand for refillable systems that reduce replacement frequency in high-traffic restrooms.
Regulatory Environment and Outlook
The EPA regulates antimicrobial claims under FIFRA, requiring registration of treated articles that inhibit bacterial growth on brush surfaces sold in the United States. REACH compliance in Europe restricts certain phthalates and heavy metals in plastic components, redirecting formulation toward bio-based polymers. California's Proposition 65 labeling mandates affect distribution into that state, creating compliance segmentation between national and restricted product lines. Stakeholders must monitor evolving state-level chemical disclosure requirements and weigh the capital costs of dual-SKU manufacturing against the pricing power of certified clean-label positioning.
Market Dynamics
Antimicrobial surface treatments and REACH-mandated material substitutions are restructuring procurement criteria across hospitality and institutional channels, compressing legacy plastic volumes while elevating silicone and wood alternatives.
Growth Catalysts
- REACH chemical restrictions:ECHA's expanding substance blacklist is forcing formulation pivots toward bio-based polymers and non-porous silicone bristles that resist bacterial colonization.
- Hospitality hygiene protocols:North American hotel chains are mandating refillable brush systems with antimicrobial claims to reduce cross-contamination in high-traffic restrooms.
- Artisan labor collapse:Traditional brush-making centers in Southern Europe are shedding manual production capacity, accelerating automation investment in Eastern European manufacturing clusters.
Market Restraints
- Petrochemical input volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, squeezing margin stability for volume-tier manufacturers dependent on plastic components.
- Antimicrobial registration friction:EPA FIFRA compliance for treated articles requires 18-24 month approval cycles, blocking rapid product iteration for US-bound lines.
- Silicone supply concentration:Medical-grade silicone feedstock for premium brushes concentrates among three German and Chinese chemical suppliers, creating bottleneck risk.
Strategic Opportunities
- EU Green Deal procurement mandates:Public facility tenders across Germany and France now weight lifecycle carbon metrics, advantaging wood-fiber and recycled-content brush suppliers.
- Direct-to-hospitality channel bypass:Specialized distributors serving hotel chains are consolidating, creating entry points for manufacturers to build captive procurement relationships.
- Smart restroom convergence:IoT-enabled dispensers and usage-tracking systems are opening integration partnerships for brush manufacturers with sensor and facility management platforms.
Industry Challenges
- Ergonomic design talent scarcity:Industrial designers with expertise in antimicrobial surface engineering and user-centered handle development command premium compensation, constraining mid-tier R&D budgets.
- Dual-SKU manufacturing complexity:California Proposition 65 labeling requirements force separate production runs for state-restricted versus national product lines, elevating inventory carrying costs.
- Antimicrobial claim substantiation:Laboratory testing for EPA-registration-compliant efficacy data requires specialized microbiology partnerships that smaller manufacturers struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Brush Market |
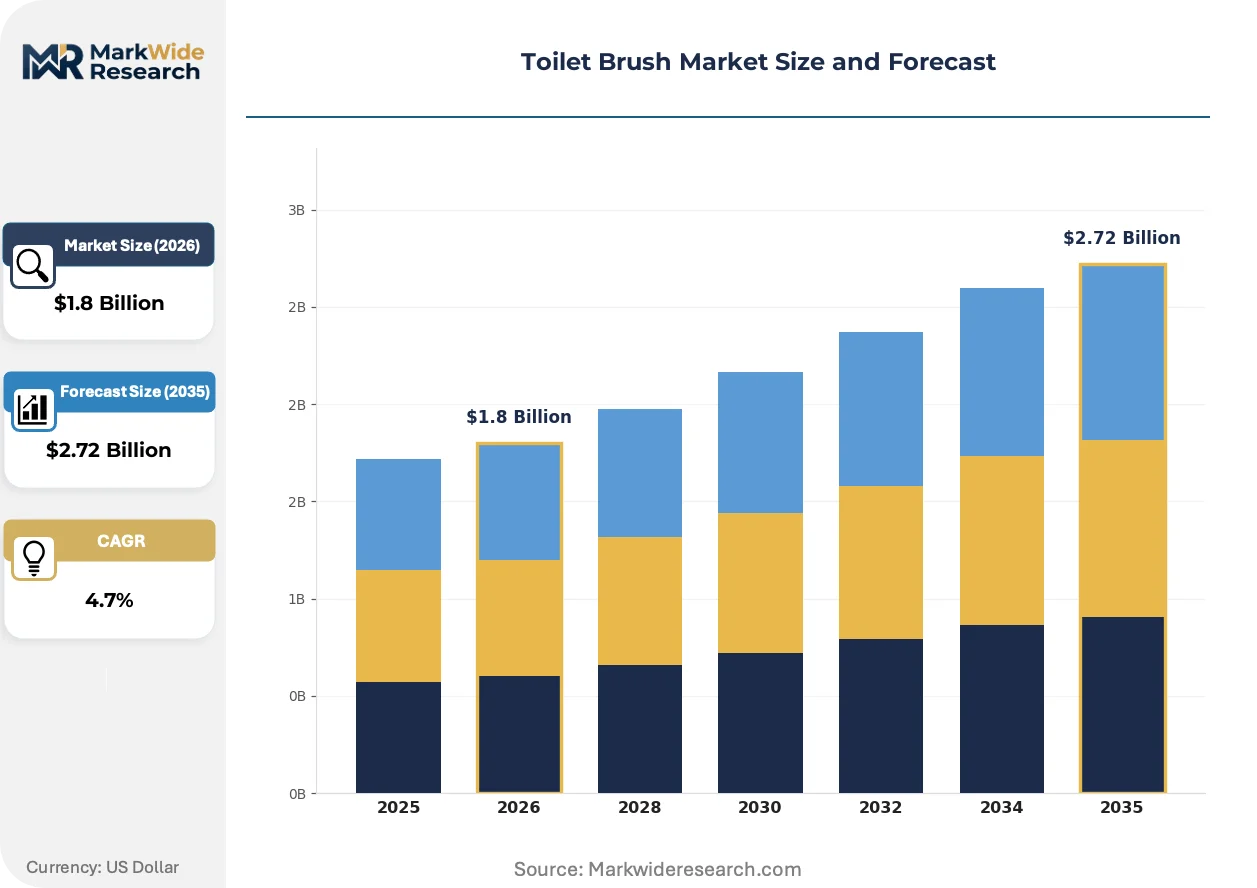
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Stainless Steel, Silicone, Wood Type: Traditional, Disposable, Automatic, Ergonomic Feature: Antimicrobial, Refillable, Compact, Eco-friendly Customer Type: Residential, Commercial, Institutional, Hospitality |
| Companies Covered | Casabella, Joseph Joseph, OXO International, 3M, Fuller Brush Company, Rubbermaid Commercial Products, Clorox, Libman, Simplehuman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Brush Market Trends and Innovations
Battery-powered scrubbing mechanisms and quick-drying material science are collapsing the functional gap between manual and automated cleaning systems, while regulatory chemistry restrictions are accelerating material substitution timelines.
Silicone blade and bristle formulations are miniaturizing into compact, replaceable cartridges that snap into standardized handle systems. Boutique hotel operators in Scandinavia are adopting these configurations fastest, compressing replacement cycles from annual to quarterly while reducing water retention and bacterial growth surfaces. The technology is miniaturizing component footprints enough to enable wall-mounted dispensing units in space-constrained urban restrooms.
ECHA REACH Annex XVII expansions are prohibiting additional phthalate plasticizers and heavy metal stabilizers in consumer goods, redirecting compounder R&D toward bio-based polyesters and natural fiber reinforcements. German retailers are now demanding full material disclosure documentation as a listing prerequisite, filtering out opaque supply chains. Premium private-label programs at specialty homeware chains are responding fastest, sourcing certified wood and compressed fiber alternatives.
Facility managers are unbundling brush replacement from full-system procurement, treating consumables as separate spend categories with distinct vendor qualification. Hospitality procurement teams are consolidating this purchasing through group purchasing organizations that negotiate multi-year supply agreements. This behavior shift is most pronounced in German-speaking markets, where facility services outsourcing has concentrated buying power among three major hospitality supply consortia.
Toilet Brush Market Segmentation
Material chemistry and antimicrobial claims now determine procurement eligibility across institutional channels, while hospitality buyers unbundle replacement cycles from handle systems. Segmentation strategy must align formulation portfolios with diverging regulatory thresholds rather than treating material choice as a cost variable alone.
Material:
REACH Annex XVII restrictions on phthalates and heavy metal stabilizers are fragmenting compliant supply chains across European procurement, forcing manufacturers to maintain parallel formulation tracks for regulated and unregulated markets.
- Plastic:Polypropylene bristle arrays dominate volume manufacturing due to cost efficiency and moldability. Procurement concentrates among budget-tier residential channels in North America and Eastern Europe, though EPA FIFRA registration requirements for antimicrobial-treated variants extend lead times for US-bound product lines.
- Silicone:Non-porous elastomer formulations resist bacterial colonization and enable rapid drying. German hotel chains and Scandinavian boutique operators are standardizing on medical-grade silicone cartridges that snap into standardized handle systems, compressing replacement cycles while satisfying stringent hygiene protocols.
- Stainless Steel:Corrosion-resistant shafts and ferrules provide structural longevity in high-frequency institutional environments. Japanese facility management contractors specify brushed-finish grades for premium commercial restrooms.
- Wood:Compressed fiber and certified timber alternatives satisfy EU Green Deal lifecycle carbon metrics for public facility tenders. French and German retailers now require full material disclosure documentation as a listing prerequisite.
Plastic handles the majority of throughput; silicone is the fastest mover on share.
Type:
Automation economics are collapsing the functional gap between manual scrubbing and powered systems as battery miniaturization reduces unit costs.
- Traditional:Basic bristle-and-handle configurations persist in price-sensitive residential segments. Italian and Spanish households retain preference for replaceable-head designs that extend handle lifespan.
- Disposable:Single-use wands with pre-loaded cleaning agents target convenience-oriented consumers. UK supermarket private-label programs have expanded shelf allocation for these configurations.
- Automatic:Battery-powered scrubbing mechanisms with rotating heads reduce manual labor in high-traffic restrooms. North American hospitality chains are piloting these systems in airport and convention center properties.
- Ergonomic:Angled handles and grip-optimized geometries reduce wrist strain for cleaning staff. OXO International sustains premium positioning in North American retail through patented contour designs.
Traditional configurations retain volume dominance; automatic systems are climbing the fastest on margin contribution.
Feature:
Antimicrobial registration friction is creating a two-tier market split between EPA-registered treated articles and unverified marketing claims.
- Antimicrobial:Silver-ion or triclosan-treated surfaces require FIFRA compliance documentation for US distribution. Rubbermaid Commercial Products dominates institutional procurement with registered formulations that meet facility hygiene standards.
- Refillable:Cartridge-based systems separate consumable bristles from permanent handles. German hospitality supply consortia negotiate multi-year agreements for these configurations to reduce total cost of ownership.
- Compact:Miniaturized footprints enable wall-mounted dispensing in space-constrained urban restrooms. Scandinavian boutique hotel operators have adopted these designs fastest.
- Eco-friendly:Bio-based polymers and recycled-content certification satisfy public procurement mandates. French facility tenders now weight lifecycle carbon metrics explicitly.
Antimicrobial features command premium placement; eco-friendly specifications are gaining share fastest in EU public procurement.
Customer Type:
Procurement concentration among hospitality group purchasing organizations is compressing vendor margins while extending contract durations.
- Residential:Individual household purchases through retail and e-commerce channels. German consumers demonstrate strongest willingness-to-pay for premium eco-friendly designs.
- Commercial:Office building and retail facility maintenance contracts. US facility management platforms are integrating IoT-enabled usage tracking with brush replacement scheduling.
- Institutional:Government and healthcare facilities with stringent hygiene mandates. EPA FIFRA compliance is non-negotiable for hospital procurement committees.
- Hospitality:Hotel chains and foodservice operations with standardized room configurations. Three major German-speaking supply consortia now control the majority of procurement volume in that market.
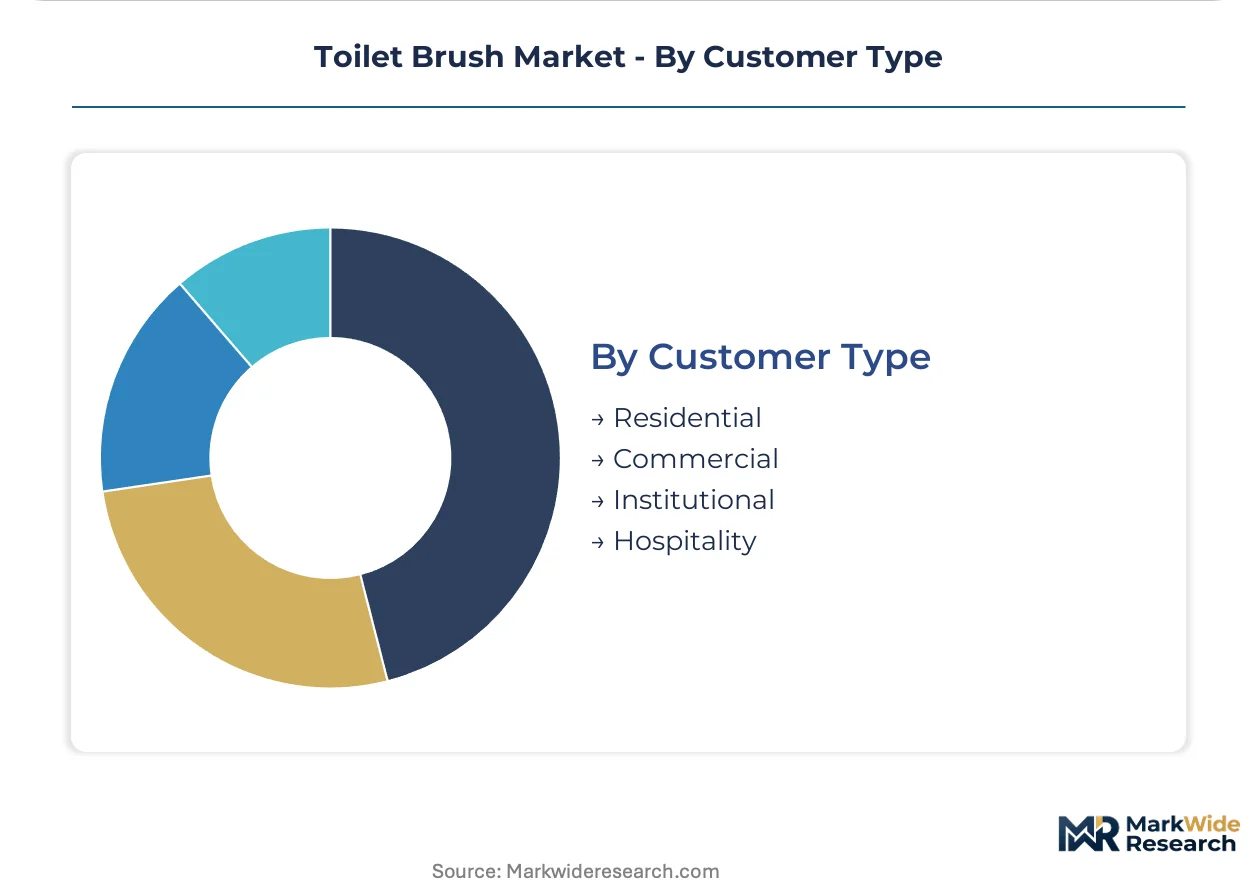
Residential channels absorb the highest unit volume; hospitality procurement is expanding most quickly on value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households favor premium eco-friendly designs with full material disclosure, while US hospitality chains prioritize antimicrobial compliance and refillable systems. Japanese facility managers specify corrosion-resistant grades for high-frequency commercial environments. REACH chemical restrictions and EPA FIFRA registration requirements are fragmenting compliant supply chains across these markets.
Germany
German retailers now mandate complete material documentation as a listing prerequisite, filtering opaque supply chains from shelf placement. ECHA REACH Annex XVII expansions prohibit additional phthalate plasticizers, redirecting compounder R&D toward bio-based polyesters. The Baden-Württemberg manufacturing cluster hosts precision molders supplying cartridge-based silicone systems to hospitality consortia.
United States
North American hotel chains are standardizing on refillable brush systems with EPA-registered antimicrobial claims to reduce cross-contamination liability. EPA FIFRA compliance requires 18-24 month approval cycles for treated articles, blocking rapid product iteration. Chicago-based facility management platforms are piloting IoT-enabled usage tracking integrated with brush replacement scheduling.
Japan
Japanese facility management contractors specify brushed-finish stainless steel grades for premium commercial restrooms in high-traffic properties. METI industrial standards guide material specifications for institutional procurement committees. The Kanto region around Tokyo concentrates demand from corporate headquarters and luxury hospitality properties.
France
French public facility tenders now weight lifecycle carbon metrics explicitly, advantaging wood-fiber and recycled-content brush suppliers. EU Green Deal procurement mandates extend to municipal cleaning contracts across Île-de-France and regional capitals. Lyon-based hospitality supply distributors are consolidating procurement relationships with certified sustainable manufacturers.
United Kingdom
UK supermarket private-label programs have expanded shelf allocation for disposable wand configurations targeting convenience-oriented consumers. The country's national chemical regulator enforces REACH-aligned restrictions on consumer goods composition. Greater Manchester hosts contract manufacturers serving budget-tier retail channels across Northern England.
Toilet Brush Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the toilet brush market. The upper tier commands institutional procurement relationships through antimicrobial registration expertise and multi-year supply agreements. Below them, design-forward specialists and regional fabricators compete on ergonomic innovation and material certification. Competitive moves concentrate on strategic partnerships with hospitality group purchasing organizations and portfolio diversification into smart restroom integration.
Among design-centric specialists, Joseph Joseph exemplifies the compact, design-forward archetype that commands specialty homeware retail placement. OXO International occupies a position within the ergonomic innovation tier, sustaining premium positioning through patented handle geometries. Rubbermaid Commercial Products anchors the institutional-grade segment, representing the antimicrobial-registered archetype that dominates facility hygiene procurement.
| Leading Market Players |
|---|
| Casabella |
| Joseph Joseph |
| OXO International |
| 3M |
| Fuller Brush Company |
| Rubbermaid Commercial Products |
| Clorox |
| Libman |
| Simplehuman |
| Others |
Pricing and Supply Chain Analysis
Silicone substitution for polypropylene bristles is simultaneously relocating supply geography toward German and Chinese chemical suppliers and compressing margin structures for volume-tier manufacturers dependent on petrochemical inputs. This material pivot elevates input costs while creating pricing power for certified medical-grade formulations that satisfy hospitality procurement mandates.
Pricing Analysis
Long-term offtake agreements dominate hospitality procurement through German-speaking supply consortia, while spot purchasing persists in residential retail channels. Three-tier pricing structure across premium silicone-cartridge, standard plastic-replaceable, and economy fixed-head configurations separates antimicrobial-registered offerings from unverified claims. Cost compression in budget-tier plastic lines is intensifying because polypropylene resin prices fluctuate with crude oil benchmarks. Price sensitivity concentrates among Eastern European residential buyers, while German hotel chains demonstrate willingness-to-pay for certified lifecycle carbon documentation.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Chinese-sourced silicone feedstock and polypropylene resin shipments. Manufacturing concentrates in China for plastic components, Germany for precision silicone molding, and Italy for compressed wood-fiber alternatives. Raw material dependencies rest on polypropylene resin, medical-grade silicone elastomers, and certified timber feedstock. Single-source vulnerability concentrates among three German and Chinese silicone suppliers. Distribution runs through hospitality group purchasing organizations in German-speaking markets, specialty homeware retailers in North America, and supermarket private-label programs in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EPA FIFRA registration and REACH compliance create 18-24 month approval barriers that protect incumbent antimicrobial-registered positions from rapid competitive replication.
For Market Incumbents: Secure multi-year supply agreements with consolidating hospitality group purchasing organizations before channel power further concentrates. Deepen backward integration into medical-grade silicone compounding to reduce dependency on bottlenecked German and Chinese suppliers. Prioritize certification investment in EU Green Deal lifecycle carbon documentation to capture French and German public facility tender mandates. For New Entrants and Emerging Players: Direct-to-hospitality channel bypass represents the most penetrable white-space opportunity, as specialized distributors serving boutique hotel chains remain fragmented relative to consolidated retail. Target Scandinavian boutique operators with compact wall-mounted dispensing configurations that compress replacement cycles. Pursue private-label partnerships with UK supermarket programs expanding disposable wand shelf allocation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated compounders with captive silicone supply and registered antimicrobial formulations. Long-term viability hinges on regulatory chemistry expertise rather than manufacturing scale alone. Monitor ECHA REACH Annex XVII expansion announcements as the critical inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Registration Investment | EPA FIFRA compliance creates 18-24 month barriers protecting institutional procurement relationships. |
| Silicone Compounding Backward Integration | Captive supply of medical-grade elastomers reduces bottleneck risk from concentrated German and Chinese suppliers. |
| Hospitality GPO Partnership | Multi-year agreements with German-speaking supply consortia lock in volume before channel consolidation completes. |
| EU Green Deal Certification | Lifecycle carbon documentation satisfies French and German public facility tender weighting requirements. |
| Smart Restroom Integration | IoT-enabled usage tracking partnerships with facility management platforms create recurring replacement revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across published sources. Primary interviews encompassed procurement directors at hospitality group purchasing organizations, category buyers at German and UK retailers, regulatory affairs specialists navigating EPA FIFRA and REACH compliance, and plant managers at silicone compounding facilities. Secondary sources included customs trade records for polypropylene and silicone elastomer flows, SEC filings from listed household goods manufacturers, ECHA substance restriction announcements, and hospitality supply consortium tender documentation. Bottom-up demand modeling triangulated against top-down market sizing from trade association aggregates.
Across the projection horizon, the analytical framework modeled volume and value trajectories through segmentation across material chemistry, product type, feature configuration, and customer channel. CAGRs derived from regression analysis of historical procurement patterns and elasticity estimates for antimicrobial premiumization. Industry-specific forecast inputs incorporated REACH Annex XVII expansion schedules and hospitality hygiene protocol adoption curves.
Underlying assumptions cover stable petrochemical input pricing and continued ECHA regulatory expansion, with deviation risk concentrated in silicone supply disruptions and accelerated state-level chemical disclosure mandates in the United States. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Snow Blower Market
Household Items
Global Paper Towels Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Insulated Tumblers Market
Household Items
Insulated Drinkware Market
Household Items
Aromatherapy Diffuser Market
Household Items
Bottle Openers Market
Household Items
MENA POU Water Purifiers Market
Household Items
Sleeping Pods Market
Household Items
Lunch Box Market
Household Items
Portable Iron Market
Household Items
Asean Cookware Market
Household Items
Mirror Holder Market
Household Items
Air Humidifier Market
Household Items
Residential Air Purifiers Market
Household Items
Chest Freezers Market