
 Insulated Lunch Box Market | 2026-2036
Insulated Lunch Box Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Lunch Box Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for European suppliers, forcing reformulation of insulation foams and adhesive bonding agents. Yeti leverages premium thermal engineering to sustain pricing power across North American outdoor retail channels. PackIt anchors its position through proprietary freezable gel-wall technology that eliminates separate ice packs. Bentgo competes in the children's segment with compartmentalized designs that simplify portion control for parents.
An insulated lunch box is a portable food-storage vessel engineered with thermal barrier layers—typically expanded polystyrene, polyurethane foam, or vacuum-insulated stainless steel walls—to maintain interior temperatures for four to twelve hours, designed for commercial and consumer meal transport away from kitchen infrastructure. Stainless steel constructions command margin pools at the premium tier due to durability claims and food-safety perceptions, while fabric-based soft-sided variants lead unit volumes through lower price points and collapsible convenience. The professional consumer segment shows the fastest structural expansion as hybrid work normalization sustains interest in office-compatible meal solutions.
FDA food-contact material regulations govern polymer and coating safety in the United States, while the EU Green Deal's packaging waste directives are accelerating biodegradable insulation trials across Continental manufacturers. China's SAMR enforces GB standards for plastic migration limits, shaping export compliance burdens for Asian suppliers. Stakeholders must monitor whether thermal-performance certification schemes emerge as a de facto market-access gate in jurisdictions where food-safety agencies expand their purview beyond materials into functional claims.
Market Dynamics
EU Green Deal packaging-waste directives are forcing Continental manufacturers to abandon petroleum-based insulation foams and requalify supply chains around bio-based alternatives, compressing margin structures while creating first-mover certification advantages.
Growth Catalysts
- REACH compliance consolidation:European suppliers absorbing reformulation costs are capturing shelf space as non-compliant imports face customs detention at Rotterdam and Hamburg ports.
- Commuter density in urban India:Metro expansions in Mumbai, Bangalore, and Delhi are extending daily travel times beyond viable hot-food windows, elevating thermal retention from convenience to necessity.
- Polyurethane foam substitution:Vacuum-insulated stainless-steel wall assemblies are penetrating the professional segment as hybrid work patterns normalize office meal-prep routines.
Market Restraints
- Petrochemical input volatility:Expanded polystyrene bead prices fluctuate with benzene derivative markets, squeezing contract manufacturers in Guangdong and Zhejiang provinces.
- Single-supplier concentration for freezable gels:Proprietary phase-change materials rely on captive Japanese chemical houses, exposing PackIt-style competitors to force-majeure allocation risk.
- Thermal-performance certification gaps:Absence of harmonized ASTM or ISO test protocols for duration claims permits specification inflation, eroding buyer trust in premium tiers.
Strategic Opportunities
- Sub-Saharan African urbanization:Lagos, Nairobi, and Johannesburg commuter corridors lack cold-chain retail penetration, creating white space for solar-charged active-cooling lunch systems.
- FSSAI food-contact material recognition:Indian regulatory alignment with EU migration limits would unlock export qualification for domestic stainless-steel fabricators.
- Direct-to-employer contracting:Corporate wellness programs in metropolitan China are bypassing retail channels to source branded meal-prep kits for distributed workforces.
Industry Challenges
- Thermal-engineering talent scarcity:Competent finite-element analysis for multi-layer barrier design concentrates in South Korean and German industrial-design consultancies, inflating project fees.
- Biodegradable insulation scale-up:Mycelium and starch-foam alternatives require capital-intensive pilot lines that lack depreciation schedules matched to uncertain offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Lunch Box Market |
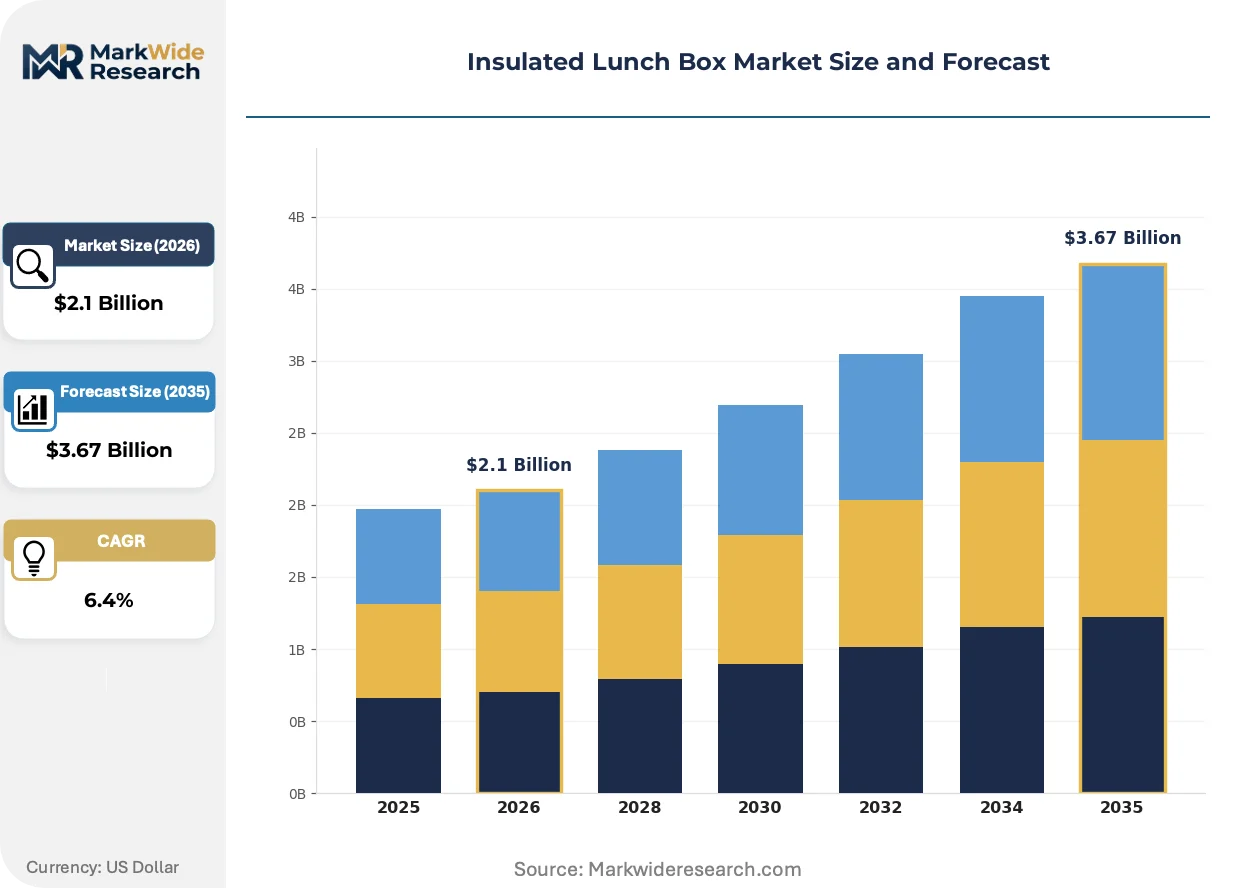
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Stainless Steel, Glass, Fabric Size: Small, Medium, Large, Extra Large Target Consumer: Students, Professionals, Outdoor Enthusiasts, Families Feature: Leak-Proof, Microwave-Safe, Eco-Friendly, Divided Compartments |
| Companies Covered | CleverMade, Black + Blum, Yeti, PlanetBox, Tatay, PackIt, L.L. Bean, Bentgo, Pottery Barn Kids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Lunch Box Market Emerging Trajectories
Active-cooling integration and modular thermal-barrier architectures are displacing passive-insulation dominance, while regulatory material bans accelerate substitution timelines beyond typical product-development cycles.
Vacuum-insulated stainless-steel wall assemblies are modularizing across premium-tier product lines. Professional consumers in metropolitan China and urban India are adopting these systems as daily commute durations extend. The technology is modularizing supplier ecosystems, enabling original-design manufacturers to mix-and-match barrier layers without captive foam-injection capacity.
REACH Annex XVII restrictions on persistent organic pollutants in adhesives are eliminating solvent-based bonding agents from European production. Continental manufacturers are qualifying water-based polyurethane dispersions and UV-cured acrylics for lamination processes. Children's segment suppliers face the steepest retooling burden due to enhanced safety documentation requirements for food-contact surfaces.
Employer-subsidized meal-prep programs are displacing individual retail purchase as the dominant procurement channel for professional-grade units. Corporate procurement departments in Seoul, Tokyo, and Singapore are negotiating volume frameworks directly with original-equipment manufacturers. This concentration is most visible in South Korean chaebol-affiliated manufacturing compounds where on-site commissaries have been decommissioned.
Insulated Lunch Box Market Segmentation
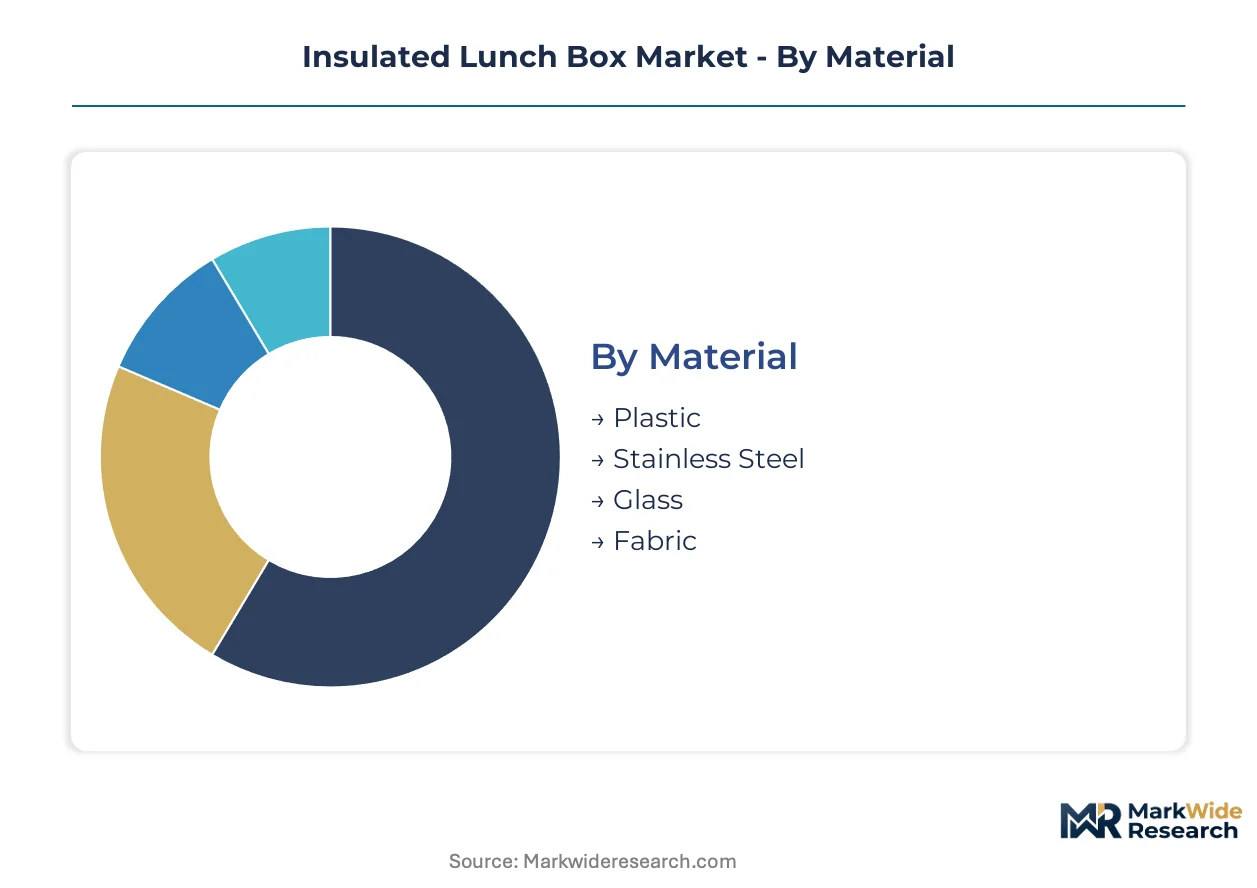
Thermal-performance requirements and regulatory material bans are fragmenting demand across distinct construction formats, while commuter-density patterns reshape size preferences and employer-subsidized procurement redefines target-consumer boundaries.
Material:
Standalone thermal systems dominate portable meal transport, whereas embedded insulation within corporate meal-prep infrastructure remains nascent.
- Plastic:Expanded polystyrene and polyurethane foam cores deliver four-to-six-hour retention at entry price points. Demand concentrates in Guangdong and Zhejiang manufacturing clusters serving Southeast Asian export markets, though EU Green Deal directives are accelerating phase-out timelines.
- Stainless Steel:Vacuum-insulated double-wall assemblies achieve eight-to-twelve-hour thermal stability through copper-lined barriers. Professional consumers in metropolitan China and urban India absorb premium pricing as hybrid work normalizes daily meal-prep routines.
- Glass:Borosilicate vessels with silicone sleeves target microwave-safe convenience for office environments. Japanese and South Korean consumers prioritize food-safety transparency over weight penalties.
- Fabric:Soft-sided constructions with reflective foil liners and closed-cell foam padding dominate collapsible convenience. Indian commuter corridors favor these formats for multi-modal transport across metro and bus networks.
Plastic leads volumes today; stainless steel is gaining share fastest.
Size:
Cost tiers stratify sharply between single-portion commuter formats and family-scale systems requiring reinforced structural engineering.
- Small:Single-compartment vessels under one liter target snack transport and pediatric portioning. South Korean chaebol wellness programs source these for desk-side meal supplementation.
- Medium:One-to-two-liter capacities balance main-course storage with briefcase compatibility. Professionals in Tokyo and Singapore corporate towers represent the densest adoption cluster.
- Large:Multi-container systems accommodate complete meals with thermal zoning for hot and cold components. Indian nuclear families in Bangalore and Mumbai metro zones drive replacement cycles.
- Extra Large:Picnic-scale coolers with shoulder straps and external pockets serve outdoor recreation and construction-site catering. North American outdoor retail channels sustain premium positioning.
Medium formats anchor revenue today; large configurations are expanding most quickly.
Target Consumer:
Application context determines thermal-duration specifications more than demographic labels alone.
- Students:K-12 and university segments prioritize drop-resistance and compartmentalization over extended retention. Bentgo-style portion-control designs simplify parent purchasing decisions in US and European markets.
- Professionals:Office-compatible aesthetics and leak-proof seals dominate procurement criteria. Employer-subsidized programs in Seoul, Tokyo, and Singapore are bypassing retail channels for direct OEM contracting.
- Outdoor Enthusiasts:Hunters, anglers, and campers demand ruggedized shells and active-cooling integration. Yeti leverages premium thermal engineering across North American specialty retail.
- Families:Multi-user systems with color-coded containers reduce cross-contamination risk. Indian and Chinese extended-family structures favor stackable modular architectures.
Professionals generate the steepest expansion trajectory; families retain the largest installed base.
Feature:
Certification-grade attributes command margin premiums while baseline functionality competes on unit economics.
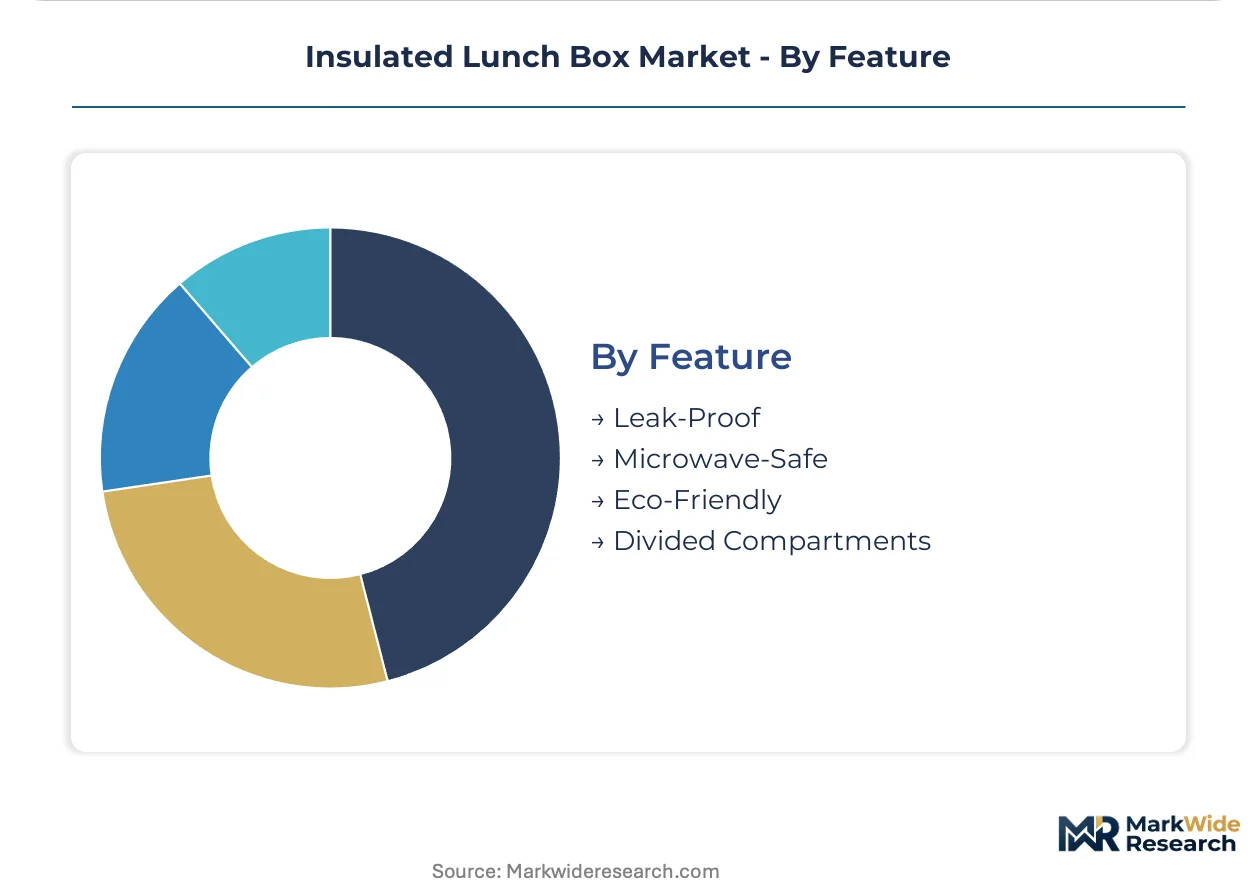
- Leak-Proof:Silicone-gasket sealing systems and locking latches prevent liquid migration during multi-modal commutes. REACH-compliant adhesive bonding is eliminating solvent-based alternatives from European production.
- Microwave-Safe:Borosilicate glass and BPA-free polymer containers enable in-office reheating without vessel transfer. Japanese regulatory alignment with FDA migration limits accelerates cross-border qualification.
- Eco-Friendly:Bio-based insulation foams and recycled stainless steel respond to EU packaging-waste directives. Mycelium and starch-foam alternatives require capital-intensive pilot lines with uncertain offtake.
- Divided Compartments:Modular tray systems separate proteins, carbohydrates, and sauces to preserve texture. Parents in US and European markets absorb 15-25% price premiums for portion-control convenience.
Leak-proof engineering anchors purchase decisions today; eco-friendly certification is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuting professionals in metropolitan India and China anchor regional demand concentration. European regulatory pressure through REACH and the EU Green Deal redirects supply chains toward bio-based alternatives. North American outdoor recreation channels sustain premium-tier thermal engineering investments.
United States
Corporate wellness programs and hybrid work normalization sustain professional-grade procurement volumes. FDA food-contact material regulations govern polymer safety standards for domestic manufacturing. Outdoor retail channels in Colorado and the Pacific Northwest concentrate premium thermal-engineering distribution.
China
SAMR enforces GB standards for plastic migration limits that shape export compliance burdens for Asian suppliers. Metropolitan commuter corridors in Beijing, Shanghai, and Shenzhen absorb vacuum-insulated stainless-steel assemblies as daily travel times extend. Pearl River Delta manufacturing clusters face polyurethane foam substitution pressures from EU-bound export requirements.
India
Metro expansions in Mumbai, Bangalore, and Delhi elevate thermal retention from convenience to necessity for working professionals. FSSAI food-contact material regulations remain misaligned with EU migration limits, blocking export qualification for domestic fabricators. Fabric-based soft-sided production concentrates in Tamil Nadu and Gujarat for multi-modal commuter portability.
Germany
REACH Annex XVII restrictions on persistent organic pollutants in adhesives eliminate solvent-based bonding agents from Continental production. ECHA compliance documentation requirements compress margin structures for children's segment suppliers. Industrial-design consultancies in Bavaria and Baden-Württemberg concentrate finite-element analysis capability for multi-layer barrier engineering.
Japan
METI standards alignment with FDA migration limits accelerates cross-border qualification for borosilicate glass manufacturers. Kanto and Kansai commuter corridors prioritize microwave-safe convenience for office environments. Osaka-based chemical houses maintain captive supply positions for proprietary phase-change gel materials.
Insulated Lunch Box Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Structure fragments across premium thermal-engineering, mid-market fabric, and entry-level plastic construction formats. Three archetypes dominate: outdoor-recreation heritage brands, commuter-focused design houses, and contract manufacturers serving private-label retail. Capacity expansion and geographic licensing represent the dominant competitive moves as regulatory compliance costs reshape viable scale thresholds.
Within the heritage outdoor-recreation tier, Yeti exemplifies premium thermal-engineering positioning through North American specialty retail channels. PackIt occupies a distinct technology-driven position through proprietary freezable gel-wall systems that eliminate separate ice packs. Bentgo anchors the children's segment archetype with compartmentalized designs that simplify parent purchasing decisions in US and European markets. These three represent divergent strategic vectors: performance engineering, integrated cooling technology, and portion-control convenience.
| Leading Market Players |
|---|
| CleverMade |
| Black + Blum |
| Yeti |
| PlanetBox |
| Tatay |
| PackIt |
| L.L. Bean |
| Bentgo |
| Pottery Barn Kids |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators in Tamil Nadu and Gujarat anchor soft-sided production, their generational control over loom capacity and finishing workshops enabling pricing discipline that resists margin erosion despite polyester input volatility. This ownership structure concentrates supply-side bargaining power while insulating contract rates from quarterly earnings pressure faced by publicly traded competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates stainless-steel vacuum assemblies with certification documentation from bare-bones fabric liners lacking thermal-performance guarantees. Pricing stratifies across premium, standard, and economy tiers where copper-lined barriers and REACH-compliant adhesive bonding command 40-60% markups over solvent-laminated alternatives. Cost compression in entry-level plastic formats is intensifying because Guangdong contract manufacturers face EU Green Deal phase-out timelines. Corporate wellness programs in Seoul and Tokyo show least price sensitivity; Indian commuter corridors exhibit highest elasticity.
Supply Chain Analysis
Certification/qualification gating through REACH Annex XVII and FDA food-contact material standards fragments supplier viability across compliance tiers. Manufacturing gravity centers on China, India, and Vietnam, with Pearl River Delta clusters feeding export demand and Tamil Nadu workshops serving domestic Indian portability needs. Raw material flows draw from benzene derivative markets for expanded polystyrene, Japanese chemical houses for proprietary phase-change gels, and copper sheet suppliers for vacuum-insulated barriers. Single-source concentration for freezable gel materials creates force-majeure allocation exposure. Distribution runs through outdoor specialty retail in North America, direct-to-employer contracting in East Asian metropolitan corridors, and multi-brand general trade across Indian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated lunch box market reads as a late-cycle quality story, with professional consumers in metropolitan China and urban India absorbing premium pricing for vacuum-insulated stainless-steel assemblies as hybrid work normalizes daily meal-prep routines.
For Market Incumbents: To counter biodegradable insulation scale-up risks, prioritize captive supply of mycelium and starch-foam pilot capacity in EU-adjacent manufacturing zones, while securing ECHA pre-certification for water-based polyurethane dispersion bonding agents ahead of Annex XVII enforcement waves. For New Entrants and Emerging Players: The price-point gap between vacuum-insulated premium tier and collapsible fabric economy tier creates white-space opportunity in medium-format microwave-safe borosilicate systems for Japanese and South Korean office corridors. Target employer-subsidized procurement channels in Singapore and Seoul with modular tray architectures that bypass retail margin stacking. For Investors and Strategic Acquirers: Valuations sit cheapest among fabric-based soft-sided specialists with underdeveloped certification documentation and limited EU market access. Long-term viability hinges on regulatory alignment capabilities across REACH, FDA, and FSSAI migration limits. Watch for FSSAI-EU harmonization announcements as inflection signal unlocking export qualification for Indian stainless-steel fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Adhesive Transition | ECHA documentation requirements compress margin structures for children's segment suppliers. |
| Vacuum-Insulated Capacity Expansion | Copper-lined barrier assembly investments capture professional segment pricing power in Shenzhen. |
| Direct-to-Employer Contracting | Corporate wellness programs in Seoul and Tokyo bypass retail channels for volume frameworks. |
| Bio-Based Insulation Pilot Lines | Mycelium and starch-foam alternatives require capital-intensive depreciation schedules matched to uncertain offtake. |
| FSSAI Export Qualification | Indian regulatory alignment with EU migration limits would unlock European market access for domestic fabricators. |
Methodological Framework
Bottom-up professional consumer modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with supply chain managers at Guangdong contract manufacturers, procurement leads at South Korean chaebol wellness programs, regulatory affairs specialists at German industrial-design consultancies, and category buyers at North American outdoor retail channels were cross-validated against secondary sources including SAMR GB standard filings, ECHA REACH registration databases, Indian customs export records, and Japanese METI technical standard notifications.
Historical trendline analysis across material substitution cycles and commuter-density patterns informed the projection framework. Segmentation dimensions modeled include construction format, thermal-performance tier, target consumer archetype, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and input-cost trajectory assumptions. Forecast inputs incorporated hybrid work normalization patterns, metro expansion timelines in Mumbai and Bangalore, and EU Green Deal implementation pacing.
The model assumes a particular technology adoption path; alternative pathways for active-cooling solar-charged systems in Sub-Saharan African corridors would alter the outlook. Forecasts reflect assumptions around REACH compliance consolidation rates and petrochemical input stability. A model refresh is warranted upon material change in FSSAI-EU regulatory harmonization announcements or phase-change gel supply allocation disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Integrated Smart Toilet Market
Household Items
Ironing Boards Market
Household Items
Germany Digital Showers Market
Household Items
Global Electric Scissors Market
Household Items
United States Smart Shower Market
Household Items
Cast Iron Cookware Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Drinkware Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Brazil Cookware Market
Household Items
Facial Tissue Paper Market
Household Items
Book Light Market
Household Items
Ultrasonic Diffusers Market
Household Items
Manual Bottle Opener Market
Household Items
Air Mattress Market
Household Items
Japan Digital Showers Market