
 Fuel and Convenience Store POS Market | 2026-2036
Fuel and Convenience Store POS Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel and Convenience Store POS Market Analysis
Cloud-native architecture is tilting the technology stack away from monolithic on-premise systems toward API-first platforms that integrate fuel pumps, loyalty engines, and back-office analytics in real time. NCR Corporation leverages its installed base of petroleum retailers to sustain recurring software revenue. Verifone anchors its position through payment terminal specialization at high-volume fuel stations. Gilbarco Veeder-Root dominates the forecourt controller layer, extending hardware-software bundling that competitors struggle to replicate.
Fuel and convenience store point-of-sale systems encompass hardware peripherals, transaction processing software, and payment terminals engineered to withstand petroleum vapors, temperature extremes, and continuous uptime demands exceeding 99.5% availability. Cloud-based deployment is outpacing on-premise installations as distributed fuel chains prioritize centralized inventory visibility across hundreds of sites. Mobile POS represents the fastest-expanding product type, though payment terminals still capture the dominant margin pool due to EMV certification barriers and processor exclusivity agreements. Hardware remains mature with compressed margins, while technical support services generate sticky recurring revenue that software vendors increasingly target.
PCI DSS standards govern payment data security, while NIST frameworks influence federal procurement criteria for critical retail infrastructure. State-level weights-and-measures regulators enforce pump-to-register accuracy mandates that shape hardware replacement timelines. Stakeholders must monitor how open-banking APIs and real-time payment rails alter processor relationships before committing to multi-year terminal leases.
Market Dynamics
Cloud-native architecture is compressing replacement cycles as independent fuel retailers abandon decade-old on-premise terminals for API-first platforms that unify forecourt controllers, loyalty engines, and real-time inventory visibility across distributed sites.
Growth Catalysts
- EMV compliance mandates:United States payment networks enforce chip-card acceptance at fuel pumps, forcing hardware refreshes that accelerate terminal replacement timelines and expand addressable market for certified vendors.
- Consolidation of convenience store chains:Large multi-site operators in the United States standardize POS infrastructure across acquired locations, creating bulk procurement opportunities that favor integrated platform providers.
- Edge computing architectures:Distributed processing at fuel islands enables sub-second transaction authorization and offline continuity during network interruptions, reducing downtime penalties for high-volume retailers.
Market Restraints
- Semiconductor supply concentration:Payment terminal chipsets depend on concentrated Asian foundry capacity, exposing hardware vendors to allocation delays and input cost volatility during supply shocks.
- Petroleum vapor certification requirements:Underwriters Laboratories and equivalent national safety bodies impose extended testing protocols for forecourt electronics, lengthening product development timelines and freezing out unqualified competitors.
- Processor exclusivity agreements:Acquiring banks lock fuel retailers into multi-year terminal leases with penalty clauses, constraining switching behavior and limiting competitive displacement.
Strategic Opportunities
- Electric vehicle charging integration:POS platforms that unify fuel and EV payment workflows capture emerging hybrid forecourt operators seeking single-vendor simplicity for mixed-energy retail.
- Real-time payment rail adoption:FedNow and equivalent instant settlement systems in the United States enable fuel retailers to reduce working capital tied up in authorization holds, creating preference for compatible terminal infrastructure.
- Computer vision at self-checkout:C-store operators deploy camera-based loss prevention and age-verification automation, opening attach-rate opportunities for POS vendors with integrated peripheral ecosystems.
Industry Challenges
- Legacy system integration complexity:Petroleum retailers operate heterogeneous back-office platforms accumulated through decades of site acquisitions, forcing costly middleware development to achieve cloud connectivity.
- PCI DSS compliance talent scarcity:Qualified security assessors and certified payment application developers command premium compensation, constraining vendor scaling and extending implementation timelines for complex deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel and Convenience Store POS Market |
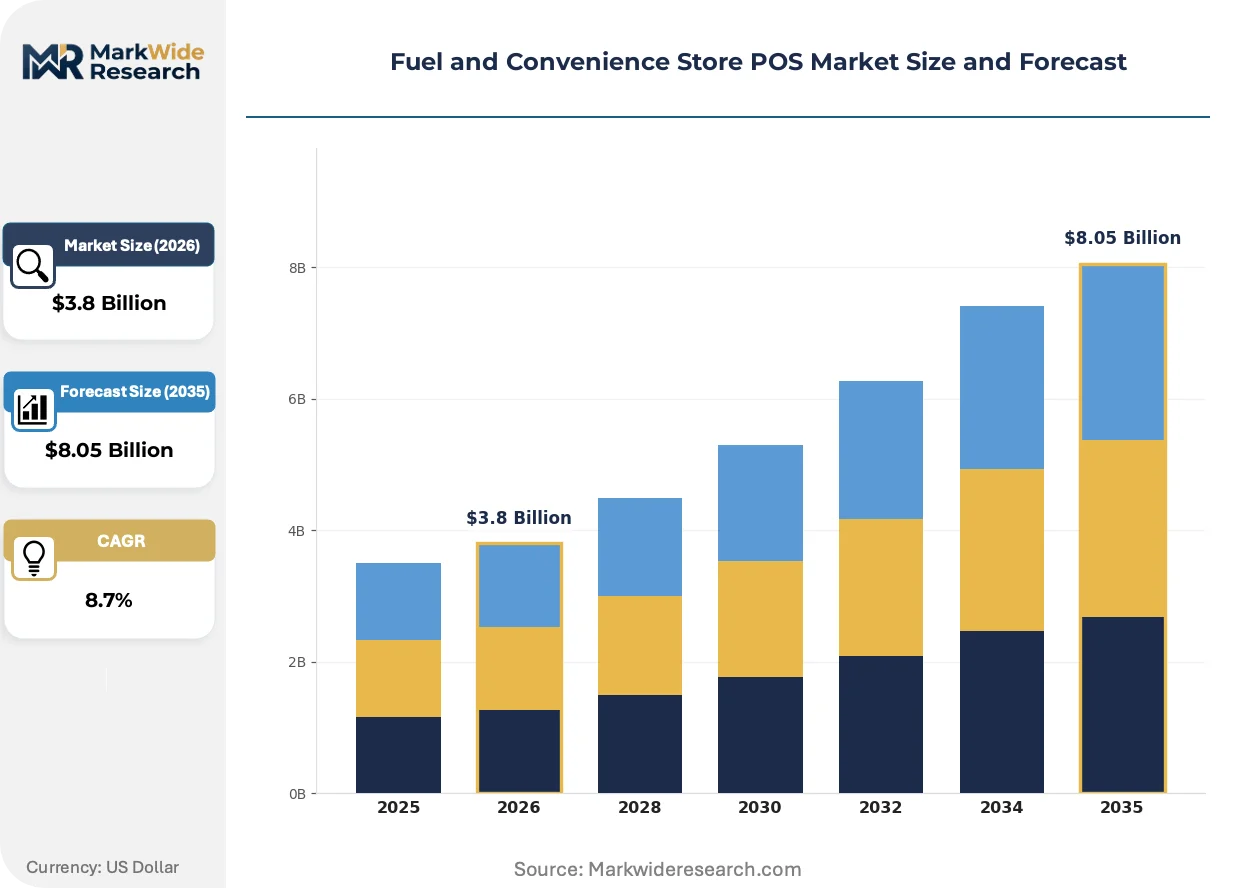
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Payment Terminal, Mobile POS Deployment: On-Premise, Cloud-Based, Hybrid, Terminal-Based End User: Independent Retailers, Supermarkets, Fuel Stations, Franchises Service Type: Installation, Maintenance, Technical Support, Consulting |
| Companies Covered | NCR Corporation, Verifone, Gilbarco Veeder-Root, Square, Clover Network, Fujitsu Limited, Oracle, PDI Technologies, LS Retail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel and Convenience Store POS Market Emerging Trajectories
Software-defined infrastructure is dissolving the boundary between transaction processing, loyalty management, and forecourt control, enabling petroleum retailers to operate unified commerce stacks previously segmented across incompatible vendor silos.
Containerized POS software is virtualizing the traditional terminal hardware stack, allowing fuel retailers to run payment applications on commodity edge devices while maintaining EMV certification through hardware security module abstraction. Mid-size convenience store chains in the United States are piloting this architecture to reduce per-site capital expenditure and accelerate feature deployment through over-the-air updates. The shift is compressing margins for dedicated terminal manufacturers while expanding recurring software revenue pools for platform orchestrators.
State-level weights-and-measures regulators in the United States are tightening pump-to-register accuracy audit frequencies, mandating tamper-evident digital seals and automated calibration logging that reshape hardware replacement specifications. Vendors must now engineer forecourt controllers with immutable audit trails and remote attestation capabilities to satisfy enforcement regimes in California, Texas, and Florida. Compliance investments are favoring incumbent suppliers with established regulatory relationships over new market entrants lacking certification heritage.
Subscription-based hardware provisioning is displacing capital purchase models as fuel retailers prioritize operational expenditure predictability over ownership. Fleet operators and franchisee networks in the United States are adopting terminal-as-a-service contracts that bundle devices, software licenses, and technical support into per-transaction fees. This reconfiguration transfers obsolescence risk to vendors and accelerates refresh cycles by aligning contract durations with certification expiration timelines rather than depreciation schedules.
Fuel and Convenience Store POS Market Segmentation
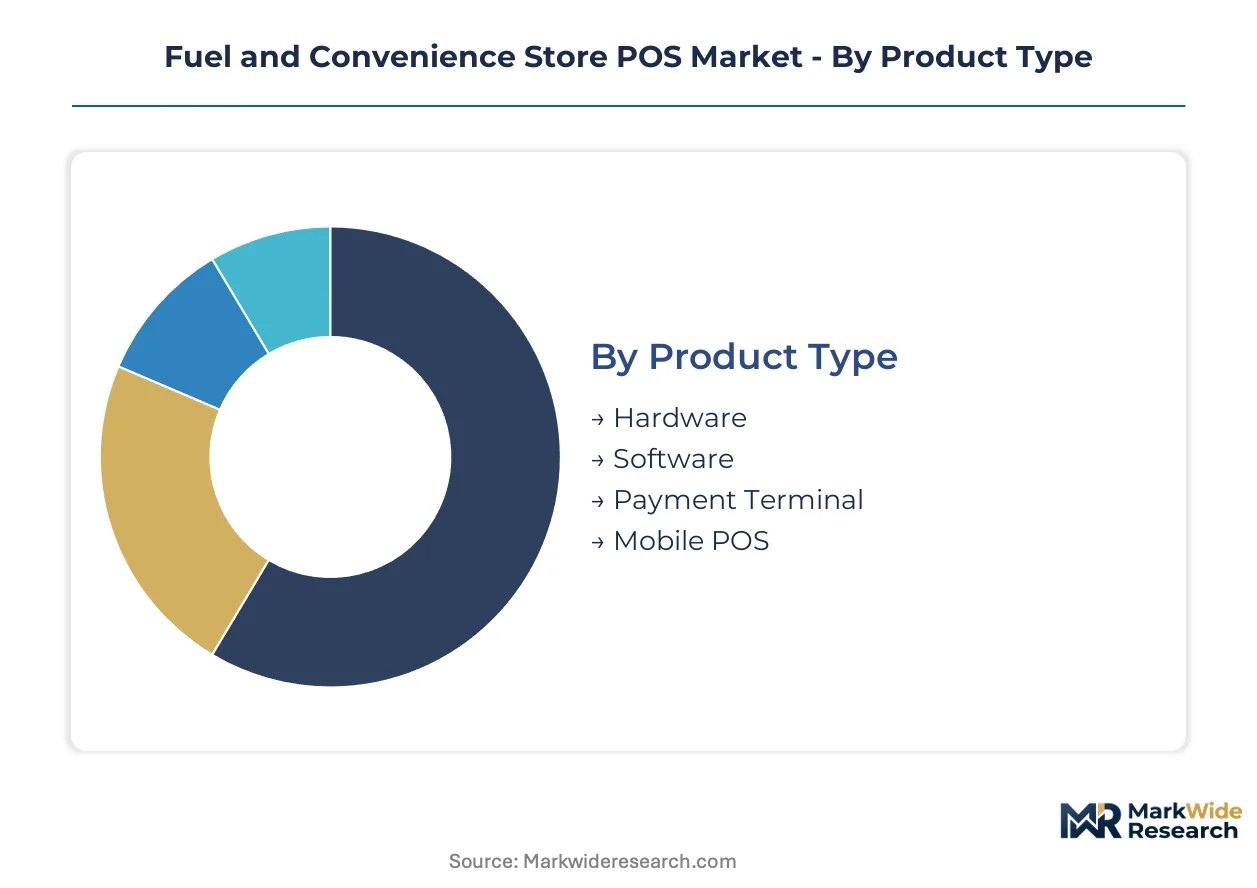
Fuel and convenience store POS systems fragment across four distinct dimensions that shape procurement priorities and vendor positioning. Each segmentation layer reflects different buyer economics, from capital-intensive hardware purchases to recurring software subscriptions and service dependencies.
Product Type:
Forecourt operators select from four product categories spanning physical infrastructure, application layers, and transaction endpoints.
- Hardware:Ruggedized terminals, forecourt controllers, and peripheral devices engineered to withstand petroleum vapors, temperature extremes, and continuous operation exceeding 99.5% availability. Demand concentrates among United States independent fuel retailers upgrading decade-old installations to meet EMV compliance deadlines at pumps and registers.
- Software:Transaction processing engines, loyalty management platforms, and back-office analytics delivered through cloud-native or on-premise architectures. Large multi-site operators in the United States prioritize API-first platforms that unify inventory visibility across hundreds of distributed locations.
- Payment Terminal:EMV-certified devices handling chip-card, contactless, and mobile wallet transactions at fuel islands and c-store counters. Processor exclusivity agreements in North America constrain switching behavior and extend replacement cycles tied to certification expiration timelines.
- Mobile POS:Tablet and smartphone-based transaction systems enabling curbside payment, line-busting, and temporary checkout expansion. Franchise networks pilot these deployments to reduce per-site capital expenditure while maintaining payment flexibility.
The dominant share belongs to Hardware, while Mobile POS is closing the gap fastest.
Deployment:
Architecture choices determine capital structure, operational control, and upgrade velocity for petroleum retailers.
- On-Premise:Legacy systems installed and managed at individual fuel sites with localized data storage and processing. Independent retailers in rural United States markets retain these installations due to unreliable broadband infrastructure and preference for physical control over transaction data.
- Cloud-Based:Centralized platforms delivering software updates, security patches, and feature deployments through internet connectivity. Consolidated convenience store chains across the United States standardize on this model to achieve real-time inventory synchronization across acquired locations.
- Hybrid:Architectures combining local transaction processing with cloud-connected analytics and management layers. Fuel stations in bandwidth-constrained regions deploy edge computing nodes that maintain offline continuity during network interruptions.
- Terminal-Based:Dedicated payment devices with embedded software stacks and hardware security modules. Petroleum vapor certification requirements from Underwriters Laboratories favor established vendors with extended testing protocols and regulatory relationships.
Cloud-Based deployments are expanding most quickly, though Terminal-Based systems retain the largest installed base.
End User:
Buyer segmentation reveals divergent procurement scales, technical sophistication, and vendor relationship expectations.
- Independent Retailers:Single-site or small-chain fuel operators with limited IT staff and preference for bundled hardware-software-support packages. These buyers in the United States drive replacement cycles through regulatory compliance mandates rather than competitive differentiation goals.
- Supermarkets:Grocery chains operating fuel islands as traffic drivers and loyalty program anchors. Their procurement emphasizes integration with existing retail POS infrastructure and unified customer data platforms across fuel and grocery operations.
- Fuel Stations:Dedicated petroleum retailers ranging from branded dealerships to unbranded independents. EMV compliance deadlines and weights-and-measures accuracy requirements in California, Texas, and Florida shape their hardware refresh priorities.
- Franchises:Networked operators balancing corporate standardization mandates with franchisee capital constraints. Terminal-as-a-service contracts appeal to these buyers by transferring obsolescence risk to vendors and converting capital expenditure to operational expenditure.
Fuel Stations command the dominant share, while Franchises are gaining share fastest through network expansion and standardization mandates.
Service Type:
Post-sale service layers generate recurring revenue streams and create switching costs that cement vendor relationships.
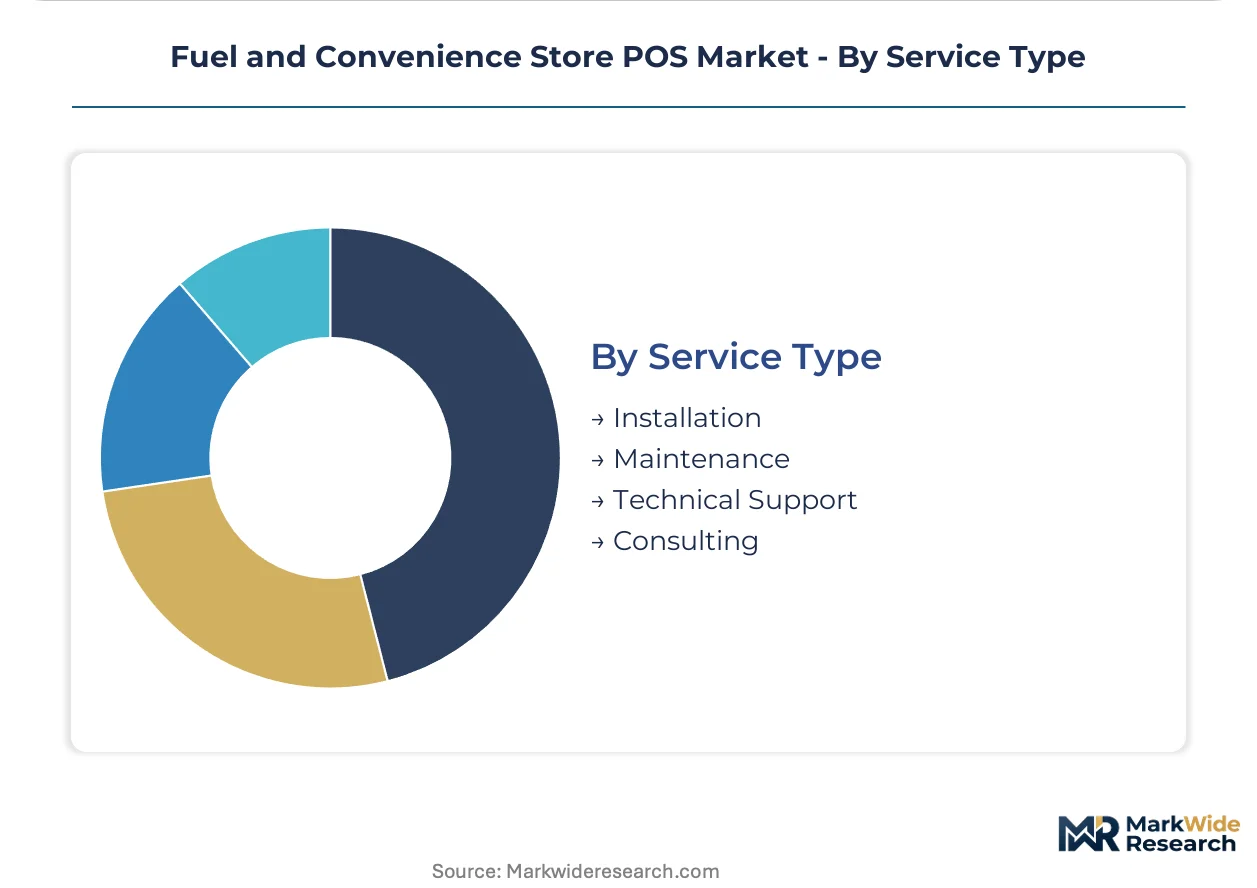
- Installation:Site preparation, hardware deployment, software configuration, and initial certification testing. PCI DSS compliance requirements and petroleum vapor safety protocols extend implementation timelines and favor vendors with qualified security assessor relationships.
- Maintenance:Preventive servicing, component replacement, and firmware updates preserving operational availability. Fuel retailers in high-volume United States markets prioritize response time guarantees to minimize downtime penalties during peak traffic periods.
- Technical Support:Helpdesk services, remote diagnostics, and on-site troubleshooting delivered through subscription contracts. Qualified payment application developers command premium compensation, constraining vendor scaling and extending resolution timelines for complex deployments.
- Consulting:Strategic advisory on platform selection, integration architecture, and compliance roadmap planning. Multi-site operators engaging in consolidation activity leverage these services to rationalize heterogeneous back-office platforms accumulated through decades of acquisitions.
Technical Support captures the dominant share, while Consulting is climbing the fastest as consolidation accelerates platform rationalization projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-site fuel retailers and convenience store consolidators dominate procurement across mature markets, while independent operators in emerging economies drive replacement cycles through regulatory compliance mandates rather than competitive differentiation.
United States
EMV compliance deadlines at fuel pumps and convenience store registers accelerate hardware refresh timelines for petroleum retailers. State-level weights-and-measures regulators in California, Texas, and Florida enforce pump-to-register accuracy mandates with automated calibration logging. The Dallas-Fort Worth metroplex hosts concentrated deployment of cloud-connected forecourt controllers as regional fuel chains standardize infrastructure across acquired locations.
Canada
Payment terminal replacement concentrates among independent fuel retailers upgrading legacy systems to meet chip-card acceptance requirements. Health Canada and Measurement Canada coordinate safety and accuracy certification protocols for forecourt electronics. The Alberta oil corridor sees sustained demand for ruggedized POS hardware engineered to withstand temperature extremes and petroleum vapor exposure at high-volume truck stops.
Germany
Automotive-focused retail technology investments align with the country's advanced fuel station automation standards. KBA and federal weights-and-measure authorities enforce stringent pump calibration and data logging requirements. The Rhine-Ruhr industrial cluster drives adoption of integrated loyalty-and-payment platforms as supermarket fuel islands expand market share.
United Kingdom
Forecourt operators modernize POS infrastructure to support contactless and mobile wallet adoption at fuel islands and c-store counters. FCA payment regulations and HMRC fuel duty tracking requirements shape hardware specifications. The Southeast England logistics corridor sees concentrated deployment of edge-computing terminals enabling offline transaction continuity during network interruptions.
Australia
Remote fuel stations prioritize hybrid cloud-terminal architectures maintaining operational continuity across bandwidth-constrained outback regions. The national measurement institute enforces pump accuracy standards with increasing audit frequency. The Perth mining hinterland drives specialized demand for mobile POS enabling curbside payment at isolated fleet refueling depots.
Fuel and Convenience Store POS Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated platform orchestrators bundling hardware-software-support, payment terminal specialists leveraging EMV certification barriers, and regional system integrators serving independent fuel retailers. Strategic moves concentrate on cloud-native architecture transitions and subscription-based hardware provisioning models transferring obsolescence risk to vendors.
Within the integrated platform tier, NCR Corporation and Oracle occupy positions exemplifying petroleum retail technology consolidation, while Verifone anchors the payment terminal specialization vector through EMV-certified device ecosystems. Gilbarco Veeder-Root represents the forecourt controller hardware-software bundling archetype that competitors struggle to replicate against petroleum vapor certification requirements.
| Leading Market Players |
|---|
| NCR Corporation |
| Verifone |
| Gilbarco Veeder-Root |
| Square |
| Clover Network |
| Fujitsu Limited |
| Oracle |
| PDI Technologies |
| LS Retail |
| Others |
Supply Flow & Price Mechanics
The Port of Long Beach logistics corridor shapes cost dynamics across Fuel and Convenience Store POS hardware procurement, where semiconductor freight surcharges from concentrated Asian foundries amplify price differentiation between certified terminal manufacturers and commodity peripheral suppliers.
Pricing Analysis
Cost-plus contracts with quarterly semiconductor indexation dominate terminal procurement between acquiring banks and hardware vendors. Three-tier pricing structure across premium, standard, and economy levels segments by EMV certification tier and petroleum vapor safety ratings from Underwriters Laboratories. Pricing pressure stems from subscription-based hardware provisioning transferring obsolescence risk to vendors. Independent retailers exhibit highest price sensitivity, while consolidated multi-site operators prioritize integration reliability over unit economics.
Supply Chain Analysis
Upstream feedstock for payment terminal chipsets draws from Taiwan, South Korea, and mainland China foundry capacity. ARM-based processors, hardware security modules, and petroleum-resistant enclosure polymers constitute critical component dependencies. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through processor exclusivity agreements that lock fuel retailers into multi-year terminal leases with penalty clauses constraining competitive displacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
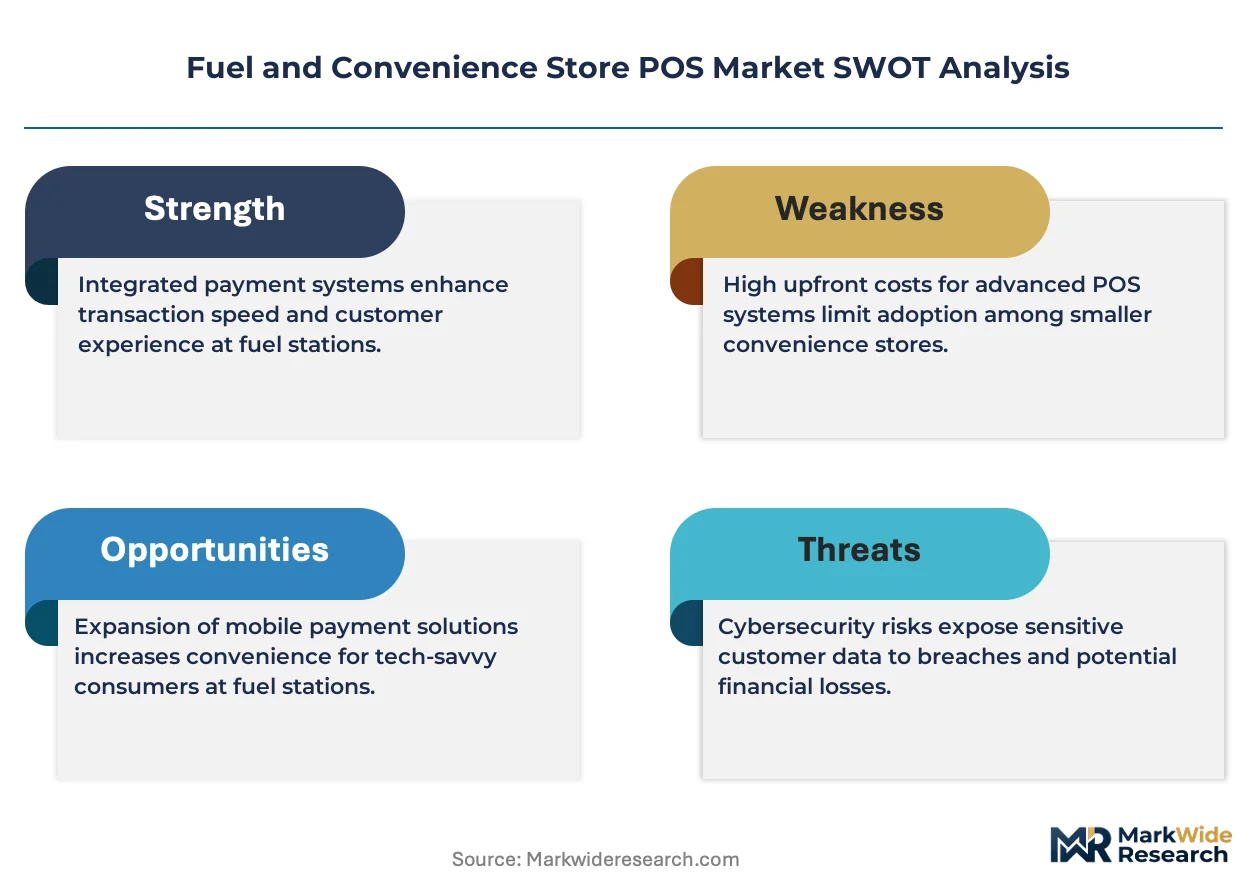
Payment facilitator platforms and smartphone-based tap-to-pay applications threaten traditional POS terminal incumbents by circumventing EMV certification barriers through software abstraction.
For Market Incumbents: Build regulatory certification moats through accelerated petroleum vapor safety testing protocols and state-level weights-and-measures pre-certification relationships. Deepen backward integration into hardware security module design to offset semiconductor allocation volatility. Anchor cloud-native platform stickiness via API-first loyalty engine integrations that increase switching costs for consolidated fuel chains. For New Entrants and Emerging Players: Build out containerized POS software deployments targeting mid-size convenience store chains seeking to virtualize terminal hardware onto commodity edge devices. Target franchise networks with terminal-as-a-service contracts converting capital expenditure to operational expenditure. Pursue electric vehicle charging integration as the go-to-market wedge for hybrid forecourt operators seeking unified payment workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from petroleum equipment conglomerates seeking to divest non-core POS software divisions amid corporate restructuring. Long-term viability hinges on recurring software revenue multiples exceeding hardware margin compression trajectories. Watch FedNow real-time payment rail adoption rates as the inflection signal for terminal infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | API-first architectures unify forecourt controllers with loyalty engines for consolidated fuel chains. |
| EMV Certification Acceleration | Pre-certified hardware modules compress deployment timelines for independent retailers facing compliance deadlines. |
| Terminal-as-a-Service Provisioning | Subscription models transfer obsolescence risk from franchise networks to vendor balance sheets. |
| EV Charging Payment Integration | Unified workflows capture hybrid forecourt operators managing mixed-energy retail infrastructure. |
| Edge Computing Node Deployment | Distributed processing enables offline transaction continuity at bandwidth-constrained rural fuel stations. |
Methodological Framework
A standing panel of petroleum retail technology executives, payment processor partnership directors, convenience store chain IT procurement officers, and state weights-and-measures enforcement officials provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from SEC filings of publicly traded POS vendors, PCI DSS certification databases, and petroleum equipment trade association shipment reports. Bottom-up site-level demand estimation triangulated against top-down vendor revenue aggregation across the analysis window.
Scenario-bracketing anchored the analytical framework, with growth trajectories modeled across product type, deployment architecture, end-user scale, and regional regulatory cluster dimensions. CAGRs derived from segment-level elasticity coefficients applied to baseline penetration rates. Forecast inputs incorporated EMV compliance deadline schedules, convenience store consolidation velocity, and real-time payment rail adoption curves without binding to specific calendar years.
Sensitivities concentrate around semiconductor supply allocation shocks, petroleum vapor certification protocol changes, and open-banking API standardization timelines. Cross-checking against PCI DSS certified device deployment databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Slovakia POS Terminal Market
Payments
Wearable Payments Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Global Accounts Payable Automation Market
Payments
United States POS Terminals Market
Payments
Cross-Border Payment Platform Market
Payments
Retail POS Terminals Market
Payments
Global Wearable Payment Device Market
Payments
Germany Payment Gateway Market
Payments
Canada Buy Now Pay Later Market
Payments
Spain POS Terminals Market
Payments
South Korea Digital Payments Market
Payments
Global Payments As a Service Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Proximity Mobile Payment Market
Payments
Spain Mobile Payment Market