
 Mpos Terminals Market | 2026-2036
Mpos Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Mpos Terminals Market Analysis
PCI DSS compliance is consolidating the vendor landscape by forcing smaller hardware makers to absorb certification costs or exit. Square leverages its integrated software-hardware stack to anchor merchant retention across North American micro-businesses. PAX Technology competes aggressively on manufacturing scale, shipping EMV-certified devices to European acquirers at compressed margins. Ingenico sustains channel control through direct banking partnerships in France, Germany, and Italy.
MPOS terminals are compact, wireless payment acceptance devices that pair with smartphones or tablets via Bluetooth or audio jack, typically incorporating EMV chip readers, NFC antennas, and magnetic stripe heads to process card-present transactions for mobile merchants. The hardware serves commercial users requiring point-of-sale capability without fixed infrastructure, such as market vendors, delivery fleets, and pop-up retailers. Portable terminals lead volume shipments due to their battery-operated form factor suited for tableside hospitality and curbside retail, while cloud-based deployment configurations capture expanding margin pools as payment-as-a-service models displace perpetual-license software. NFC technology segments are gaining fastest penetration as dual-interface cards and wallet-enabled phones displace magnetic stripe acceptance at merchant locations.
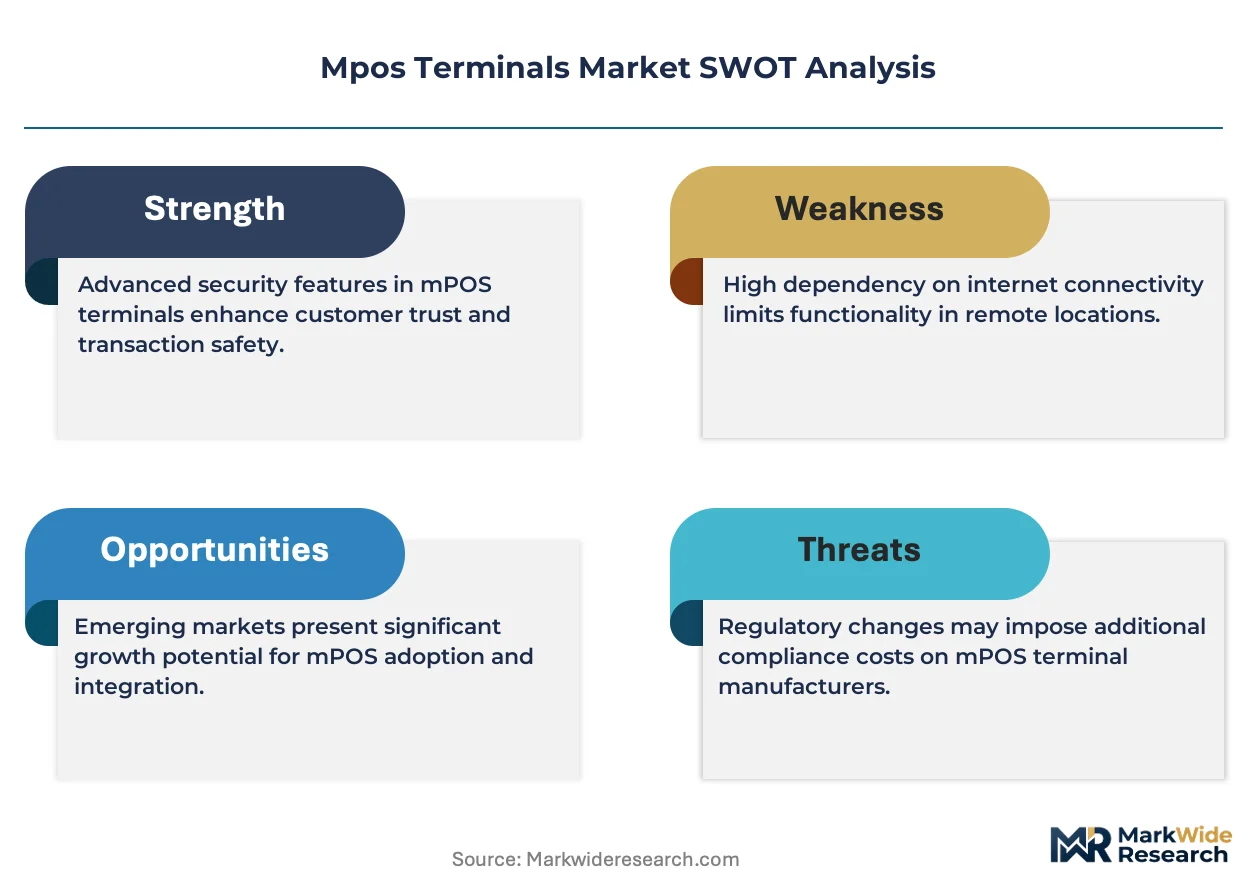
FCC certification governs radio-frequency emissions for MPOS devices sold in the United States, while the EU's Radio Equipment Directive and GDPR impose concurrent hardware safety and transaction data handling requirements across European markets. India's BIS mandatory certification for electronic payment devices adds a compliance layer that filters non-local assembly entrants from government-procured terminal rollouts. Stakeholders must weigh regulatory fragmentation against platform consolidation as acquirers bundle hardware subsidies with processing contracts.
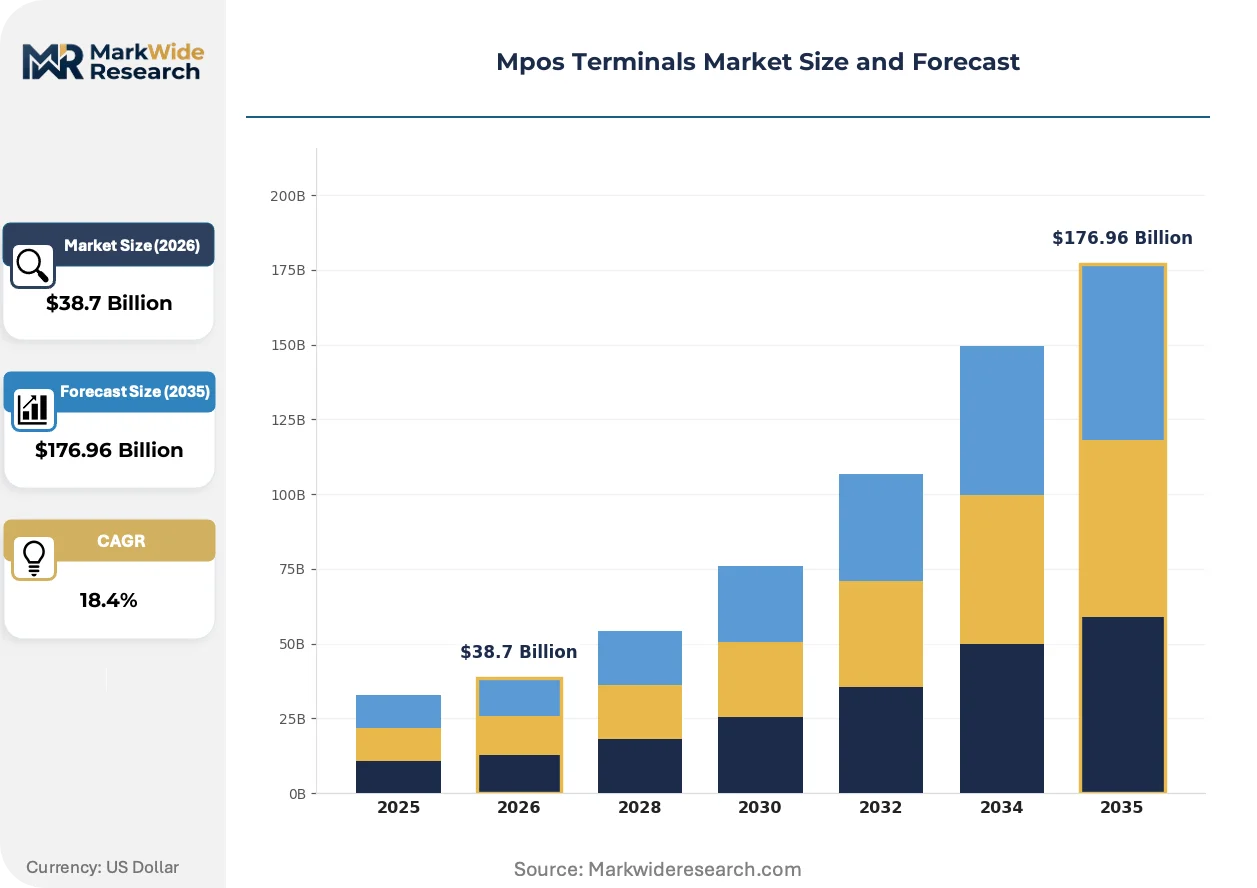
Market Dynamics
Payment-as-a-service models are compressing hardware margins while locking merchants into integrated software ecosystems, forcing terminal vendors to subsidize devices through recurring revenue streams rather than upfront sales.
Growth Catalysts
- RBI Digital Push:India's central bank mandates for merchant payment digitization are converting cash-dependent small retailers to smartphone-connected card acceptance. Street vendors and kirana stores now constitute the fastest-expanding addressable base.
- Contactless NFC Mandates:Dual-interface card issuance and wallet-enabled smartphone proliferation are rendering magnetic stripe infrastructure obsolete. Pharmacies and clinics in Brazil adopted touch-free protocols under ANVISA-aligned health standards.
- Cloud Deployment Architectures:Perpetual-license software is yielding to subscription-based terminal management. Acquirers bundle real-time analytics and inventory integration to deepen merchant stickiness.
Market Restraints
- PCI DSS Certification Burden:Compliance costs for hardware security modules and firmware attestation are forcing smaller original design manufacturers to exit or sell to consolidated platforms.
- Semiconductor Supply Concentration:NFC controller chips and secure elements depend on concentrated Asian foundry capacity. Terminal vendors face allocation priority tiers from component suppliers.
- Magnetic Stripe Infrastructure:Legacy card acceptance remains entrenched in rural and developing markets, delaying full EMV migration and fragmenting hardware requirements.
Strategic Opportunities
- Sub-Saharan Africa Underpenetration:Mobile money interoperability with card rails presents white space for Bluetooth-enabled terminals. Kenya and Nigeria's agent banking networks lack sufficient point-of-sale hardware density.
- SoftPOS Convergence:Near-field communication antennas embedded in standard smartphones are eliminating dedicated hardware for micro-merchants. Android-based acceptance apps are compressing entry costs toward zero.
- EU Digital Identity Wallets:The eIDAS 2.0 framework mandates payment credential integration with government-issued digital identities. Terminal vendors can capture authentication infrastructure upgrades.
Industry Challenges
- Firmware Security Talent Scarcity:Secure boot implementation and cryptographic key injection require specialized embedded systems expertise. Vendors compete for limited penetration testing and threat modeling professionals.
- Multi-Jurisdiction Certification Timelines:FCC, CE marking, BIS, and ANATEL approvals run sequentially rather than in parallel. Product launches face 14-18 month validation cycles.
- Legacy POS Integration Complexity:Estate refresh programs require middleware development for property management systems and loyalty platforms. Hospitality chains demand seamless migration without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mpos Terminals Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminal, Portable Terminal, Mobile Terminal, Integrated POS Technology: Chip & Pin, NFC, Magnetic Stripe, Contactless Payment End User: Retail, Hospitality, Transportation, Healthcare Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Square, VeriFone, PAX Technology, Ingenico, Fiserv, PayPal, Samsung Electronics, Adyen, SumUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mpos Terminals Market Emerging Trajectories
Biometric authentication modules and edge-computing transaction processing are redefining terminal architecture, shifting security verification from centralized servers to device-local neural networks.
SoftPOS technology is electrifying merchant acquisition economics by converting standard NFC-enabled smartphones into payment terminals without additional hardware. Food delivery platforms and gig economy marketplaces are deploying this capability to onboard drivers and couriers at marginal cost near zero. The structural consequence is electrifying terminal commoditization, compressing dedicated hardware to high-volume, high-risk, or offline-capable use cases.
The EU's Radio Equipment Directive and GDPR impose concurrent hardware safety and transaction data sovereignty requirements across member states. Terminal vendors must implement data residency controls and pseudonymization protocols that increase firmware complexity. French and German acquirers are responding by consolidating vendor lists to those with dedicated EU-based secure element provisioning facilities.
Merchant buying patterns now favor bundled hardware subsidies tied to minimum processing commitments rather than capital expenditure ownership. Independent software vendors and payment facilitators are disintermediating traditional distribution through direct-to-merchant onboarding portals. This shift is most visible in North American micro-business segments where Square and Shopify have captured significant terminal placement volume through software-led acquisition funnels.
Mpos Terminals Market Segmentation
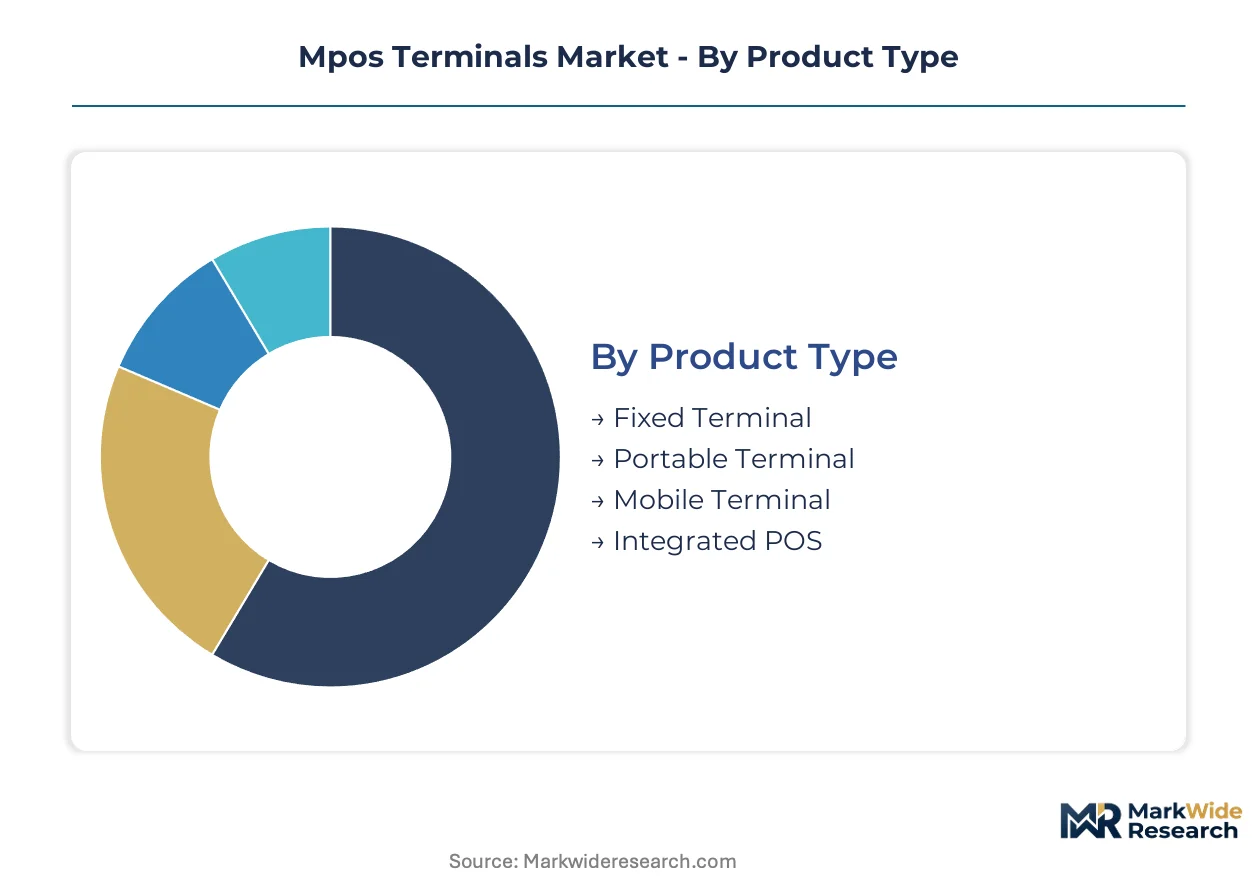
MPOS terminal purchasing decisions hinge on mobility requirements, transaction security protocols, and integration complexity with existing merchant systems. Vendors align product roadmaps across four structural dimensions that determine hardware specifications, certification burdens, and recurring revenue potential.
Product Type:
Merchant mobility requirements and infrastructure investment thresholds determine hardware selection across fixed and portable configurations.
- Fixed Terminal:Counter-mounted devices with Ethernet connectivity and integrated receipt printers serve high-volume checkout environments. Demand concentrates in supermarket chains across Germany and France where PCI DSS compliance mandates favor hardened, permanently installed units.
- Portable Terminal:Battery-operated wireless devices with Bluetooth or Wi-Fi connectivity dominate tableside hospitality and curbside retail. Street vendors in Mumbai and delivery fleets in São Paulo drive procurement volume for this form factor.
- Mobile Terminal:Smartphone-docked card readers with audio jack or USB-C connections enable micro-merchant acceptance. Kenya's agent banking networks and India's kirana stores represent the core addressable base.
- Integrated POS:All-in-one systems combining terminal, tablet, cash drawer, and peripheral connectivity target mid-market retailers seeking unified estate management.
Volume sits with Portable Terminal; growth tilts toward Mobile Terminal.
Technology:
Payment network mandates and card issuer roadmaps dictate merchant hardware refresh cycles and certification priorities.
- Chip & Pin:EMV-compliant terminals with PIN entry devices remain mandatory for card-present authentication in European markets. French and Italian acquirers maintain this as baseline procurement specification due to EBA liability shift enforcement.
- NFC:Dual-interface terminals supporting contactless cards and wallet-enabled smartphones are displacing magnetic stripe infrastructure. Brazilian pharmacies adopted this technology under ANVISA-aligned health protocols requiring touch-free checkout.
- Magnetic Stripe:Legacy swipe readers persist in rural Indian markets and informal economies where EMV migration lags RBI digitization timelines.
- Contactless Payment:Tap-to-pay functionality without PIN for low-value transactions accelerates throughput in transportation and quick-service retail.
Volume sits with Chip & Pin; expansion tilts most steeply toward NFC.
End User:
Industry-specific transaction patterns and regulatory exposure shape terminal feature requirements and support service levels.
- Retail:High-frequency checkout environments demand durable hardware with inventory system integration. India's FMCG chains and Brazil's pharmacy networks anchor procurement volume.
- Hospitality:Tableside payment and tip-adjustment workflows require portable terminals with extended battery life. Parisian bistros and Berlin hotels specify this configuration.
- Transportation:Fare collection systems prioritize speed and offline transaction capability for subway and bus networks.
- Healthcare:Patient billing and pharmacy checkout in clinics demand HIPAA or GDPR-aligned data handling with antimicrobial device coatings.
Volume sits with Retail; expansion tilts most steeply toward Healthcare.
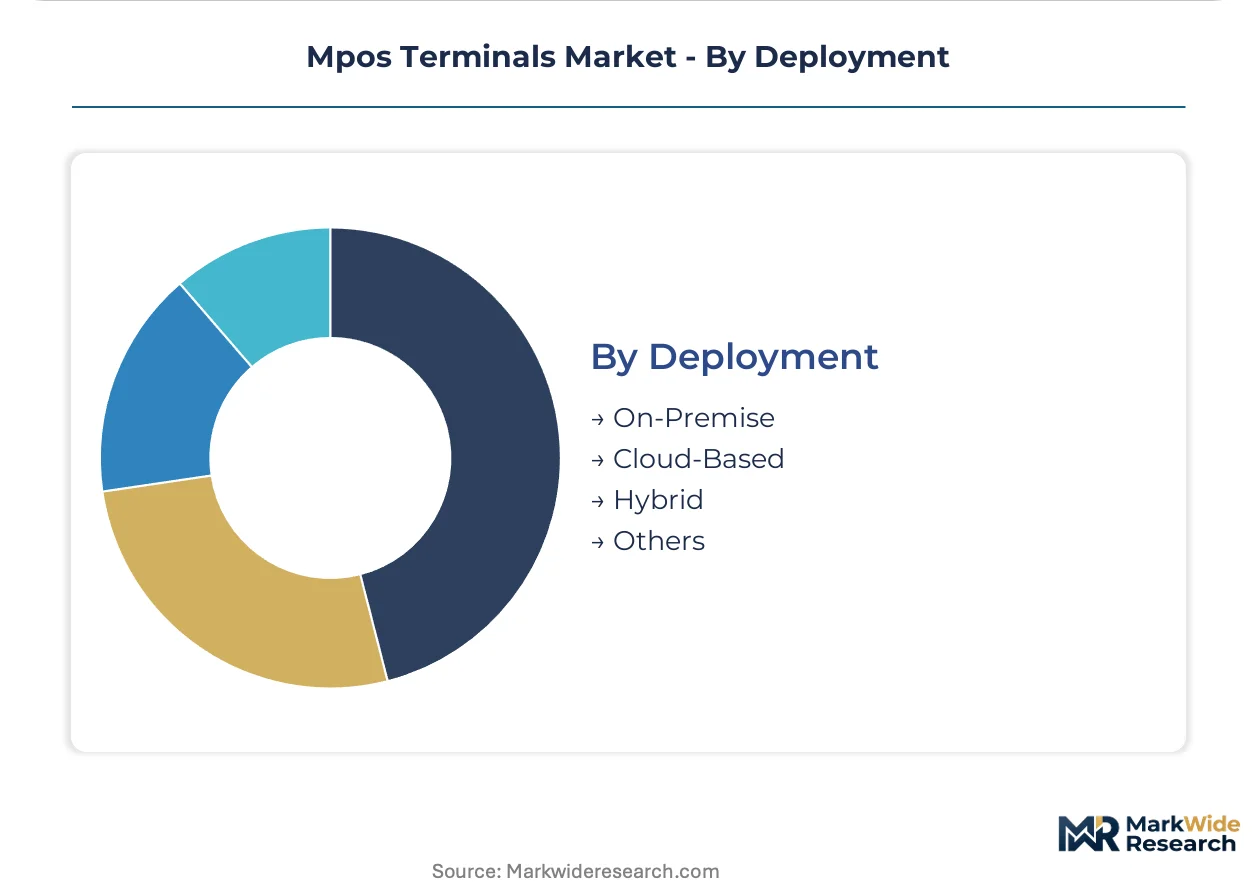
Deployment:
Merchant IT sophistication and total cost of ownership preferences determine software architecture selection and vendor contract structures.
- On-Premise:Perpetual-license software running on local servers suits large retailers with dedicated IT staff and legacy system dependencies.
- Cloud-Based:Subscription terminal management with real-time analytics and remote firmware updates is displacing licensed software. North American micro-businesses and European mid-market chains drive adoption.
- Hybrid:Mixed architectures preserve sensitive transaction processing locally while offloading reporting and inventory sync to cloud infrastructure.
- Others:Edge-computing configurations and white-label managed service arrangements serve specialized acquirer requirements.
Volume sits with On-Premise; expansion tilts most steeply toward Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate MPOS terminal assembly capacity, drawing component suppliers and certification laboratories into clustered supply networks that reduce time-to-market for new device launches.
United States
FCC certification requirements for radio-frequency emissions govern terminal distribution across retail and hospitality sectors. Merchants in New York and Los Angeles drive demand for cloud-integrated devices that sync with inventory management platforms. Square anchors merchant acquisition through software-led onboarding funnels targeting micro-businesses.
Brazil
ANVISA-aligned health protocols accelerated contactless NFC adoption in São Paulo pharmacies and Rio de Janeiro clinics. Street vendors and delivery fleets across the Southeast region procure portable Bluetooth terminals for curbside transactions. Local acquirers bundle hardware subsidies with minimum processing commitments.
India
RBI mandates for merchant payment digitization convert cash-dependent kirana stores in Mumbai and Delhi to smartphone-connected card acceptance. BIS mandatory certification filters non-local assembly entrants from government-procured terminal rollouts. Karnataka's electronics manufacturing clusters host firmware development centers.
Germany
GDPR and the Radio Equipment Directive impose concurrent hardware safety and transaction data handling requirements across payment networks. Frankfurt and Berlin acquirers consolidate vendor lists to those with EU-based secure element provisioning facilities. Chip-and-PIN compliance remains mandatory under EBA liability shift enforcement.
United Kingdom
FCA oversight of payment services intersects with GDPR data residency mandates for terminal deployments. London fintechs drive SoftPOS adoption, converting standard NFC smartphones into acceptance devices without dedicated hardware. Manchester and Birmingham hospitality chains specify portable terminals for tableside service.
Mpos Terminals Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software integration, and merchant acquisition services. The vendor base stratifies into three tiers: integrated platform operators bundling devices with processing contracts, component-scale manufacturers shipping EMV-certified hardware to acquirers, and regional specialists serving localized certification requirements. Dominant competitive moves include M&A activity consolidating firmware security capabilities and strategic partnerships between terminal vendors and payment facilitators disintermediating traditional distribution.
Within the integrated platform tier, Square and PayPal exemplify software-led merchant acquisition models that subsidize hardware through recurring revenue streams. PAX Technology occupies a position among scale-driven manufacturers supplying EMV-certified devices to European banking networks. Ingenico anchors the traditional terminal vendor archetype through direct banking partnerships concentrated in France, Germany, and Italy.
| Leading Market Players |
|---|
| Square |
| VeriFone |
| PAX Technology |
| Ingenico |
| Fiserv |
| PayPal |
| Samsung Electronics |
| Adyen |
| SumUp |
| Others |
Supply Flow & Price Mechanics
Secure element chip spot prices cascade through Shenzhen assembly lines into three-tier pricing structures across premium, standard, and economy certification levels. Terminal vendors absorb component volatility through subscription bundling that shifts hardware margin pressure onto recurring software fees.
Pricing Analysis
Lead-time premiums compress margins for expedited FCC and CE marking certifications, while spot inventory discounts clear aging EMV L1-certified stockpiles. Pricing stratifies across premium, standard, and economy tiers driven by secure element grade and after-sales firmware support depth. Cost compression in economy terminals intensifies because SoftPOS alternatives eliminate dedicated hardware for micro-merchants. India's kirana stores exhibit highest price sensitivity; German banking networks tolerate premium positioning for EU-based secure element provisioning.
Supply Chain Analysis
Freight cost spikes from Asian foundries to European distribution hubs amplify landed costs for NFC controller chips and battery packs. Manufacturing concentrates in China, Taiwan, and Vietnam, drawing from concentrated semiconductor wafer output and lithium-ion cell production. Single-source vulnerability pervades secure element provisioning facilities. Distribution runs through acquirer-led subsidy programs that bundle hardware with processing contracts rather than independent retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element foundry capacity constraints prop pricing power for vendors with allocated wafer supply. Terminal procurement queues extend as payment-as-a-service models accelerate hardware refresh cycles.
For Market Incumbents: Lock in firmware security talent through acquisition of embedded systems specialists in Bangalore and Shenzhen. Deepen backward integration into secure element provisioning by establishing EU-based facilities ahead of eIDAS 2.0 mandates. Channel control through direct banking partnerships in France and Germany defends against payment facilitator disintermediation. For New Entrants and Emerging Players: The premium-economy price-point gap in Sub-Saharan Africa agent banking networks offers white-space entry. Kenya and Nigeria's mobile money interoperability with card rails presents the most penetrable geography. SoftPOS convergence enables Android-based acceptance apps that compress customer acquisition costs toward zero. For Investors and Strategic Acquirers: Distressed-cycle entries favor firmware security specialists with BIS and ANATEL certification capabilities in India and Brazil. Long-term viability hinges on payment-as-a-service transition completion within a decade horizon. Watch SoftPOS penetration rates in North American gig economy platforms as inflection indicator for dedicated hardware commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Acquisition | Consolidates scarce embedded systems talent ahead of PCI DSS 4.0 mandates. |
| EU Secure Element Facility | Positions vendors for eIDAS 2.0 digital identity wallet integration requirements. |
| SoftPOS Platform Launch | Captures micro-merchant segments that dedicated hardware economics cannot serve. |
| Sub-Saharan Distribution Partnership | Addresses agent banking hardware density gaps in Kenya and Nigeria. |
| Cloud-First Terminal Management | Aligns with acquirer shift from perpetual-license to subscription revenue models. |
Methodological Framework
Independent corroboration across terminal vendor supply chain managers, payment network compliance officers, and acquirer procurement leads underwrites the qualitative findings. Secondary validation draws from RBI circulars, FCC equipment authorization databases, EU Radio Equipment Directive technical documentation, and customs import records for payment device classifications. Bottom-up shipment estimates triangulate against top-down payment volume projections.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation modeling spans product type, technology protocol, end-user industry, and deployment architecture. CAGRs derive from fitted growth curves against historical terminal placement data and projected payment digitization policy impacts. Inputs include EMV migration timelines, NFC card issuance forecasts, and cloud POS adoption curves.
Inputs from regulatory filing databases and vendor shipment disclosures were available through the study window; gaps in informal economy cash-to-digital transition rates introduce uncertainty bands. Forecasts reflect documented assumptions about policy enforcement consistency and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Prepaid Cards Market
Payments
Instant Payments Market
Payments
Hong Kong Credit Cards Market
Payments
US Buy Now Pay Later Services Market
Payments
B2C Payment Market
Payments
Latin America Retail Cash Management Market
Payments
Bulgaria POS Terminals Market
Payments
Digital Money Transfer Market
Payments
Japan Retail Cash Management Market
Payments
Nigeria Mobile Money Market
Payments
Retail POS Terminals Market
Payments
Europe Real Time Payments Market
Payments
China Forex Cards Market
Payments
India RTP Market
Payments
Electronic Payment Processing Software Market
Payments
Accelerator Card Market