
 Electronic Toll Collection (ETC) Market | 2026-2036
Electronic Toll Collection (ETC) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Toll Collection (ETC) Market Analysis
Modular system bundling that combines RFID transponders, ANPR cameras, and back-office analytics into single procurement packages is expanding buyer choice across toll authorities. Kapsch TrafficCom AG leverages its integrated roadside-to-cloud architecture to dominate European highway contracts. Siemens AG anchors its position through deep manufacturing scale in DSRC roadside units. Cubic Corporation competes aggressively in North American urban tolling corridors with transit-payment interoperability.
Electronic Toll Collection encompasses automated vehicle identification, classification, and payment processing at toll points using radio-frequency communication, optical recognition, or mobile credentialing, typically operating at 5.8 GHz DSRC or 860-960 MHz RFID frequencies with transaction completion under 100 milliseconds. RFID technology leads installed base globally due to proven interoperability and low unit cost, while mobile payment represents the fastest-expanding segment as smartphone penetration enables account-based tolling without dedicated hardware. Highway Tolling commands the largest revenue pool, though Parking Management applications are attracting new entrants seeking recurring software subscription margins.
The U.S. DOT and FHWA enforce interoperability mandates through MAP-21 and subsequent reauthorization bills, compelling state agencies to adopt compatible systems. Europe's ETSI standards and CE marking requirements shape product certification, while India's NHAI and BIS drive domestic manufacturing compliance through tolling-specific technical specifications. Stakeholders must monitor evolving cybersecurity frameworks for connected infrastructure and assess cloud deployment architectures against data sovereignty requirements in multi-jurisdictional corridors.
Market Dynamics
Government mandates for cashless tolling are compressing procurement timelines and forcing interoperability standards across multi-jurisdictional highway networks, fundamentally restructuring vendor selection criteria toward integrated system providers.
Growth Catalysts
- India's FASTag Mandate:NHAI's nationwide RFID requirement for commercial and private vehicles eliminates cash lanes and generates recurring transaction volume for system operators.
- DSRC-to-C-V2X Transition:The 5.9 GHz spectrum reallocation by the FCC is accelerating roadside unit upgrades and creating replacement demand across US interstate corridors.
- Urban Congestion Pricing:Metropolitan tolling zones in Singapore, London, and Stockholm demonstrate revenue models that city planners in São Paulo and Jakarta are replicating.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries dominate RF chipset production, exposing toll system OEMs to allocation delays and price volatility.
- Interoperability Fragmentation:E-ZPass, SunPass, and TxTag maintain incompatible back-office protocols despite MAP-21 mandates, forcing dual-tagging in cross-border corridors.
- Optical Recognition Limitations:ANPR accuracy degrades below operational thresholds in heavy precipitation and direct sunlight, requiring redundant RFID infrastructure.
Strategic Opportunities
- Parking-Tolling Convergence:Smartphone credentialing enables unified mobility accounts spanning highway gantries and municipal parking structures, unlocking subscription revenue.
- Brazil's BR-101 Modernization:Federal concession renewals on the coastal highway corridor specify open-road tolling requirements without legacy plaza infrastructure.
- Edge AI Integration:On-gantry inference engines processing vehicle classification and anomaly detection reduce cloud latency and data transmission costs.
Industry Challenges
- Cybersecurity Certification Complexity:IEC 62443 compliance for connected roadside infrastructure extends deployment timelines by 8-14 months and requires specialized audit partners.
- Legacy Back-Office Migration:State agencies operating 1990s-era mainframe transaction processors face integration failures when connecting to modern API-based clearinghouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Toll Collection (ETC) Market |
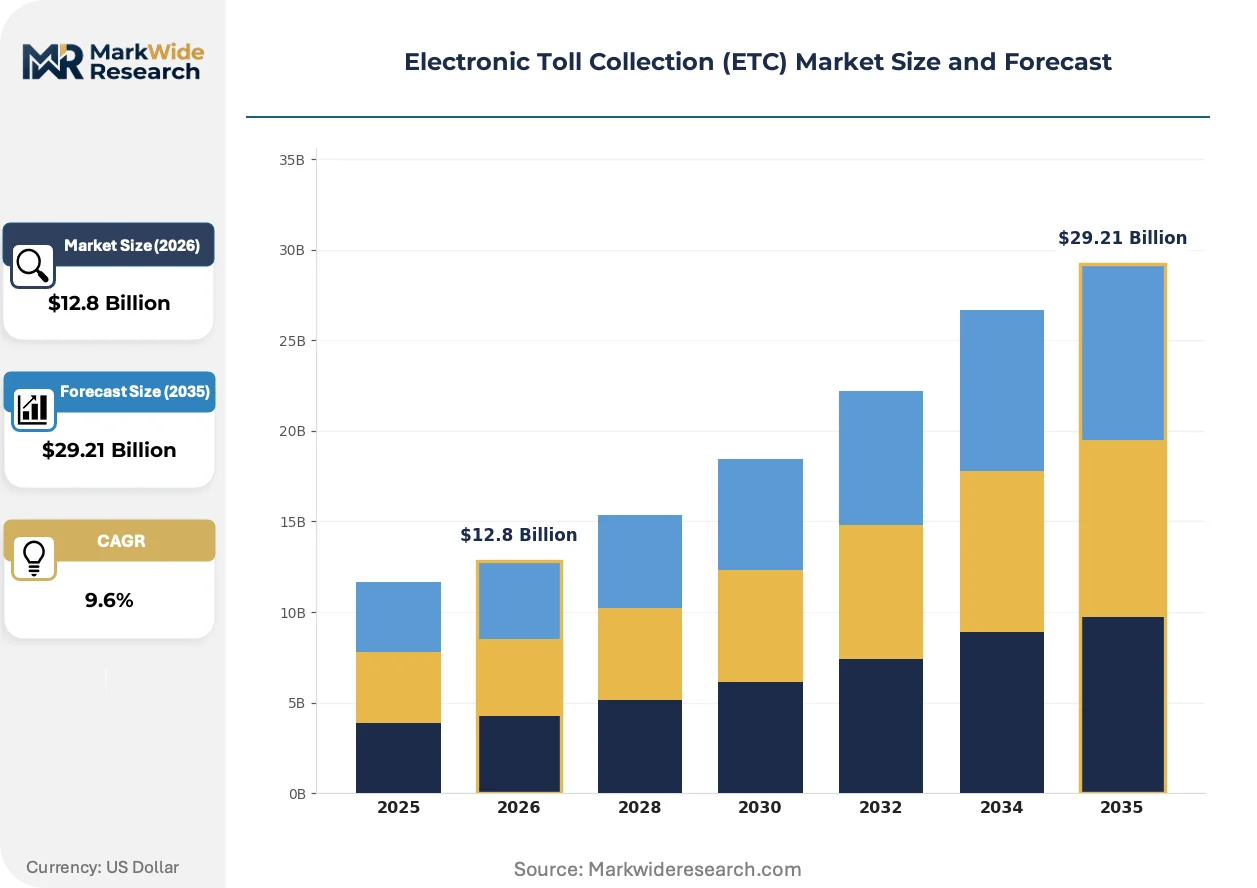
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, ANPR, DSRC, Mobile Payment End User: Government Agencies, Highway Operators, Private Operators, Transport Authorities Deployment: Cloud-based, On-premises, Hybrid, IP-based Application: Urban Tolling, Highway Tolling, Parking Management, Fleet Management |
| Companies Covered | Kapsch TrafficCom AG, Conduent Incorporated, TransCore, Thales Group, Siemens AG, EFKON GmbH, Cubic Corporation, Raytheon Technologies Corporation, Q-Free, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Toll Collection (ETC) Market Emerging Trajectories
Credentialing technology is fragmenting across hardware, software, and hybrid models, forcing toll operators to architect for multi-protocol acceptance rather than single-technology standardization. This diversification is compressing vendor lock-in and expanding procurement options.
Blockchain-based settlement networks are decentralizing inter-agency reconciliation by enabling real-time fund transfers between toll authorities without centralized clearinghouse intermediaries. Pilot deployments in the Netherlands and Texas validate the architecture. The structural consequence is reducing working capital requirements and dispute resolution overhead for multi-state operators.
The EU's Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure timelines on connected infrastructure vendors selling into European markets. Manufacturers must maintain software support lifecycles of at least five years. DSRC roadside unit suppliers are restructuring engineering teams to meet these continuous compliance requirements.
Fleet operators are consolidating toll account management through third-party mobility platforms that aggregate transactions across multiple jurisdictions and vehicle classes. This intermediation disintermediates direct agency relationships and shifts pricing power toward volume buyers. The pattern is most pronounced among North American trucking companies operating across state lines.
Electronic Toll Collection (ETC) Market Segmentation
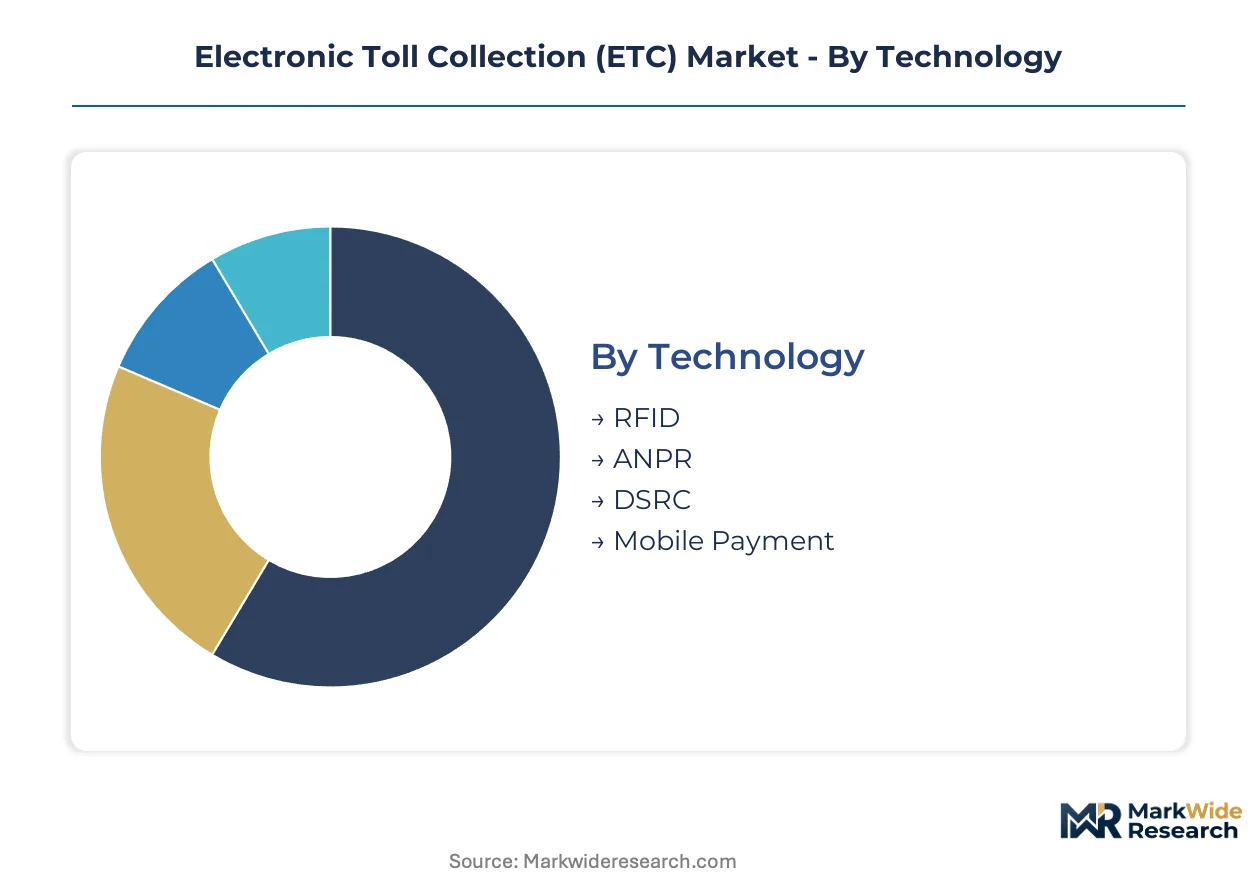
Technology choice determines infrastructure lifespan and interoperability scope for toll operators. Procurement decisions cascade across hardware refresh cycles, back-office integration complexity, and compliance with evolving spectrum regulations.
Technology:
Upgrade cycles vary sharply by frequency band and chipset architecture, with roadside unit replacements triggered by spectrum reallocation mandates rather than equipment failure alone.
- RFID:Operates in the 860-960 MHz band using passive tag-to-reader communication with read ranges up to 15 meters. India's NHAI mandates this technology for FASTag compliance across national highways, generating sustained procurement volume for transponder manufacturers and gantry integrators.
- DSRC:Dedicated Short-Range Communications at 5.8 GHz enables two-way vehicle-to-infrastructure dialogue with sub-100 millisecond latency. The FCC's 5.9 GHz spectrum reallocation is forcing roadside unit replacements across US interstate corridors, concentrating near-term demand in states with aging plaza infrastructure.
- ANPR:Optical character recognition captures license plates using infrared and visible-spectrum cameras for enforcement backup. Accuracy degradation in heavy precipitation limits standalone deployment.
- Mobile Payment:Smartphone credentialing eliminates dedicated hardware through GPS and cellular triangulation. Singapore's ERP 2.0 and Jakarta's planned congestion zones prioritize this architecture for urban density.
RFID sits at the top of the volume ranking, with Mobile Payment climbing the fastest.
End User:
Procurement authority concentrates differently by project scale, with federal mandates overriding local preferences in multi-jurisdictional corridors.
- Government Agencies:National transport ministries set technical standards and interoperability mandates. The US DOT enforces MAP-21 compliance across state boundaries, while China's MIIT drives domestic chipset certification requirements.
- Highway Operators:Concession holders manage toll collection under long-term infrastructure contracts. Brazil's federal highway renewals specify open-road tolling without legacy plazas.
- Private Operators:Commercial plaza owners prioritize transaction throughput and labor cost reduction. Procurement flexibility exceeds public-sector timelines.
- Transport Authorities:Metropolitan agencies integrate tolling with transit and parking systems. London's TfT and Stockholm's transport administration demonstrate unified mobility account architectures.
Government Agencies anchor procurement volume, with Transport Authorities gaining share fastest.
Deployment:
Architecture choice shapes cybersecurity exposure and data sovereignty compliance across multi-jurisdictional corridors.
- Cloud-based:Centralized transaction processing with API-based clearinghouse integration. The EU's Cyber Resilience Act imposes five-year software support mandates on vendors serving European operators.
- On-premises:Local server infrastructure for agencies with strict data residency requirements. India's BIS specifications favor domestic hosting for sensitive vehicle registry data.
- Hybrid:Edge inference for real-time classification with cloud settlement for reconciliation. Reduces latency while maintaining audit trails.
- IP-based:Internet Protocol networking for distributed gantry communication. Exposes infrastructure to ransomware targeting connected roadside units.
On-premises deployments retain the largest installed base, with Hybrid architectures expanding most quickly.
Application:
Revenue models diverge between transaction-volume highway corridors and recurring-subscription parking structures.
- Urban Tolling:Congestion pricing zones with dynamic rate structures by time and vehicle class. São Paulo and Jakarta are replicating Singapore's ERP model.
- Highway Tolling:Distance-based or point-charge collection on intercity corridors. Germany's Toll Collect system and US E-ZPass network demonstrate scale economics.
- Parking Management:Municipal and commercial structures adopting credentialing interoperability with highway accounts. Software margins exceed hardware-heavy tolling.
- Fleet Management:Aggregated account administration for multi-jurisdiction trucking operations. Third-party mobility platforms intermediate between carriers and toll authorities.
Highway Tolling commands the steepest expansion trajectory, with Parking Management showing the fastest margin improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic toll collection infrastructure first achieved commercial scale across European motorway networks during the 1990s, with Italy's Telepass and France's Liber-T systems establishing the operational template now replicated worldwide. This historical lineage shapes current deployment patterns, as mature markets replace legacy equipment while emerging economies adopt open-road architectures without plaza-era constraints.
United States
The Federal Highway Administration enforces MAP-21 interoperability mandates across state boundaries, compelling agencies like the Pennsylvania Turnpike Commission and Florida's SunPass network to adopt compatible back-office protocols. The FCC's 5.9 GHz spectrum reallocation is accelerating roadside unit replacements along interstate corridors, with California's Bay Area FasTrak and Texas's TxTag systems driving procurement volume for DSRC upgrades.
Germany
The Federal Office for Goods Transport oversees the Toll Collect system covering heavy goods vehicles across the autobahn network, generating sustained demand for satellite-based enforcement infrastructure. KBA certification requirements shape vendor selection for roadside equipment, with concentrated deployment activity across Bavaria's A9 motorway corridor and the Rhine-Ruhr industrial belt where freight density peaks.
China
MIIT standardization mandates have unified provincial toll networks under a single ETC technical framework, eliminating the fragmented systems that previously complicated inter-provincial travel. The Yangtze River Delta integration project connects Shanghai's urban expressways with Jiangsu and Zhejiang provincial networks, while Guangdong's Pearl River Delta corridor processes the world's highest transaction volumes through its gantry-based architecture.
India
NHAI's FASTag mandate requires RFID compliance across all national highways, with BIS technical specifications favoring domestic manufacturing of transponders and readers. Deployment concentrates along the Delhi-Mumbai Industrial Corridor and the Chennai-Bangalore expressway, where concession holders are eliminating cash lanes entirely to comply with federal cashless directives.
Brazil
Federal highway concession renewals on the BR-101 coastal corridor specify open-road tolling without legacy plaza infrastructure, creating procurement opportunities for gantry-based systems. ANVISA-equivalent transport regulators enforce technical standards, with São Paulo's metropolitan Rodoanel and Rio de Janeiro's Arco Metropolitano driving demand for multi-lane free-flow architectures.
Electronic Toll Collection (ETC) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across system integration complexity, with full-stack roadside-to-cloud architectures commanding pricing power over component-only suppliers. The vendor base clusters around three strategic archetypes: integrated highway system providers, specialized DSRC/RFID hardware manufacturers, and transit-payment convergence specialists. Dominant competitive moves include modular system bundling that combines transponders, cameras, and analytics into single procurement packages, and strategic partnerships between toll operators and cloud infrastructure providers to meet data sovereignty requirements.
Within the integrated system tier, Kapsch TrafficCom AG and Siemens AG exemplify the full-architecture providers that dominate European and North American highway contracts through deep manufacturing scale and roadside-to-cloud integration. Cubic Corporation occupies a distinct position bridging tolling and transit-payment interoperability, particularly in urban corridors where unified mobility accounts span multiple transportation modes. These three companies represent the competitive anchors against which specialized component suppliers and regional system integrators must differentiate.
| Leading Market Players |
|---|
| Kapsch TrafficCom AG |
| Conduent Incorporated |
| TransCore |
| Thales Group |
| Siemens AG |
| EFKON GmbH |
| Cubic Corporation |
| Raytheon Technologies Corporation |
| Q-Free |
| Others |
Supply Flow & Price Mechanics
NHAI's FASTag mandate and the FCC's 5.9 GHz reallocation are compressing procurement timelines and forcing toll authorities toward bundled system architectures, concentrating supplier power among integrated vendors while fragmenting component-level pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation anchored in certification grade (CE marking, KBA approval) and after-sales service bundling. Price differentiation stems from gantry integration complexity and cloud deployment architecture. Cost compression in standard-tier RFID transponders is intensifying because of domestic manufacturing requirements in India and China. Government agencies exhibit highest price sensitivity due to public procurement rules, while private highway operators prioritize throughput metrics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries for RF chipsets, exposing toll system OEMs to allocation delays. Manufacturing concentrates in China, Germany, and the United States for DSRC roadside units, gantry structures, and back-office software respectively. The supply chain rests on silicon carbide substrates, high-frequency antennas, and edge computing modules. Tariff exposure on Chinese-manufactured transponders creates procurement risk for North American operators. Distribution runs through system integrators and direct government contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's domestic manufacturing mandates and China's MIIT standardization create cost-advantaged supply bases against Europe's CE marking and Cyber Resilience Act compliance burdens.
For Market Incumbents: Anticipate margin pressure from mobile payment disintermediation and edge AI commoditization. Defensive consolidation should prioritize backward integration into RF chipset supply and captive cloud infrastructure development. Certification investment in IEC 62443 cybersecurity frameworks protects against regulatory displacement. For New Entrants and Emerging Players: Capture white-space in parking-tolling convergence platforms and Brazil's BR-101 open-road tolling specifications. The most penetrable segment lies in third-party fleet management intermediation for North American trucking operators. A software-first go-to-market angle bypasses hardware manufacturing scale disadvantages. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid-deployment specialists bridging on-premises data sovereignty and cloud scalability. Long-term viability favors vendors with five-year software support capabilities mandated by EU regulation. Watch for DSRC-to-C-V2X transition announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Modular System Bundling | Combines RFID, ANPR, and analytics into single procurement packages for toll authorities. |
| Backward Integration into RF Chipsets | Reduces exposure to Taiwan foundry allocation delays and price volatility. |
| Edge AI Deployment | On-gantry inference cuts cloud latency for real-time vehicle classification. |
| Cybersecurity Certification Investment | IEC 62443 compliance extends deployment timelines but locks out unqualified competitors. |
| Parking-Tolling Convergence Platform | Unified mobility accounts unlock subscription revenue across highway and municipal infrastructure. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each combining interviews with toll authority procurement directors, highway concession operators, system integration engineers, and fleet management platform executives alongside secondary validation through FCC spectrum filings, NHAI technical specifications, ETSI standards documentation, and customs trade data. Bottom-up and top-down triangulation cross-validates transaction volume estimates against infrastructure deployment records.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, modeling technology transition curves for RFID, DSRC, and mobile payment architectures alongside deployment model segmentation (cloud, on-premises, hybrid) and application categories (highway tolling, urban congestion pricing, parking management, fleet administration). CAGRs derive from infrastructure replacement cycles, government mandate enforcement timelines, and spectrum reallocation deadlines.
Spectrum reallocation delays, semiconductor supply disruptions, and cybersecurity certification backlogs are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about interoperability mandate compliance and concession renewal schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Portugal Mobile Payments Market
Payments
Dual Interface Payment Card Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Netherlands Mobile Payments Market
Payments
Ghana Mobile Money Market
Payments
MENA Digital Payments Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
Netherlands POS Terminal Market
Payments
M Commerce Payment Market
Payments
Mobile Point of Sale (POS) Market
Payments
Global Point of Sale Terminals Market
Payments
Transit Cards Market
Payments
Germany Real Time Payments Market
Payments
Mobile POS Market
Payments
Cash Management Software Market
Payments
Third Party Payment Market