
 Middle East and Africa Data Storage Market | 2026-2036
Middle East and Africa Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Data Storage Market Foresight
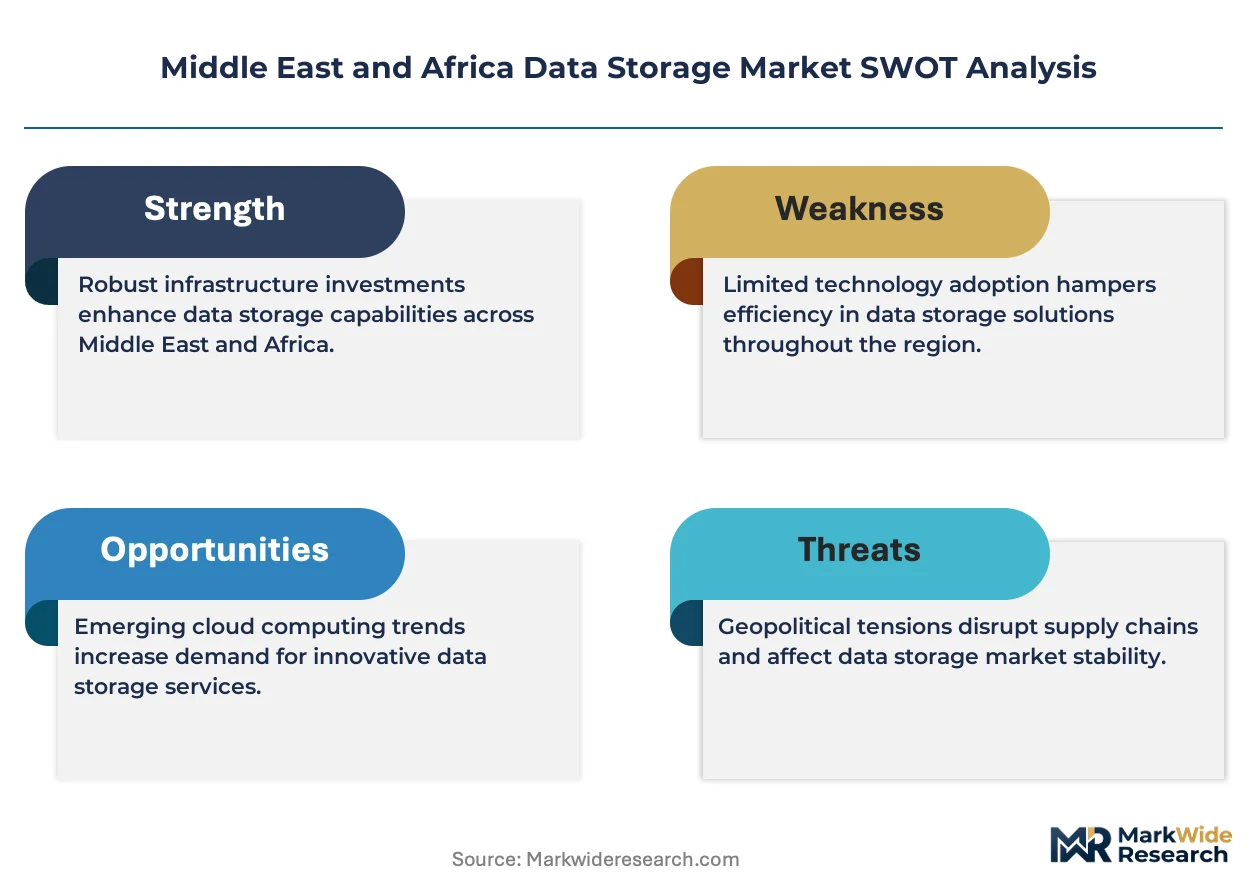
Subscription-based software-defined storage is shifting how vendors monetize capacity across the Middle East and Africa. Dell Technologies anchors its regional presence through direct enterprise engagements and localized support infrastructure. Huawei Technologies competes aggressively on price-performance metrics for government and telecom tenders. IBM differentiates through hybrid cloud orchestration layers that bridge on-premises legacy systems with public cloud endpoints.
Middle East and Africa data storage encompasses magnetic, solid-state, and cloud-based systems engineered for persistent digital retention, with NVMe interfaces now delivering sub-100-microsecond latency for transactional workloads. Solid state drives and cloud storage segments attract the majority of new capital allocation as enterprises retire spinning disk infrastructure. Deployment patterns favor hybrid architectures that let organizations keep sensitive data on-premises while bursting compute-intensive analytics to public cloud instances.
SFDA in Saudi Arabia, MOHAP in the UAE, and South Africa's national information regulator enforce data localization mandates that dictate where primary copies and backups must physically reside. These frameworks compel foreign hyperscalers to build in-region facilities and certify compliance with local encryption standards. Stakeholders must evaluate sovereign cloud partnerships against the operational complexity of maintaining fragmented compliance postures across multiple jurisdictions.
Market Dynamics
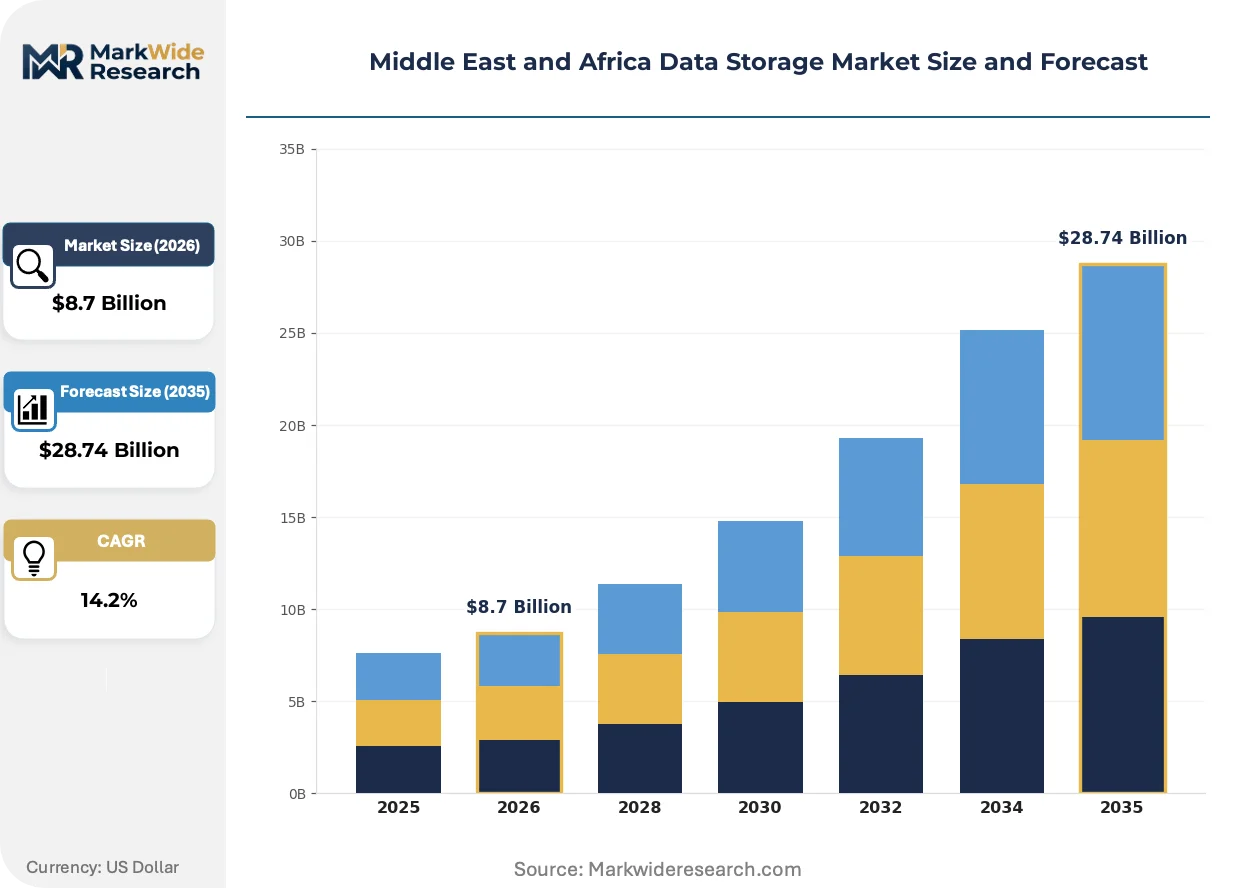
Data sovereignty mandates from Saudi Arabia's SFDA and UAE's MOHAP are forcing foreign hyperscalers to build localized infrastructure, reshaping capital allocation and vendor selection criteria across the Middle East and Africa storage landscape.
Growth Catalysts
- NVMe Interface Adoption:Sub-100-microsecond latency specifications are rewriting performance benchmarks for transactional workloads in financial services and telecom sectors.
- SFDA Localization Mandates:Saudi Arabia's pharmaceutical and healthcare data residency rules compel multi-terabyte in-country deployments and certified encryption standards.
- Hybrid Architecture Preference:South African enterprises and Nigerian banks are splitting workloads between on-premises sensitive data and burst analytics to public cloud endpoints.
Market Restraints
- Flash Memory Cost Volatility:NAND pricing fluctuations compress margin predictability for solid-state array vendors serving price-sensitive African markets.
- Power Infrastructure Deficits:Unreliable grid supply in parts of Nigeria and Kenya elevates total cost of ownership for energy-intensive spinning disk retention systems.
- Skilled Technician Scarcity:Certified storage administrators remain concentrated in Johannesburg, Lagos, and Dubai, limiting deployment velocity in secondary cities.
Strategic Opportunities
- Ethiopia and Kenya Expansion:Underpenetrated East African markets present first-mover advantages for vendors establishing localized support nodes ahead of regulatory maturation.
- AI Training Data Repositories:Sovereign cloud partnerships with Gulf telcos are creating demand for petabyte-scale object storage for machine learning pipelines.
- Subscription Monetization:Software-defined capacity contracts are displacing perpetual license models among mid-market South African retailers and logistics operators.
Industry Challenges
- Fragmented Compliance Postures:Vendors must maintain separate encryption certifications for SFDA, MOHAP, and South Africa's information regulator simultaneously.
- Legacy Tape Migration Complexity:Long-term archival customers in government and banking sectors face multi-year extraction timelines from aging magnetic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Data Storage Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Cloud Storage Technology: SAS, SATA, NVMe, USB End User: Enterprises, SMEs, Government, Educational Institutions Deployment: On-Premises, Hybrid, Private Cloud, Public Cloud |
| Companies Covered | NetApp, Hitachi Vantara, Dell Technologies, Amazon Web Services, Fujitsu, Hewlett Packard Enterprise, IBM, Microsoft, Huawei Technologies, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Data Storage Market Shifts & Advancements
Storage architecture across the Middle East and Africa is converging around software-defined control planes that abstract physical media location from application access patterns.
NVMe-over-Fabrics is rewriting latency expectations for high-frequency trading and real-time fraud detection platforms. Dubai-based financial institutions and Johannesburg stock exchange participants are deploying these fabrics at scale. The technology is compressing the performance gap between local solid-state arrays and remote cloud instances.
MOHAP's 2024 data classification framework is mandating tiered residency rules for patient records and clinical trial data. Foreign cloud operators must now maintain physically segregated Emirati zones with localized key management. Healthcare IT procurement in Abu Dhabi and Dubai is prioritizing vendors with pre-certified sovereign infrastructure.
Consumption-based capacity contracts are displacing traditional capital expenditure cycles among mid-tier Saudi manufacturers and Egyptian telecom operators. Managed service providers in Riyadh and Cairo are bundling hardware, software, and operational support into single monthly fees. This shift is most visible in organizations with unpredictable growth trajectories seeking to avoid stranded asset risk.
Middle East and Africa Data Storage Market Segmentation
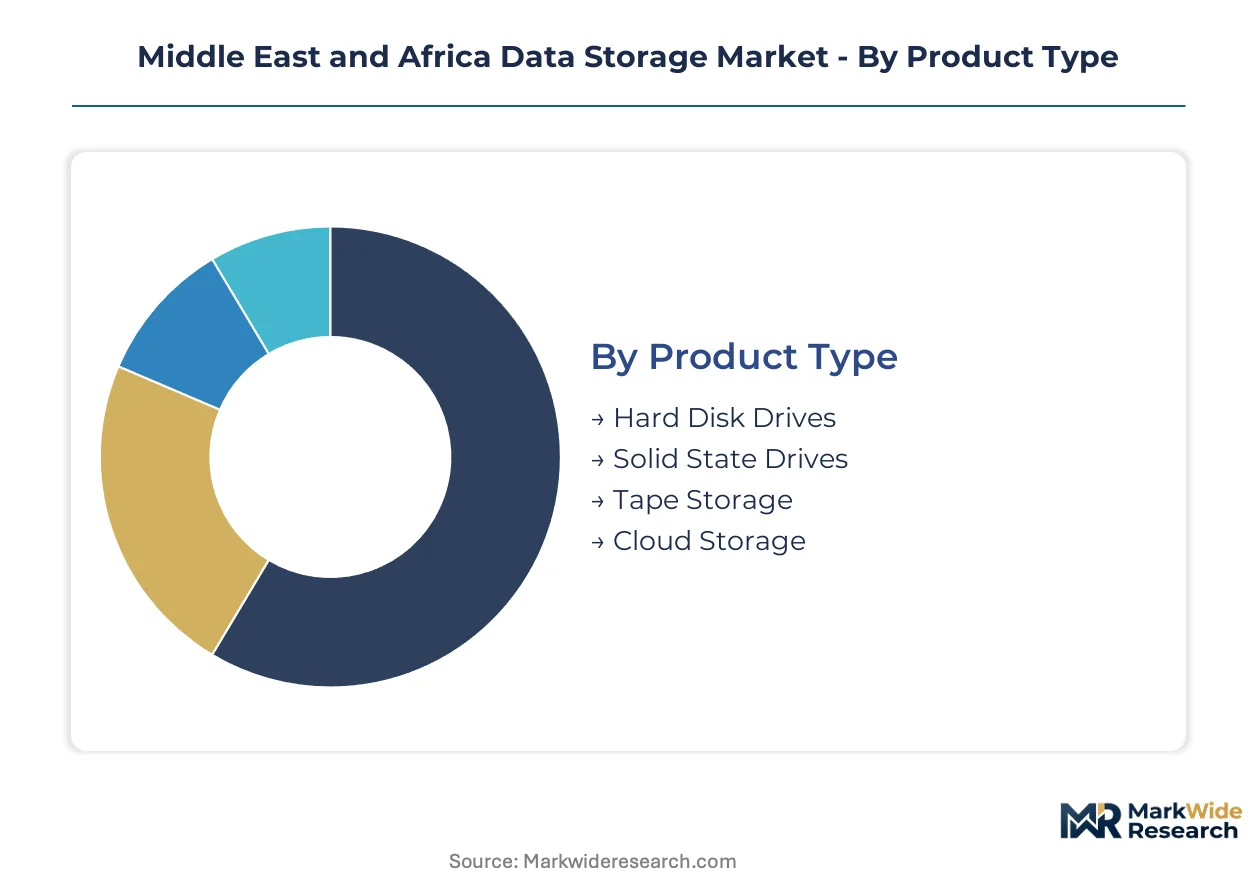
Storage procurement patterns across the Middle East and Africa diverge sharply by workload sensitivity, infrastructure maturity, and regulatory exposure. Vendors must align product portfolios with sovereign compliance mandates and hybrid architecture preferences that vary by customer scale and sector.
Product Type:
Standalone storage systems dominate enterprise and government tenders where data residency rules apply, while embedded flash configurations proliferate in telecom and fintech edge deployments.
- Solid State Drives:NAND-based persistent storage with NVMe interfaces delivers sub-100-microsecond latency for transactional databases. South African banks and UAE financial exchanges prioritize these arrays for real-time clearing systems where milliseconds determine arbitrage outcomes. SFDA-certified healthcare deployments in Riyadh specify encrypted NVMe for electronic medical record acceleration.
- Cloud Storage:Object and block services delivered via hyperscaler or sovereign cloud partnerships abstract physical infrastructure from application layers. Saudi pharmaceutical manufacturers and Nigerian mobile money operators favor consumption-based contracts that eliminate stranded capacity risk during regulatory transitions.
- Hard Disk Drives:Magnetic spinning media retains cost advantage for sequential archival workloads with relaxed latency requirements.
- Tape Storage:Linear tape-open systems persist in long-term government archives and banking compliance repositories despite extraction complexity.
Volume placements concentrate in Hard Disk Drives; the faster expansion belongs to Cloud Storage.
Technology:
Interface selection tracks performance tier requirements and legacy infrastructure inheritance, with premium workloads demanding protocol modernization while budget-constrained deployments extend SATA lifecycles.
- NVMe:PCIe-attached protocol eliminates SCSI translation overhead, enabling direct memory access for flash arrays. Johannesburg stock exchange participants and Dubai-based high-frequency trading platforms deploy NVMe fabrics to compress tick-to-trade latency. Kenyan fintech startups adopt NVMe-over-TCP to bridge on-premises transaction engines with cloud analytics.
- SAS:Serial-attached SCSI maintains enterprise server compatibility for tiered storage architectures in Egyptian manufacturing and Moroccan logistics.
- SATA:Legacy interface persists in cost-optimized secondary storage for Nigerian educational institutions and small South African retailers.
- USB:Removable flash standard serves field data collection and offline transfer scenarios across humanitarian and agricultural survey operations.
Procurement volume clusters around SAS in established enterprise accounts; NVMe claims the steepest expansion trajectory among protocol categories.
End User:
Customer scale determines whether storage acquisition follows centralized procurement with compliance certification or decentralized shadow IT with subscription flexibility.
- Government:Sovereign data mandates from SFDA, MOHAP, and South Africa's information regulator dictate encrypted, air-gapped, or sovereign-cloud architectures. Saudi healthcare authorities and UAE federal entities require localized key management and physical segregation of citizen data.
- Enterprises:Large organizations in South African mining and UAE aviation operate hybrid estates spanning owned data centers and sovereign cloud partnerships.
- SMEs:Mid-market retailers and logistics operators across Cairo and Lagos favor managed storage services with predictable monthly expenditure.
- Educational Institutions:Universities and research centers in Ethiopia and Kenya prioritize cost-efficient capacity for digital library and research data preservation.
Contract value concentrates in Government verticals; SME accounts are gaining share fastest as subscription models democratize enterprise-grade capabilities.
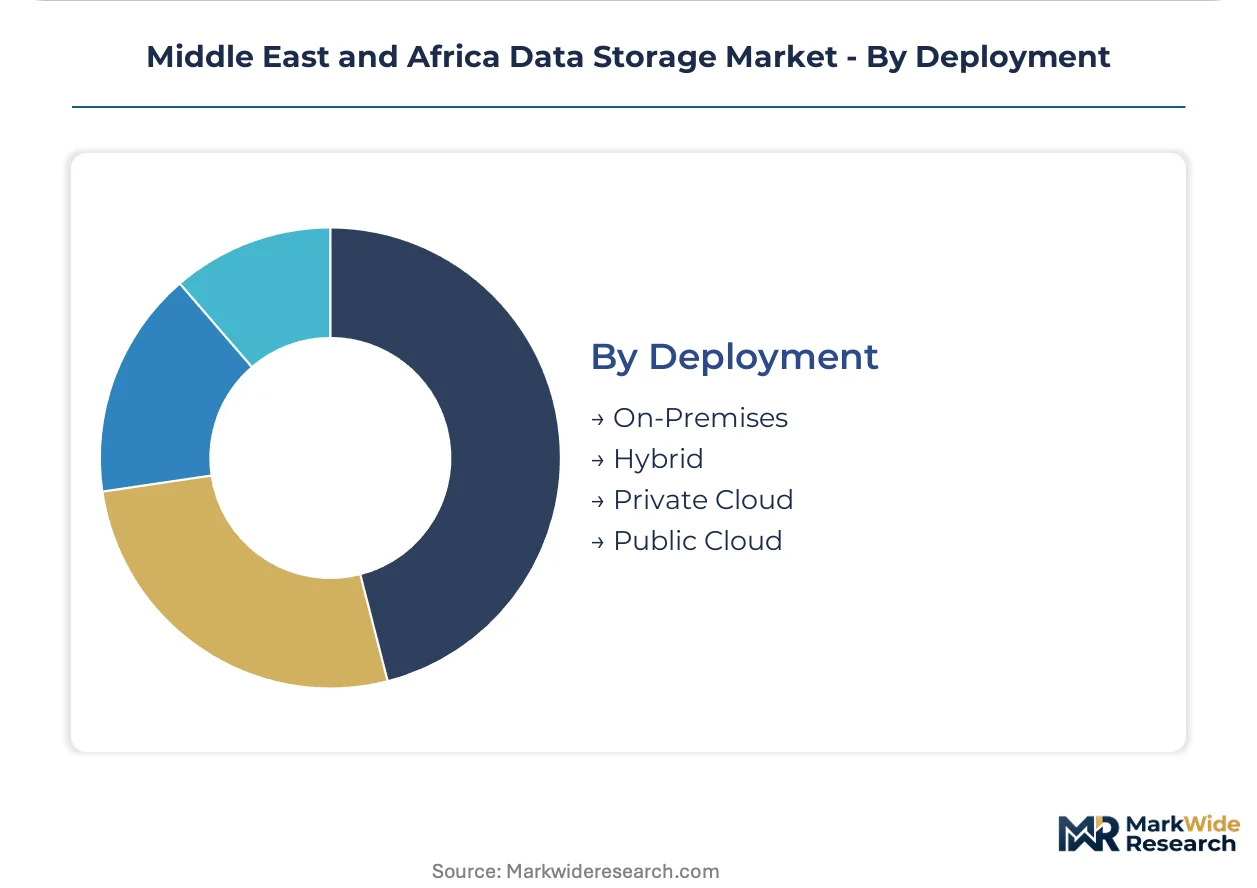
Deployment:
Architecture choice reflects data classification tiering, with sensitive primary copies anchored locally and compute-intensive analytics burst to scalable infrastructure.
- Hybrid:Split workload placement keeps regulated data on-premises while elastic compute scales to public cloud. Nigerian banks and South African insurers deploy this pattern to satisfy central bank data residency rules without sacrificing machine learning throughput.
- On-Premises:Fully owned infrastructure persists where air-gapping or latency constraints dominate, particularly in defense and critical infrastructure operators.
- Private Cloud:Single-tenant sovereign cloud instances serve MOHAP-compliant healthcare and SFDA-regulated pharmaceutical research.
- Public Cloud:Multi-tenant hyperscaler services attract development environments and non-sensitive analytics where data classification permits.
Existing infrastructure value sits in On-Premises installations; Hybrid architectures are climbing the fastest as compliance and flexibility requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage infrastructure investment across the Middle East and Africa outpaces local manufacturing capacity, creating dependency on imported systems from Asia-Pacific and European fabrication centers. Consumption concentrates in Gulf financial hubs and South African enterprise clusters while production remains negligible outside assembly operations.
Saudi Arabia
SFDA pharmaceutical data mandates and NEOM smart city deployments are driving petabyte-scale sovereign cloud procurement. The national data regulator enforces strict localization for citizen health records and financial transaction logs. Riyadh hosts the region's densest concentration of hyperscale data center construction, with multiple foreign operators establishing certified facilities.
United Arab Emirates
MOHAP's 2024 healthcare classification framework and Dubai's financial exchange latency requirements are splitting demand between sovereign private clouds and NVMe-equipped trading floors. The federal health authority mandates physically segregated Emirati zones with localized encryption key management. Abu Dhabi and Dubai together account for the Gulf's highest per-capita storage spending.
South Africa
Johannesburg Stock Exchange modernization and national information regulator compliance are accelerating hybrid architecture adoption among insurers and mining conglomerates. The country's data protection authority enforces cross-border transfer restrictions that favor in-region primary storage. Cape Town's financial district and Pretoria's government data centers anchor enterprise procurement volumes.
Nigeria
Central bank data residency rules for mobile money operators and Lagos fintech expansion are creating demand for localized Tier III facilities. The national banking regulator mandates transaction record retention within national boundaries. Lagos and Abuja concentrate the country's limited certified data center capacity, with generator-dependent operations elevating total cost of ownership.
Egypt
Government digital transformation programs and Suez Canal logistics digitization are stimulating consumption-based storage contracts among state enterprises. The national telecommunications regulator oversees data classification standards for critical infrastructure operators. Cairo and Alexandria host the majority of North African managed service provider consolidation, with subscription models displacing capital expenditure cycles.
Middle East and Africa Data Storage Market Competitive Landscape
Top-tier vendors anchor enterprise and government tenders through direct sales and localized support infrastructure, while mid-tier specialists compete on price-performance for telecom and mid-market engagements. Market structure tilts toward consolidated procurement relationships in regulated sectors and fragmented vendor selection in price-sensitive segments. Three archetypes dominate: full-stack systems integrators with sovereign cloud certifications, hardware-centric manufacturers competing on NAND economics, and hyperscalers building in-region facilities to satisfy data residency mandates. Primary competitive moves center on strategic partnerships with Gulf telcos for sovereign cloud capacity and geographic expansion into underpenetrated East African markets.
Within the full-stack systems integrator tier, Dell Technologies and IBM occupy positions exemplifying hybrid cloud orchestration and legacy modernization capabilities. Huawei Technologies anchors the hardware-centric manufacturing archetype, competing aggressively on price-performance metrics for government and telecom infrastructure tenders. These three companies collectively represent the competitive positioning spectrum spanning Western enterprise relationship depth, Chinese manufacturing scale, and emerging market localization agility.
| Leading Market Players |
|---|
| NetApp |
| Hitachi Vantara |
| Dell Technologies |
| Amazon Web Services |
| Fujitsu |
| Hewlett Packard Enterprise |
| IBM |
| Microsoft |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
SFDA and MOHAP data localization mandates are compelling hyperscalers to establish in-region facilities, forcing supply chains to absorb certification costs while pricing power shifts toward vendors with pre-certified sovereign infrastructure. This regulatory compression elevates total delivered cost for foreign operators lacking localized encryption compliance.
Pricing Analysis
Margin tightening in mid-market segments reflects NAND cost volatility and subscription-model displacement of perpetual licenses. Three-tier pricing structure across premium NVMe arrays, standard SAS configurations, and economy SATA tiers tracks certification grade and after-sales bundling intensity. Cost-down pressure on cloud storage contracts accelerates because South African retailers and Nigerian banks demand consumption-based flexibility. Government and healthcare verticals show least price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Certified storage administrator scarcity in Malaysia, Vietnam, and Philippines assembly hubs constrains localized support node expansion. Manufacturing draws from NAND fabrication concentrated in South Korea, Taiwan, and China, with controller silicon dependency on TSMC and Samsung foundry capacity. Single-source vulnerability in advanced node semiconductor supply elevates delivery risk for NVMe-equipped arrays. Distribution runs through Dubai and Johannesburg logistics clusters serving Gulf and sub-Saharan African markets respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a magnetic-to-flash transition inflection, with NVMe interfaces displacing legacy SAS and SATA infrastructure across financial and healthcare verticals.
For Market Incumbents: Acquire sovereign cloud certification assets to defend government and healthcare verticals against hyperscaler encroachment. Deepen backward integration into NAND supply relationships to buffer margin compression from flash memory cost volatility. Prioritize localized key management capabilities that satisfy SFDA and MOHAP encryption segregation requirements.
For New Entrants and Emerging Players: Direct-to-channel partnerships with managed service providers in Cairo and Lagos offer lowest-friction entry into mid-market subscription demand. Target Ethiopian and Kenyan educational institutions with cost-optimized SATA configurations ahead of regulatory maturation. Lead with consumption-based pricing to displace capital expenditure cycles among price-sensitive African retailers.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated hardware specialists with sovereign cloud partnerships and East African distribution reach. Long-term viability hinges on sustained regulatory fragmentation that privileges localized infrastructure over global hyperscale standardization. Watch for NAND pricing stabilization as inflection signal for margin recovery in solid-state array segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | MOHAP and SFDA mandates require physically segregated Emirati and Saudi zones with localized encryption. |
| NVMe Platform Integration | Dubai financial exchanges and Johannesburg trading floors demand sub-100-microsecond latency fabrics. |
| East African Geographic Expansion | Underpenetrated Ethiopian and Kenyan markets present first-mover advantages ahead of regulatory maturation. |
| Subscription Monetization Transition | Mid-market South African retailers and Egyptian telecom operators favor consumption-based capacity contracts. |
| Acquisition of Specialist Support Nodes | Certified administrator scarcity in secondary cities elevates value of localized technical capability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center procurement officers, storage infrastructure architects, sovereign cloud operations leads, and healthcare IT compliance directors combined with hyperscaler capex disclosures, SFDA certification databases, and MOHAP regulatory bulletins. Bottom-up deployment sizing and top-down vendor revenue triangulation validated segment-level estimates.
Data-stream reconciliation across shipment volumes, installation records, and contract value disclosures shaped the analytical framework. Segmentation modeled product type, interface protocol, end-user scale, and deployment architecture across the projection horizon. CAGRs derived from regression against historical adoption curves and regulatory mandate implementation timelines. NAND pricing indices and power infrastructure reliability scores informed cost sensitivity assumptions.
The model holds under continued data localization enforcement and stable semiconductor supply; deviation in NAND cost volatility or grid reliability deterioration would shift capacity deployment trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
North America AMH and Storage Systems Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Americas Flash Memory Market
Data Storage
North America SSD Caching Market
Data Storage
Next Generation Data Storage Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Digital Recording System Market
Data Storage
Solid State Array Market
Data Storage
Storage Area Network Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Blu-Ray Drive Market