
 Okra Seed Market | 2026-2036
Okra Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Okra Seed Market Analysis
Heat-tolerant germplasm is recalibrating okra seed economics as farmers replace conventional open-pollinated stock with F1 hybrid lines that withstand elevated temperatures. Syngenta Group leverages its tropical vegetable breeding stations to sustain proprietary hybrid dominance across South Asian markets. Mahyco anchors its position through deep backward integration into parental line development, while East-West Seed Group differentiates via smallholder-tailored varieties with compact plant architecture.
Okra seed comprises the dried, viable embryo of Abelmoschus esculentus, typically processed to moisture content below 10 percent and treated with polymer coatings or biological priming to enhance germination uniformity in warm, humid soils. Its primary commercial purpose centers on standardized crop establishment for fresh-pod production and processing markets. Hybrid seed commands the dominant margin pool due to proprietary genetics and repeat-purchase dependency, while organic certification segments occupy premium niche channels with tighter supply chains. Open-pollinated varieties retain volume relevance in subsistence and home gardening segments where seed-saving practices persist.
India's Central Seed Committee under the Ministry of Agriculture enforces germination standards and varietal release protocols that determine market access for new okra hybrids. BIS certification mandates and state-level seed inspectorates shape product quality expectations and channel legitimacy across domestic trade. Stakeholders must monitor evolving heat-stress tolerance benchmarks and seed treatment regulatory thresholds as climate adaptation becomes the decisive varietal selection criterion.
Market Dynamics
Climate adaptation is compressing variety replacement cycles as heat-tolerant germplasm displaces conventional open-pollinated stock across tropical vegetable belts. India's BIS seed certification mandates now incorporate elevated temperature stress benchmarks that filter market access for new hybrids.
Growth Catalysts
- Heat-stress breeding protocols:India's Central Seed Committee revised germination standards to mandate elevated temperature testing. This regulatory pivot accelerates farmer adoption of climate-resilient F1 hybrids over saved seed.
- Contract farming networks:Gujarat and Maharashtra procurement clusters anchor volume commitments from processing exporters. These arrangements lock in multi-season hybrid seed offtake with guaranteed buyback pricing.
- Polymer coating technology:Advanced seed treatments improve germination uniformity in humid subtropical soils. Treated hybrid lines command farmer willingness-to-pay premiums due to reduced replanting risk.
Market Restraints
- Parental line concentration:Proprietary inbred development remains concentrated among three breeding networks. This supply concentration limits price competition at the foundation seed tier.
- Input cost volatility:Hybrid seed production requires labor-intensive hand-pollination during narrow flowering windows. Rising agricultural wage rates in India's western belt compress margin structures for seed processors.
- Seed-saving persistence:Subsistence and home gardening segments retain open-pollinated varieties due to non-commercial use exemptions. This substitution threat caps hybrid penetration in certain district markets.
Strategic Opportunities
- Processing export corridors:Bangladesh and Nepal present underpenetrated demand for compact-canopy varieties suited to mechanized harvesting. Local distributor partnerships could unlock these adjacent markets.
- Organic certification channels:Premium niche segments reward untreated seed with documented provenance. Supply chain digitization via blockchain traceability is capturing price premiums in European import markets.
- Biological priming convergence:Integration of microbial inoculants with polymer coatings creates differentiated product positioning. This technology pairing addresses both abiotic stress tolerance and soil-borne pathogen suppression.
Industry Challenges
- Foundation seed multiplication timelines:BIS varietal release protocols require three-season adaptive trials before commercial registration. These certification delays compress effective patent protection windows for proprietary hybrids.
- Climate modeling integration:Breeding programs lack standardized phenotyping infrastructure for heat-stress validation. This capability gap forces reliance on inconsistent field trial networks across agro-climatic zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Okra Seed Market |
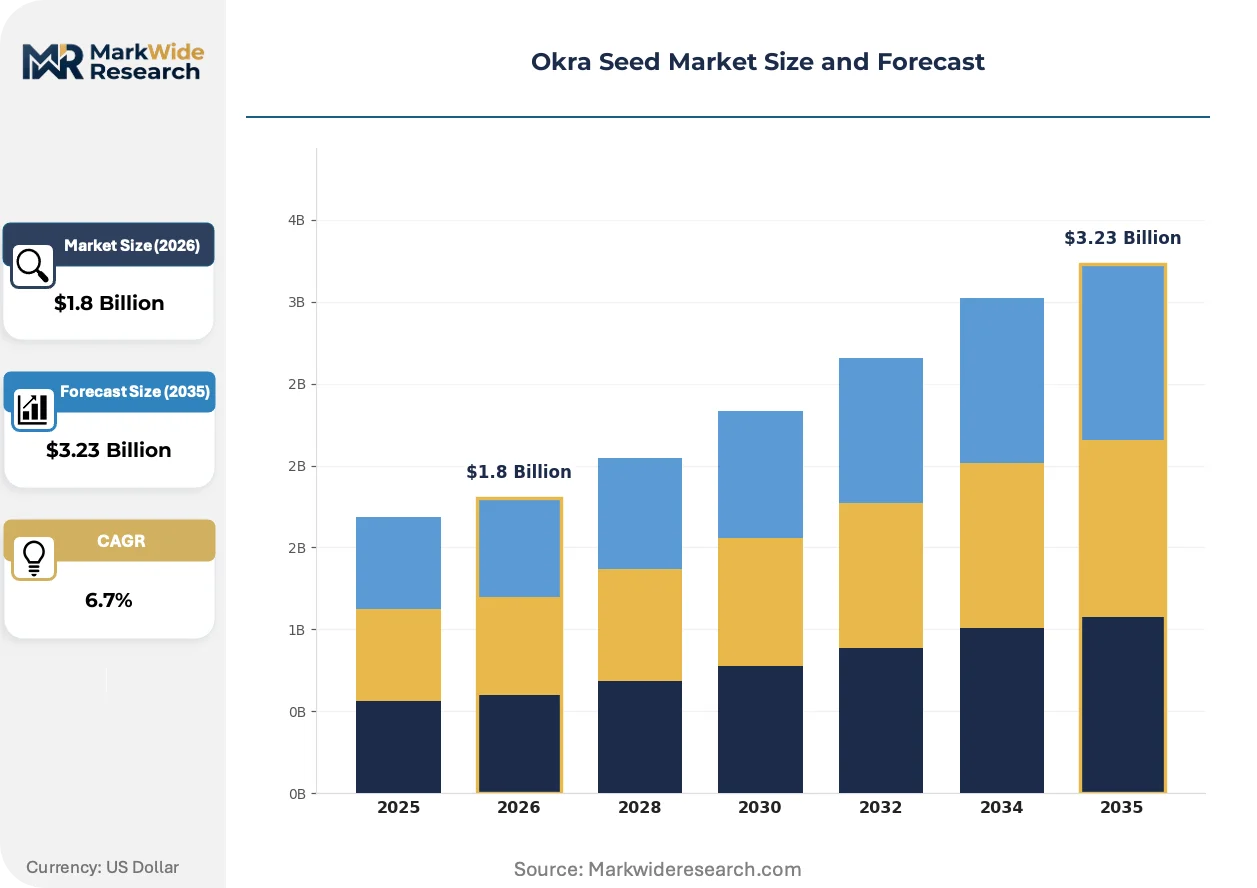
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Organic, Open-Pollinated, Conventional Packing Type: Bags, Bulk, Pouches, Bottles End Use: Agriculture, Horticulture, Home Gardening, Commercial Cultivation Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Advanta Seeds, Mahyco, Syngenta Group, UPL Limited, Sakata Seed Corporation, Bayer AG, Limagrain, East-West Seed Group, Corteva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Okra Seed Market Emerging Trajectories
Molecular breeding tools are compressing varietal development timelines while digital extension platforms reshape farmer seed selection behavior. These forces converge on climate adaptation as the decisive product attribute.
Marker-assisted selection is unifying quantitative trait loci mapping with conventional phenotyping pipelines. Tropical vegetable breeding stations deploy genomic selection to stack heat-tolerance loci into elite parental lines. This technology compression reduces hybrid development cycles from eight seasons to five, accelerating proprietary variety turnover.
India's BIS seed certification framework now mandates digital traceability tags for all certified okra seed lots. This regulatory requirement forces seed processors to upgrade packaging and inventory systems. Small and mid-scale processors in Gujarat face compliance cost pressure while integrated operators capture channel consolidation benefits.
Farmer seed sourcing is fragmenting across multiple channels as agri-input retailers, cooperative societies, and direct-to-farm digital platforms compete for wallet share. Cooperative procurement in Maharashtra's vegetable belts is losing volume to mobile-enabled distributor networks offering credit-linked seed purchases. This channel rotation is most visible in districts with high smartphone penetration and active farmer producer organization membership.
Okra Seed Market Segmentation
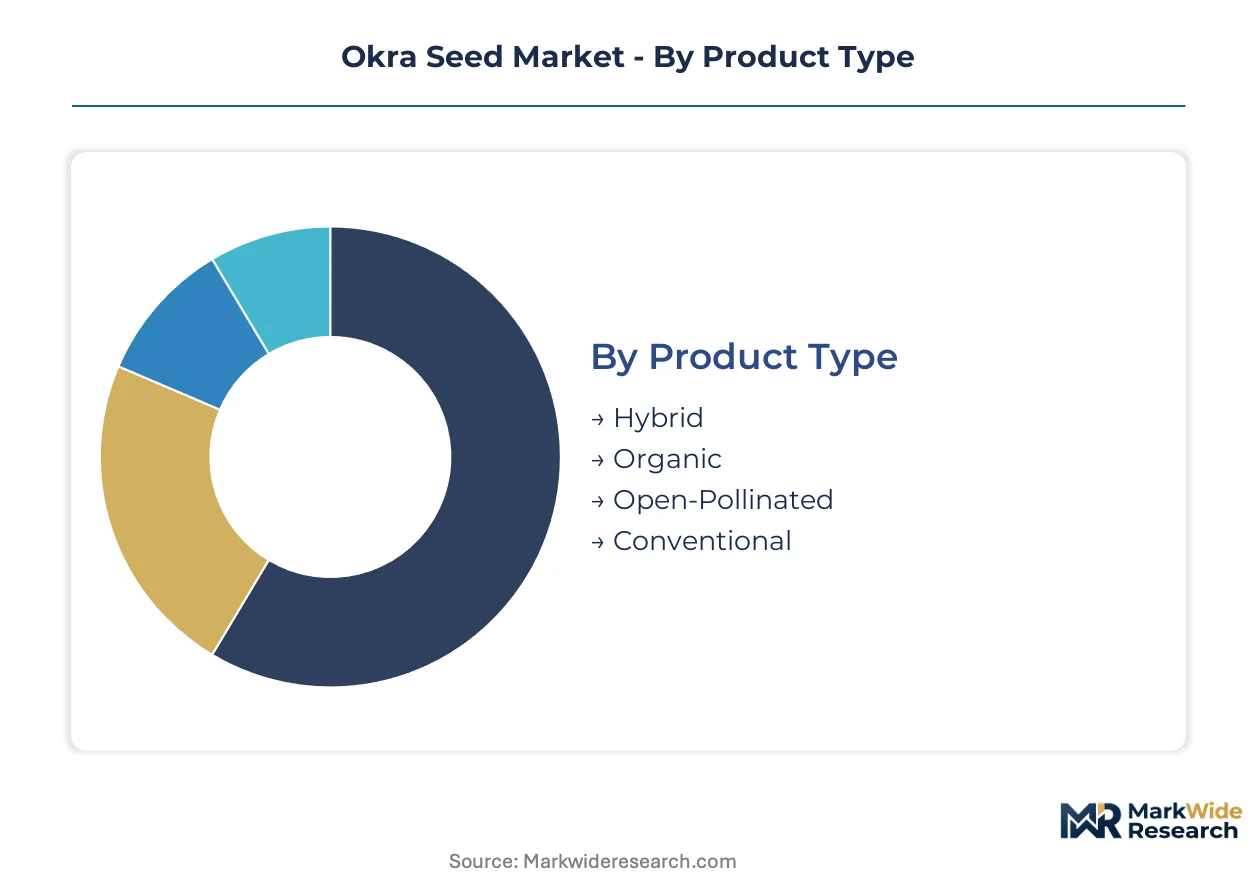
Okra seed segmentation reflects divergent supply chain configurations across germplasm types, packaging formats, and channel structures. Each dimension carries distinct margin profiles and regulatory requirements that shape procurement patterns among commercial operators and smallholder networks.
Product Type:
Proprietary germplasm development concentrates among integrated breeding networks, concentrating margin capture at the F1 hybrid tier while open-pollinated lines compete on accessibility.
- Hybrid:F1 hybrids incorporate stacked heat-tolerance loci through marker-assisted selection, delivering elevated temperature germination uniformity. Demand clusters in Gujarat and Maharashtra contract farming networks where processing exporters mandate varietal consistency for pod uniformity standards.
- Open-Pollinated:Farmers retain seed-saving rights under India's Plant Variety Protection Act, sustaining volume in subsistence districts. BIS certification exempts non-commercial saved seed, limiting formal channel penetration in certain talukas.
- Organic:Untreated seed with documented provenance captures premium positioning in European import corridors. Supply chain digitization via blockchain traceability is becoming mandatory for certification compliance.
- Conventional:Standard polymer-coated lines without biological priming occupy mid-tier price positioning. Gujarat processors dominate this segment through established distributor relationships.
Hybrid absorbs the bulk of installed capacity; organic is expanding most quickly.
Packing Type:
Packaging configuration tracks customer scale and shelf-life requirements, with bulk formats dominating processor procurement while unitized packaging serves fragmented retail channels.
- Bulk:Unpackaged seed in woven polypropylene sacks serves Maharashtra cooperative procurement at 50kg-plus volumes. This format minimizes per-unit packaging cost for multi-hectare commercial operators.
- Pouches:Laminated foil sachets with moisture barrier properties protect germplasm viability in humid subtropical storage conditions. Gujarat agri-input retailers favor this format for credit-linked smallholder transactions.
- Bags:Multi-layer paper bags with polyethylene liners balance breathability and moisture protection for regional distributor inventories.
- Bottles:Rigid PET containers with desiccant inserts target home gardening segments through organized retail placement.
Bulk commands the dominant volume position; pouches are climbing the fastest as mobile-enabled distributor networks expand.
End Use:
Application segmentation separates commercial pod production from non-commercial cultivation, with distinct input intensity and varietal performance requirements across each tier.
- Commercial Cultivation:Contract farming arrangements in Gujarat's vegetable belts specify hybrid varieties with compact canopy architecture suited to mechanized harvesting. Processing exporters anchor volume through guaranteed buyback pricing mechanisms.
- Home Gardening:Non-commercial operators in urban peripheries prioritize seed-saving viability over yield optimization. This segment retains open-pollinated varieties despite lower per-hectare productivity.
- Agriculture:Broad-acre field production encompasses both rainfed and irrigated systems across India's central plateau.
- Horticulture:Intensive vegetable production systems with drip irrigation and precision nutrient management.
Commercial cultivation captures the dominant revenue pool; home gardening is gaining share fastest through urban periphery expansion.
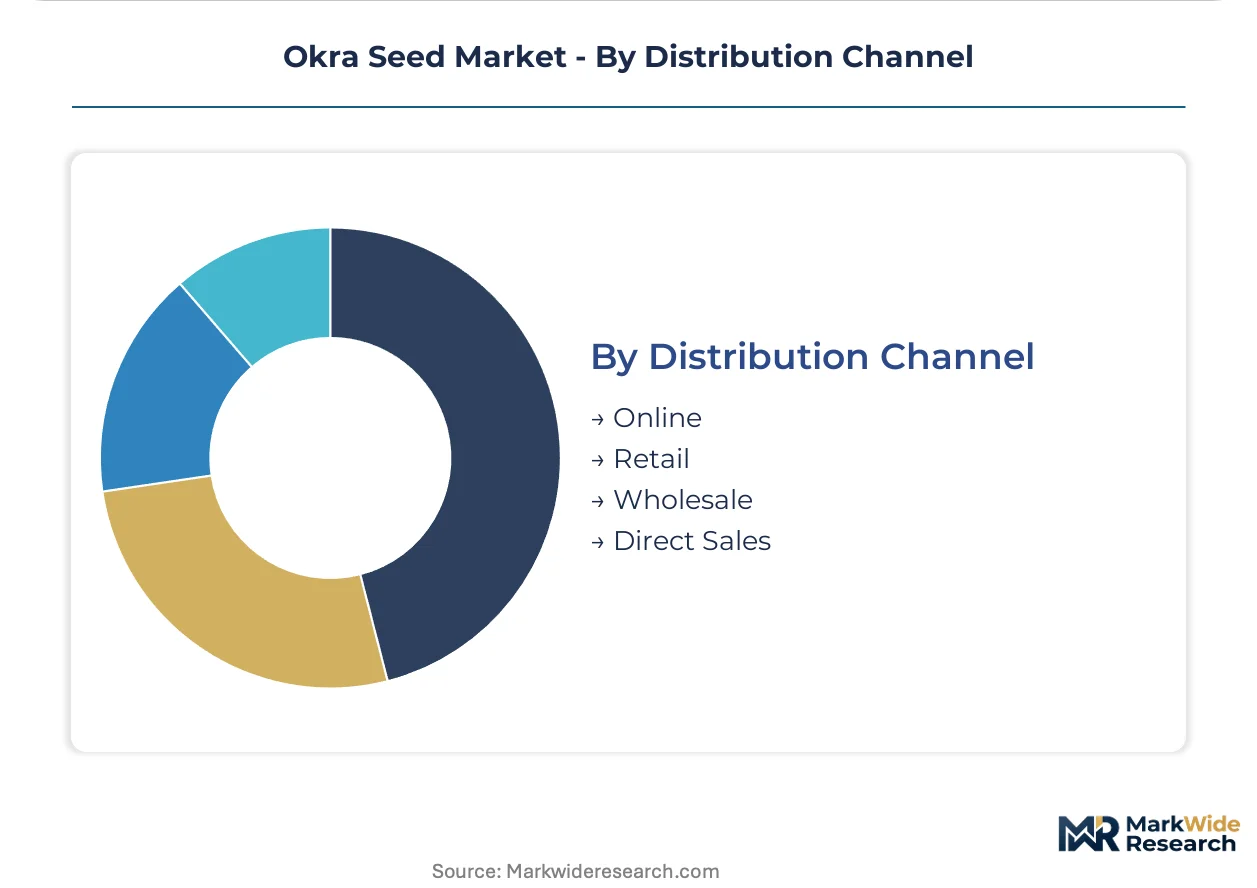
Distribution Channel:
Channel structure is fragmenting as digital platforms displace cooperative procurement, with credit integration becoming the decisive wallet-share determinant.
- Retail:Agri-input dealers in Maharashtra's vegetable belts maintain physical inventory for immediate farmer pickup. These outlets are losing volume to mobile-enabled competitors offering deferred payment terms.
- Online:Direct-to-farm platforms with embedded credit scoring now penetrate districts with high smartphone penetration. Gujarat farmer producer organizations are piloting collective procurement through these channels.
- Wholesale:Regional distributors maintain buffer stocks for taluka-level sub-distribution across western India.
- Direct Sales:Breeding company field staff engage large contract farming clusters for multi-season commitments.
Retail retains the largest transaction volume; online is expanding most quickly through credit-linked customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs the dominant share of okra seed procurement, with heat-tolerant hybrid adoption accelerating across Gujarat and Maharashtra contract farming networks. Secondary demand clusters are emerging in Bangladesh and Nepal as processing export corridors expand.
India
Commercial cultivation operators in Gujarat and Maharashtra are expanding hybrid okra seed procurement as climate-resilient varieties gain favor. India's BIS seed certification standards and rising heat-tolerant germplasm R&D steer demand toward premium hybrid lines. The Gujarat-Maharashtra belt anchors volume uptake through contract farming networks with processing exporters.
Bangladesh
Processing export demand for compact-canopy varieties suited to mechanized harvesting is penetrating Bangladesh's vegetable belts. The country's national agricultural regulator enforces seed quality protocols aligned with regional trade standards. Distributor partnerships in Dhaka and Rajshahi divisions are unlocking adjacent market access for heat-tolerant germplasm.
Nepal
Terai region vegetable producers are adopting Indian-origin hybrid okra lines for fresh-pod export to Indian processing markets. Nepal's seed quality oversight framework relies on cross-border certification recognition with BIS standards. Pokhara and Birgunj procurement clusters are piloting credit-linked seed distribution through mobile-enabled networks.
Thailand
Tropical vegetable breeding stations in Thailand's central plains are developing heat-stress germplasm for regional export. The country's agricultural ministry mandates varietal performance trials before commercial release. Chiang Mai and Nakhon Pathom research clusters are collaborating with South Asian seed networks on abiotic stress tolerance protocols.
Vietnam
Mekong Delta vegetable cooperatives are trialing heat-tolerant okra hybrids for diversification from rice-dominated rotations. Vietnam's plant variety protection office enforces distinctness-uniformity-stability testing for imported germplasm. Can Tho and An Giang province extension networks are integrating digital seed sourcing platforms for smallholder procurement.
Okra Seed Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated breeding networks capturing margin at the proprietary hybrid tier while regional processors compete on open-pollinated volume. Three breeding networks concentrate parental line development, creating supply-side constraints at the foundation seed tier. Strategic moves center on backward integration into parental line development and geographic expansion through distributor partnerships in adjacent South Asian markets.
Among integrated breeding specialists, Syngenta Group, Mahyco, and East-West Seed Group occupy positions exemplifying distinct competitive archetypes. Syngenta represents the tropical station network model leveraging proprietary germplasm dominance. Mahyco anchors the deep backward integration archetype through captive parental line development. East-West Seed Group exemplifies smallholder-tailored positioning with compact architecture varieties. These three entities collectively illustrate the strategic segmentation between premium hybrid proprietary control and accessibility-focused varietal design.
| Leading Market Players |
|---|
| Advanta Seeds |
| Mahyco |
| Syngenta Group |
| UPL Limited |
| Sakata Seed Corporation |
| Bayer AG |
| Limagrain |
| East-West Seed Group |
| Corteva |
| Others |
Supply Flow & Price Mechanics
Hand-pollination labor costs in India's western belt cascade through hybrid seed pricing tiers, with rising agricultural wage rates compressing margin structures for seed processors while contract farming networks absorb premiums through guaranteed buyback mechanisms. This input-cost pressure stratifies the market into proprietary hybrid lines commanding farmer willingness-to-pay premiums versus open-pollinated varieties retained in subsistence segments.
Pricing Analysis
Volume concentrates in open-pollinated lines while margin pools accrue to F1 hybrids. Three-tier pricing structure across premium hybrid, certified conventional, and saved-seed economy levels separates proprietary germplasm with stacked heat-tolerance loci from standard polymer-coated lines and farmer-retained stock. Pricing pressure stems from labor-intensive hand-pollination during narrow flowering windows. Smallholder networks in Gujarat and Maharashtra exhibit highest price sensitivity, while processing exporters anchoring contract farming clusters demonstrate lowest sensitivity due to varietal consistency mandates.
Supply Chain Analysis
Workforce availability constraints in India's Gujarat-Maharashtra belt and Thailand's central plains shape seed multiplication capacity. Parental line development concentrates in India, Thailand, and the Netherlands. Foundation seed production draws from proprietary inbred stocks, labor-intensive pollination protocols, and BIS-certified germplasm. Single-source vulnerability pervades the foundation seed tier where three breeding networks control parental line supply. Distribution runs through agri-input retailers, cooperative societies, and mobile-enabled direct-to-farm platforms competing for farmer wallet share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated breeding networks as BIS certification delays and climate-adaptation R&D requirements force sub-scale processors toward exit or acquisition.
For Market Incumbents: Cement proprietary hybrid dominance through captive parental line development and backward integration into heat-tolerance germplasm R&D. Expand tropical breeding station networks to compress varietal development timelines before patent protection windows narrow. Threat substitution from digital seed platforms demands channel control through credit-linked distributor partnerships.
For New Entrants and Emerging Players: Launch via mobile-enabled distributor networks with embedded credit scoring in Bangladesh and Nepal procurement clusters. Target compact-canopy varieties for mechanized harvesting in underpenetrated processing export corridors. White-space exists in organic certification channels with blockchain traceability for European import markets.
For Investors and Strategic Acquirers: BIS varietal release protocol revisions incorporating elevated temperature stress benchmarks are the leading indicator that climate-adaptation capability will separate viable targets from stranded assets. Long-term viability rests on breeding infrastructure ownership rather than contract manufacturing relationships. Acquisition target archetype: mid-scale processors with established distributor relationships and compliance-ready packaging systems. Watch for heat-stress phenotyping infrastructure investments as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parental Line Development | Mahyco's captive inbred development anchors margin capture at the foundation seed tier. |
| Tropical Breeding Station Network Expansion | Syngenta's South Asian stations sustain proprietary hybrid dominance through localized germplasm adaptation. |
| Digital Traceability Platform Deployment | BIS-mandated certification tags force packaging upgrades that favor integrated operators over small-scale processors. |
| Biological Priming Technology Convergence | Microbial inoculant integration with polymer coatings creates differentiated positioning against commodity seed treatments. |
| Credit-Linked Distributor Partnership | Mobile-enabled platforms with embedded scoring displace cooperative procurement in Maharashtra's vegetable belts. |
Methodological Framework
Regulatory filings with India's Central Seed Committee, BIS certification databases, and customs trade records formed the secondary backbone, cross-referenced against primary interviews with breeding station directors, seed processing plant managers, and cooperative procurement officers. Bottom-up triangulation aggregated contract farming volume commitments and distributor inventory flows, while top-down validation referenced germplasm registration databases and varietal release protocols. Primary fieldwork encompassed Gujarat and Maharashtra vegetable belt site visits.
Bottom-up modeling traced hybrid seed offtake through contract farming networks and retail channel shipments, while top-down analysis calibrated against processing export volumes and fresh-pod production estimates. Segmentation dimensions spanned germplasm type, packaging configuration, and distribution channel structure across the projection horizon. CAGRs derived from historical replacement cycle compression and climate-adaptation adoption curves, with forecast inputs including BIS regulatory revision timelines and heat-stress breeding program advancement rates.
The model assumes a particular technology adoption path; alternative pathways for marker-assisted selection and genomic selection convergence would alter the outlook if phenotyping infrastructure gaps persist unresolved. Forecasts reflect assumptions around regulatory compliance cost trajectories and labor cost inflation in seed multiplication zones. Material deviation in BIS certification timeline extensions or breakthrough open-pollinated heat-tolerance germplasm warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Avena Sativa Market
Seeds
South America Vegetable Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Safflower Seeds Market
Seeds
Sri Lanka Seed Market
Seeds
India Forage Seed Market
Seeds
Nepal Seeds Market
Seeds
Custom Selected Seed Market
Seeds
Flax Crop Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Vegetable Seed Protein Market