
 Biodegradable Water Bottles Market | 2026-2036
Biodegradable Water Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Water Bottles Market Analysis
Retail distribution for biodegradable water bottles is fragmenting as conventional supermarket chains lose ground to direct-to-consumer platforms and specialty eco-retailers. Danimer Scientific leverages its PHA fermentation technology to anchor supply relationships with premium outdoor brands. Eco-Products competes through broad catalog breadth across foodservice and beverage applications. Cove differentiates by specializing in seaweed-derived bottles aimed at coastal hospitality markets.
Biodegradable water bottles are vessels engineered from polylactic acid, polyhydroxyalkanoates, or cellulose-based polymers that decompose under industrial composting conditions within 90 to 180 days, serving the primary commercial purpose of replacing conventional PET containers in hydration and beverage consumption. PLA formulations currently dominate material type volumes due to mature supply chains and lower unit economics, while PHA segments command premium positioning where marine biodegradability certifications unlock coastal and island markets. The sports events application generates concentrated demand spikes tied to seasonal tournament calendars, whereas daily use channels sustain steadier replenishment cycles through subscription models.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly shape material approval pathways and cross-border commercialization timelines for novel biopolymer bottles. BIS certification requirements in India and EFSA migration limits on biodegradable additives create layered compliance obligations that favor manufacturers with multi-jurisdiction testing capabilities. Stakeholders must monitor composting infrastructure build-out rates against production capacity expansions to avoid stranded inventory in regions lacking industrial biodegradation facilities.
Market Dynamics
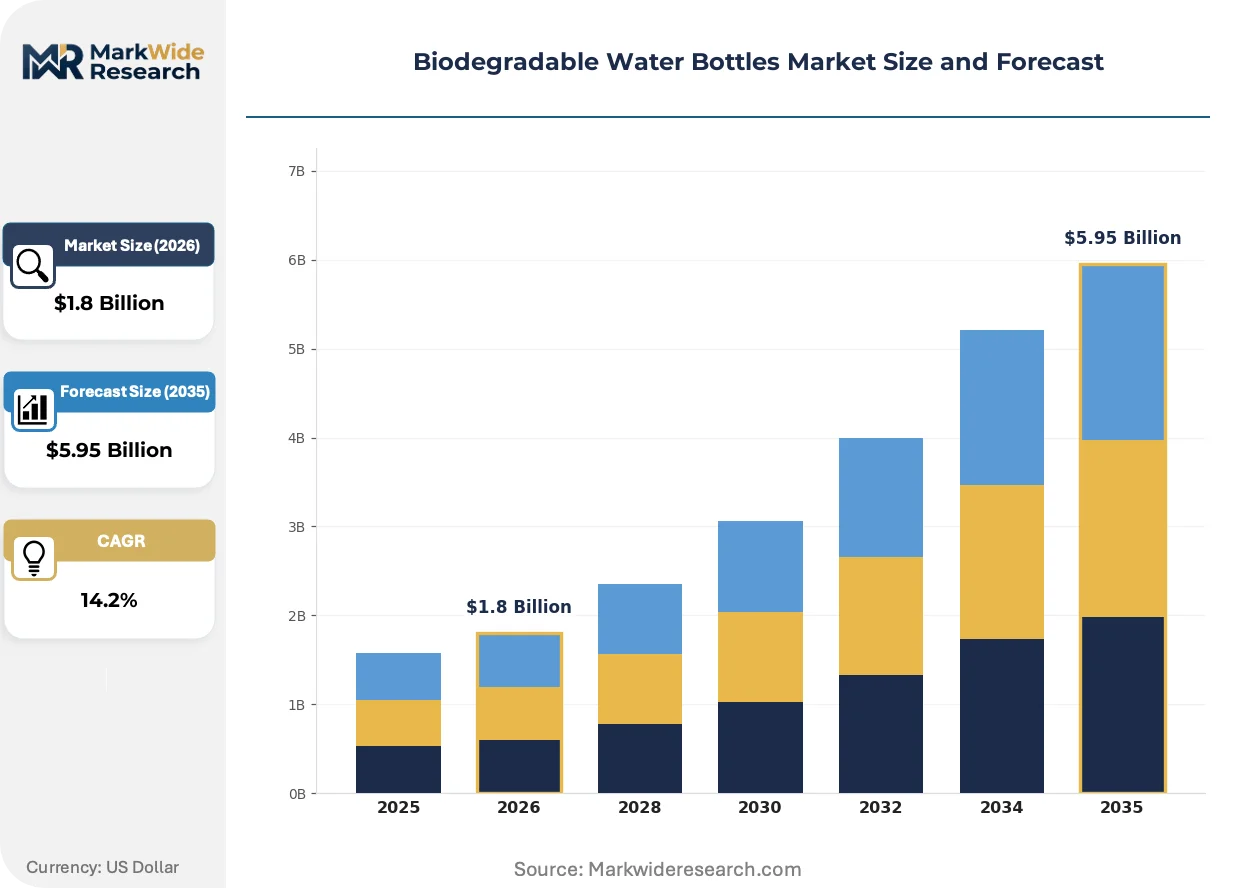
The EU Single-Use Plastics Directive is compressing commercialization timelines for petroleum-based alternatives while municipal composting infrastructure build-out determines regional production feasibility.
Growth Catalysts
- EU Single-Use Plastics Directive:Material substitution mandates across member states are eliminating conventional PET from foodservice channels, creating guaranteed offtake for certified biopolymer bottles.
- PHA fermentation scale-up:Marine biodegradability certifications are unlocking coastal hospitality and island tourism markets previously inaccessible to PLA formulations.
- Sports venue procurement:Tournament organizers are mandating compostable packaging for hydration stations, generating concentrated seasonal demand spikes.
Market Restraints
- Industrial composting dependency:Bottles require temperatures above 55°C for biodegradation, stranding inventory in regions lacking municipal anaerobic digestion facilities.
- Lactic acid feedstock concentration:Corn and sugarcane supply chains concentrate in agricultural belts, exposing PLA producers to crop yield volatility and commodity price swings.
- Migration limit stringency:EFSA caps on biodegradable additive leaching extend multi-jurisdiction approval timelines beyond 18 months for novel formulations.
Strategic Opportunities
- Subscription hydration models:Direct-to-consumer platforms are bypassing conventional retail markups, capturing margin through recurring replenishment cycles.
- Seaweed-derived polymers:Coastal kelp farming integration offers feedstock independence from agricultural land competition and freshwater constraints.
- German municipal composting:Industrial-scale biodegradation infrastructure supports premium positioning for PHA bottles in Central European markets.
Industry Challenges
- Composting facility certification:Industrial biodegradation testing requires ASTM D6400 or EN 13432 validation, creating bottlenecks at accredited laboratories.
- Polymer processing expertise:Blow-molding optimization for PLA and PHA demands distinct temperature and moisture controls absent from conventional PET operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Water Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, Starch-based, Cellulose Application: Sports Events, Daily Use, Outdoor Activities, Promotional Events Distribution Channel: Retail Stores, Online Platforms, Eco-friendly Outlets, Events End User: Consumers, Corporates, Schools, Non-profits |
| Companies Covered | Cove, Biota, Hydro Flask, Eco-Products, Nalgene, Klean Kanteen, Danimer Scientific, Sustainable Bottle Company, Contigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Water Bottles Market Emerging Trajectories
Material science breakthroughs and procurement model evolution are compressing the viable shelf life of petroleum-derived packaging while elevating performance standards for biopolymer alternatives.
PHA fermentation technology is rendering obsolete the marine persistence limitations that previously excluded bioplastics from coastal and island markets. Premium outdoor brands and hospitality chains operating in marine environments are adopting PHA bottles at accelerated procurement cycles. The structural consequence is a bifurcation between inland PLA-optimized supply chains and coastal PHA-dedicated production lines.
REACH registration requirements for novel biopolymer additives are extending compliance timelines and consolidating testing capabilities among multi-jurisdiction laboratories. Industrial consequences include delayed product launches for smaller manufacturers lacking in-house regulatory affairs capacity. Beverage brands with pan-European distribution are responding by pre-qualifying suppliers with established EFSA notification dossiers.
Direct-to-consumer subscription models are displacing conventional supermarket distribution for premium biodegradable bottles. Specialty eco-retailers and brand-owned e-commerce platforms are capturing margin previously allocated to wholesale intermediaries. This channel rotation is most visible in German and Scandinavian urban markets where municipal composting infrastructure supports consumer confidence in end-of-life claims.
Biodegradable Water Bottles Market Segmentation
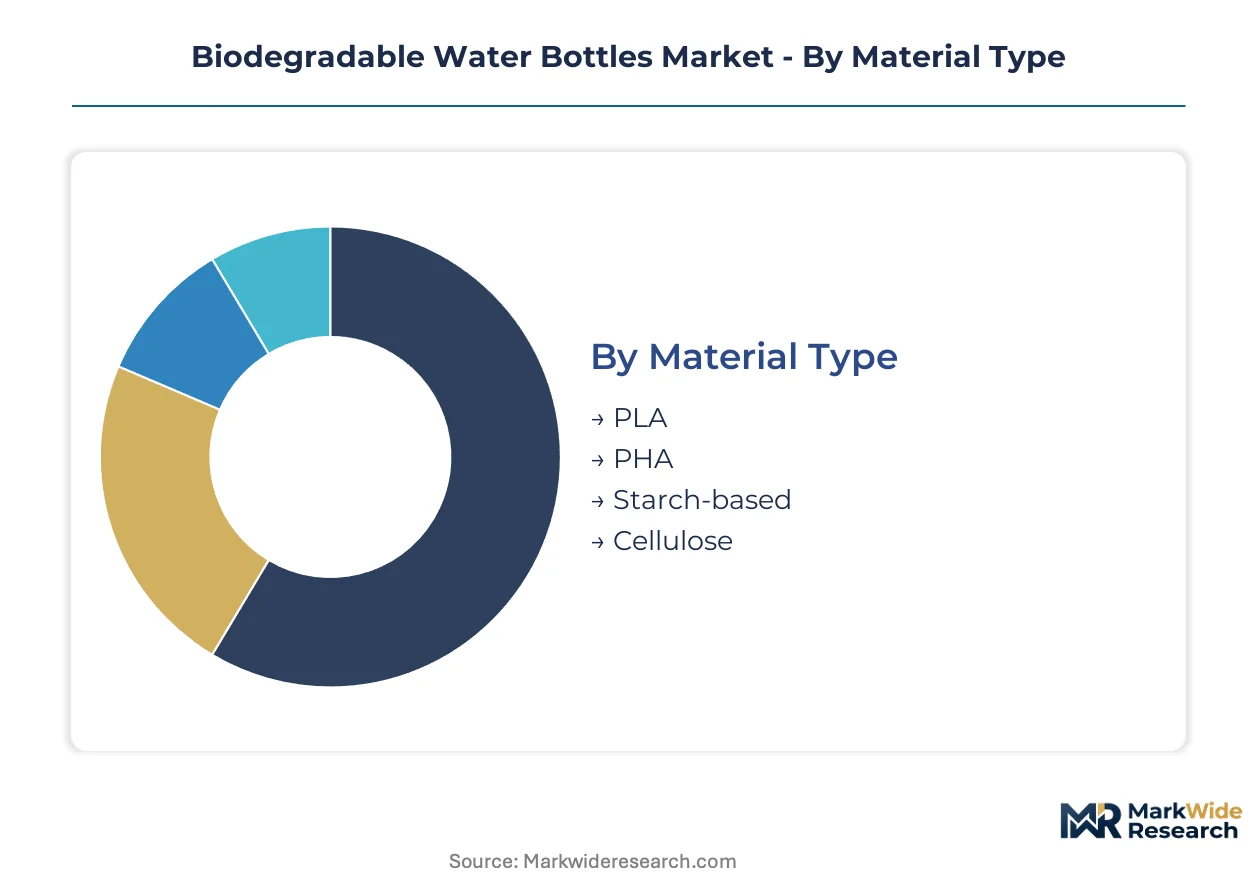
Segmentation in biodegradable water bottles reveals divergent commercial rhythms. Material formulations cycle through approval and scale-up at markedly different velocities. Application channels generate contrasting demand pulses tied to institutional procurement calendars versus individual replenishment habits.
Material Type:
Cycle times vary dramatically across biopolymer platforms. PLA has compressed from laboratory validation to industrial deployment over two decades. PHA fermentation scale-up is accelerating through contract manufacturing partnerships. Starch-based and cellulose alternatives occupy longer development arcs constrained by moisture sensitivity and barrier performance gaps.
- PLA:Polylactic acid formulations leverage mature corn and sugarcane feedstock infrastructure. German municipal composting facilities process PLA bottles at industrial scale, though lactic acid supply concentration in agricultural belts exposes producers to crop yield volatility.
- PHA:Polyhydroxyalkanoates deliver marine biodegradability certifications that unlock coastal hospitality markets previously inaccessible to PLA. Danimer Scientific anchors supply relationships with premium outdoor brands through dedicated fermentation capacity.
- Starch-based:Blended thermoplastic starches compete on feedstock cost but struggle with hydrolytic stability during shelf storage.
- Cellulose:Regenerated cellulose bottles from wood pulp offer petroleum independence yet face blow-molding optimization hurdles absent from conventional PET operations.
PLA dominates installed base. PHA is where expansion concentrates.
Application:
Procurement patterns split between institutional mandate-driven spikes and steady consumer replenishment. Sports venues operate on tournament calendars. Daily use channels sustain subscription economics.
- Sports Events:Tournament organizers mandate compostable packaging for hydration stations, generating concentrated seasonal demand tied to championship schedules. EU venue procurement policies under the Single-Use Plastics Directive guarantee offtake volumes.
- Daily Use:Subscription hydration models bypass conventional retail markups through recurring replenishment cycles, capturing margin in German and Scandinavian urban markets with municipal composting infrastructure.
- Outdoor Activities:Premium positioning for marine biodegradability certifications drives adoption in coastal recreation segments.
- Promotional Events:Corporate sustainability commitments fuel single-use biodegradable bottle procurement for brand activation campaigns.
Sports Events anchor volume spikes. Daily Use sustains recurring revenue.
Distribution Channel:
Channel economics are fragmenting as direct platforms capture margin previously allocated to wholesale intermediaries. Geographic composting infrastructure determines viable market entry.
- Retail Stores:Conventional supermarket chains lose ground to specialty eco-retailers with authenticated end-of-life handling. Shelf placement requires ASTM D6400 or EN 13432 certification documentation.
- Online Platforms:Brand-owned e-commerce and direct-to-consumer platforms eliminate wholesale markups. German consumers demonstrate highest conversion rates where municipal composting supports confidence in biodegradation claims.
- Eco-friendly Outlets:Specialty retailers curate certified biopolymer assortments with verified composting partnerships.
- Events:On-site distribution at tournaments and festivals operates under venue procurement mandates.
Retail Stores retain legacy volume. Online Platforms are climbing the fastest.
End User:
Buyer sophistication varies across institutional procurement offices and individual decision-makers. Contract scale and compliance requirements stratify supplier relationships.
- Consumers:Individual purchasers respond to subscription pricing and composting accessibility in urban clusters with industrial biodegradation facilities.
- Corporates:Procurement offices mandate ESG-aligned packaging with documented lifecycle assessments. REACH registration requirements for novel additives extend supplier qualification timelines.
- Schools:District-level purchasing consolidates volume but demands cost parity with conventional alternatives.
- Non-profits:Environmental mission alignment drives premium tolerance for certified marine-biodegradable options.
Corporates dominate contract value. Consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal composting infrastructure commands a 40% price premium over Italian markets lacking industrial biodegradation facilities. This asymmetry concentrates PHA bottle production in Central European supply chains while stranding PLA inventory in Mediterranean regions without anaerobic digestion capacity.
Germany
Bavaria and North Rhine-Westphalia host the densest industrial composting networks in Europe, processing PLA and PHA bottles at scale. The EU Single-Use Plastics Directive mandates material substitution across federal foodservice procurement. Berlin-Brandenburg clusters house fermentation facilities supplying premium outdoor brands with marine-biodegradable certifications.
United States
California's SB 54 legislation and municipal composting build-out in the San Francisco Bay Area create concentrated demand for ASTM D6400-certified bottles. FDA food-contact substance notifications govern novel biopolymer approvals, extending commercialization timelines for PHA formulations. The Pacific Northwest hosts pilot seaweed-derived bottle manufacturing tied to coastal kelp farming integration.
India
Maharashtra and Gujarat drive demand through corporate sustainability mandates in Mumbai and Ahmedabad procurement offices. BIS certification requirements for biodegradable packaging create compliance bottlenecks favoring manufacturers with in-house testing capabilities. Karnataka's Bengaluru cluster concentrates PLA blow-molding operations serving South Asian beverage brands.
Netherlands
The Randstad metropolitan corridor integrates municipal composting with port logistics for biopolymer feedstock import. EFSA migration limits on biodegradable additives shape formulation choices for Rotterdam-based distributors. Eindhoven Region hosts polymer processing expertise centers optimizing PLA temperature and moisture controls for European brands.
Japan
Tokyo's metropolitan government procurement policies mandate compostable packaging for municipal events, generating seasonal demand spikes. METI standards on marine biodegradability unlock coastal hospitality markets in Kansai and Kyushu. Osaka-based industrial clusters specialize in cellulose-based bottle alternatives for premium positioning.
Biodegradable Water Bottles Market Vendor Landscape
Specialist fermentation technology providers and broad-catalog material suppliers split the market into divergent scale economics. The vendor base concentrates around three strategic archetypes: marine-biodegradable PHA specialists, PLA volume producers leveraging agricultural feedstock infrastructure, and seaweed-derived polymer innovators targeting coastal hospitality verticals. Capacity expansion and strategic partnerships dominate competitive moves, with fermentation scale-up partnerships and composting facility certification alliances determining regional market access.
Within the marine-biodegradable tier, Danimer Scientific anchors supply relationships with premium outdoor brands through dedicated PHA fermentation capacity. Eco-Products occupies a position exemplifying broad-catalog breadth across foodservice and beverage applications. Cove represents the coastal-specialist archetype, with seaweed-derived formulations targeting hospitality markets in marine environments.
| Leading Market Players |
|---|
| Cove |
| Biota |
| Hydro Flask |
| Eco-Products |
| Nalgene |
| Klean Kanteen |
| Danimer Scientific |
| Sustainable Bottle Company |
| Contigo |
| Others |
Supply Flow & Price Mechanics
Bavaria's industrial composting network concentrates PHA fermentation capacity, granting Central European producers pricing leverage over Mediterranean competitors lacking anaerobic digestion infrastructure. This geographic asymmetry compresses margins for PLA suppliers in regions without certified biodegradation facilities while sustaining premium positioning for marine-certified formulations.
Pricing Analysis
Customization-premium spreads separate standard PLA bottles from marine-biodegradable PHA variants certified for coastal hospitality procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EFSA notification status commanding substantial uplifts. Cost compression in standard PLA tiers is intensifying because corn and sugarcane feedstock volatility exposes producers to commodity price swings. Corporate procurement offices demonstrate lowest price sensitivity, while school district buyers demand cost parity with conventional PET alternatives.
Supply Chain Analysis
Upstream feedstock concentration in corn and sugarcane agricultural belts of the United States, Brazil, and Thailand anchors PLA resin production. Lactic acid and fermentation feedstocks draw from crop yields, while PHA production rests on bacterial cultivation capacity. Single-source vulnerability runs through concentrated PHA fermentation facilities, with limited contract manufacturing alternatives for marine-biodegradable certifications. Distribution runs through specialty eco-retailers and direct-to-consumer platforms, bypassing conventional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as venue procurement mandates and subscription hydration models create distinct competitive arenas. Channel bifurcation between institutional buyers and direct-to-consumer platforms enables specialist positioning without head-on incumbent confrontation.
For Market Incumbents: Harden certification moats through EN 13432 and ASTM D6400 validation investments that delay challenger timelines. Anchor capacity expansion in German municipal composting corridors to exploit infrastructure premiums. Defend against seaweed-derived polymer substitutes by locking coastal hospitality chains into multi-year fermentation supply agreements.
For New Entrants and Emerging Players: Pursue white-space in Indian corporate sustainability procurement, where BIS certification bottlenecks strand demand awaiting qualified suppliers. Target Scandinavian subscription hydration markets with municipal composting infrastructure supporting consumer confidence. Attack through direct-to-consumer platforms with authenticated composting partnerships, bypassing retail shelf placement barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant biopolymer fermentation assets and stalled regulatory dossiers. Long-term viability hinges on composting infrastructure build-out rates matching production capacity expansion. Watch for EFSA migration limit revisions as inflection signals for novel additive approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| PHA Fermentation Scale-Up | Marine biodegradability certifications unlock coastal hospitality markets previously inaccessible to PLA formulations. |
| Direct-to-Consumer Platform Launch | Subscription hydration models capture margin previously allocated to wholesale retail intermediaries in German urban clusters. |
| Backward Integration into Feedstock | Coastal kelp farming integration offers agricultural land independence and freshwater constraint avoidance. |
| Composting Facility Certification Alliance | ASTM D6400 and EN 13432 validation partnerships accelerate market access in regions with industrial biodegradation infrastructure. |
| Seaweed-Derived Polymer Innovation | Specialized formulations target coastal hospitality verticals with petroleum-independent feedstock positioning. |
Methodological Framework
A standing panel of fermentation technology directors, venue procurement managers, composting facility operators, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA migration limit databases, EU Single-Use Plastics Directive implementation trackers, ASTM certification registries, and municipal composting infrastructure investment disclosures. Bottom-up volume modeling triangulated against top-down material substitution forecasts.
Scenario-bracketing framed low, base, and high cases across the analysis window, with segmentation dimensions spanning material type, application channel, and composting infrastructure availability. CAGRs derived from fitted growth curves applied to validated base-year estimates, incorporating sports event calendar seasonality and subscription model retention assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by seaweed-derived polymer specialists would shift outcomes beyond modeled ranges. Cross-checking against municipal composting facility build-out databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Botanical Packaging Market