
 Organic Whey Protein Market | 2026-2036
Organic Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Whey Protein Market Intelligence
E-commerce distribution for organic whey protein is fragmenting as direct-to-consumer subscriptions, Amazon storefronts, and specialty health platforms pull volume from traditional retail. Milk Specialties Global leverages its captive whey processing infrastructure to control ingredient quality from farm to powder. NOW Health Group Inc. competes through broad SKU breadth across isolate, concentrate, and hydrolyzed formats. Glanbia plc anchors European supply with integrated dairy operations spanning Ireland and the Netherlands.
Organic whey protein is the soluble protein fraction separated from organic milk during cheese manufacturing, typically containing 80-90% protein by dry weight in concentrate form and exceeding 90% in isolate form, with biological value scores near 104 due to its complete essential amino acid profile. It serves primarily as a functional ingredient in sports nutrition, clinical nutrition, and premium food fortification applications. Isolate commands the highest margin pool among product types due to its superior protein density and lower lactose burden, while hydrolyzed variants represent the fastest-growing segment as pre-digested proteins gain traction among consumers with sensitivity concerns. Fitness enthusiasts and health-conscious consumers together absorb the majority of volume through online retail channels, where subscription models now lock in recurring purchases.
The USDA Organic seal governs feed, land management, and processing standards for US-sourced organic whey, while the EU Organic Regulation enforces comparable strictures across European production, and both frameworks are tightening traceability requirements that favor vertically integrated suppliers. These certification barriers elevate compliance costs for new entrants but simultaneously insulate incumbent producers from commodity whey price erosion. Stakeholders must monitor evolving organic livestock feed rules and emerging state-level climate disclosure mandates that could reshape sourcing economics across North American and European supply bases.
Market Dynamics
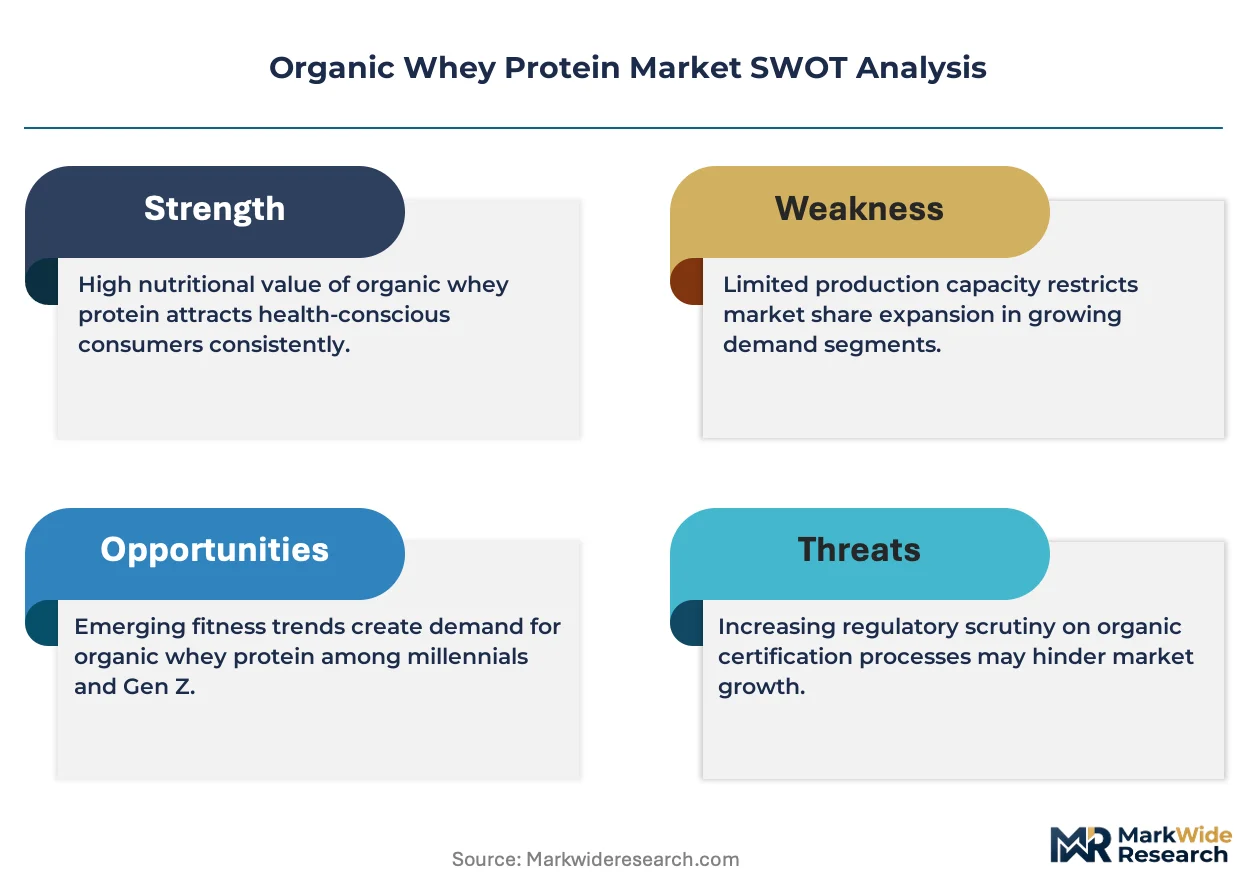
USDA Organic feed-source traceability mandates are compressing supplier margins while simultaneously locking in procurement advantages for vertically integrated dairy processors. The regulatory ratchet is forcing consolidation at the farm-gate level.
Growth Catalysts
- EU Organic Regulation traceability expansion:Batch-level digital tracking requirements favor processors with captive organic milk supply, accelerating backward integration into herd management.
- Clinical nutrition absorption:Hospital and long-term care facilities are expanding organic whey inclusion in enteral formulas as patient intolerance to conventional dairy rises.
- Grass-fed certification stacking:Dual-certified organic and grass-fed whey commands shelf-space premiums in US natural retail channels.
Market Restraints
- Organic feed cost volatility:Non-GMO soybean and corn prices swing with weather patterns in Argentina and Brazil, compressing processor margins unpredictably.
- Supply concentration in Ireland and Netherlands:European organic whey processing clusters around Glanbia and Arla Foods facilities, creating single-source vulnerability for brands.
- Lactose residual limitations:Concentrate formats retain 4-8% lactose, excluding significant portions of the clinically lactose-intolerant population from addressable demand.
Strategic Opportunities
- USDA Organic livestock feed rule revisions:Pending pasture-access requirements will displace commodity feedlot dairy, opening procurement windows for new organic herd entrants.
- Pediatric nutrition white space:Organic whey hydrolysate for infant formula remains underdeveloped relative to adult sports applications.
- Direct-to-consumer subscription platforms:Recurring revenue models bypass distributor markups and capture lifetime value data unavailable through wholesale.
Industry Challenges
- Organic certification timeline compression:USDA transition periods stretch 36 months, locking capital in non-revenue-generating herd conversion.
- Cross-contamination control capex:Dedicated organic whey processing lines require duplicate spray-drying infrastructure to prevent conventional dairy commingling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Whey Protein Market |
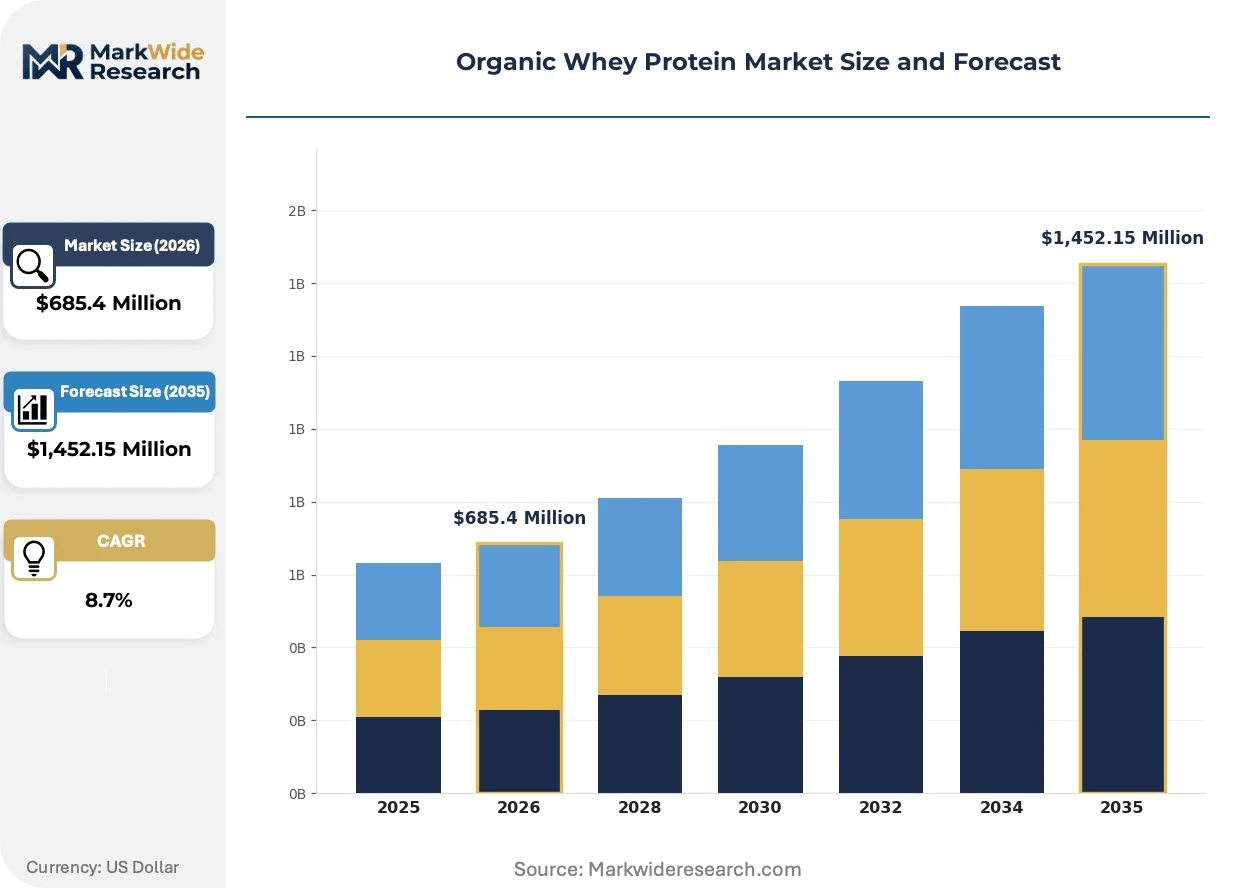
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolyzed, Blends End User: Fitness Enthusiasts, Athletes, Bodybuilders, Health-Conscious Consumers Packaging Type: Bags, Tubs, Sachets, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Milk Specialties Global, Nestle SA, Arla Foods amba, Vital Proteins LLC, NOW Health Group Inc., Glanbia plc, Organic Valley, Legion Athletics, Hilmar Cheese Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Whey Protein Market Strategic Shifts & Innovations
Membrane filtration advances and enzymatic hydrolysis are reshaping product architecture, while regulatory digitization and channel fragmentation rewrite go-to-market economics.
Microfiltration and ultrafiltration technology is collapsing the cost differential between organic whey isolate and concentrate production. Mid-sized sports nutrition brands are adopting these systems to bring isolate manufacturing in-house rather than sourcing from European toll processors. The equipment investment is compressing legacy margin structures that depended on geographic arbitrage between US milk costs and EU processing expertise.
EU Green Deal farm-to-fork traceability requirements are mandating blockchain-verified organic feed documentation by 2027. Irish and Dutch dairy cooperatives are deploying satellite pasture-monitoring to prove compliance. US brands sourcing European organic whey face audit burden expansion that favors long-term supply contracts over spot purchasing.
Subscription-based replenishment is displacing retail replenishment cycles among fitness enthusiasts. Brands like Ritual and Athletic Greens are bundling organic whey into broader supplement stacks, capturing share from single-SKU competitors. This pattern concentrates most visibly in coastal US metropolitan markets where direct delivery logistics density supports same-day or next-day fulfillment economics.
Organic Whey Protein Market Segmentation
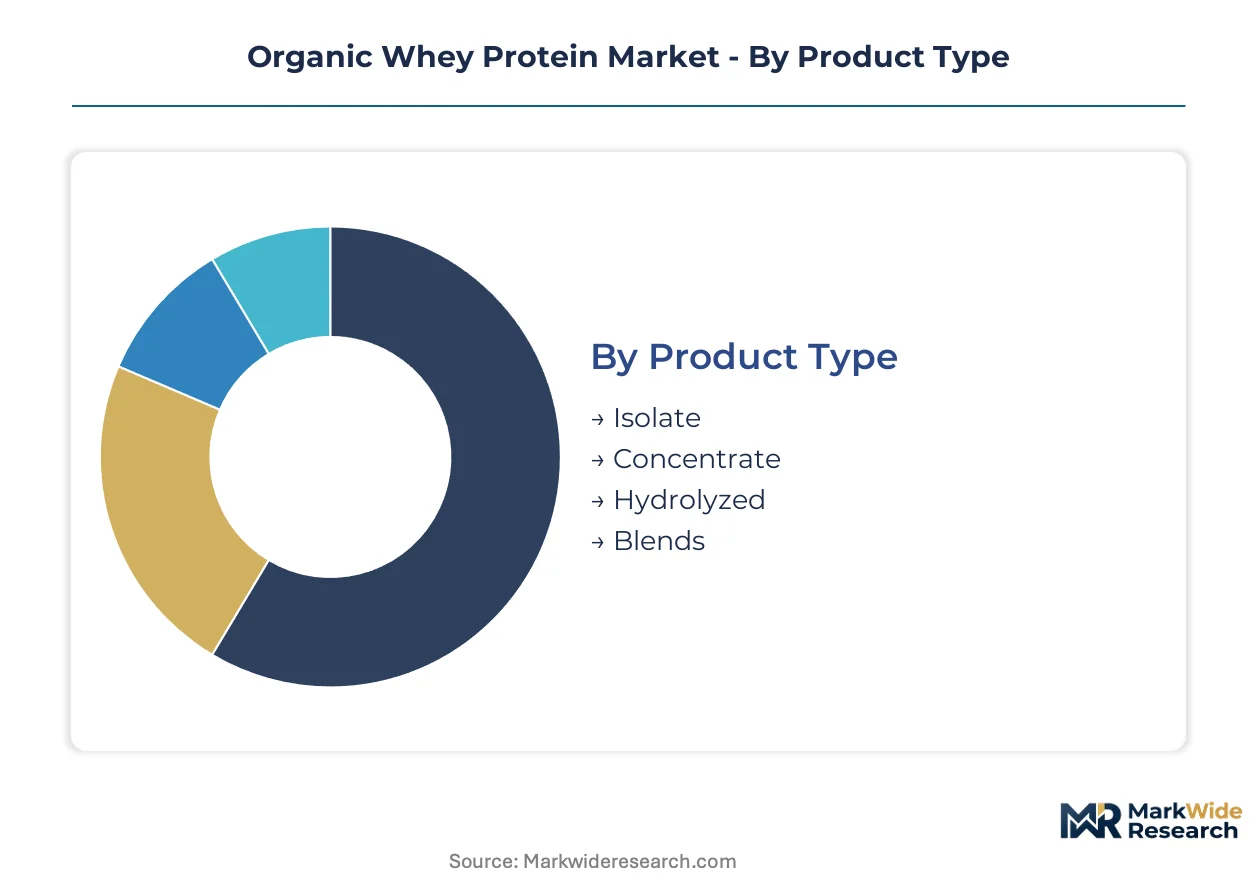
Organic whey protein segmentation reveals how processing intensity, consumer athletic commitment, and channel economics split addressable demand into discrete profit pools. Each dimension carries distinct margin structures and certification burdens that reshape supplier strategy.
Product Type:
Mature isolates dominate premium positioning while hydrolyzed formats emerge as the sensitivity-driven growth vector.
- Isolate:Exceeds 90% protein by dry weight with minimal lactose residue. Sports nutrition brands in the United States absorb the majority of volume as consumers prioritize protein density per serving.
- Concentrate:Contains 80-90% protein with 4-8% residual lactose. Price-sensitive fitness segments in Germany and the Netherlands tolerate the carbohydrate load for cost savings.
- Hydrolyzed:Pre-digested peptides reduce allergenic response. Clinical nutrition applications in Japanese hospital systems drive uptake among intolerance-prone populations.
- Blends:Custom ratios of isolate, concentrate, and hydrolyzed. Mid-tier sports brands in Brazil formulate proprietary combinations for taste-masked ready-to-drink applications.
Isolate handles the majority of throughput; hydrolyzed is the fastest mover on share.
End User:
Volume concentrates with recreational fitness participants while competitive athletes command formulation specificity.
- Fitness Enthusiasts:Recreational gym-goers seeking convenient protein supplementation. E-commerce subscriptions in California and Texas lock in recurring purchases through flavor variety.
- Athletes:Competitive performers requiring batch-tested, banned-substance-free certification. NCAA and Olympic testing protocols in the United States drive third-party verification demand.
- Bodybuilders:High-dose consumers prioritizing leucine content and amino acid completeness. Contest-prep cycles in Florida and Arizona spike seasonal procurement.
- Health-Conscious Consumers:Wellness-focused buyers seeking clean-label fortification. Organic certification stacking with grass-fed claims attracts premium grocery shoppers in Massachusetts and Washington.
Fitness enthusiasts generate the bulk of volume; health-conscious consumers are expanding most quickly as organic credentials penetrate mainstream retail.
Packaging Type:
Format selection tracks consumption occasion frequency and storage constraints across residential and travel contexts.
- Bags:Bulk formats for high-volume home use. Multi-kilogram pouches dominate CrossFit affiliate sales in Texas.
- Tubs:Rigid containers protecting powder integrity through repeated opening. Standard for Amazon pantry subscriptions in suburban United States markets.
- Sachets:Single-serve portability for travel and trial. Airport retail and hotel fitness centers in Dubai and Singapore stock premium organic variants.
- Pouches:Flexible stand-up formats reducing shipping cube. Direct-to-consumer brands in California favor pouches for sustainability messaging and freight efficiency.
Tubs command the largest installed base; pouches are climbing the fastest as sustainability credentials reshape packaging procurement.
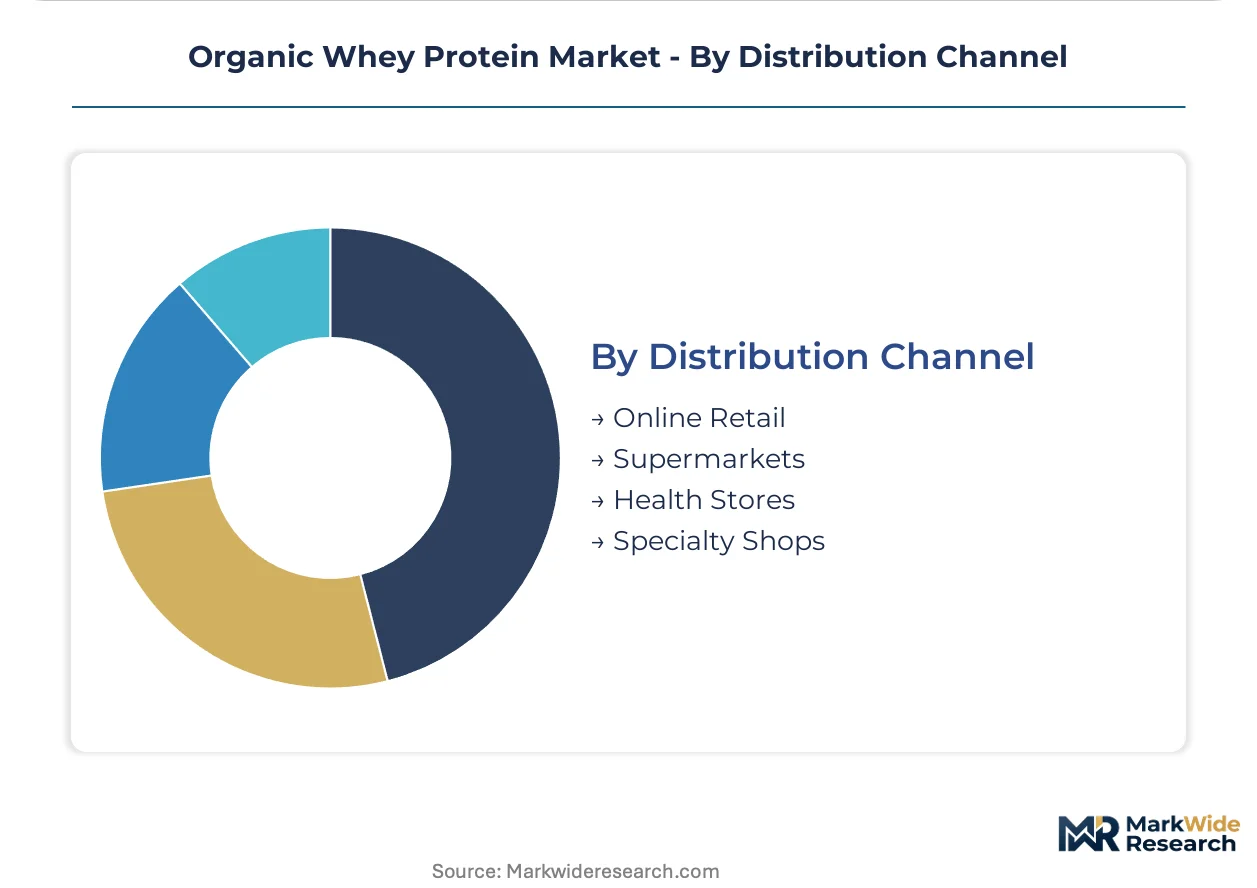
Distribution Channel:
Channel economics fragment as subscription platforms capture lifetime value that wholesale relationships cannot match.
- Online Retail:Brand-direct storefronts and Amazon marketplace presence. NOW Health Group and Ritual leverage subscription algorithms to predict replenishment timing.
- Supermarkets:Mass-market placement requiring slotting fee investment. Whole Foods Market and Sprouts Farmers Market curate organic whey assortments in coastal United States locations.
- Health Stores:Specialty retailers with educated staff recommendation power. GNC and Vitamin Shoppe locations in Florida and California prioritize grass-fed certified inventory.
- Specialty Shops:Independent supplement boutiques and CrossFit box retail. Affiliate gyms in Texas and Colorado stock house-branded organic whey for member convenience.
Online retail handles the majority of throughput; specialty shops are expanding most quickly as fitness community commerce tightens brand loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Irish and Dutch processors over US brands, reflecting captive organic milk supply and EU Green Deal traceability premiums. This asymmetry reshapes procurement geography as American sports nutrition companies absorb European whey at widening markups. Certification stacking and direct-to-consumer channel density further differentiate regional competitive positions.
United States
Grass-fed dairy sourcing and subscription platform maturity concentrate demand in California and Texas fitness communities. USDA Organic pasture-access requirements are tightening feed-source documentation, extending transition timelines for conventional herd conversions. CrossFit affiliate retail and Amazon pantry subscriptions in suburban Texas lock in recurring isolate purchases through flavor-rotation algorithms.
Germany
Price-sensitive fitness segments tolerate concentrate formats with residual lactose loads, prioritizing cost efficiency over protein density. EU Organic Regulation batch-level digital tracking mandates favor processors with integrated herd management systems. Bavarian dairy cooperatives are deploying satellite pasture-monitoring to satisfy 2027 blockchain-verified feed documentation requirements.
Netherlands
European organic whey processing clusters around integrated dairy operations spanning Ireland and Dutch facilities, creating single-source vulnerability for brands. ECHA chemical safety frameworks intersect with EU Green Deal farm-to-fork traceability, elevating audit burdens for US importers. Rotterdam logistics hubs expedite organic whey isolate distribution to German and French sports nutrition formulators.
Ireland
Glanbia anchors European supply with integrated operations leveraging grass-fed pasture advantages for premium positioning. EU Organic Regulation enforcement tightens traceability requirements that insulate incumbent producers from commodity whey price erosion. Cork and Limerick processing corridors specialize in isolate and hydrolyzed formats for clinical nutrition export markets.
Japan
Hospital and long-term care facilities expand organic whey inclusion in enteral formulas as patient intolerance to conventional dairy rises. PMDA pharmaceutical-grade manufacturing standards elevate processing compliance costs for imported isolate. Tokyo and Osaka metropolitan health systems drive hydrolyzed variant uptake among intolerance-prone geriatric populations.
Organic Whey Protein Market Key Industry Players
Vertically integrated dairy processors and specialized sports nutrition brands split the market into distinct capability tiers. Consolidation favors entities controlling captive organic milk supply from farm-gate through spray-drying infrastructure. Three archetypes dominate: integrated dairy cooperatives with backward herd ownership, toll-processing specialists leveraging membrane filtration scale, and direct-to-consumer brands bundling subscription algorithms with certification stacking. Competitive moves center on M&A targeting organic herd capacity and long-term supply contracts locking in traceability-compliant European whey.
Among integrated dairy processors, Milk Specialties Global and Glanbia plc exemplify archetypes built on captive whey processing infrastructure and geographic pasture advantages. NOW Health Group Inc. occupies a position within the SKU-breadth tier, spanning isolate, concentrate, and hydrolyzed formats across multiple certification schemes. These three entities represent the structural divergence between supply-control strategies and portfolio-differentiation approaches reshaping procurement relationships with sports nutrition and clinical nutrition end-users.
| Leading Market Players |
|---|
| Milk Specialties Global |
| Nestle SA |
| Arla Foods amba |
| Vital Proteins LLC |
| NOW Health Group Inc. |
| Glanbia plc |
| Organic Valley |
| Legion Athletics |
| Hilmar Cheese Co. Inc. |
| Others |
Cost & Logistics Intelligence
Cork and Limerick processing corridors in Ireland concentrate organic whey isolate capacity, translating captive grass-fed milk supply into premium pricing power over US brands dependent on European toll processing. This geographic asymmetry forces American sports nutrition companies to absorb widening markups or invest in backward herd ownership.
Pricing Analysis
Configured-to-order pricing for custom hydrolysate blends commands substantial premiums over standard isolate and concentrate SKUs. Three-tier pricing structure across premium isolate, standard concentrate, and economy hydrolyzed formats stratifies the market by certification density and protein purity. Cost compression in the concentrate tier is intensifying because organic feed price volatility in Argentina and Brazil squeezes processor margins. Fitness enthusiasts in Germany and the Netherlands exhibit highest price sensitivity, tolerating residual lactose loads for unit cost savings, while clinical nutrition buyers in Japan accept premium isolate pricing for pharmaceutical-grade compliance.
Supply Chain Analysis
Tariff exposure between the United States and European Union dairy processors dominates supply chain risk calculus for American brands sourcing Irish and Dutch organic whey. Geographic supply concentration in Ireland, the Netherlands, and Germany creates single-source vulnerability, with Glanbia and Arla Foods facilities controlling the majority of European processing capacity. Raw material dependencies on non-GMO soybean and corn feed, organic pasture land, and specialized membrane filtration equipment tether production economics to agricultural commodity cycles. Distribution runs through Rotterdam logistics hubs for European brands and direct-to-consumer subscription platforms for US market entrants, with blockchain-verified feed documentation mandates elevating audit burdens for spot purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic whey protein demand follows cyclical recovery patterns tied to fitness participation rates and clinical nutrition budget cycles, with post-pandemic gym membership resurgence and hospital formulary expansion driving volume normalization.
For Market Incumbents: Pre-empt margin erosion from membrane filtration cost compression by securing long-term organic milk supply contracts in Wisconsin and New York dairy corridors. Invest in dedicated organic processing lines to prevent cross-contamination liabilities that conventional dairy commingling creates. Certification stacking with grass-fed and regenerative agriculture claims defends premium positioning against emerging private-label entrants. For New Entrants and Emerging Players: Build out pediatric nutrition applications for organic whey hydrolysate, the most penetrable white space relative to saturated adult sports nutrition. Target health-conscious consumer segments in Massachusetts and Washington through subscription platforms that capture lifetime value data unavailable through wholesale. Partner with CrossFit affiliates and boutique fitness studios for community-anchored distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified dairy cooperatives seeking to monetize captive organic whey processing assets. Long-term viability hinges on vertical integration depth from farm-gate through spray-drying infrastructure, with 5-10 year returns favoring entities controlling pasture-access compliant herd capacity. Monitor USDA Organic livestock feed rule revisions as the inflection signal for new organic dairy entrant economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Herd Ownership | Captive milk supply insulates processors from EU toll processing markups and feed cost volatility. |
| Blockchain-Verified Feed Documentation Investment | EU Green Deal traceability mandates by 2027 favor early movers with satellite pasture-monitoring systems. |
| Direct-to-Consumer Subscription Platform Launch | Recurring revenue models bypass distributor markups and capture replenishment timing data in California fitness markets. |
| Clinical Nutrition Formulation Partnership | Hospital system enteral formula contracts in Japan and US long-term care facilities expand addressable demand beyond sports nutrition. |
| Membrane Filtration Technology Adoption | In-house isolate production collapses cost differentials with concentrate, compressing legacy European processor margins. |
Research Approach
The analysis maps organic whey protein sub-sectors spanning isolate, concentrate, hydrolyzed, and blended formats, each validated through dairy cooperative managers, sports nutrition brand procurement directors, clinical nutrition formulators, and membrane filtration equipment specialists. Primary interviews with these stakeholders combined with secondary validation from USDA Organic certification databases, EU Organic Regulation compliance filings, customs trade records, and SEC dairy processor disclosures. Bottom-up volume triangulation across product types, end-user segments, and distribution channels converged with top-down market sizing from organic milk production statistics.
Assumptions held organic certification standards and pasture-access requirements fixed across the analysis window, while feed cost volatility and membrane filtration adoption rates varied scenario-to-scenario. Segmentation dimensions modeled include product type, end-user athletic commitment level, packaging format, and channel economics, with CAGRs derived from historical organic dairy protein growth patterns and projected fitness participation normalization. Industry-specific forecast inputs incorporated organic herd conversion timelines and blockchain traceability compliance cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-sized sports nutrition brands would shift supply concentration and pricing power dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
US Hangover Cure Products Market