
 Electrolyte Powder Market | 2026-2036
Electrolyte Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyte Powder Market Insights
Fitness enthusiasts are redrawing demand patterns in the electrolyte powder category, pulling volume away from elite athlete segments toward everyday wellness consumers. PepsiCo Inc. leverages its massive beverage distribution network to push powdered hydration into convenience retail. Nestlé SA anchors its position through science-backed medical nutrition credentials inherited from its health science division. LMNT specializes in zero-sugar, high-sodium formulations that resonate with ketogenic and paleo diet adherents.
Electrolyte powder comprises water-soluble mineral salts—primarily sodium, potassium, magnesium, and calcium—formulated for rapid dissolution and ionic absorption to restore fluid balance and neuromuscular function. The powder format dominates manufacturing economics due to lower shipping weights, extended shelf stability, and flexible dosing compared to ready-to-drink alternatives. Among end users, athletes still occupy the largest revenue pool, though fitness enthusiasts represent the fastest-expanding segment as gym culture permeates mainstream demographics. The medical use application sustains premium pricing through clinical validation requirements and pharmacy channel control.
The FDA governs electrolyte powders sold as dietary supplements under DSHEA, while the FTC monitors advertising claims related to hydration performance and health benefits. Sports performance applications face additional scrutiny from NSF International and Informed Sport certification programs that test for banned substances. Stakeholders must monitor evolving clean-label standards and sugar-tax legislation across state and municipal jurisdictions, as these regulatory currents will determine which formulations retain shelf access and consumer trust.
Market Dynamics
Clean-label formulation mandates from the FDA and emerging state-level sugar-tax legislation are compressing ingredient sourcing flexibility, forcing manufacturers to rebuild supply chains around certified organic mineral salts and natural flavor systems.
Growth Catalysts
- DSHEA dietary supplement framework:The FDA's existing regulatory structure provides clear market entry pathways for electrolyte powders, reducing compliance uncertainty for new entrants while enabling rapid product iteration cycles.
- Fitness enthusiast segment expansion:Mainstream gym culture penetration across suburban demographics is pulling volume from elite athlete channels into higher-frequency, lower-dose consumption patterns that favor powder economics.
- Direct-to-consumer subscription infrastructure:Specialized fulfillment networks and recurring revenue platforms in the United States are capturing lifetime value through personalized dosing algorithms and flavor rotation programs.
Market Restraints
- Premium mineral salt input volatility:Certified organic sodium and potassium sources face agricultural yield fluctuations that compress margin structures for clean-label formulators.
- Pharmacy channel gatekeeping:Medical-use electrolyte powders require clinical validation documentation and pharmacist training investments that limit brand expansion beyond specialty retail.
- Ready-to-drink substitution threat:Convenience-oriented consumers in grab-and-go retail environments increasingly select bottled alternatives despite higher per-serving costs.
Strategic Opportunities
- Pediatric and geriatric hydration:Underpenetrated age-specific formulations targeting school lunch programs and long-term care facilities in the United States offer premium pricing potential through medical channel partnerships.
- NSF Certified for Sport convergence:Crossover demand from amateur endurance athletes seeking banned-substance verification is creating dual-certification SKUs that command shelf space in both specialty and mass retail.
- Functional beverage hybridization:Electrolyte-adaptogen and electrolyte-nootropic combinations are capturing wellness consumers seeking multi-benefit products through natural channel distribution.
Industry Challenges
- Clean-label certification timeline compression:NSF International and Informed Sport testing protocols require 8-12 week validation cycles that delay seasonal product launches and flavor extensions.
- Flavor stability chemistry expertise scarcity:Natural flavor systems without artificial preservatives demand specialized formulation talent that concentrates among a limited pool of beverage technologists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyte Powder Market |
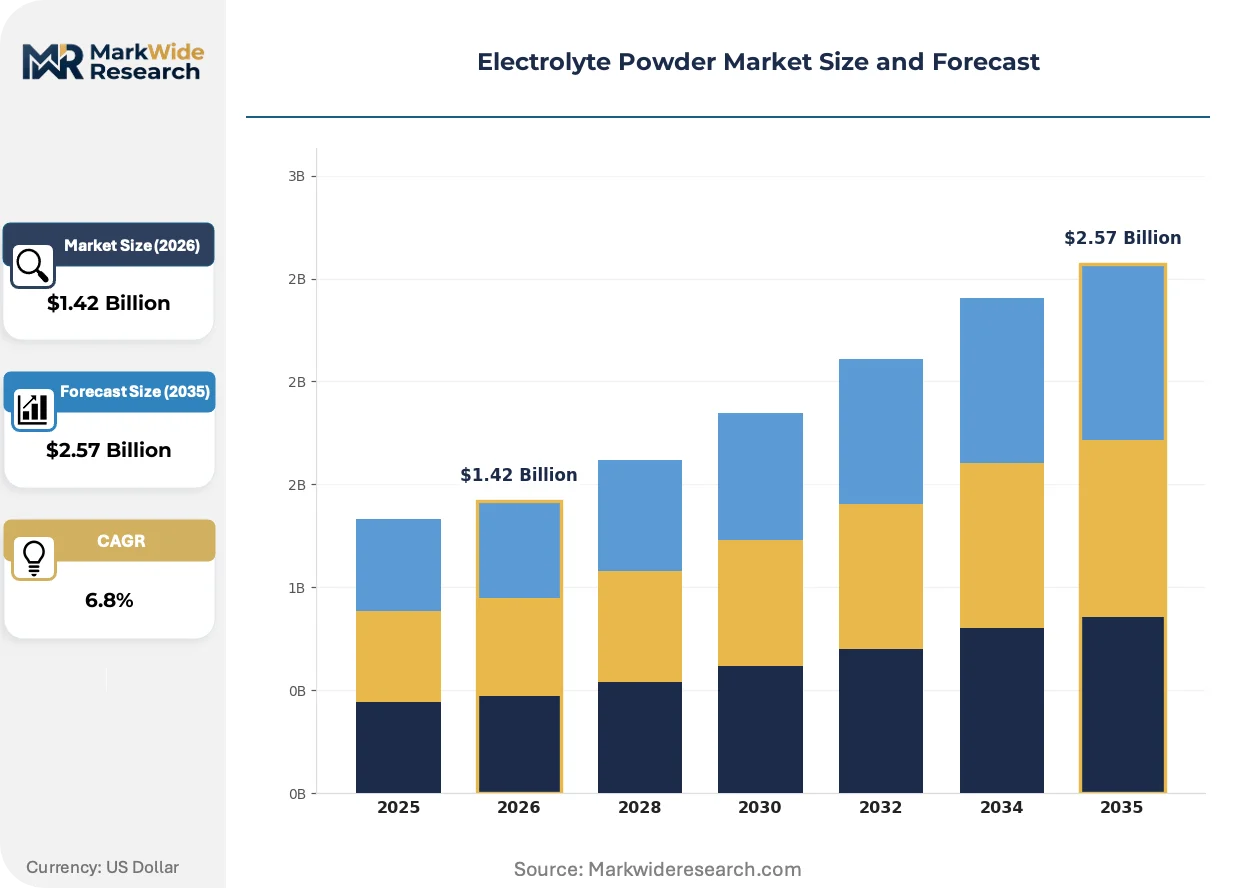
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Tablet End User: Athletes, Diabetics, Patients, Fitness Enthusiasts Application: Hydration, Nutritional Supplement, Medical Use, Sports Performance Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, Nestlé SA, Abbott Laboratories, Liquid I.V., LMNT, Nuun, Skratch Labs, Vitalyte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyte Powder Market Trends and Innovations
Formulation science and distribution architecture are converging to compress product development cycles while fragmenting consumption occasions across new demographic entry points. Three developments are actively restructuring competitive requirements.
Microencapsulation technology for hygroscopic mineral salts is miniaturizing. This process coats sodium and potassium particles with lipid barriers that prevent clumping during storage while enabling rapid dissolution upon contact with water. Functional beverage startups and legacy sports nutrition brands are adopting these systems to extend shelf stability without synthetic anti-caking agents. The technology is miniaturizing batch-size requirements, allowing pilot production runs that test regional flavor preferences before national scale-up.
REACH chemical registration requirements in Europe are tightening traceability obligations for electrolyte powder imports containing novel mineral chelates or bioavailability-enhancing compounds. Manufacturers must now document full substance dossiers for complexed magnesium and zinc forms that previously entered under simplified notification procedures. Sports nutrition distributors serving EU markets are responding by consolidating supplier relationships around pre-registered ingredient vendors with established safety data packages.
Subscription-based replenishment models are displacing traditional retail replenishment cycles among core fitness enthusiast buyers. Direct-to-consumer platforms capture consumption velocity data that enables predictive shipping algorithms, reducing stockout risk while building switching costs through flavor profile customization. This pattern concentrates in United States metropolitan markets where same-day or next-day delivery infrastructure supports just-in-time hydration supply.
Electrolyte Powder Market Segmentation
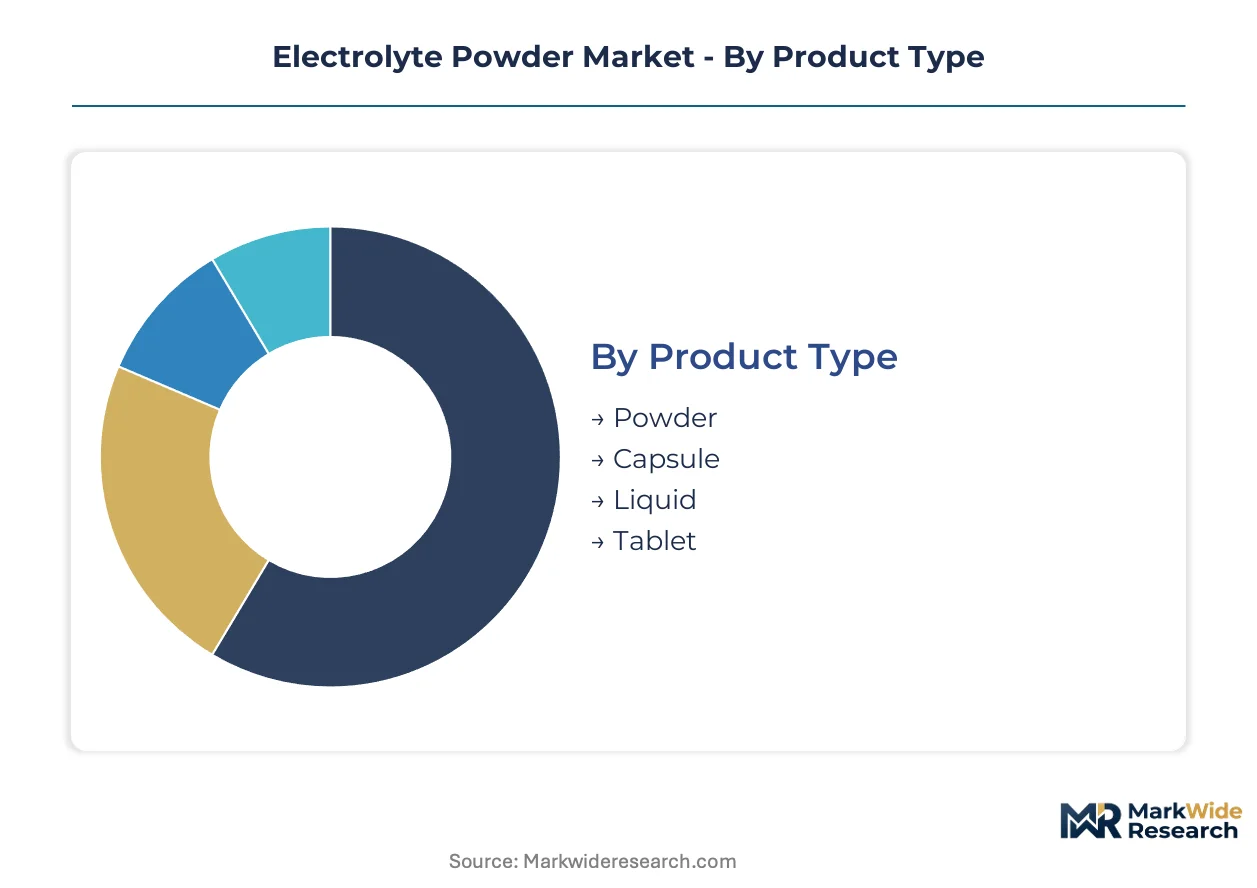
Electrolyte powder manufacturers calibrate formulation, packaging, and channel strategy against distinct consumption patterns that vary sharply by use case and buyer sophistication. Segment boundaries are blurring as fitness enthusiasts adopt medical-grade specifications and sports formulations penetrate pharmacy channels.
Product Type:
Powder formats dominate domestic manufacturing output across the United States, while capsule and tablet variants concentrate in export-oriented contract manufacturing facilities serving European and Asia-Pacific markets.
- Powder:Water-soluble mineral salts formulated for rapid dissolution and flexible dosing. Demand concentrates among fitness enthusiasts in United States metropolitan markets, where direct-to-consumer subscription platforms capture recurring replenishment cycles through personalized flavor algorithms.
- Capsule:Pre-measured mineral doses in gelatin or vegetable-based shells. Export-led demand from Germany and Japan favors this format for workplace and travel hydration, driven by portability requirements and portion control preferences.
- Liquid:Concentrated mineral solutions requiring dilution. Bottled concentrate production clusters in California and Florida facilities serving ready-to-drink hybrid formulations.
- Tablet:Effervescent or swallowable compressed mineral forms. United Kingdom and Australian buyers favor effervescent tablets for on-the-go use, though tablet economics struggle against powder shipping efficiency.
Powder commands the established base. The steepest expansion runs through capsule formats as European workplace wellness programs standardize portable hydration protocols.
End User:
Cost tier differentiation separates premium clinical formulations from mass-market sports nutrition, with reimbursement eligibility driving pricing architecture.
- Athletes:Elite and competitive sports professionals requiring NSF Certified for Sport verification. Demand concentrates in United States collegiate athletic programs and professional team training facilities, constrained by banned-substance testing protocols that extend procurement cycles.
- Fitness Enthusiasts:Recreational gym-goers and home workout adherents seeking clean-label, zero-sugar formulations. This segment climbs the fastest in United States suburban markets, where subscription models and flavor customization build switching costs.
- Diabetics:Individuals managing blood glucose through electrolyte balance. Pharmacy channel control in United States markets limits brand access without clinical validation documentation.
- Patients:Hospital discharge and chronic disease management populations. Long-term care facilities in Florida and Arizona represent concentrated demand for medical-grade powders with precise sodium-to-potassium ratios.
Athletes anchor premium pricing tiers. Fitness enthusiasts gain share fastest as gym culture permeates mainstream demographics.
Application:
Volume concentration favors hydration and sports performance, while margin concentration sits with medical use applications requiring clinical validation.
- Hydration:General fluid balance restoration for daily wellness and heat exposure. United States military and outdoor worker programs drive institutional procurement, with bulk powder contracts favoring domestic manufacturers.
- Sports Performance:Electrolyte replacement timed to training intensity and duration. Amateur endurance athletes in Colorado and Oregon represent expanding demand for dual-certification SKUs bridging specialty and mass retail.
- Nutritional Supplement:Broad-spectrum mineral intake for dietary gap coverage. Natural channel distribution in California and New York captures wellness consumers seeking adaptogen-electrolyte combinations.
- Medical Use:Clinically indicated electrolyte replacement for acute or chronic conditions. Pharmacy gatekeeping in United States markets sustains premium pricing through prescriber and pharmacist training investments.
Hydration commands volume leadership. Medical use captures margin expansion as clinical validation requirements limit competitive entry.
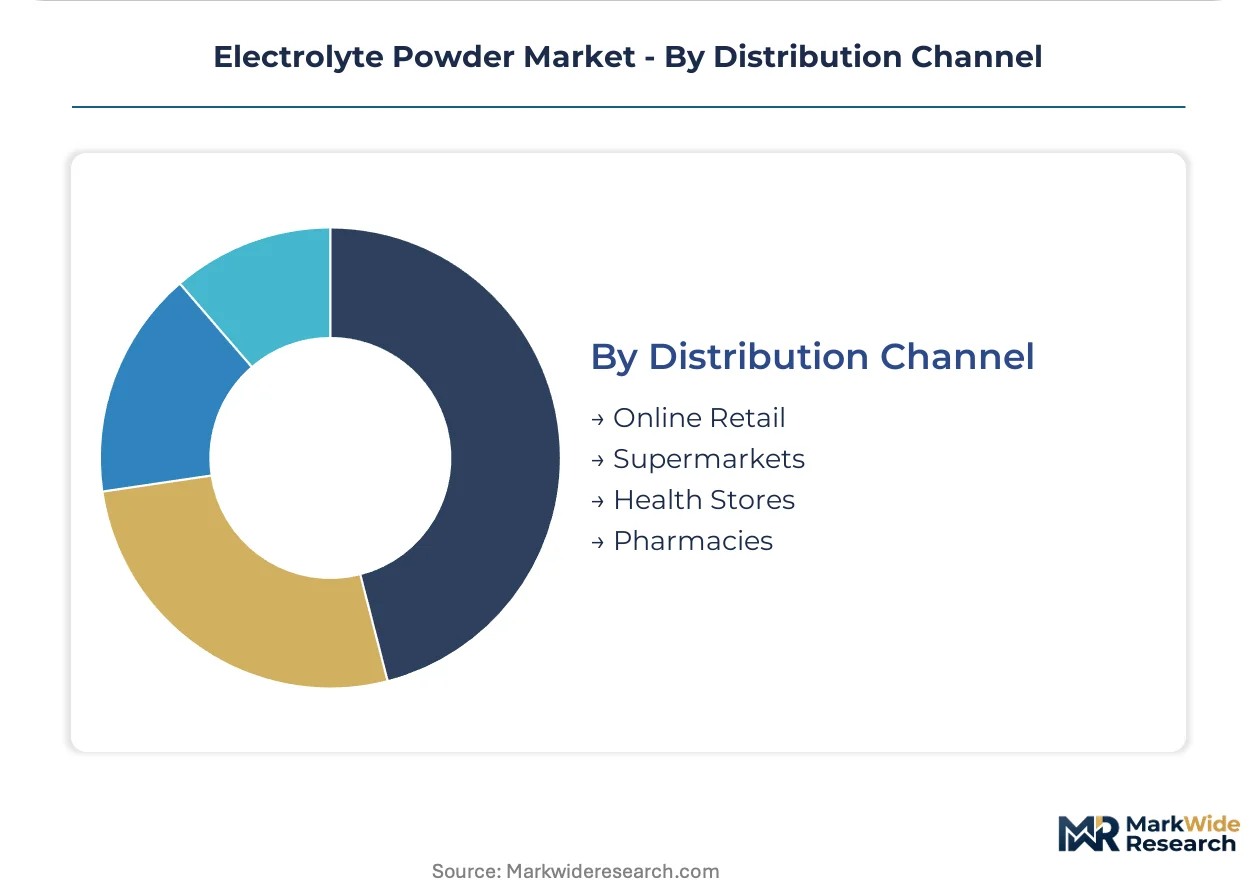
Distribution Channel:
Customer type fragmentation separates convenience-oriented grab-and-go buyers from research-intensive subscribers, with channel choice correlating to formulation sophistication.
- Online Retail:Direct-to-consumer platforms and marketplace fulfillment. United States metropolitan markets concentrate here, with predictive shipping algorithms reducing stockout risk for core fitness enthusiast buyers.
- Pharmacies:Controlled retail with pharmacist consultation. Medical-use applications require this channel for reimbursement eligibility and clinical trust transfer.
- Health Stores:Specialty retail with natural and organic positioning. Clean-label formulations dominate shelf space, with NSF and Informed Sport certifications determining access.
- Supermarkets:Mass retail with convenience placement. Ready-to-drink substitution threat is most acute here, as grab-and-go shoppers prioritize bottle convenience over powder economics.
Online retail commands growth velocity. Pharmacies defend margin concentration through channel control and clinical validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-manufactured electrolyte powders flow primarily to Canadian and Mexican retail channels under USMCA tariff preferences, while European Union REACH compliance requirements redirect Asian sourcing toward pre-registered mineral salt vendors in Germany and the Netherlands.
United States
Fitness enthusiast subscription models and military institutional procurement drive domestic consumption velocity. The FDA's DSHEA framework governs dietary supplement classification while FTC monitors hydration performance advertising claims. Direct-to-consumer fulfillment clusters in California and Texas metro areas concentrate predictive shipping algorithm development for personalized flavor rotations.
Germany
Workplace wellness program standardization and amateur endurance sports participation expand powder demand beyond traditional athletic channels. ECHA's REACH chemical registration mandates full substance dossiers for novel mineral chelates entering EU markets. Contract manufacturing facilities in Bavaria and North Rhine-Westphalia specialize in capsule format production for export to Japanese and Australian buyers.
Japan
Aging population hydration protocols and heat-exposure occupational safety regulations sustain medical-use applications. METI oversees functional food labeling standards that distinguish electrolyte powders from quasi-drugs. Pharmaceutical distribution networks in the Kanto region around Tokyo control pharmacy channel access for clinically validated formulations.
Australia
Outdoor worker hydration mandates and amateur triathlon participation create dual-demand streams for bulk institutional and premium retail formats. The TGA regulates therapeutic claims while state-level occupational health codes drive mining and agricultural sector procurement. Manufacturing concentrates in New South Wales and Victoria facilities serving domestic and Asia-Pacific export markets.
United Kingdom
Effervescent tablet preference among urban commuters and NHS cost-containment pressures shape format demand divergence. The MHRA governs borderline product classification between food supplements and medicines. Distribution infrastructure in the Southeast and Midlands channels products toward pharmacy and health store retail with distinct certification requirements.
Electrolyte Powder Market Competitive Landscape
Player mix skews toward diversified beverage conglomerates with legacy distribution infrastructure and emerging direct-to-consumer specialists with formulation agility. Market structure exhibits tiered consolidation where multinational CPG holdings command mass retail shelf space while venture-backed startups capture subscription recurring revenue. Strategic archetypes separate scale-driven hydration platforms, clean-label specialists, and medical-nutrition credential holders. Dominant competitive moves include portfolio diversification into functional beverage adjacencies and vertical integration into certified organic mineral salt sourcing.
Within the diversified beverage tier, PepsiCo Inc. and The Coca-Cola Company occupy positions anchored by convenience retail network density and cross-category brand leverage. Nestlé SA exemplifies the medical-nutrition credential archetype through health science division heritage. Among direct-to-consumer specialists, LMNT represents zero-sugar formulation purity targeting ketogenic and paleo diet adherents, while Liquid I.V. sits within the rapid-absorption technology positioning. Abbott Laboratories anchors the clinical validation tier through pharmacy channel control and prescriber relationship infrastructure.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| Nestlé SA |
| Abbott Laboratories |
| Liquid I.V. |
| LMNT |
| Nuun |
| Skratch Labs |
| Vitalyte |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements for certified organic mineral salts lock in supply access and price visibility for clean-label formulators navigating FDA DSHEA compliance and emerging state sugar-tax legislation. These contracts insulate premium tier producers from agricultural yield volatility while compressing margin flexibility for spot-market buyers in the standard tier.
Pricing Analysis
Formulation-generation pricing gaps separate microencapsulated mineral systems from conventional powder blends and legacy tablet formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control, with NSF Certified for Sport verification commanding shelf space premiums. Cost compression in the economy tier intensifies as ready-to-drink substitution erodes powder volume in supermarket convenience placement. Fitness enthusiasts show lowest price sensitivity through subscription lock-in, while grab-and-go supermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Inventory cycles for hygroscopic sodium and potassium salts extend lead times during agricultural harvest windows, compressing seasonal product launch windows. Mineral extraction concentrates in Chile, Australia, and the United States, with processing capacity clustering in domestic facilities serving military and institutional procurement. Supply chains draw from certified organic salt deposits, natural flavor systems, and lipid barrier coatings for microencapsulation. Single-source vulnerability runs through concentrated natural flavor technologist pools in California and New Jersey. Distribution runs through direct-to-consumer platforms, pharmacy networks, and specialty health store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in age-specific hydration niches as pediatric and geriatric formulations remain underpenetrated relative to fitness enthusiast saturation.
For Market Incumbents: Compound defensive positioning through captive supply of certified organic mineral salts and predictive shipping algorithm refinement that raises subscriber switching costs. Ready-to-drink substitution from beverage conglomerates threatens powder volume in mass retail, demanding channel control investments in pharmacy and specialty health store gatekeeping. Backward integration into pre-registered ingredient vendors with established safety data packages reduces REACH compliance exposure for EU market access. For New Entrants and Emerging Players: NSF Certified for Sport fast-track programs enable rapid credibility acquisition among amateur endurance athletes seeking banned-substance verification. White-space targets concentrate in long-term care facility procurement in Florida and Arizona, where precise sodium-to-potassium ratio formulations command medical-grade premiums. Pediatric hydration protocols for school lunch programs offer institutional volume with lower competitive density than saturated fitness channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription specialists with flavor customization infrastructure and predictive replenishment algorithms. Long-term viability favors acquisition targets with clinical validation documentation enabling pharmacy channel expansion beyond specialty retail. Signal to watch: consolidation velocity among natural flavor system suppliers as formulation expertise scarcity intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | NSF and Informed Sport verification unlocks pharmacy and specialty retail shelf access. |
| Direct-to-Consumer Platform Buildout | Predictive shipping algorithms capture lifetime value through personalized flavor rotation programs. |
| Microencapsulation Technology Adoption | Lipid barrier coatings extend shelf stability without synthetic anti-caking agents. |
| Pediatric Formulation Development | School lunch program penetration offers institutional volume with premium pricing potential. |
| EU REACH Compliance Infrastructure | Pre-registered ingredient vendor relationships accelerate market entry under ECHA dossier requirements. |
Research Methodology
A spread of perspectives from brand managers at diversified beverage conglomerates, category buyers at specialty health retailers, formulation scientists at contract manufacturing facilities, and procurement leads at long-term care facilities converged on the working assumptions. Primary interview insights combined with secondary validation from FDA DSHEA guidance documents, NSF International certification databases, ECHA REACH substance dossiers, and Nielsen retail audit data. Bottom-up demand modeling triangulated against top-down market sizing across powder, capsule, tablet, and liquid format segments.
Segmentation dimensions modeled include product format, end-user archetype, application use case, and distribution channel across the analysis window. CAGRs derived from historical volume trajectories, subscription platform growth rates, and channel shift assumptions. Forecast inputs incorporated military procurement contract cycles, sugar-tax legislation adoption timelines, and microencapsulation technology diffusion curves.
Underlying assumptions cover clean-label formulation mandate continuity, mineral salt agricultural yield stability, and subscription platform retention rates, with deviation risk concentrated in regulatory acceleration or flavor system supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Choline Bitartrate Market