
 Vitamin Shot Market | 2026-2036
Vitamin Shot Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Shot Market Insights
Contract manufacturing organizations across South Korea is repositioning output toward sterile injectable capacity to serve North American wellness chains. Pfizer leverages its pharmaceutical-grade sterile infrastructure to supply hospital-adjacent clinic networks with B-complex and lipotropic formulations. AdvaCare Pharma anchors private-label production for emerging brands seeking CE-marked entry into European markets. Reviv differentiates through owned-clinic deployment in London, Dubai, and Singapore, controlling both product and channel.
Vitamin shots are sterile liquid formulations containing concentrated water-soluble vitamins, amino acids, and cofactors typically administered via intramuscular injection or intravenous infusion, with pH ranges between 4.5 and 7.0 and osmolality calibrated for vascular tolerance. These preparations bypass gastrointestinal absorption barriers to achieve rapid serum concentration peaks, serving therapeutic correction of deficiencies and performance optimization in clinical and consumer settings. Immune Support products dominate pharmacy and clinic channels where influenza seasonality and post-viral recovery protocols drive repeat purchase cycles. Wellness Shots represent the fastest-expanding category as employers integrate on-site injection services into corporate health programs. Injectable delivery commands premium positioning against oral alternatives due to perceived bioavailability advantages and practitioner-administered accountability.
The FDA's 503B compounding regulations and USP <797> sterile compounding standards govern production quality and batch testing for US-manufactured vitamin shots, while the EU's MDR framework imposes clinical evidence requirements on class IIa and IIb devices used in IV administration systems. India's CDSCO and BIS standards shape export compliance for contract manufacturers supplying active pharmaceutical ingredients and finished sterile preparations to Western markets. Stakeholders must monitor evolving pharmacovigilance reporting obligations for compounded nutrient injections as regulators scrutinize adverse event profiles and therapeutic claims.
Market Dynamics
FDA enforcement of 503B compounding standards is compressing domestic manufacturing capacity while South Korean contract manufacturers scale sterile injectable output to capture displaced North American demand. This regulatory-driven supply reconfiguration is accelerating price divergence between pharmaceutical-grade and wellness-channel formulations.
Growth Catalysts
- EMA MDR compliance pathways:CE-marked IV administration devices unlock clinic network expansion across Germany, France, and the Netherlands. European wellness chains are integrating B12 and NAD+ protocols into corporate health contracts.
- On-site employer injection services:Large US employers in technology and financial services sectors are contracting directly with IV therapy providers for workforce wellness programs, bypassing traditional pharmacy channels.
- Sports medicine adoption:Injectable vitamin protocols are displacing oral supplementation in professional and collegiate athletic programs seeking rapid recovery optimization.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for B-complex formulations concentrates in Indian and Chinese manufacturing zones, exposing formulators to export licensing delays.
- Cold chain infrastructure gaps:Last-mile temperature-controlled distribution remains underdeveloped in secondary US metropolitan markets, limiting clinic network penetration.
- Substitution by high-dose oral formulations:Pharmaceutical manufacturers are advancing liposomal and sublingual delivery technologies that narrow the bioavailability gap with injectable routes.
Strategic Opportunities
- MFDS-certified Korean manufacturing:South Korean sterile compounding facilities are repositioning capacity to serve North American wellness chains seeking FDA-aligned quality at lower unit costs.
- Home administration device convergence:Auto-injector technology adapted from diabetes care is enabling self-administered vitamin shots outside clinical settings.
- Post-viral recovery protocols:Long COVID clinics in the United Kingdom and United States are establishing recurring injection schedules for immune and metabolic support.
Industry Challenges
- Sterile compounding workforce scarcity:USP <797>-certified pharmacy technicians command premium wages, constraining 503B facility expansion timelines.
- Batch testing and release bottlenecks:Endotoxin and sterility testing capacity at third-party laboratories is creating production-to-market delays of two to four weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Shot Market |
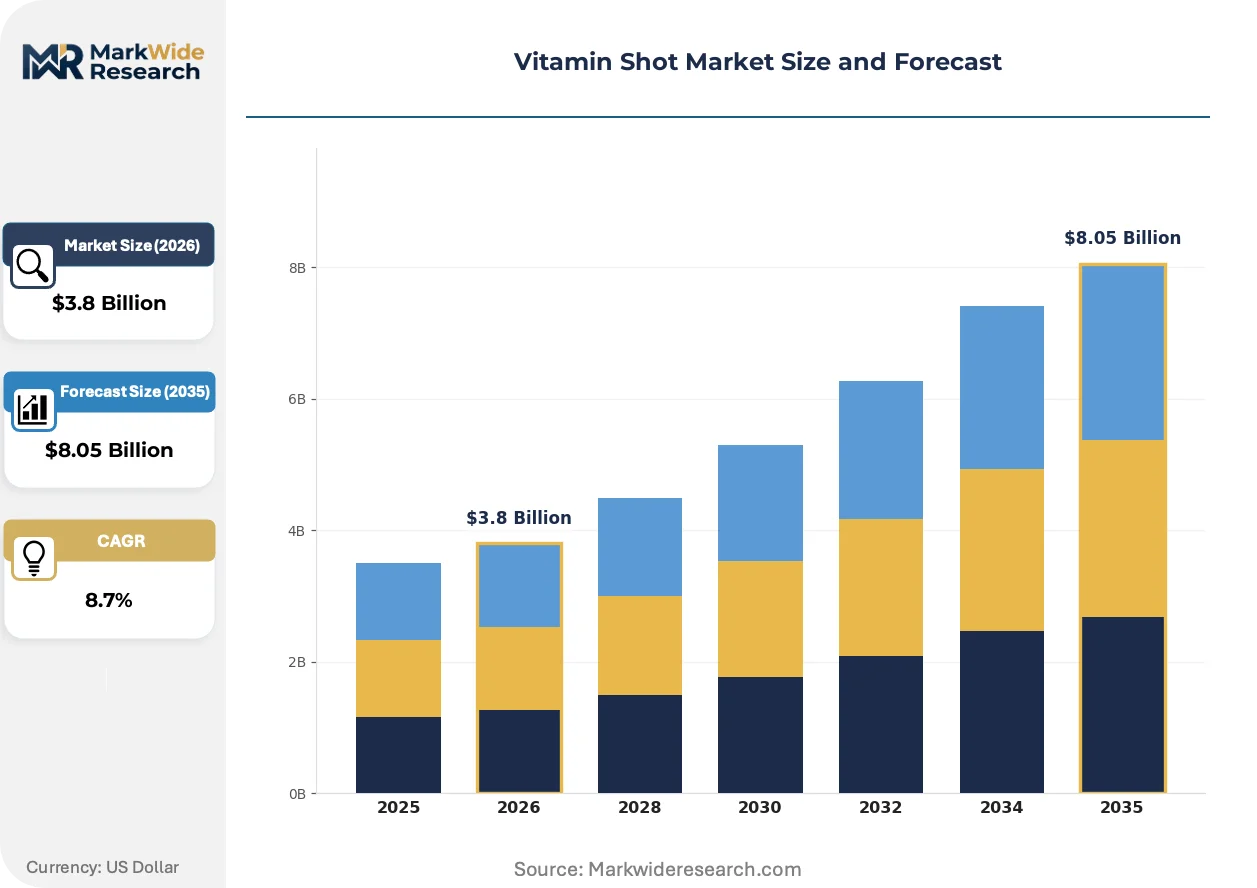
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Boosters, Immune Support, Beauty Enhancers, Wellness Shots Delivery Mode: Injectable, Oral, Sublingual, Intravenous Target Audience: Fitness Enthusiasts, Health-Conscious Consumers, Seniors, Athletes Distribution Channel: Pharmacies, Health & Wellness Stores, Online Retail, Clinics |
| Companies Covered | Pfizer, AdvaCare Pharma, Reviv, House of Bratz, Vitalounge, Sriya, Zeon Biotech, SKG Caring Health, Empower Pharmacy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Shot Market Trends and Innovations
Formulation science and administration technology are converging to expand vitamin shot delivery beyond clinical settings into employer, athletic, and eventually consumer-directed contexts. Three developments are compressing the traditional clinic-centric model.
Lyophilized single-dose vials are electrifying the portability of vitamin formulations, enabling ambulatory administration without cold chain dependency. Military and expedition medicine programs are piloting these formats for field nutrient repletion. The technology is compressing the infrastructure requirements for injection services in remote or mobile settings.
MDR Article 117 clinical evidence requirements for IV administration devices are forcing European manufacturers to generate performance data beyond basic safety benchmarks. Class IIa and IIb device re-certification timelines have extended by twelve to eighteen months. German and Swiss medical device specialists are absorbing these compliance costs while smaller competitors exit the category.
Direct contracting between self-insured employers and regional IV therapy networks is disintermediating traditional pharmacy benefit managers. Technology and professional services firms in Texas, California, and New York are leading this procurement evolution. The model shifts payment from per-dose reimbursement to annual per-employee wellness subscriptions.
Vitamin Shot Market Segmentation
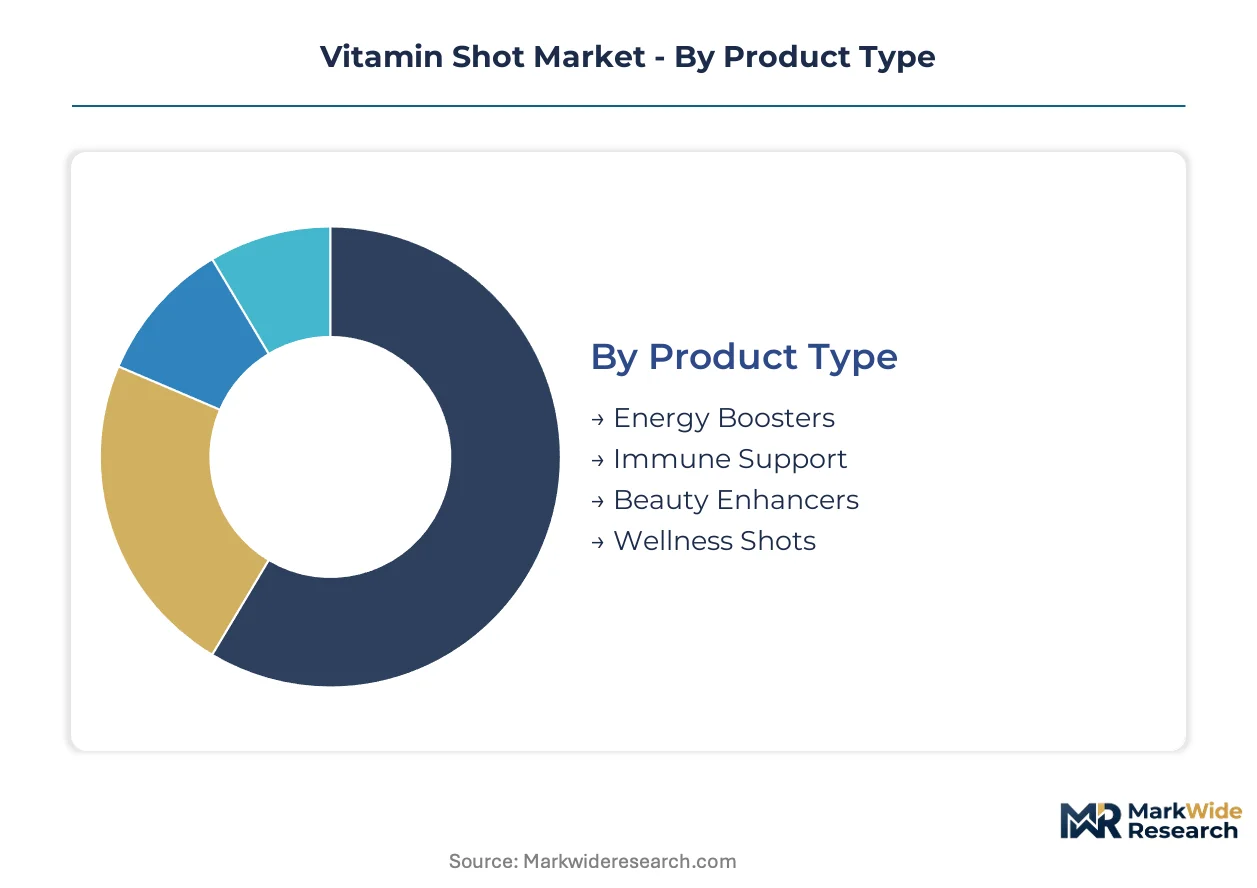
Vitamin shot manufacturers configure production lines around formulation complexity and sterility requirements. Product positioning diverges sharply between clinical-grade injectables and consumer-facing wellness formats, with distribution economics dictating viable segment entry.
Product Type:
Standardized base formulations compete against customized nutrient cocktails across this category.
- Energy Boosters:These formulations combine B-complex vitamins with amino acid cofactors such as taurine and carnitine to support mitochondrial ATP production. Demand concentrates in corporate wellness programs across Texas and California, where employers contract directly with IV therapy providers for workforce fatigue management.
- Immune Support:High-dose vitamin C, zinc, and glutathione formulations dominate pharmacy and clinic channels. Influenza seasonality drives repeat purchase cycles in United States metropolitan markets, with post-viral recovery protocols extending treatment duration.
- Beauty Enhancers:Biotin and collagen-supporting nutrient blends target aesthetic medicine clinics.
- Wellness Shots:NAD+ and lipotropic formulations command premium positioning in medspa chains.
Most installed capacity flows through Immune Support. Expansion is steepest in Wellness Shots.
Delivery Mode:
Route of administration determines regulatory pathway, cold chain requirements, and margin structure across this category.
- Injectable:Intramuscular formulations bypass gastrointestinal absorption barriers to achieve rapid serum concentration peaks. Sports medicine programs at collegiate and professional athletic facilities in the United States are displacing oral supplementation with practitioner-administered injection protocols for recovery optimization.
- Intravenous:Direct vascular delivery enables higher nutrient loads with immediate bioavailability. IV therapy clinics in London, Dubai, and Singapore have established dense metropolitan footprints, with Reviv controlling both product formulation and channel deployment.
- Oral:Liposomal encapsulation technologies are narrowing the bioavailability gap with injectable routes.
- Sublingual:Mucosal absorption offers intermediate convenience for home administration.
Injectable delivery captures the highest unit economics. Intravenous administration is gaining share fastest among premium clinic networks.
Target Audience:
Athletic performance requirements and age-related absorption limitations create divergent formulation specifications across user groups.
- Athletes:Injectable vitamin B12 and NAD+ protocols are gaining traction in sports medicine for rapid recovery and metabolic optimization. Professional and collegiate athletic programs seek practitioner-administered accountability and perceived bioavailability advantages over oral alternatives.
- Fitness Enthusiasts:This segment represents the fastest-expanding buyer category as recreational athletes adopt clinical-grade supplementation previously restricted to elite competitors.
- Health-Conscious Consumers:Preventive wellness orientation drives subscription-based purchasing patterns.
- Seniors:Malabsorption concerns and polypharmacy interactions necessitate physician-supervised protocols.
Athletes command the highest per-protocol spending. Fitness Enthusiasts are expanding most quickly across all distribution channels.
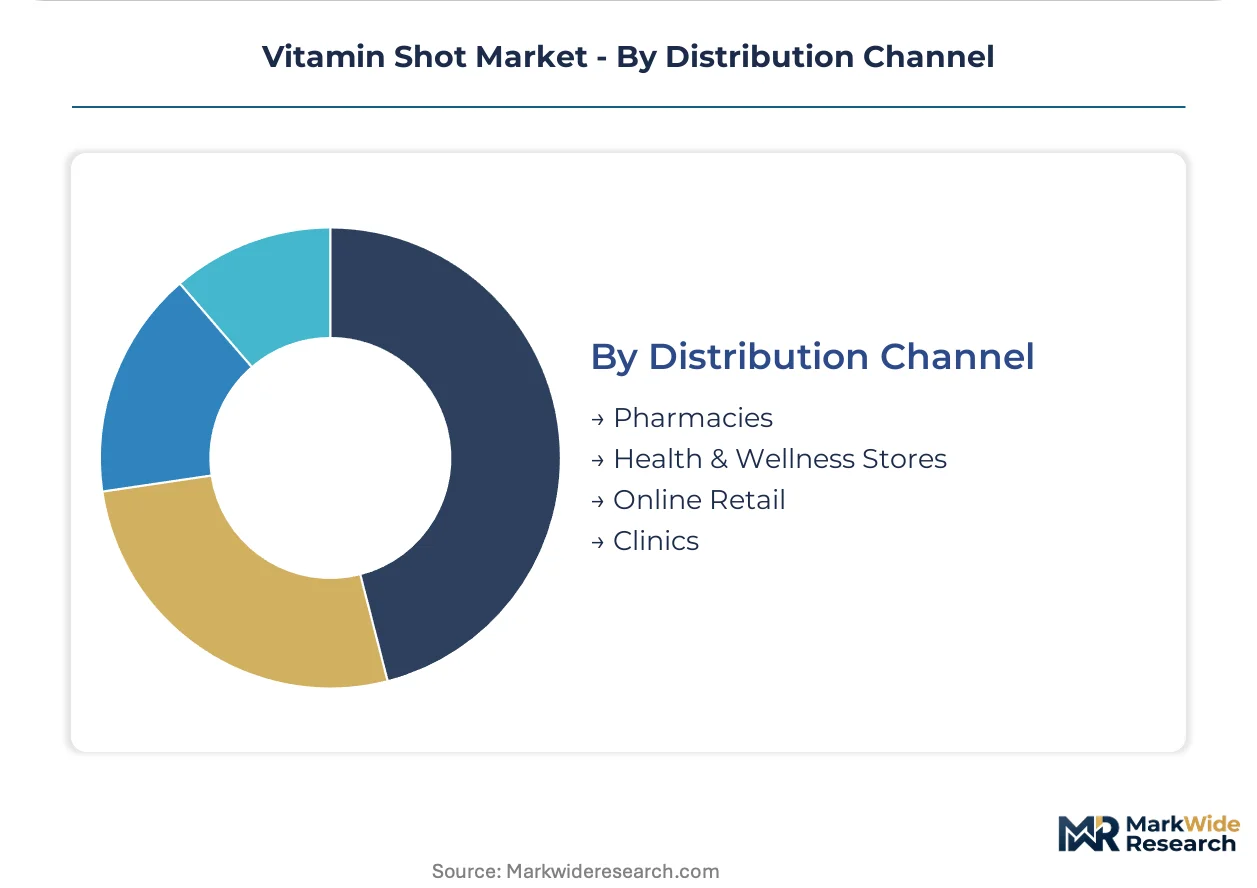
Distribution Channel:
Channel selection determines regulatory exposure, pricing autonomy, and patient relationship depth.
- Clinics:Medspa and IV therapy chains control the patient experience and capture service revenue alongside product margin. United States metropolitan markets have seen dense clinic network formation, with direct employer contracting in technology and financial services sectors bypassing traditional pharmacy benefit managers.
- Pharmacies:Retail and compounding pharmacies serve prescription-driven therapeutic correction of documented deficiencies. FDA 503B compounding regulations and USP sterile compounding standards govern production quality and batch testing for US-manufactured preparations.
- Online Retail:Direct-to-consumer platforms are expanding auto-injector technology adapted from diabetes care for home administration.
- Health & Wellness Stores:Physical retail provides education and trial for oral and sublingual formats.
Clinics absorb the majority of injectable volume. Online Retail is climbing the fastest as device technology enables self-administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as FDA 503B compliance costs push North American wellness chains toward South Korean contract manufacturers. Quality-aligned jurisdictions with lower unit economics are capturing displaced sterile compounding capacity.
United States
IV therapy clinics and medspa chains have established dense metropolitan footprints in Texas, California, and New York. FDA enforcement of 503B compounding standards and USP <797> sterile compounding requirements is compressing domestic manufacturing capacity. Cold chain infrastructure gaps in secondary metropolitan markets limit clinic network penetration in the Mountain West and Southwest.
South Korea
MFDS-certified sterile compounding facilities are repositioning output toward injectable capacity to serve North American wellness chains. The country's pharmaceutical regulator maintains alignment with FDA quality frameworks while offering lower unit production costs. Busan-Ulsan and Seoul Capital Area industrial clusters are absorbing contract manufacturing demand from US-based IV therapy networks.
United Kingdom
Long COVID clinics in London and Southeast England are establishing recurring injection schedules for immune and metabolic support. The MHRA oversees pharmacovigilance reporting for compounded nutrient injections as post-viral recovery protocols extend treatment duration. Reviv controls both product formulation and channel deployment through owned-clinic deployment in London.
Germany
EMA MDR compliance pathways for CE-marked IV administration devices are unlocking clinic network expansion across Germany, France, and the Netherlands. German medical device specialists are absorbing extended class IIa and IIb device re-certification timelines while smaller competitors exit. Bavaria and Baden-Württemberg anchor sterile device manufacturing clusters serving European wellness chains.
India
CDSCO and BIS standards shape export compliance for contract manufacturers supplying active pharmaceutical ingredients and finished sterile preparations to Western markets. B-complex formulation ingredient production concentrates in Indian manufacturing zones, exposing formulators to export licensing delays. Maharashtra and Gujarat pharmaceutical corridors supply API inputs to North American and European vitamin shot formulators.
Vitamin Shot Market Competitive Landscape
United States producers anchor the pharmaceutical-grade tier; South Korean and Indian specialists hold contract manufacturing positions. The vendor base splits between vertically integrated clinic operators and pure-play formulators serving third-party channels. Three archetypes dominate: sterile infrastructure owners, private-label contract manufacturers, and owned-clinic deployers. Competitive moves concentrate on geographic capacity repositioning and direct employer contracting bypassing pharmacy benefit managers.
Within the pharmaceutical-grade infrastructure tier, Pfizer leverages sterile manufacturing assets to supply hospital-adjacent clinic networks. AdvaCare Pharma anchors private-label production for emerging brands seeking CE-marked European entry. Reviv exemplifies the owned-clinic deployer archetype through integrated product and channel control in London, Dubai, and Singapore.
| Leading Market Players |
|---|
| Pfizer |
| AdvaCare Pharma |
| Reviv |
| House of Bratz |
| Vitalounge |
| Sriya |
| Zeon Biotech |
| SKG Caring Health |
| Empower Pharmacy |
| Others |
Pricing and Supply Chain Analysis
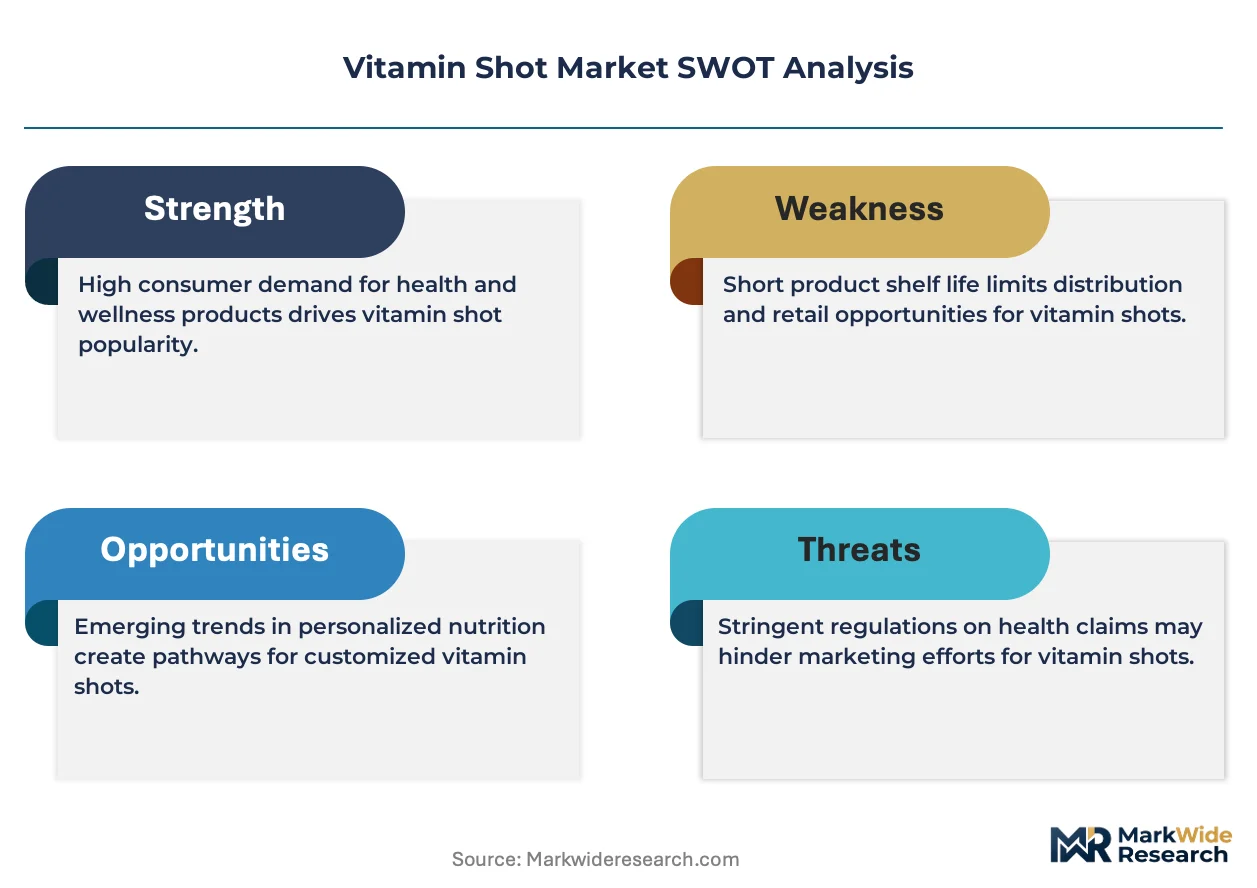
FDA 503B environmental monitoring and sterile facility validation requirements gate both qualified supply access and premium-tier pricing power, compressing domestic manufacturing capacity while elevating compliance-invested producers to price leadership positions.
Pricing Analysis
Distributor margin capture varies sharply between pharmaceutical-grade sterile injectables and wellness-channel formulations. Three-tier pricing structure across pharmaceutical-grade, compounding pharmacy, and direct-to-consumer levels separates certified 503B facilities from MFDS-aligned Korean imports and unregulated online sellers. Pricing pressure stems from South Korean contract manufacturers underbidding domestic 503B facilities on unit economics for wellness chains. Corporate wellness buyers demonstrate lowest price sensitivity due to per-employee subscription models, while individual online consumers drive aggressive discounting.
Supply Chain Analysis
Workforce scarcity for USP <797>-certified pharmacy technicians constrains expansion timelines across United States sterile compounding zones. Active pharmaceutical ingredient production concentrates in Indian and Chinese manufacturing corridors, with B-complex vitamin precursors and sterile water for injection drawing from Maharashtra and Gujarat pharmaceutical clusters. Single-source vulnerability runs through Indian export licensing delays for B12 and NAD+ raw materials. Distribution runs through cold chain-dependent logistics networks serving IV therapy clinics and medspa chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Athletic programs and corporate wellness buyers are shifting procurement toward pharmaceutical-grade sterile certification as a non-negotiable specification.
For Market Incumbents: Anticipate regulatory escalation by securing redundant MFDS-certified Korean manufacturing partnerships before FDA enforcement tightens further. Lock in multi-year direct employer contracts in Texas and California technology corridors to substitute channel margin for pharmacy benefit manager displacement. Prioritize lyophilized single-dose vial R&D to compress cold chain dependency and defend against oral liposomal substitution threats. For New Entrants and Emerging Players: The premium-to-economy price-point gap in employer-sponsored wellness programs offers white-space entry for mid-tier MFDS-certified formulators. Target secondary US metropolitan markets with underdeveloped cold chain infrastructure using ambient-stable lyophilized formats. Penetrate through direct contracting with regional IV therapy networks bypassing established clinic chains. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated clinic operators because direct employer contracting is disintermediating traditional pharmacy channels and concentrating purchasing power. Five-to-ten year viability hinges on regulatory compliance moats rather than brand differentiation. Watch for FDA 503B facility closure announcements as inflection signals for Korean contract manufacturing demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Pathway | Unlocks lower-unit-cost supply for North American wellness chains seeking FDA-aligned quality. |
| Direct Employer Contracting | Bypasses pharmacy benefit managers and captures recurring per-employee subscription revenue. |
| Lyophilized Format Development | Eliminates cold chain dependency and enables clinic network penetration in secondary markets. |
| Auto-Injector Technology Licensing | Adapts diabetes care devices for self-administered home use outside clinical settings. |
| Post-Viral Recovery Protocol Partnerships | Secures recurring injection schedules with long COVID clinics in London and Southeast England. |
Research Methodology
Direct dialogue with sterile compounding facility managers, IV therapy clinic operators, corporate wellness procurement leads, and USP <797>-certified pharmacy technicians grounded qualitative insights. Secondary validation drew from FDA 503B registration databases, MFDS facility inspection records, ClinicalTrials.gov entries for NAD+ protocols, and employer wellness program RFP documents. Bottom-up capacity modeling triangulated against top-down expenditure estimates across the analysis window.
Segmented outputs across product type, delivery mode, target audience, and distribution channel dimensions calibrated penetration rates and pricing tier trajectories. CAGRs derived from regression analysis of historical clinic network formation, employer contract signings, and regulatory enforcement event impacts. Forecast inputs incorporated MFDS facility commissioning timelines and USP <797> workforce training pipeline constraints.
Caveats apply where FDA enforcement intensity, Indian API export licensing delays, or oral liposomal bioavailability advances could materially shift the outlook. Forecasts embed assumptions about sterile compounding workforce availability and cold chain infrastructure buildout rates. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Tryptophan Market