
 Global Hangover Rehydration Supplements Market | 2026-2036
Global Hangover Rehydration Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hangover Rehydration Supplements Market Foresight
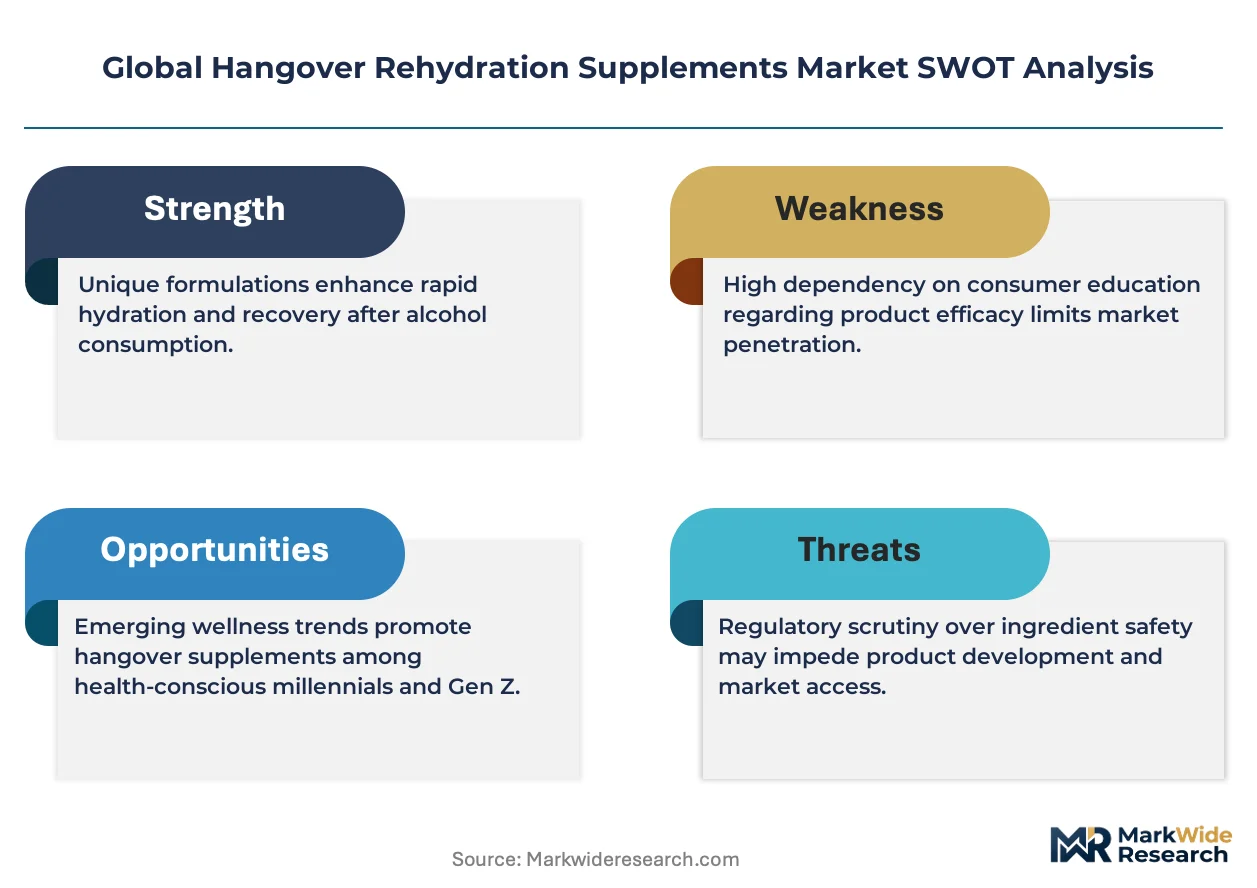
The EU Nutrition and Health Claims Regulation is pivoting the cost-of-entry calculus for new entrants by demanding clinical substantiation for electrolyte recovery claims. Flyby Ventures leverages its DTC subscription infrastructure to sustain recurring revenue in North America. More Labs anchors its position through pharmaceutical-grade manufacturing partnerships that control quality consistency. Himalaya Wellness differentiates via Ayurvedic ingredient positioning that occupies a distinct premium tier against synthetic competitors.
Hangover rehydration supplements comprise formulated electrolyte, vitamin, and herbal compositions designed to restore fluid balance and mitigate alcohol-induced dehydration symptoms, typically delivered through osmolarity-optimized solutions that enhance cellular water uptake. Their primary commercial purpose centers on acute wellness recovery for social alcohol consumers seeking functional alternatives to traditional remedies. Electrolyte powders lead product type revenue due to portability and dosing flexibility, while ready-to-drink beverages capture the fastest growth as convenience retail expands. Online retailers dominate distribution channel value, though pharmacies command higher per-unit margins through clinical credibility positioning.
The FDA oversees dietary supplement labeling under DSHEA, while the EU EFSA evaluates health claim validity, and China's SAMR enforces functional food registration requirements that collectively shape formulation transparency and cross-border market access. Compliance divergence between these frameworks forces manufacturers to maintain multiple specification tiers, elevating operational complexity for global portfolios. Stakeholders must monitor evolving caffeine and sugar content thresholds as regulators recalibrate consumer protection standards.
Market Dynamics
Post-pandemic social consumption rebound is compressing the adoption cycle for functional recovery products, with nightlife venues and event organizers emerging as concentrated bulk purchasers that reshape volume economics.
Growth Catalysts
- Nightlife venue procurement:Event organizers in the United States and United Kingdom are negotiating direct supply agreements with electrolyte powder manufacturers, bypassing traditional retail markups.
- EU EFSA health claim pathways:Manufacturers investing in clinical substantiation for electrolyte recovery claims gain preferential shelf placement in European pharmacy channels.
- Osmolarity optimization:Advances in cellular water uptake formulation science are improving efficacy perception among repeat purchasers.
Market Restraints
- Input cost volatility:Magnesium and potassium citrate prices fluctuate with mining output from Chile and Israel, compressing margin predictability.
- Regulatory friction:China's SAMR functional food registration requirements impose 18-24 month approval timelines that delay market entry.
- Substitution threat:Coconut water and sports drink brands are repositioning products for morning-after consumption with lower price points.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI regulatory clarity on herbal-adjacent functional beverages opens premium positioning for Ayurvedic-influenced entrants.
- Regulatory tailwind:Japan's METI consumer wellness subsidies for functional foods reduce effective price sensitivity among salaryman demographics.
- Technology convergence:Combination of rapid-dissolve powder formats with NFC-enabled packaging is consolidating authentication and reordering into single touchpoints.
Industry Challenges
- Certification timeline compression:FDA DSHEA notification requirements and EU EFSA substantiation demands run on parallel tracks, forcing dual-track documentation.
- Talent scarcity:Formulation chemists with cross-jurisdictional regulatory experience command premium compensation that strains mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hangover Rehydration Supplements Market |
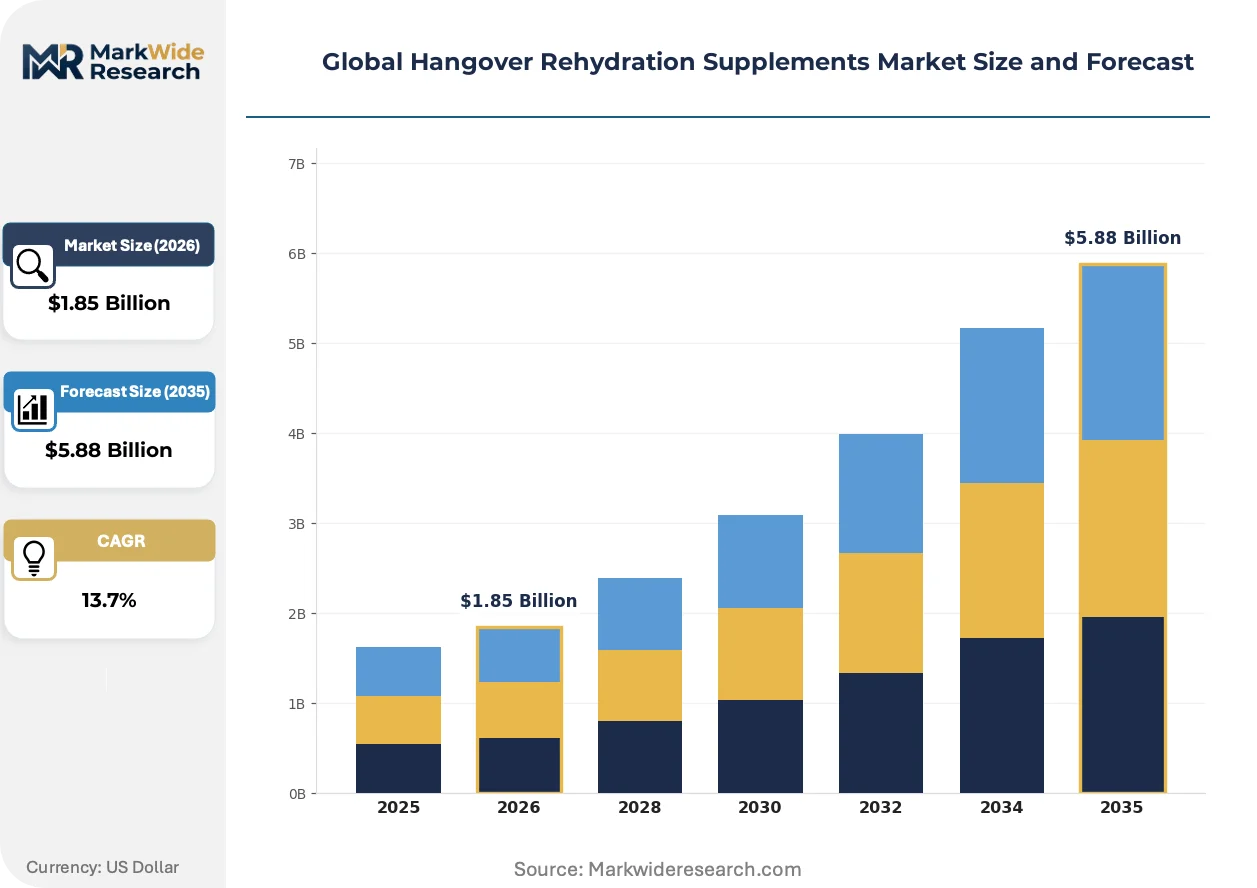
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Rehydration Solutions, Electrolyte Powders, Effervescent Tablets, Ready-to-Drink Beverages, Capsules Application: Personal Wellness, Sports Recovery, Travel & Leisure, Nightlife & Events, Corporate Gifting End User: Young Adults, Fitness Enthusiasts, Working Professionals, Festival Attendees, College Students Distribution Channel: Pharmacies, Online Retailers, Supermarkets, Convenience Stores, Health & Wellness Clinics |
| Companies Covered | Flyby Ventures, Cheers Health, More Labs, The IV Doc, DOTSHOT, Himalaya Wellness, Drinkwel, Liquid I.V., Rally Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hangover Rehydration Supplements Market Shifts & Advancements
Formulation science and distribution infrastructure are converging to compress product development cycles while expanding point-of-access for acute consumption moments.
Isotonic delivery systems is consolidating competitive positioning among ready-to-drink beverage producers. Nightlife distributors in Germany and Australia are adopting these formats for venue cooler placement. The technology is consolidating shelf space allocation away from traditional sports drinks in convenience retail.
EU Nutrition and Health Claims Regulation substantiation requirements are forcing clinical investment upstream of product launch. Manufacturers must complete human intervention studies before marketing electrolyte recovery benefits. German and French pharmacy chains are prioritizing shelf access for EFSA-validated claims over unverified functional positioning.
Subscription-based replenishment models are displacing episodic pharmacy purchases among urban professional demographics. Direct-to-consumer platforms in the United States and United Kingdom are capturing recurring revenue through automated reorder algorithms. Japan shows parallel adoption among corporate wellness program administrators seeking bulk procurement efficiency.
Global Hangover Rehydration Supplements Market Segmentation
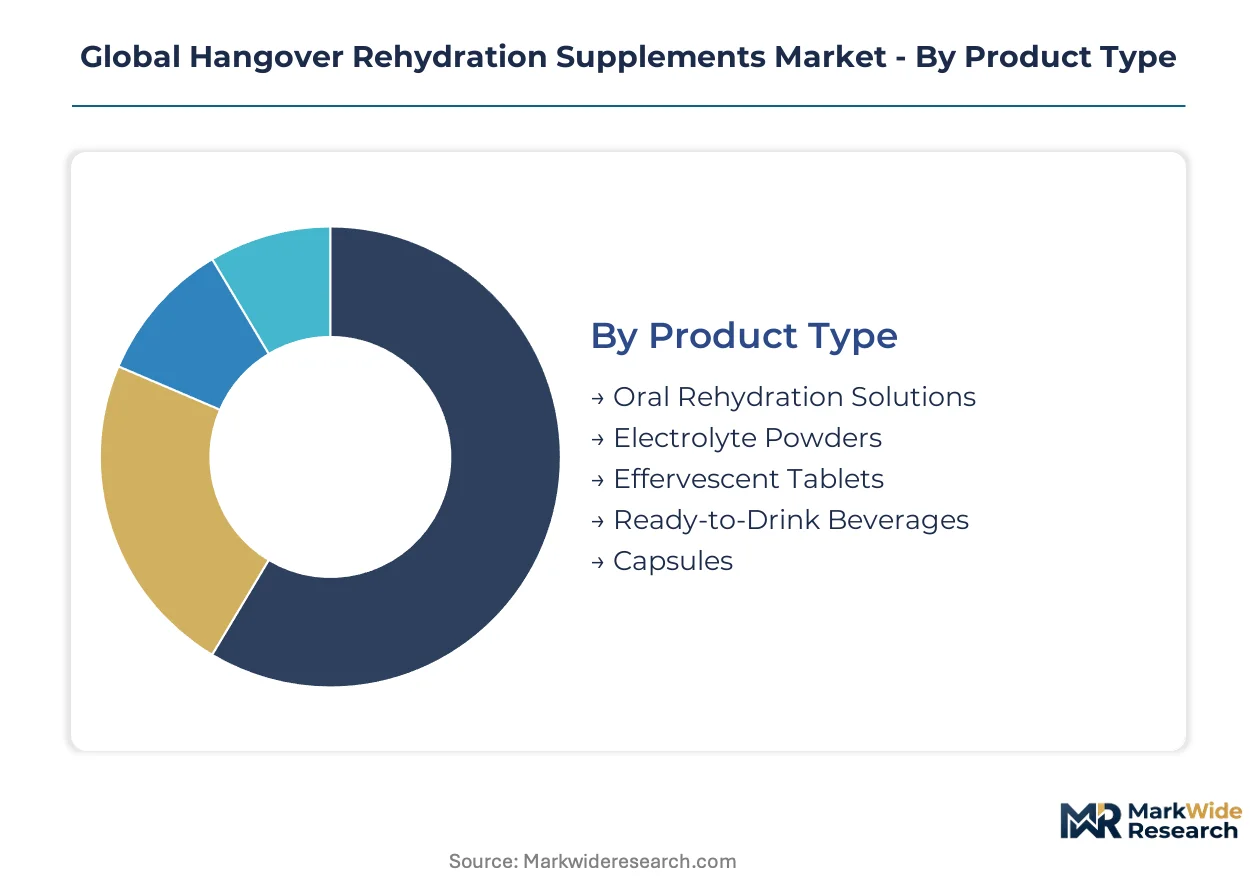
Segmentation in hangover rehydration supplements reveals divergent margin structures across format portability and consumption occasion. Formulation chemistry and channel economics create distinct competitive arenas that reward specialized positioning over broad coverage.
Product Type:
Volume concentrates in portable formats, while premium pricing accrues to ready-to-drink convenience.
- Electrolyte Powders:Formulated sachets containing sodium, potassium, and magnesium citrate blends optimized for osmolarity-driven cellular uptake. Demand clusters among nightlife venues in Germany and Australia seeking bulk procurement flexibility with minimal cooler space requirements. Margin compression from mineral input volatility constrains smaller manufacturers.
- Ready-to-Drink Beverages:Isotonic solutions in single-serve packaging with pre-mixed electrolyte ratios and flavor masking for palatability. Convenience retail expansion in Japan and United States is accelerating placement in airport kiosks and hotel minibars. Premium positioning sustains higher per-unit economics despite logistics complexity.
- Oral Rehydration Solutions:Clinical-grade formulations meeting WHO standards for rapid fluid restoration, primarily distributed through pharmacy channels.
- Effervescent Tablets:Compressed mineral compounds with carbonation-triggered dissolution, favored by travel retailers for carry-on compliance.
- Capsules:Encapsulated herbal and vitamin complexes targeting consumers averse to flavored beverages.
Today's leader: Electrolyte Powders. Tomorrow's challenger: Ready-to-Drink Beverages.
Application:
Consumption occasion segmentation separates acute recovery from preventive wellness positioning.
- Nightlife & Events:Immediate post-consumption recovery products distributed through venue partnerships and event medical stations. United Kingdom festival organizers now mandate on-site rehydration stations, creating procurement concentration. Regulatory scrutiny of implied alcohol consumption claims limits marketing latitude in EU jurisdictions.
- Personal Wellness:Subscription-based home stocking for anticipated social consumption, dominant in United States direct-to-consumer channels. Automated replenishment algorithms reduce price sensitivity among urban professionals. Churn management becomes critical as novelty effects dissipate.
- Sports Recovery:Positioning overlap with established electrolyte brands creates substitution pressure from Gatorade and Powerade portfolio extensions.
- Travel & Leisure:Airport and hotel retail placement targeting jet lag and dehydration from cabin pressure.
- Corporate Gifting:Branded wellness kits for client entertainment budgets, concentrated in financial services sectors.
Nightlife & Events commands current volume. Personal Wellness offers the steepest expansion trajectory through recurring revenue mechanics.
End User:
Demographic targeting aligns formulation messaging with lifestyle identity rather than physiological need.
- Working Professionals:Salaryman demographics in Japan and corporate employees in United States prioritize next-day cognitive performance. METI wellness subsidies in Japan reduce effective price barriers. Subscription retention exceeds other segments due to habitual consumption patterns.
- Festival Attendees:Concentrated demand spikes around Coachella, Tomorrowland, and Glastonbury drive seasonal production planning. Bulk procurement by event organizers bypasses traditional retail markups entirely.
- Young Adults:Social media-influenced trial purchases with low brand loyalty and high price elasticity.
- Fitness Enthusiasts:Overlap with sports nutrition positioning creates channel conflict with established protein and pre-workout brands.
- College Students:Campus ambassador programs and Greek life procurement drive concentrated geographic demand.
Working Professionals anchor subscription economics. Festival Attendees generate episodic volume spikes that strain supply chain planning.
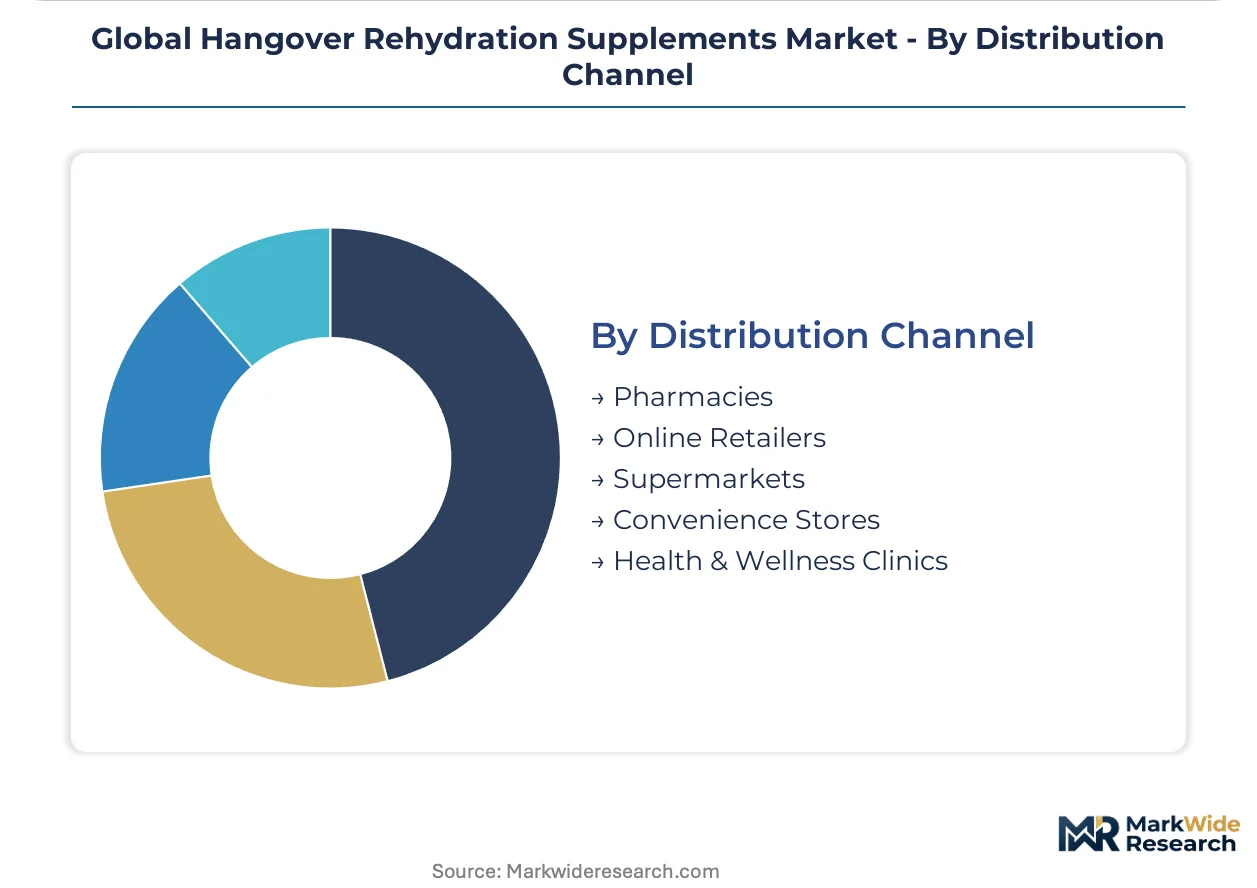
Distribution Channel:
Channel selection determines margin capture and clinical credibility positioning.
- Online Retailers:Direct-to-consumer platforms with subscription infrastructure and automated reorder algorithms. United States and United Kingdom markets show highest penetration. Customer acquisition costs escalate as digital advertising efficiency declines.
- Pharmacies:German and French chains prioritize EFSA-validated claims, commanding premium shelf placement for substantiated products. Per-unit margins exceed other channels due to clinical credibility transfer.
- Supermarkets:Mass-market placement requires price competitiveness against coconut water and sports drink alternatives.
- Convenience Stores:Impulse purchase positioning for acute consumption moments, expanding in Japan and South Korea.
- Health & Wellness Clinics:Practitioner recommendation channels with highest consumer trust but limited scale.
Online Retailers dominate value capture today. Pharmacies represent the credibility gateway for premium positioning tomorrow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with cross-jurisdictional regulatory experience concentrate in the United States, Germany, and Japan, anchoring product development capacity for osmolarity-optimized recovery solutions.
United States
Direct-to-consumer wellness brands sustain recurring revenue through automated subscription algorithms targeting urban professionals. FDA DSHEA notification requirements govern dietary supplement labeling while permitting structure-function claims without pre-market approval. Los Angeles and New York Metro host the densest clusters of nightlife venue procurement teams negotiating direct supply agreements with electrolyte powder manufacturers.
Germany
Pharmacy chains prioritize EFSA-validated electrolyte recovery claims for premium shelf placement, rewarding clinical substantiation investments. EU Nutrition and Health Claims Regulation enforcement tightens substantiation standards for functional beverage labeling across member states. Berlin and Munich nightlife distributors adopt isotonic ready-to-drink formats for venue cooler placement, compressing traditional sports drink shelf allocation.
Japan
METI consumer wellness subsidies for functional foods reduce effective price sensitivity among salaryman demographics seeking next-day cognitive performance. Pharmaceutical and Food Safety Bureau standards align with international osmolarity benchmarks for rapid rehydration efficacy. Tokyo and Osaka corporate wellness program administrators drive bulk procurement efficiency through automated replenishment systems.
United Kingdom
Festival organizers mandate on-site rehydration stations at Glastonbury and Tomorrowland satellite events, creating concentrated procurement volume. MHRA guidance on borderline products between foods and medicines influences formulation positioning for hangover recovery claims. London direct-to-consumer platforms capture recurring revenue through subscription infrastructure rivaling United States penetration rates.
India
FSSAI regulatory clarity on herbal-adjacent functional beverages opens premium positioning for Ayurvedic-influenced entrants targeting working professionals. Central and state food safety authorities enforce labeling standards that distinguish traditional remedies from clinically substantiated formulations. Mumbai and Bangalore wellness startups leverage Ayurvedic ingredient positioning to occupy distinct premium tiers against synthetic competitors.
Global Hangover Rehydration Supplements Market Competitive Landscape
The competitive structure tilts toward direct-to-consumer specialists with subscription infrastructure and pharmaceutical-grade manufacturing partners controlling quality consistency. Tiered positioning separates clinical-credibility players from convenience-retail optimizers and Ayurvedic premium differentiators. Dominant competitive moves include vertical integration into mineral supply chains and strategic partnerships with nightlife distributors bypassing traditional retail markups.
Within the DTC-specialist tier, Flyby Ventures and More Labs exemplify divergent infrastructure strategies. Flyby Ventures anchors North American recurring revenue mechanics through subscription platform optimization. More Labs occupies a position defined by pharmaceutical-grade manufacturing partnerships that standardize quality consistency across production batches. Himalaya Wellness represents the Ayurvedic-differentiation archetype, leveraging traditional ingredient positioning against synthetic formulation competitors.
| Leading Market Players |
|---|
| Flyby Ventures |
| Cheers Health |
| More Labs |
| The IV Doc |
| DOTSHOT |
| Himalaya Wellness |
| Drinkwel |
| Liquid I.V. |
| Rally Labs |
| Others |
Supply & Pricing Matrix
EU EFSA substantiation mandates for electrolyte recovery claims gate qualified supply access and premium-tier pricing power, forcing manufacturers to absorb clinical study costs before pharmacy channel entry while commodity-grade competitors retreat to unverified convenience retail positioning. This regulatory filter concentrates margin capture among substantiated players in German and French pharmacy networks.
Pricing Analysis
Bundled subscription services command recurring revenue premiums against unbundled transactional purchases in United States direct-to-consumer channels. Three-tier pricing structure across EFSA-validated pharmacy tiers, standard retail placement, and economy bulk procurement for nightlife venues separates clinical credibility from convenience positioning. Cost compression in mineral inputs from Chile and Israel is intensifying margin pressure on mid-tier powder manufacturers. Festival organizers and corporate wellness administrators show lowest price sensitivity due to bulk procurement efficiency, while young adult trial purchasers exhibit highest elasticity.
Supply Chain Analysis
Warehouse-distribution layer consolidation around regional distribution centers in Germany, Japan, and the United States compresses last-mile logistics for ready-to-drink beverage formats. Active pharmaceutical ingredient sourcing for clinical-grade formulations draws from Swiss and Indian manufacturing hubs, while mineral citrate extraction rests on Chilean and Israeli mining output. Single-source vulnerability in magnesium supply chains from Atacama Desert operations exposes margin predictability to extraction volatility. Distribution runs through direct-to-consumer platforms and pharmacy wholesale networks with divergent working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hangover rehydration supplements hinges on upstream mineral cost control and downstream subscription retention mechanics that convert episodic purchasers into recurring revenue streams.
For Market Incumbents: Hedge against coconut water and sports drink substitution by securing pharmaceutical-grade manufacturing partnerships that standardize batch consistency for EFSA validation. Backward integration into Chilean magnesium citrate supply chains reduces input cost volatility exposure. Channel control through exclusive nightlife distributor agreements in Berlin and Los Angeles Metro protects volume economics from retail markup compression. For New Entrants and Emerging Players: Begin with India's FSSAI-regulated Ayurvedic-adjacent positioning where Himalaya Wellness has validated premium-tier acceptance among working professionals. Corporate wellness bulk procurement in Tokyo and Osaka offers the most penetrable recurring revenue entry point. Direct-to-consumer launch with automated replenishment algorithms reduces customer acquisition cost exposure versus competing for saturated United States digital advertising inventory. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap DTC specialists with proven subscription retention algorithms because customer lifetime value concentration in urban professional demographics exceeds traditional CPG benchmarks. Acquisition targets should demonstrate automated reorder infrastructure and cross-jurisdictional regulatory documentation capacity. Watch EFSA claim validation timelines as inflection indicator for European pharmacy channel access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Clinical Substantiation Investment | Pharmacy channel shelf access in Germany and France hinges on validated electrolyte recovery claims. |
| Direct-to-Consumer Subscription Platform | Automated replenishment algorithms capture recurring revenue from United States urban professionals. |
| Backward Integration into Mineral Supply | Captive sourcing of Chilean magnesium citrate insulates margin predictability from extraction volatility. |
| Nightlife Distribution Partnership | Exclusive venue supply agreements in Berlin and Los Angeles bypass traditional retail markup layers. |
| Ayurvedic Ingredient Positioning | FSSAI-compliant herbal formulations unlock premium tier differentiation against synthetic competitors in India. |
Research Methodology
Multiple input streams — formulation chemist interviews, regulatory affairs consultations, nightlife procurement manager discussions, and pharmacy chain category buyer interviews — were reconciled against secondary validation from FDA DSHEA notification databases, EFSA health claim registers, and customs trade records for mineral citrate imports. Bottom-up segment sizing across product types, applications, and distribution channels was triangulated with top-down macroeconomic indicators for consumer wellness expenditure.
Data-stream reconciliation supported analytical framework development across the projection horizon, modeling electrolyte powder, ready-to-drink beverage, and oral rehydration solution formats alongside nightlife events, personal wellness, and corporate gifting applications. CAGRs were derived from segment-level volume and value trajectories incorporating osmolarity optimization technology adoption curves and METI subsidy impact on Japanese salaryman demand.
Caveats apply where EFSA substantiation timeline extensions or SAMR registration delays in China could materially shift the outlook for pharmacy channel expansion and cross-border market access. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Dysphagia Supplements Market