
 Microemulsions Market | 2026-2036
Microemulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Microemulsions Market Outlook
Specialized colloid chemist availability is unwinding across European and North American formulation labs, tightening pilot-scale capacity for new microemulsion development. Evonik Industries leverages its alkoxylated surfactant portfolio to anchor pharmaceutical-grade supply chains. DowDuPont competes through silicone-based microemulsion platforms for personal care applications. Innospec dominates fuel and oilfield microemulsion additive channels with tailored sulfonate chemistry.
Microemulsions are thermodynamically stable, isotropic dispersions of two immiscible liquids stabilized by surfactant and co-surfactant films, typically measuring 10-100 nanometers in droplet diameter and forming spontaneously without high-energy input. These systems function primarily as enhanced solubilization vehicles, enabling hydrophobic active ingredients to disperse uniformly in aqueous matrices for drug delivery, cosmetic serums, and agrochemical sprays. Oil-phase microemulsions lead formulation value pools in pharmaceutical and personal care applications due to superior bioavailability enhancement. High-pressure homogenization technology sustains premium positioning in sterile parenteral manufacturing where droplet size distribution demands tight control. Phase inversion methods occupy cost-sensitive agrochemical and food processing segments where thermal stability requirements are less stringent.
EMA stability guidelines and REACH surfactant registration frameworks in Europe, alongside FDA cGMP expectations for parenteral microemulsions in the United States, shape formulation development timelines and raw material qualification burdens. EPA and FIFRA compliance for agrochemical microemulsion concentrates adds registration complexity for crop protection entrants. Stakeholders must monitor evolving pharmacopeial monographs for nanoscale dispersion characterization methods and pre-emptively validate alternative bio-based surfactant feedstocks before supply restrictions tighten.
Market Dynamics
REACH surfactant registration requirements and tightening EMA stability guidelines are compressing formulation development timelines while concentrating pilot-scale capacity among labs with qualified colloid chemists. This regulatory pressure is reshaping competitive positioning by favoring incumbents with established bio-based surfactant qualification pathways.
Growth Catalysts
- Oil-phase pharmaceutical formulations:Superior bioavailability enhancement drives adoption in parenteral drug delivery systems. Sterile manufacturing protocols favor thermodynamically stable dispersions over conventional emulsions.
- REACH compliance deadlines:European surfactant sourcing rules accelerate qualification of bio-based alternatives. Formulation labs with pre-validated feedstock pipelines capture contract manufacturing share.
- High-pressure homogenization upgrades:Equipment investments in Germany, the United States, and Japan tighten droplet size distribution control. Premium positioning in sterile parenteral segments sustains margin pools.
Market Restraints
- Specialized colloid chemist scarcity:Pilot-scale capacity constraints in European and North American formulation labs limit new development throughput. Talent pipeline gaps extend project timelines.
- Raw material concentration risk:Alkoxylated surfactant supply chains anchor to limited European and Asian producers. REACH registration burdens deter new supplier entry.
- Agrochemical registration friction:EPA FIFRA compliance requirements for microemulsion concentrates add 18-36 month approval cycles. Crop protection entrants face capital lockup before revenue realization.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO regulatory alignment with ICH guidelines opens contract formulation opportunities. Domestic production incentives under PLI schemes reduce import dependency.
- Food processing phase inversion methods:Thermal stability requirements in beverage and edible oil applications favor lower-energy processing. Cost-sensitive segments accept broader droplet distributions.
- EU Green Deal bio-surfactant mandates:Rhamnolipid and sophorolipid qualification pathways gain regulatory preference. First-movers in fermentation-derived stabilizers secure offtake agreements.
Industry Challenges
- Pharmacopeial monograph validation:Evolving nanoscale dispersion characterization methods require analytical method redevelopment. Labs must pre-validate alternative bio-based feedstocks before supply restrictions tighten.
- Silicone-based platform integration:Personal care formulators face compatibility testing burdens when substituting traditional surfactants. DowDuPont's established silicone microemulsion architectures create switching friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microemulsions Market |
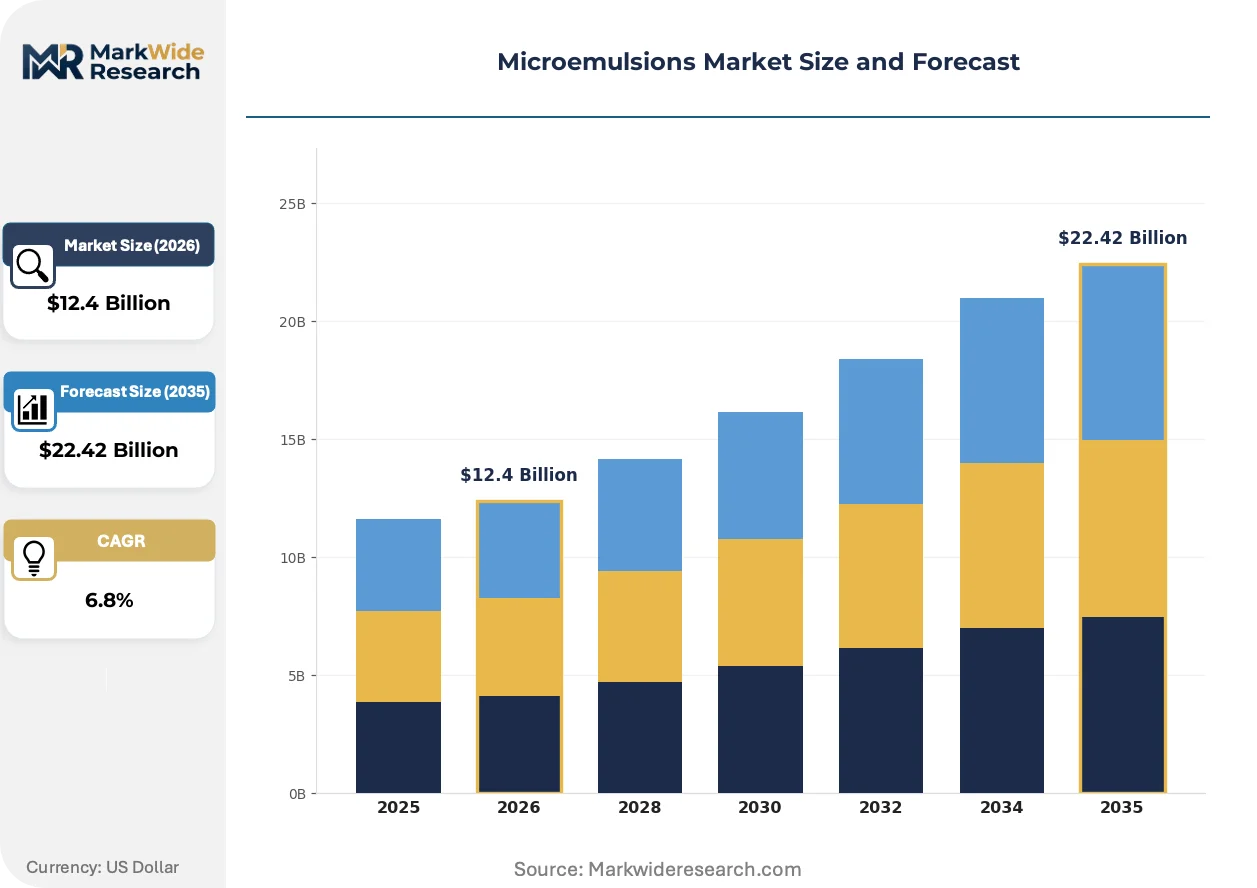
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Surfactants, Co-surfactants, Water Application: Pharmaceuticals, Cosmetics, Food Industry, Agrochemicals End User: Healthcare, Personal Care, Food & Beverage, Agriculture Technology: High-Pressure Homogenization, Ultrasonication, Microfluidization, Phase Inversion |
| Companies Covered | Wacker Chemie, Innospec, DowDuPont, PeroxyChem, Schlumberger, Evonik Industries, Chem Arrow, Huntsman Corporation, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microemulsions Market Strategic Shifts
Formulation science is splitting across energy-intensive precision manufacturing and lower-energy spontaneous systems, with regulatory chemistry requirements driving divergence in equipment investment and talent specialization.
High-pressure homogenization is bifurcating sterile parenteral manufacturing from cost-sensitive agrochemical processing. Pharmaceutical contract manufacturers in Germany and Switzerland adopt 1000+ bar systems for tight droplet distribution control. Agrochemical blenders in Brazil and India accept broader specifications from phase inversion methods.
EMA stability guidelines now mandate accelerated aging protocols for nanoscale dispersions, extending qualification timelines for new surfactant chemistries. European formulation labs redirect resources toward pharmacopeial monograph pre-submissions. United States FDA cGMP expectations for parenteral microemulsions create parallel compliance tracks.
Personal care procurement teams now unbundle formulation development from manufacturing, contracting specialized colloid labs for pilot-scale validation before transferring to commercial production. This disintermediation compresses internal R&D headcount at brand owners. North American and European beauty companies lead this restructuring.
Microemulsions Market Segmentation
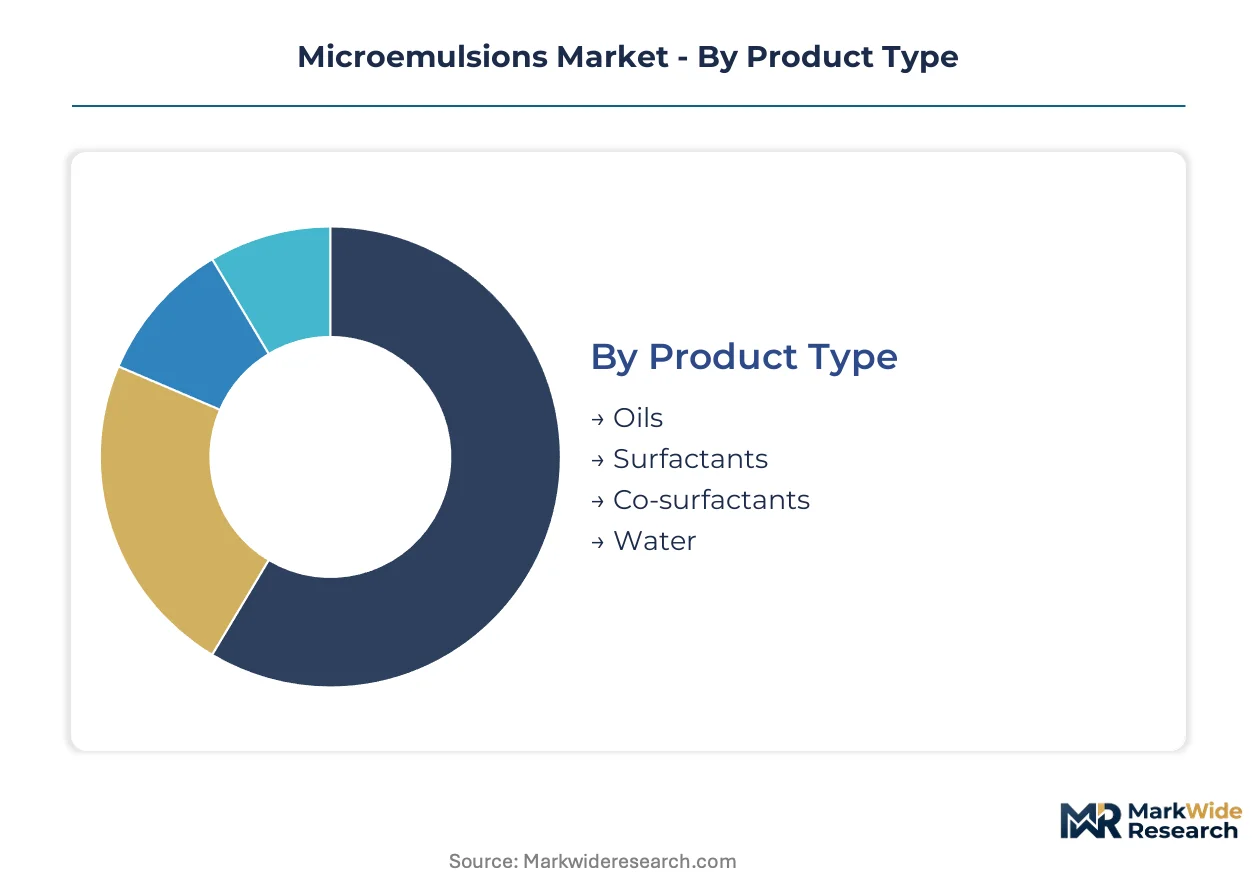
Microemulsion formulation complexity demands precise segmentation mapping. Each dimension—composition, application, and processing technology—carries distinct regulatory burdens and margin profiles that determine competitive positioning.
Product Type:
EMA stability guidelines and FDA cGMP requirements impose differentiated qualification timelines across feedstock categories. REACH registration status determines sourcing flexibility for European manufacturers.
- Oils:Hydrophobic core materials ranging from medium-chain triglycerides to essential oils define the dispersed phase. Pharmaceutical-grade oils in Germany and Switzerland face USP-NF monograph compliance burdens. Sterile parenteral applications in the United States command premium positioning through tight oxidative stability specifications.
- Surfactants:Alkoxylated non-ionics and ionic stabilizers form the interfacial film. Bio-based rhamnolipid qualification under EU Green Deal procurement rules is accelerating in France and the Netherlands. REACH-registered ethoxylates from Belgian and German producers anchor established supply chains.
- Co-surfactants:Short-chain alcohols and polyols lower interfacial tension for spontaneous formation. Japanese pharmaceutical formulators favor pharmaceutical-grade hexylene glycol for injectable applications.
- Water:Purified or WFI-grade aqueous phase constitutes the continuous matrix. USP Purified Water standards in the United States and EP Water for Injections specifications in Europe drive quality differentiation.
Oils handles the majority of throughput; surfactants is the fastest mover on share.
Application:
Cost tier stratification separates sterile manufacturing protocols from commodity processing. High-pressure homogenization capital intensity creates entry barriers that protect margin pools in premium segments.
- Pharmaceuticals:Parenteral drug delivery systems leverage superior bioavailability enhancement. FDA cGMP compliance for sterile microemulsions in the United States and EMA stability protocols in Europe extend development timelines. Contract manufacturers in Germany and Switzerland capture value through validated high-pressure homogenization infrastructure.
- Cosmetics:Serum and emulsion formulations exploit optical clarity and skin penetration. Personal care brands in France and the United States unbundle pilot-scale validation from commercial production. Silicone-based architectures create switching friction for formulators seeking surfactant substitutions.
- Food Industry:Edible oil and beverage applications accept broader droplet distributions from phase inversion methods. FSSAI compliance in India and FDA food additive regulations in the United States govern formulation pathways. Thermal stability requirements favor lower-energy processing.
- Agrochemicals:Pesticide and herbicide concentrates rely on spontaneous formation for field dilution. EPA FIFRA registration in the United States and PMRA compliance in Canada impose 18-36 month approval cycles. Brazilian and Indian blenders prioritize cost over droplet precision.
Pharmaceuticals commands the highest value per liter; agrochemicals is expanding most quickly in absolute volume terms.
End User:
Customer procurement sophistication determines specification stringency. Healthcare and personal care buyers enforce pharmacopeial compliance; agricultural purchasers prioritize cost efficiency.
- Healthcare:Hospital and clinic procurement of parenteral nutrition and drug formulations. CDSCO alignment with ICH guidelines in India opens contract manufacturing opportunities. PLI scheme incentives reduce import dependency for domestic production.
- Personal Care:Beauty brand owners and contract manufacturers driving formulation innovation. North American and European labs concentrate pilot-scale capacity for new development.
- Food & Beverage:Processors of fortified beverages and functional oils. Phase inversion methods dominate for thermal stability in heat-treated products.
- Agriculture:Crop protection distributors and on-farm application systems. Registration friction in the United States and Europe favors incumbents with established compliance infrastructure.
Healthcare absorbs the most rigorous qualification overhead; personal care is climbing the fastest on formulation outsourcing intensity.
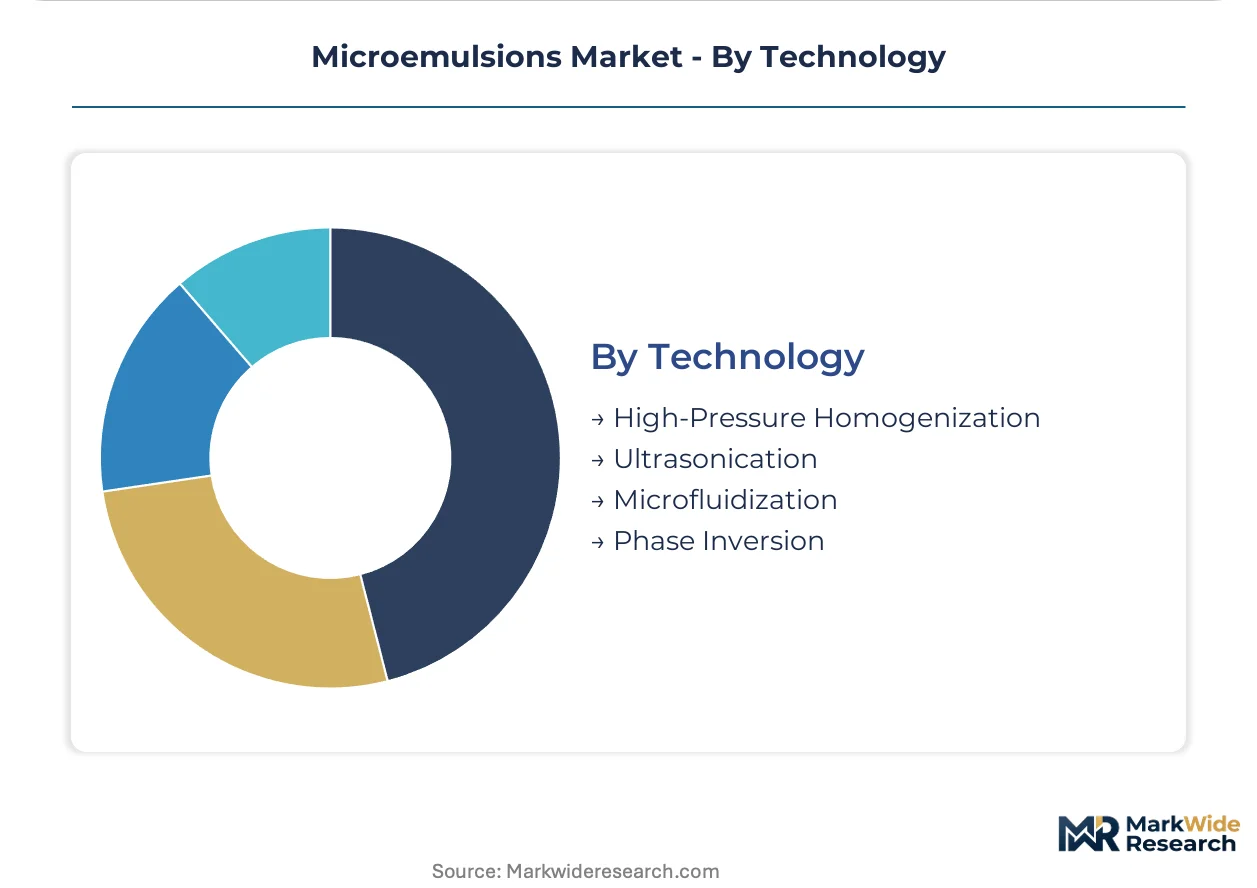
Technology:
Equipment investment patterns bifurcate across precision manufacturing and cost-sensitive processing. Droplet size distribution requirements determine technology selection.
- High-Pressure Homogenization:1000+ bar systems deliver tight distributions for sterile parenterals. German and Swiss pharmaceutical contractors sustain premium positioning through equipment upgrades. FDA cGMP validation protocols extend deployment timelines.
- Ultrasonication:Acoustic cavitation generates nanoscale dispersions for lab-scale and pilot production. Japanese equipment manufacturers lead transducer reliability engineering.
- Microfluidization:Fixed-geometry interaction chambers enable continuous manufacturing scale-up. Emerging adoption in United States-based sterile injectable facilities.
- Phase Inversion:Temperature or composition-driven spontaneous formation without mechanical energy. Brazilian and Indian agrochemical blenders accept broader specifications for cost advantage.
High-pressure homogenization dominates sterile pharmaceutical throughput; phase inversion is gaining share fastest in emerging market agrochemical processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States concentrate pharmaceutical-grade microemulsion demand, while Brazil and India favor cost-optimized agrochemical formulations. This consumption-mix differential shapes equipment investment patterns and regulatory compliance burdens across geographies.
United States
FDA cGMP expectations for sterile parenteral microemulsions drive high-pressure homogenization upgrades among contract manufacturers. EPA FIFRA compliance requirements add 18-36 month approval cycles for agrochemical concentrates. New Jersey and Massachusetts formulation labs concentrate pilot-scale capacity for pharmaceutical applications.
Germany
EMA stability guidelines and REACH surfactant registration frameworks compress development timelines while favoring incumbents with bio-based feedstock pipelines. Evonik Industries anchors pharmaceutical-grade supply chains through its alkoxylated surfactant portfolio. North Rhine-Westphalia and Bavaria host concentrated high-pressure homogenization equipment investments.
India
CDSCO regulatory alignment with ICH guidelines opens contract formulation opportunities for parenteral drug delivery systems. PLI scheme incentives reduce import dependency for domestic pharmaceutical production. Maharashtra and Gujarat formulation facilities expand phase inversion capacity for cost-sensitive agrochemical processing.
Brazil
Crop protection distributors prioritize spontaneous formation methods over precision droplet control for field dilution applications. ANVISA pharmaceutical regulations create parallel compliance tracks for imported active ingredients. São Paulo and Minas Gerais blenders dominate regional agrochemical concentrate formulation.
Japan
PMDA sterile manufacturing protocols sustain premium positioning for thermodynamically stable dispersions in parenteral nutrition. METI industrial policy supports high-pressure homogenization equipment reliability engineering. Kanto region pharmaceutical contractors maintain tight droplet size distribution capabilities for export markets.
Microemulsions Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in microemulsion formulation supply. Tier-one players combine surfactant manufacturing with formulation services, while mid-scale competitors focus on application-specific delivery systems. Two strategic archetypes dominate: alkoxylated surfactant suppliers anchoring pharmaceutical channels, and silicone-based platform providers serving personal care procurement. Competitive moves concentrate on backward integration into bio-based feedstock production and geographic expansion through contract manufacturing partnerships.
Within the integrated surfactant-formulator tier, Evonik Industries and DowDuPont occupy distinct positioning archetypes. Evonik represents the European pharmaceutical-grade supplier model with REACH-registered alkoxylated chemistry. DowDuPont exemplifies North American personal care platform specialization through silicone-based architectures. Innospec sits within the fuel and oilfield additive specialist category, anchoring sulfonate chemistry applications without direct overlap in pharmaceutical or cosmetic segments.
| Leading Market Players |
|---|
| Wacker Chemie |
| Innospec |
| DowDuPont |
| PeroxyChem |
| Schlumberger |
| Evonik Industries |
| Chem Arrow |
| Huntsman Corporation |
| Ashland |
| Others |
Value Chain & Pricing Dynamics
REACH surfactant registration gates both supply qualification and price differentiation simultaneously, forcing European manufacturers to absorb higher feedstock validation costs while passing certification premiums downstream to pharmaceutical buyers. This regulatory chemistry creates a bifurcated market where REACH-registered alkoxylated surfactants command sustained premiums against unregistered alternatives.
Pricing Analysis
Long-term offtake contracts anchor pharmaceutical-grade microemulsion supply, with three-tier pricing structure across premium, standard, and economy levels separating sterile parenteral formulations from agrochemical concentrates. Price differentiation rests on USP-NF monograph compliance and EMA stability validation. Cost compression in agrochemical tiers is intensifying because Brazilian and Indian blenders prioritize phase inversion methods over precision droplet control. Personal care procurement teams exhibit lowest price sensitivity due to unbundled R&D outsourcing.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for alkoxylated surfactant feedstocks, compressing margins for formulation labs without captive supply arrangements. Raw material sourcing concentrates in Germany, Belgium, and Japan for REACH-registered ethoxylates. Supply chains draw from medium-chain triglycerides, pharmaceutical-grade hexylene glycol, and fermentation-derived bio-surfactants. Single-source vulnerability in European alkoxylated surfactant production creates concentration risk. Distribution runs through contract manufacturing networks anchored by German and Swiss pharmaceutical specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified colloid chemist availability constrains pilot-scale capacity expansion, creating a capability-scarcity environment where incumbents with pre-validated feedstock pipelines capture disproportionate contract manufacturing share.
For Market Incumbents: Consolidate pilot-scale capacity in Germany and Switzerland through high-pressure homogenization equipment upgrades, locking in sterile parenteral formulation contracts before CDSCO-aligned Indian facilities mature. Anchor backward integration into bio-based surfactant fermentation to preempt EU Green Deal procurement mandates. Threat of silicone-based platform substitution by DowDuPont architectures demands accelerated compatibility testing investment. For New Entrants and Emerging Players: CDSCO-ICH alignment fast-tracks contract formulation opportunities in Maharashtra and Gujarat for parenteral drug delivery systems, bypassing saturated European and North American pilot-scale markets. Target food processing phase inversion applications in India and Brazil where thermal stability requirements favor lower-energy processing. Go-to-market leverage rests on pre-validated bio-surfactant offtake agreements with fermentation technology partners. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile parenteral manufacturing as 1000+ bar homogenization systems become table stakes for FDA cGMP compliance. Five-to-ten year viability favors acquisition of mid-scale European formulation labs with REACH-registered feedstock pipelines and established EMA stability validation track records. Signal to monitor: CDSCO inspection readiness scores at Indian contract manufacturers as proxy for competitive displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Production | Fermentation-derived rhamnolipid capacity secures EU Green Deal procurement preference ahead of mandates. |
| High-Pressure Homogenization Equipment Upgrade | 1000+ bar systems in Germany and Switzerland lock in sterile parenteral premium positioning through tight droplet control. |
| CDSCO-Aligned Contract Manufacturing Partnership | PLI scheme incentives in Maharashtra reduce import dependency for domestic pharmaceutical production expansion. |
| Pharmacopeial Monograph Pre-Submission | EMA accelerated aging protocol validation extends development timelines but blocks competitor surfactant substitutions. |
| Phase Inversion Method Deployment | Cost-optimized agrochemical processing in Brazil and India captures volume growth without precision equipment capital. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across formulation labs, pharmaceutical contract manufacturers, personal care brand owners, and agrochemical blenders. Secondary validation drew from EMA stability guideline documents, FDA cGMP inspection observations, REACH registration databases, and SEC filings from integrated surfactant suppliers. Bottom-up capacity assessments at high-pressure homogenization facilities were triangulated against top-down market sizing from pharmaceutical and personal care procurement spend analysis.
Across the projection horizon, the analytical framework modeled segmentation by product type (oils, surfactants, co-surfactants, water), application (pharmaceuticals, cosmetics, food industry, agrochemicals), and processing technology (high-pressure homogenization, ultrasonication, microfluidization, phase inversion). CAGRs were derived from volume-throughput buildups at identified contract manufacturing facilities, cross-referenced against regulatory approval timelines and feedstock capacity expansion announcements. Industry-specific inputs included CDSCO inspection readiness scoring and EU Green Deal bio-surfactant mandate implementation trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and CDSCO-ICH alignment; material deviation in regulatory chemistry requirements or surfactant feedstock availability would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Bitumen Emulsifier Market
Surfactants
Global Rhamnolipid Market
Surfactants
Cetanol Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Specialty Surfactants Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Detergent Chemicals Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Zeolite for Detergents Market