
 Amphoteric Emulsifier Market | 2026-2036
Amphoteric Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Amphoteric Emulsifier Market Outlook
China's Yangtze River Delta chemical corridor is reshaping regional supply dynamics for amphoteric emulsifiers. Evonik Industries AG leverages its German R&D base to sustain technology leadership in phospholipid formulations. Stepan Company anchors North American production through integrated fatty acid chemistry operations. Cargill Inc. competes in plant-derived segments with backward integration into vegetable oil feedstocks.
Amphoteric emulsifiers are surface-active compounds bearing both cationic and anionic functional groups, typically synthesized through phosphorylation or amino acid condensation reactions yielding pH-responsive interfacial stability. These molecules reduce surface tension between immiscible phases, enabling stable oil-in-water dispersions in cosmetic creams, drug delivery systems, and food emulsions. Phospholipid grades command premium positioning in pharmaceutical applications due to biocompatibility requirements, while alkyl amino acid variants are gaining fastest in personal care as sulfate-free formulations proliferate. Liquid concentrates dominate volume throughput for industrial coatings, though powder forms retain margin advantages in food processing where moisture sensitivity constrains formulation options.
EMA pharmaceutical excipient guidelines and REACH Annex XVII restrictions on ethoxylated surfactants are elevating amphoteric alternatives in European formularies. China's NMPA cosmetic ingredient filing requirements and GB standards for food additives are synchronizing compliance costs across the supply chain. FDA GRAS determinations and EPA Safer Choice specifications in the United States further segment product qualification pathways by end-use. Stakeholders must monitor regulatory divergence between cosmetic and food-grade specifications when allocating capacity across phospholipid versus synthetic amino acid chemistries.
Market Dynamics
Sulfate-free formulation mandates in personal care are compressing demand for traditional anionic surfactants while elevating alkyl amino acid emulsifiers across Southeast Asian cosmetic manufacturing clusters. REACH Annex XVII restrictions on ethoxylated compounds are simultaneously redirecting European pharmaceutical procurement toward phospholipid-derived alternatives.
Growth Catalysts
- REACH compliance deadlines:ECHA's tightening purity specifications for cosmetic-grade phospholipids are forcing formulators to upgrade emulsifier specifications, creating qualified-supplier premiums for compliant manufacturers.
- Sulfate-free personal care:Clean beauty positioning among Southeast Asian cosmetic brands is accelerating procurement of mild amphoteric surfactants for facial cleansers and baby care formulations.
- Yangtze River Delta concentration:China's coastal chemical clusters are scaling dedicated alkyl amino acid production lines, reducing import dependency for domestic cosmetics manufacturers.
Market Restraints
- Phospholipid feedstock volatility:Rapeseed and soybean oil price swings transmit directly into phosphatidylcholine production costs, compressing margins for European pharmaceutical-grade suppliers.
- Specialized reactor requirements:Amino acid condensation chemistry demands corrosion-resistant stainless steel vessels with precise temperature control, elevating capital intensity versus conventional surfactant synthesis.
- Regulatory divergence:FDA GRAS determinations for food-grade amphoterics remain misaligned with EFSA purity thresholds, forcing dual-track qualification investments for multinational suppliers.
Strategic Opportunities
- India personal care penetration:BIS cosmetic ingredient standards are formalizing, creating first-mover advantages for suppliers establishing local technical service capabilities ahead of enforcement.
- Biopharma drug delivery:Liposomal formulation growth for mRNA therapeutics is expanding demand for injection-grade phospholipid emulsifiers with endotoxin specifications below 10 EU/g.
- Green chemistry procurement mandates:Germany's chemical sector sustainability requirements are prioritizing plant-derived feedstock traceability, rewarding backward-integrated vegetable oil processors.
Industry Challenges
- Cross-functional formulation expertise:Personal care brands require emulsifier suppliers to demonstrate compatibility with microbiome-friendly preservative systems, demanding expanded technical service teams.
- Dual-use certification timelines:Cosmetic-to-food grade conversion for alkyl amino acid plants requires 18-24 month FSSAI or FDA requalification, constraining capacity reallocation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphoteric Emulsifier Market |
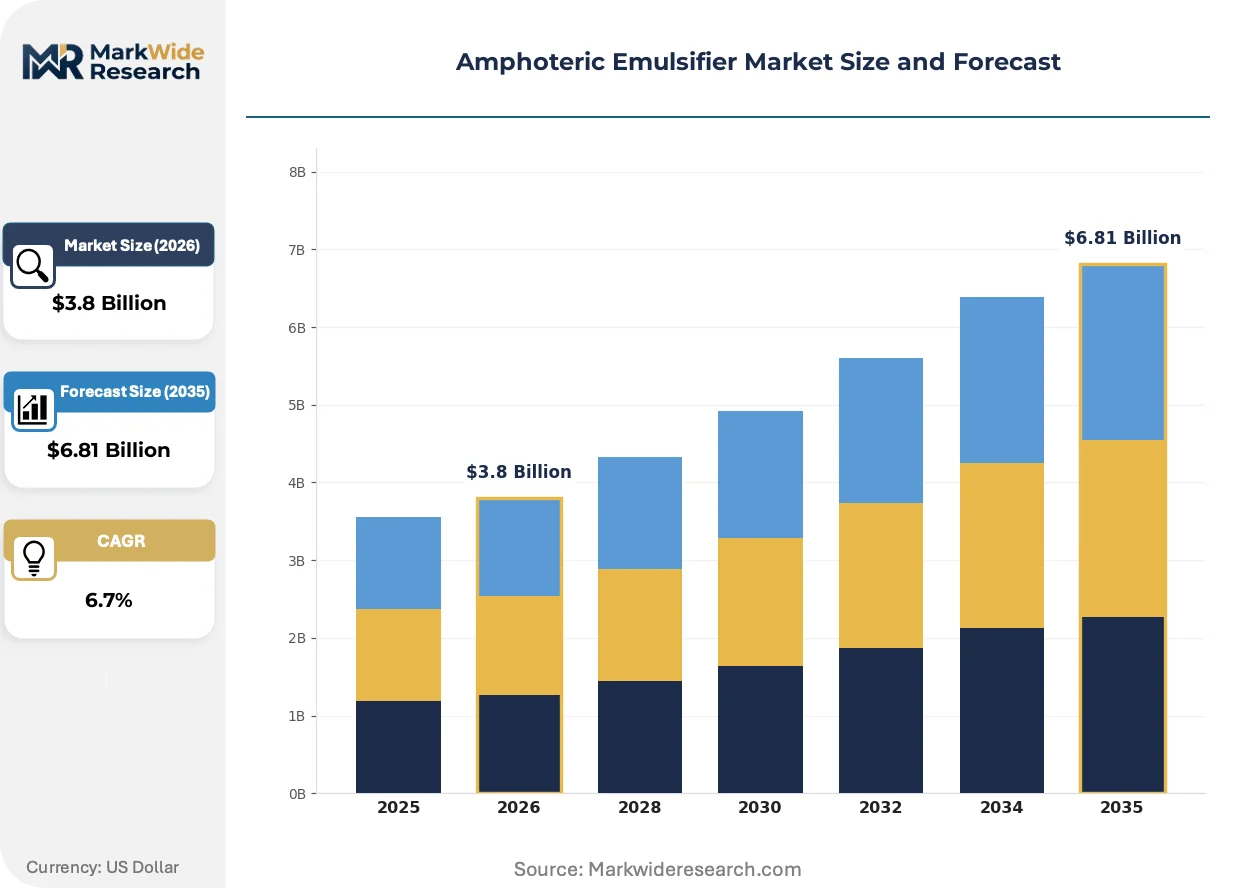
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoalkyl Phosphate, Dialkyl Phosphate, Alkyl Amino Acid, Phospholipids Application: Personal Care, Food & Beverages, Pharmaceuticals, Industrial Coatings Form: Liquid, Powder, Granules, Concentrate End User: Cosmetics Manufacturers, Food Processors, Pharmaceutical Companies, Paint Producers |
| Companies Covered | Cargill Inc., The Lubrizol Corporation, du Pont de Nemours and Company, Evonik Industries AG, Chemoran, Stepan Company, Kalichem Srl, SURFAX S.A. de C.V., SISTerna B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphoteric Emulsifier Market Strategic Shifts
Process analytical technology is penetrating amphoteric emulsifier manufacturing, replacing batch-end testing with real-time quality verification. Digital integration across synthesis and formulation is compressing development cycles while elevating specification consistency.
Inline Raman spectroscopy is digitizing phosphorylation reaction monitoring, enabling closed-loop control of phospholipid headgroup substitution ratios. European pharmaceutical excipient manufacturers are deploying these systems to reduce batch-to-batch variability for liposomal drug delivery applications. The technology is digitizing quality assurance workflows, shifting resource allocation from laboratory testing toward process engineering.
EMA's revised pharmaceutical excipient guidelines are elevating elemental impurity thresholds for parenteral-grade emulsifiers, forcing suppliers to implement dedicated production lines with acid-washed equipment protocols. German manufacturers are responding by segregating pharmaceutical and cosmetic production assets to avoid cross-contamination risks. The regulation is accelerating capital deployment into single-purpose reactor infrastructure across the Rhine-Ruhr chemical corridor.
Direct technical engagement between emulsifier suppliers and indie cosmetic brands is displacing traditional distributor relationships in Southeast Asia. Formulators in Indonesia and Vietnam are accessing application laboratories through supplier digital platforms, bypassing regional chemical traders. The pattern concentrates in mid-tier personal care manufacturers seeking rapid prototype turnaround for sulfate-free launches.
Amphoteric Emulsifier Market Segmentation
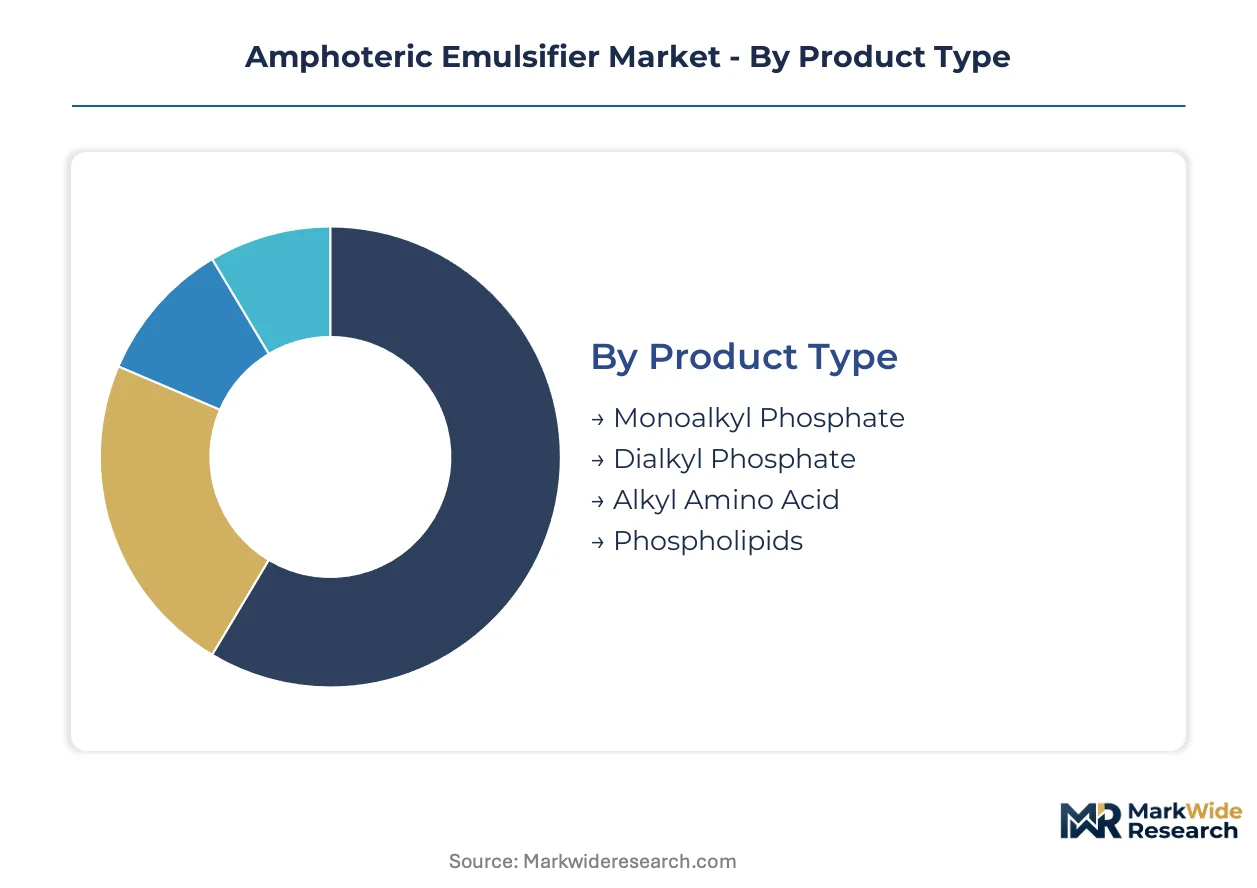
Segmentation in the amphoteric emulsifier market reveals divergent margin structures and qualification barriers across chemistries and end-uses. Formulators face distinct procurement cycles depending on whether they source phospholipid grades for parenteral applications or alkyl amino acids for rinse-off cosmetics.
Product Type:
Inventory velocity varies dramatically across these chemistries, with alkyl amino acid variants turning over fastest due to sulfate-free formulation proliferation while phospholipid grades sit longer due to endotoxin testing protocols.
- Monoalkyl Phosphate:Single-chain phosphate esters synthesized through partial phosphorylation of fatty alcohols deliver intermediate hydrophilic-lipophilic balance values. Facial cleanser formulators in Indonesia's Batam cosmetic cluster specify these for mild foaming systems that comply with ASEAN cosmetic directive irritancy thresholds.
- Dialkyl Phosphate:Diester structures formed from complete phosphorylation of C12-C18 alcohol fractions exhibit stronger lipophilic character and superior emulsion stability in waxy cosmetic bases. German pharmaceutical excipient manufacturers favor these for topical cream applications where EMA impurity limits apply.
- Alkyl Amino Acid:Condensation products of fatty acids with sarcosine or glutamic acid deliver pH-responsive mildness prized by sulfate-free personal care brands.
- Phospholipids:Naturally derived phosphatidylcholine and phosphatidylethanolamine fractions command premium positioning in liposomal drug delivery systems.
Alkyl amino acid variants anchor the volume base while phospholipid grades gain share at the steepest rate.
Application:
Cost tier stratification separates commodity food-grade specifications from pharmaceutical-grade premiums requiring dedicated production lines.
- Personal Care:Sulfate-free facial cleansers, baby shampoos, and microbiome-friendly moisturizers drive procurement of mild amphoteric surfactants. Southeast Asian contract manufacturers in Vietnam's Binh Duong province specify alkyl amino acids for export to EU clean beauty brands.
- Food & Beverages:Emulsification of chocolate coatings, dairy analogs, and beverage clouding systems employs phospholipid and synthetic amino acid grades. Chinese food additive GB standards constrain supplier selection for domestic processors.
- Pharmaceuticals:Parenteral and topical drug delivery applications demand endotoxin-controlled phospholipid emulsifiers with documented excipient master files.
- Industrial Coatings:Waterborne paint systems utilize liquid concentrates for pigment dispersion and wetting efficiency in high-volume architectural applications.
Personal care applications dominate procurement volume while pharmaceutical specifications capture the widest margin spreads.
Form:
Moisture sensitivity and handling economics determine form selection across end-use environments.
- Liquid:Pumpable concentrates with standardized active content simplify bulk handling for industrial coatings manufacturers. Rhine-Ruhr chemical corridor suppliers ship these in dedicated ISO tank containers to paint producers.
- Powder:Spray-dried or agglomerated forms with low residual moisture suit food processing operations where water activity constraints apply. Free-flowing properties enable pneumatic conveying in bakery and confectionery plants.
- Granules:Intermediate particle size distributions balance dissolution rate with dust control for mid-scale cosmetic compounders.
- Concentrate:High-active formulations reduce freight costs for distant personal care manufacturing sites but require heated storage infrastructure.
Liquid forms move the highest tonnage while powder grades retain the most stable pricing.
End User:
Customer sophistication and technical service requirements segment the supplier base by account management intensity.
- Cosmetics Manufacturers:Indie brands and multinational personal care houses demand rapid prototype support and preservative compatibility data. Direct supplier relationships are displacing regional distributors in Jakarta and Ho Chi Minh City.
- Food Processors:Large-scale dairy and confectionery operations prioritize batch-to-batch consistency and kosher/halal certification over formulation support.
- Pharmaceutical Companies:Biopharma liposome developers and generic topical manufacturers require excipient drug master files and audit access to production facilities.
- Paint Producers:Architectural and industrial coatings formulators seek cost-optimized liquid concentrates with minimal technical service overhead.
Cosmetics manufacturers generate the most intensive technical service demand while paint producers drive the highest volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amphoteric emulsifier manufacturing clusters along Germany's Rhine-Ruhr corridor and China's Yangtze River Delta dominate qualified supply capacity. Regulatory divergence between EMA pharmaceutical guidelines and China's NMPA cosmetic filings shapes regional procurement strategies. Formulators in Southeast Asian manufacturing hubs increasingly source from nearby Chinese alkyl amino acid producers to compress lead times.
Germany
EMA's revised pharmaceutical excipient guidelines drive investment in dedicated parenteral-grade production lines. REACH Annex XVII restrictions on ethoxylated surfactants redirect European formulators toward phospholipid-derived alternatives. The Rhine-Ruhr chemical corridor hosts segregated reactor infrastructure to prevent cross-contamination between cosmetic and pharmaceutical grades.
China
Domestic cosmetics brands in the Yangtze River Delta are scaling procurement of locally manufactured alkyl amino acid emulsifiers. NMPA cosmetic ingredient filing requirements synchronize compliance costs for multinational suppliers operating in the market. Shanghai and surrounding chemical clusters are expanding dedicated production capacity for sulfate-free personal care formulations.
United States
FDA GRAS determinations for food-grade amphoteric emulsifiers create distinct qualification pathways from pharmaceutical specifications. EPA Safer Choice program preferences elevate plant-derived surfactants in federal procurement. Stepan Company anchors North American production through integrated fatty acid chemistry operations in Illinois and New Jersey.
India
BIS cosmetic ingredient standards formalization creates first-mover advantages for suppliers establishing local technical service capabilities. FSSAI dual-use certification timelines of 18-24 months constrain rapid capacity reallocation between cosmetic and food grades. Maharashtra and Gujarat chemical zones attract investment from multinational emulsifier suppliers seeking proximity to domestic personal care manufacturers.
Vietnam
Contract manufacturers in Binh Duong province specify alkyl amino acid emulsifiers for export to EU clean beauty brands. ASEAN cosmetic directive irritancy thresholds align procurement specifications with European formulator requirements. Ho Chi Minh City-based compounders are bypassing regional distributors through direct supplier digital platforms.
Amphoteric Emulsifier Market Competitive Environment
Integrated chemical conglomerates and specialized surfactant manufacturers split the market between scale-driven commodity supply and qualification-intensive premium segments. The vendor base concentrates around three strategic archetypes: backward-integrated vegetable oil processors, dedicated surfactant synthesis specialists, and pharmaceutical-grade excipient suppliers. Capacity expansion in Asia-Pacific manufacturing clusters and technology licensing for process analytical systems represent the dominant competitive moves.
Within the integrated processor tier, Cargill Inc. exemplifies backward integration into vegetable oil feedstocks for plant-derived emulsifier production. Among dedicated surfactant specialists, Stepan Company anchors North American manufacturing through captive fatty acid chemistry operations. Evonik Industries AG occupies a position in the pharmaceutical-grade excipient segment, leveraging German R&D infrastructure for phospholipid formulation technology.
| Leading Market Players |
|---|
| Cargill Inc. |
| The Lubrizol Corporation |
| du Pont de Nemours and Company |
| Evonik Industries AG |
| Chemoran |
| Stepan Company |
| Kalichem Srl |
| SURFAX S.A. de C.V. |
| SISTerna B.V. |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr to Yangtze River Delta freight corridors transmit rapeseed oil price volatility directly into phospholipid emulsifier landed costs, concentrating pricing power with backward-integrated vegetable oil processors while compressing margins for synthetic amino acid producers facing sulfur-free formulation procurement deadlines.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the European market, separating pharmaceutical-grade phospholipids with endotoxin documentation from cosmetic-grade alkyl amino acids. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with EMA excipient master files commanding substantial premia over BIS-compliant cosmetic grades. Pricing pressure stems from rapeseed and soybean oil commodity swings, which transmit rapidly into phosphatidylcholine production economics. Paint producers exhibit the highest price sensitivity due to liquid concentrate commoditization, while biopharma liposome developers demonstrate minimal elasticity for injection-grade specifications.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for European pharmaceutical formulators sourcing alkyl amino acids. Manufacturing concentrates in Germany, China, and the United States, with the Yangtze River Delta scaling dedicated capacity for sulfate-free personal care feedstocks. Feedstock dependencies center on vegetable oil fractions, fatty alcohols, and amino acid precursors. Single-source vulnerability persists for endotoxin-controlled phospholipids qualified under EMA guidelines. Distribution runs through direct technical engagement platforms that displace regional chemical distributors in Southeast Asian cosmetic manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulfate-free formulation mandates and liposomal drug delivery expansion are disrupting procurement patterns faster than incumbent capacity can adapt, creating asymmetric opportunities for qualified suppliers.
For Market Incumbents: Build regulatory moats through segregated pharmaceutical-grade production assets that preempt cross-contamination risks under EMA revised excipient guidelines. Defensive consolidation should prioritize captive fatty acid chemistry operations in North America to offset REACH-driven European cost inflation. Process analytical technology investments in inline Raman spectroscopy compress batch-to-batch variability for liposomal applications, defending margin position against commodity surfactant substitutes. For New Entrants and Emerging Players: India's Maharashtra and Gujarat chemical zones offer geographic underpenetration ahead of BIS cosmetic ingredient standards formalization. White-space targets include technical service capabilities for microbiome-friendly preservative compatibility and rapid prototype support for indie cosmetic brands. Direct digital platform engagement with Ho Chi Minh City and Jakarta compounders bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated vegetable oil processors seeking to monetize backward-integrated emulsifier divisions. Long-term viability favors assets with dual cosmetic-pharmaceutical qualification pathways and established excipient master files. The signal to watch is NMPA filing acceleration for alkyl amino acid producers, indicating compliance cost synchronization favorable to consolidated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Feedstocks | Cargill's captive supply of rapeseed and soybean fractions insulates phospholipid margins from commodity volatility. |
| Process Analytical Technology Deployment | Inline Raman spectroscopy at Evonik's German facilities reduces batch-to-batch variability for EMA-compliant pharmaceutical grades. |
| Segregated Pharmaceutical Production Lines | Rhine-Ruhr manufacturers deploy acid-washed equipment protocols to satisfy EMA elemental impurity thresholds for parenteral applications. |
| Direct Digital Platform Engagement | Supplier technical service platforms displace regional distributors in Vietnam's Binh Duong contract manufacturing cluster. |
| Dual-Use Certification Investment | Alkyl amino acid producers absorbing 18-24 month FSSAI requalification timelines constrain competitor capacity reallocation flexibility. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at downstream cosmetic OEMs, and technical R&D directors anchors the qualitative findings. Secondary sources include customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and NMPA cosmetic ingredient filing databases. Bottom-up capacity modeling triangulates against top-down demand segmentation across personal care, pharmaceutical, food, and industrial coatings end-uses.
Calibration against historical price realizations for phospholipid and alkyl amino acid grades informs the projection framework across the analysis window. Segmentation dimensions encompass chemistry type, application sector, form specification, and regional production hub. CAGRs derive from installed capacity expansion announcements, regulatory deadline impacts, and substitution elasticity estimates for sulfate-free formulations. Forecast inputs incorporate REACH compliance cost trajectories and Yangtze River Delta capacity buildout timelines.
Practitioners should monitor rapeseed oil price volatility, EMA excipient guideline enforcement intensity, and NMPA filing velocity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Asia Pacific Surfactants Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Selenium Sulphide Market
Surfactants
Cetanol Market
Surfactants
Glycol Monostearate Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Wetting Agents Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Defoamers Market
Surfactants
Global Biosurfactant Market
Surfactants
Chlorooctane Market