
 Amino Acid Surfactants Market | 2026-2036
Amino Acid Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acid Surfactants Market Analysis
A widening capital-intensity gap between integrated feedstock producers and formulation specialists is rotating competitive advantage toward upstream capabilities. Ajinomoto Co., Inc. leverages its fermentation technology heritage to secure consistent amino acid precursor supply. BASF SE anchors its position through backward integration into fatty alcohol and amino acid chemistry. Galaxy Surfactants Ltd. competes on specialized personal care formulations for emerging Asian markets.
Amino acid surfactants comprise amphiphilic molecules built from amino acid headgroups and fatty acid tails, typically synthesized through acylation or N-acylation reactions yielding pH-compatible, biodegradable surface-active agents. These compounds reduce surface tension at concentrations as low as 0.1% and serve primarily as mild cleansing agents in sulfate-restricted personal care and sensitive-skin applications. Sodium Cocoyl Isethionate dominates liquid facial cleanser formulations due to its dense foam profile and skin compatibility, while Disodium Cocoyl Glutamate captures expanding share in premium rinse-off products where ultra-mildness commands margin premiums. Personal Care applications lead value generation, though Household Cleaning channels are deepening penetration as European retailers enforce green procurement standards.
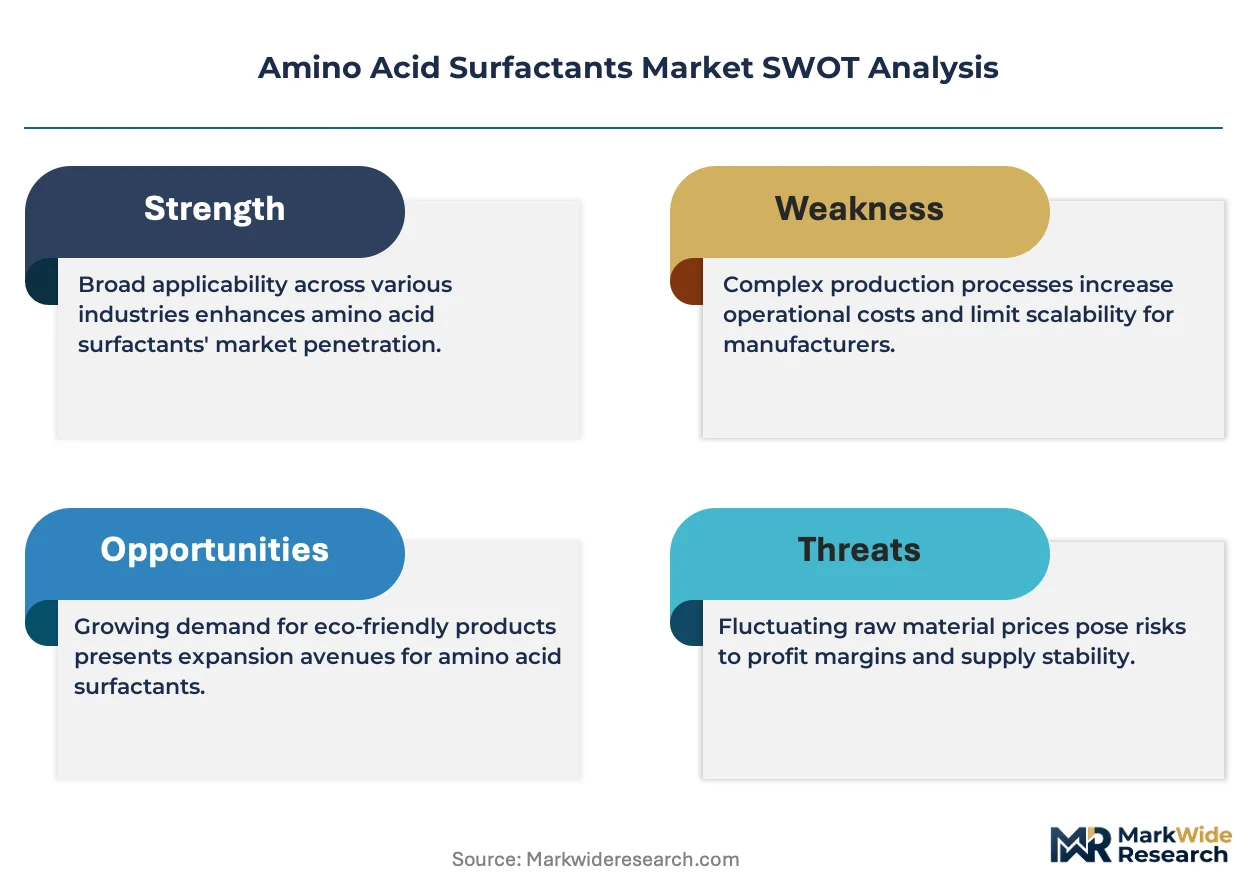
REACH registration requirements and the EU Green Deal's chemical sustainability targets are tightening specifications for biodegradability and aquatic toxicity, directly elevating amino acid surfactant qualification rates against conventional alternatives. FDA cosmetic ingredient reviews and China's GB standards for surfactant safety are converging toward stricter dermal irritation thresholds that favor these milder chemistries. Stakeholders must monitor regulatory harmonization momentum between Europe and Asia-Pacific to anticipate formulation reformulation cycles and raw material qualification timelines.
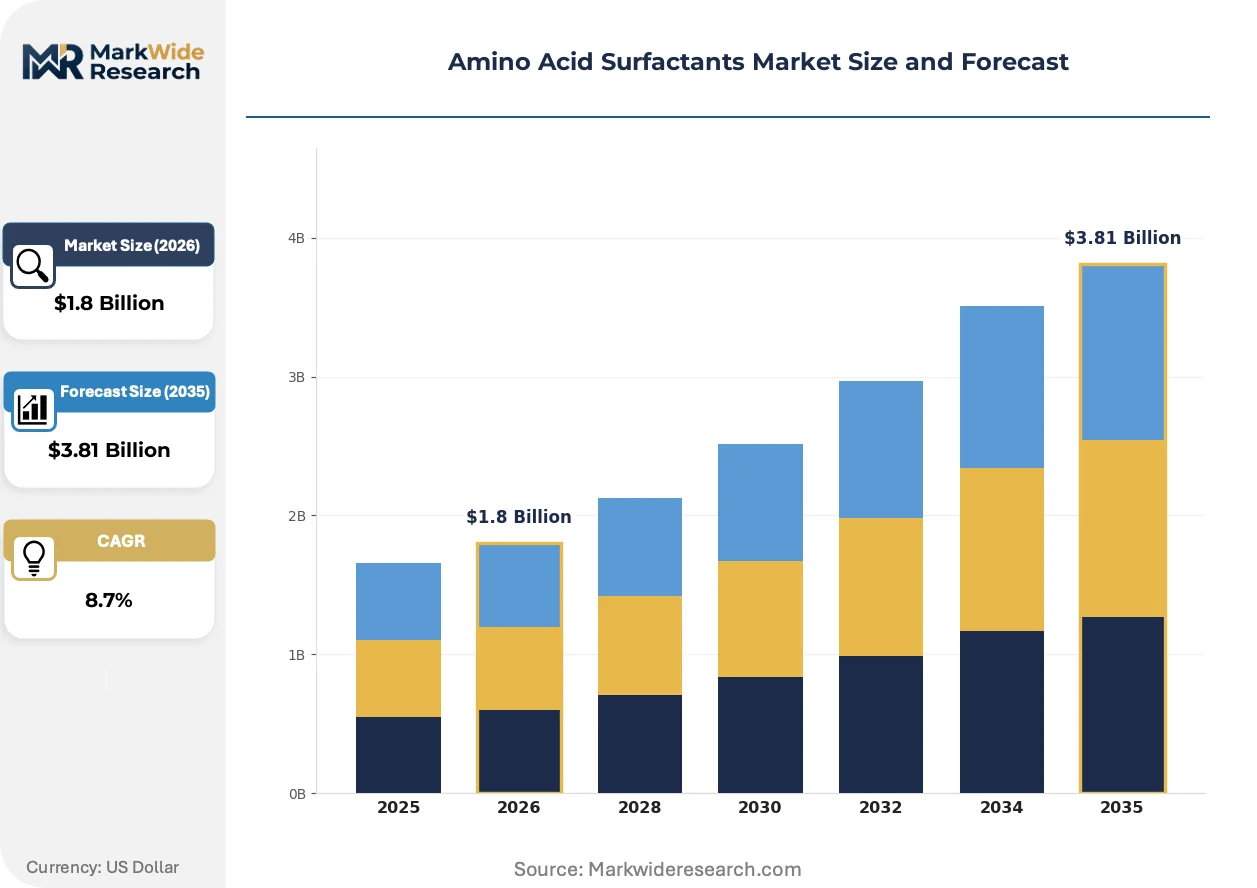
Market Dynamics
REACH registration deadlines and EU Green Deal chemical sustainability targets are compressing qualification timelines for bio-based surfactants, forcing reformulation cycles that favor amino acid-based alternatives over petrochemical legacy chemistries.
Growth Catalysts
- EU Green Deal chemical sustainability mandates:REACH registration requirements tighten biodegradability and aquatic toxicity specifications, elevating amino acid surfactant qualification rates against conventional alternatives in European personal care formulations.
- Sulfate-free personal care demand:Clean-label cosmetic manufacturers in China scale production of mild cleansing products, concentrating procurement of sodium cocoyl isethionate and glutamate-derived surfactants for sensitive-skin applications.
- Fermentation technology maturation:Bioprocess advances reduce amino acid precursor production costs, improving feedstock economics for acylation reactions that yield pH-compatible surfactant molecules.
Market Restraints
- Fatty alcohol price volatility:Palm kernel and coconut oil feedstock fluctuations transmit directly to surfactant manufacturing costs, compressing margins for non-integrated producers lacking captive fatty acid supply.
- Upstream concentration in Southeast Asia:Oleochemical feedstock refining clusters in Indonesia and Malaysia create geographic supply risk for European and North American formulators dependent on imported fatty alcohols.
- Performance limitations in hard water:Amino acid surfactants exhibit reduced foaming stability and cleansing efficacy in high-calcium water conditions, restricting household cleaning applications versus synthetic alternatives.
Strategic Opportunities
- India personal care market penetration:Domestic cosmetic manufacturers under BIS standards compliance timelines seek mild surfactant alternatives for sulfate-free shampoo and facial cleanser production targeting urban middle-class consumers.
- Enzymatic synthesis convergence:Lipase-catalyzed acylation processes reduce reaction temperatures and solvent requirements, enabling energy-efficient production of specialty amino acid surfactants for premium rinse-off segments.
- Green procurement retail mandates:European supermarket chains enforce chemical sustainability scorecards that prioritize biodegradable surfactants, creating qualification pathways for amino acid-based household cleaning formulations.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise for amino acid production concentrates among legacy food-grade manufacturers, limiting new entrant access to qualified technical personnel.
- REACH dossier compilation timelines:Extended substance registration periods for novel surfactant chemistries delay market entry, requiring 18-24 month pre-launch investment without revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acid Surfactants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Lauryl Sarcosinate, Sodium Cocoyl Isethionate, Disodium Cocoyl Glutamate, Sodium Lauroyl Methyl Isethionate Application: Personal Care, Household Cleaning, Industrial Cleaning, Food Processing End User: Cosmetic Manufacturers, Household Product Companies, Food Industry, Textile Producers Formulation Type: Liquid, Powder, Gel, Bar |
| Companies Covered | Changsha Puji Biotechnology Co., Ltd., Galaxy Surfactants Ltd., Ajinomoto Co., Inc., Zschimmer & Schwarz, Miwon Commercial Co., Ltd., Clariant AG, BASF SE, Croda International Plc, Sino Lion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acid Surfactants Market Emerging Trajectories
Formulation science advances and regulatory chemistry requirements are converging to reposition amino acid surfactants from niche mildness additives toward mainstream performance ingredients across rinse-off personal care and household cleaning categories.
Enzymatic acylation using immobilized lipase biocatalysts is displacing traditional chemical synthesis routes for N-acyl amino acid production. Specialty chemical manufacturers in Japan and Germany adopt these bioprocesses to reduce solvent waste and energy consumption. This technology is displacing capital-intensive chemical plant investments while enabling modular production scales that match regional formulation demand.
China's GB standards for cosmetic surfactant safety are converging with EU REACH irritation thresholds, creating regulatory harmonization pressure on multinational personal care brands. Domestic Chinese manufacturers accelerate clean-label production to meet both export and domestic premium segment requirements. Facial cleanser and baby care categories face the most immediate reformulation timelines as dual-compliance becomes mandatory for market access.
Direct-to-consumer cosmetic brands compress traditional distributor channels, altering surfactant procurement patterns toward smaller batch sizes with faster turnaround. These brands prioritize ingredient transparency certifications over legacy performance benchmarking, shifting supplier selection criteria. This channel evolution concentrates in China's tier-one cities and South Korean digital-native beauty markets where consumer education on sulfate-free benefits drives premium positioning.
Amino Acid Surfactants Market Segmentation
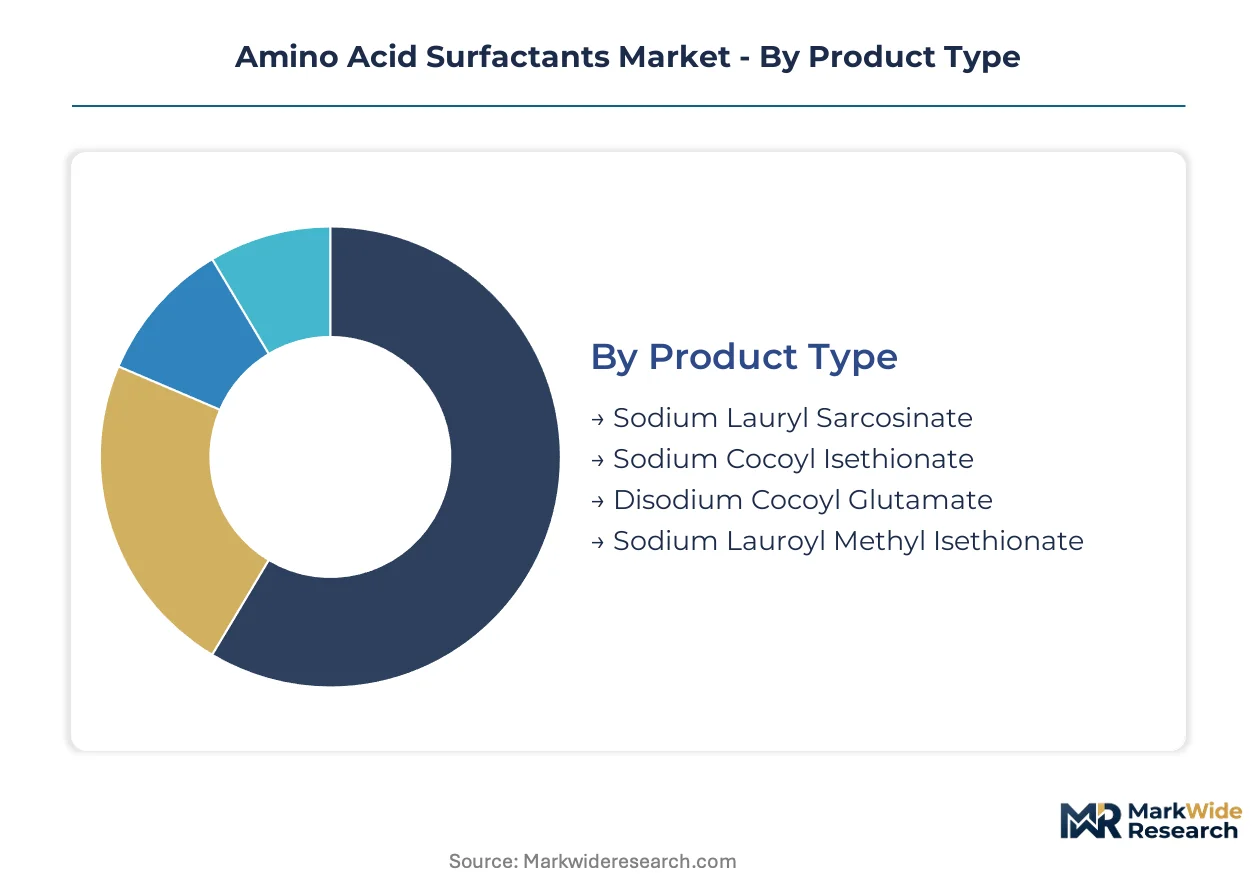
Amino acid surfactant value pools fragment across molecular architectures, application performance requirements, and formulation compatibility constraints. Understanding margin distribution by segment enables targeted capacity allocation and technical service investment.
Product Type:
Margin concentration tracks molecular complexity and patent protection status, with acylated glutamates commanding premium positioning over commodity sarcosinates.
- Sodium Cocoyl Isethionate:A coconut fatty acid-derived surfactant combining dense foam generation with exceptional skin compatibility. Procurement concentrates among Chinese facial cleanser manufacturers responding to GB standards for mild cleansing agents in sulfate-free formulations.
- Disodium Cocoyl Glutamate:An ultra-mild anionic surfactant produced through glutamic acid acylation, prized for tear-free properties in baby care applications. European premium rinse-off brands under REACH compliance timelines drive qualification volumes for this higher-cost chemistry.
- Sodium Lauryl Sarcosinate:An amino acid-based surfactant derived from sarcosine with established cost-positioning in mass-market personal care.
- Sodium Lauroyl Methyl Isethionate:A modified isethionate variant offering enhanced hard-water tolerance for emerging market formulations.
The dominant share belongs to Sodium Cocoyl Isethionate, while Disodium Cocoyl Glutamate is closing the gap fastest.
Application:
Volume throughput and technical service intensity diverge sharply between performance-driven personal care and specification-driven industrial segments.
- Personal Care:Facial cleansers, shampoos, and baby care products requiring mildness certification and dermatological testing. Chinese domestic cosmetic manufacturers scaling clean-label production represent the steepest expansion trajectory for amino acid surfactant procurement.
- Household Cleaning:Dishwashing liquids and surface cleaners where European retailer green procurement scorecards mandate biodegradable surfactant substitution. German and French supermarket chains enforce chemical sustainability thresholds that favor amino acid alternatives over petrochemical legacy chemistries.
- Industrial Cleaning:Metal degreasing and equipment sanitation applications with stringent foam control requirements.
- Food Processing:Equipment cleaning agents requiring regulatory clearance for incidental food contact.
Personal Care generates the dominant revenue share, though Household Cleaning is climbing the fastest as retail mandates harden.
End User:
Procurement sophistication and formulation partnership depth separate cosmetic-grade qualification from commodity surfactant purchasing.
- Cosmetic Manufacturers:Brands and contract manufacturers requiring batch certification, traceability documentation, and co-development support for sensitive-skin positioning.
- Household Product Companies:Detergent and cleaner producers balancing cost targets against emerging green label requirements.
- Food Industry:Processing equipment sanitation specialists governed by national food safety regulators.
- Textile Producers:Fiber scouring and dyeing auxiliaries seeking biodegradable wetting agents.
Cosmetic Manufacturers command the dominant procurement volume, while Household Product Companies are gaining share fastest through sustainability-driven reformulation.
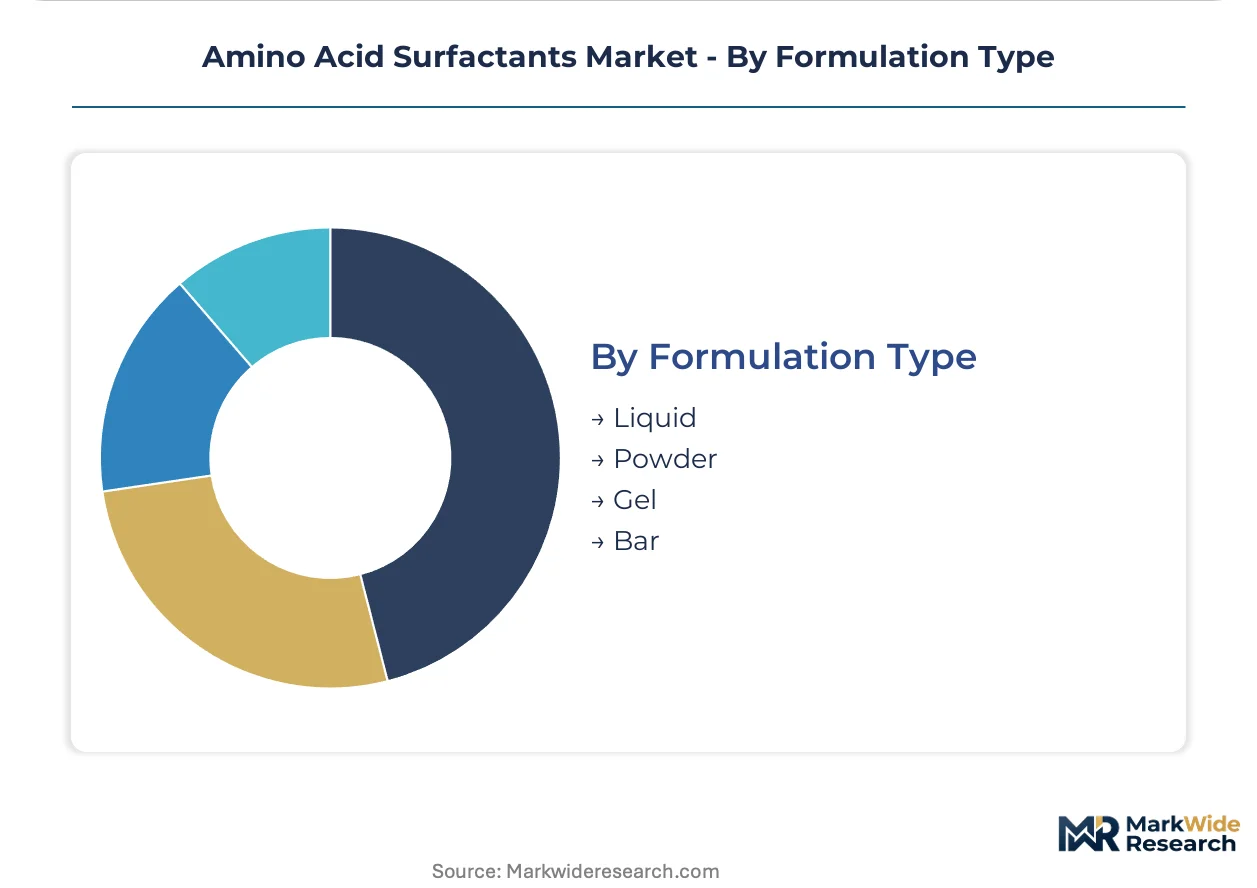
Formulation Type:
Physical form selection constrains manufacturing asset utilization and logistics cost structures across the value chain.
- Liquid:Ready-to-use concentrates dominating facial cleanser and body wash production with minimal downstream processing requirements.
- Powder:Dry blends enabling formulation flexibility and reduced shipping weights for distant manufacturing locations.
- Gel:Structured systems for premium positioning and controlled release applications.
- Bar:Solid cleansing formats experiencing renewed interest in plastic-free personal care positioning.
Liquid formulations hold the dominant share, though Powder is expanding most quickly for supply chain efficiency in emerging market distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cosmetic manufacturers demonstrate the lowest price elasticity for amino acid surfactant procurement, absorbing premium costs for sulfate-free certification, while European household cleaning formulators remain highly sensitive to fatty alcohol feedstock fluctuations. Indian domestic brands occupy a middle position, trading mildness claims against local cost benchmarks. Brazilian mass-market producers show the highest elasticity, delaying bio-based adoption until petrochemical parity emerges.
China
Domestic facial cleanser manufacturers in Shanghai and Guangzhou scale clean-label production for sulfate-free positioning. GB standards for cosmetic surfactant safety tighten dermal irritation thresholds, accelerating qualification of sodium cocoyl isethionate and glutamate derivatives. The Yangtze River Delta cluster concentrates fermentation-based amino acid precursor capacity serving both captive use and merchant sales.
Germany
Household cleaning formulators face supermarket chain green procurement scorecards mandating biodegradable surfactant substitution. REACH registration requirements and EU Green Deal chemical sustainability targets compress qualification timelines for bio-based alternatives. The North Rhine-Westphalia chemical corridor anchors oleochemical refining and surfactant formulation capabilities for European distribution.
United States
Direct-to-consumer cosmetic brands compress procurement patterns toward smaller batch sizes with faster turnaround for ingredient transparency positioning. FDA cosmetic ingredient reviews converge toward stricter mildness benchmarks that favor amino acid chemistries. New Jersey and California host contract manufacturing clusters serving digital-native beauty brands with sulfate-free formulation expertise.
India
Domestic shampoo and facial cleanser producers under BIS standards compliance timelines seek mild surfactant alternatives for urban middle-class consumers. The country's national cosmetic regulator tightens safety specifications for rinse-off products. Maharashtra and Gujarat concentrate personal care manufacturing capacity with emerging amino acid surfactant qualification programs.
Japan
Premium rinse-off brands prioritize ultra-mildness claims for sensitive-skin segmentation, accepting higher surfactant costs for dermatological positioning. METI guidelines on chemical substance management elevate biodegradability requirements for household applications. The Kansai region maintains specialized acylation technology capabilities for high-purity amino acid surfactant production.
Amino Acid Surfactants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where fermentation expertise and oleochemical integration define distinct advantage vectors. The market consolidates around three strategic groupings: integrated feedstock producers with captive amino acid supply, specialized surfactant formulators serving personal care niches, and diversified chemical conglomerates with backward integration into fatty alcohol chemistry. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players seeking to secure precursor supply or expand regional formulation services.
Among Asia-Pacific-based specialists, Ajinomoto Co., Inc. and Galaxy Surfactants Ltd. exemplify divergent archetypes—one anchored in fermentation heritage for precursor control, the other in specialized personal care formulation for emerging markets. European diversified players represented by BASF SE occupy positions defined by backward integration into both fatty alcohol and amino acid chemistry. These three companies illustrate how competitive positioning fragments across upstream technology mastery versus downstream formulation intimacy.
| Leading Market Players |
|---|
| Changsha Puji Biotechnology Co., Ltd. |
| Galaxy Surfactants Ltd. |
| Ajinomoto Co., Inc. |
| Zschimmer & Schwarz |
| Miwon Commercial Co., Ltd. |
| Clariant AG |
| BASF SE |
| Croda International Plc |
| Sino Lion |
| Others |
Supply Flow & Price Mechanics
Petrochemical surfactant substitution by amino acid-based alternatives simultaneously redistributes production capacity toward fermentation clusters in China and Japan while compressing margin structures for non-integrated European formulators dependent on imported fatty alcohols. This dual transformation elevates pricing power for upstream amino acid precursor producers while forcing downstream specialists toward volume commitments or captive supply investments.
Pricing Analysis
After-sales technical service contracts and formulation co-development agreements drive lifetime value capture beyond commodity surfactant sales. Pricing stratifies across premium-certified, standard-industrial, and economy-mass-market tiers differentiated by dermatological testing depth and REACH dossier completeness. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers scale sodium cocoyl isethionate output for facial cleanser applications. Cosmetic manufacturers in Japan exhibit the lowest price sensitivity, accepting premium positioning costs for sensitive-skin segmentation, while Brazilian mass-market household cleaning producers delay bio-based adoption until cost parity emerges.
Supply Chain Analysis
Strait of Malacca transit vulnerability for palm kernel and coconut oil feedstocks underwrites supply security planning for European and North American surfactant formulators. Manufacturing concentration in Indonesia, Malaysia, and the Philippines for oleochemical refining creates geographic dependency for fatty alcohol inputs. The value chain draws from fermentation-derived amino acids, acylation catalysts, and specialized pH buffering agents. Single-source vulnerability concentrates in Southeast Asian oleochemical clusters subject to El Niño-related crop yield volatility. Distribution runs through regional formulation centers serving personal care contract manufacturers and household cleaning compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amino acid surfactants occupy an early-cycle expansion phase where sulfate-free personal care penetration in China and green procurement mandates in Europe create simultaneous adoption tailwinds across distinct regional demand pools.
For Market Incumbents: Fortify upstream amino acid precursor supply through fermentation capacity additions in the Yangtze River Delta or backward integration into fatty alcohol refining. Incumbents must defend against specialty chemical entrants from Japan and Germany deploying enzymatic acylation technology by accelerating REACH dossier completion for novel surfactant variants before qualification timelines compress further. For New Entrants and Emerging Players: EU REACH registration fast-track pathways for bio-based surfactants create entry leverage for qualified technical personnel possessing fermentation scale-up expertise. New entrants should prioritize India's BIS compliance-driven reformulation cycle for sulfate-free shampoos and facial cleansers, deploying direct technical service partnerships with domestic cosmetic manufacturers in Maharashtra and Gujarat rather than distributor-dependent models. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors acquisition targets possessing captive amino acid supply or established REACH registration portfolios. Long-term viability hinges on feedstock integration depth rather than formulation specialization alone. Investors should monitor enzymatic synthesis patent filing velocity as an inflection indicator for process economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Precursors | Captive fermentation supply secures margin capture against fatty alcohol price volatility in Southeast Asian feedstock markets. |
| REACH Dossier Acceleration | Early registration completion locks qualification pathways before EU Green Deal chemical sustainability timelines compress further. |
| Enzymatic Synthesis Technology Licensing | Lipase-catalyzed acylation reduces energy consumption and solvent waste for premium rinse-off segment positioning. |
| India Market Technical Service Expansion | Direct formulation partnerships with domestic cosmetic manufacturers capture BIS compliance-driven reformulation demand. |
| Long-term Fatty Alcohol Supply Agreements | Contracted oleochemical feedstock mitigates palm kernel and coconut oil price transmission risk for European formulators. |
Methodological Framework
A standing panel of fermentation technology directors, personal care procurement leads at multinational brands, household cleaning formulation chemists, and REACH regulatory consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, ECHA registration dossiers, SEC chemical sector filings, and Chinese GB standards documentation. Bottom-up capacity estimates triangulated against top-down demand modeling from personal care and household cleaning end-use segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including molecular architecture, application performance tier, formulation compatibility, and regional regulatory cluster. CAGRs derived from production capacity expansion announcements, feedstock cost trajectory assumptions, and substitution elasticity estimates for sulfate-free personal care formulations. Industry-specific inputs incorporated enzymatic synthesis technology maturation curves and retailer green procurement scorecard implementation timelines.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and Chinese domestic cosmetic scaling assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH registration timeline adjustments and Southeast Asian oleochemical supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Specialty Surfactants Market
Surfactants
Powder Defoamers Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Micellar Water Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Microemulsions Market
Surfactants
Sodium Lauryl Sulphate Market