
 Asia-Pacific Kegs Market | 2026-2036
Asia-Pacific Kegs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Kegs Market Outlook
The Asia-Pacific kegs market is repositioning around a widening split between premium stainless steel units and commodity-grade plastic alternatives. BLEFA GmbH leverages its European engineering heritage to anchor high-margin contracts with premium brewers across Japan and South Korea. Ningbo BestFriends Beverage Containers Co. Ltd competes on manufacturing scale, sustaining cost leadership in the 20L and 30L steel segments that dominate Chinese domestic distribution.
Asia-Pacific kegs are cylindrical, reusable beverage containers typically fabricated from stainless steel or aluminum, with standardized valve and spear assemblies designed to withstand pressurized carbonated liquid handling and repeated sanitization cycles. Their primary commercial purpose is to transport draft beer, cider, and emerging ready-to-drink beverages from production facilities to on-premise consumption points. Steel kegs occupy the structural core of regional volume, while plastic variants represent the fastest-growing material category as microbreweries seek lower capital entry points. The 20L capacity tier leads absolute unit demand, though 50L configurations command concentrated margin pools within large-format brewery direct-sales channels.
China's SAMR enforces GB standards governing food-contact metal migration limits, while Japan's METI administers JIS certification requirements that shape import eligibility for foreign-manufactured kegs. Australia's TGA-aligned state food safety regulators impose parallel traceability mandates that elevate compliance costs for new market entrants. Stakeholders must monitor diverging material certification timelines across these frameworks to optimize regional production footprints and avoid customs detention at port of entry.
Market Dynamics
The Asia-Pacific kegs market is bifurcating around China's tightening GB standards for food-contact metals, which are forcing stainless steel suppliers to recertify alloys while simultaneously accelerating plastic keg adoption among cost-sensitive microbreweries.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of stricter food-contact metal migration limits is elevating certified stainless steel keg premiums and rewarding pre-qualified domestic manufacturers.
- Draft Beer Infrastructure:Australia's hospitality corridor linking Sydney and Melbourne is seeing concentrated investment in pressurized dispensing systems that require compatible steel fleet expansion.
- Ready-to-Drink Beverages:Cider and RTD producers across Japan and South Korea are repurposing existing keg logistics networks for carbonated alternative beverages.
Market Restraints
- Aluminum Price Volatility:Input cost swings for 304-grade stainless steel and aluminum alloys compress margin predictability for fabricators serving price-locked annual contracts.
- Import Certification Friction:Japan's METI-administered JIS certification creates 4-6 month port-of-entry delays for European and North American keg shipments lacking pre-approval.
- Single-Use Packaging Substitution:Bag-in-box and aluminum bottle formats capture ambient-temperature distribution routes previously served by returnable kegs.
Strategic Opportunities
- Vietnam Microbrewery Expansion:Ho Chi Minh City and Hanoi craft beer clusters remain underpenetrated by certified stainless steel suppliers, creating first-mover positioning for compliant entrants.
- Digital Fleet Tracking:RFID-enabled keg monitoring systems are converging with cloud-based inventory platforms to enable usage-based leasing models for smaller brewers.
- Australian TGA Traceability Mandates:State-level food safety regulators are tightening documentation requirements that favor integrated manufacturers with captive metallurgical testing capabilities.
Industry Challenges
- Welding Certification Bottlenecks:ASME-certified pressure vessel welders remain scarce across Southeast Asian fabrication hubs, constraining capacity expansion timelines.
- Legacy Valve Standard Fragmentation:Incompatible spear and coupler designs across Japanese, Australian, and Chinese dispensing systems force brewers to maintain segmented keg pools.
- Sanitization Protocol Integration:Automated clean-in-place systems require retrofitted keg geometry that conflicts with existing brewery infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Kegs Market |
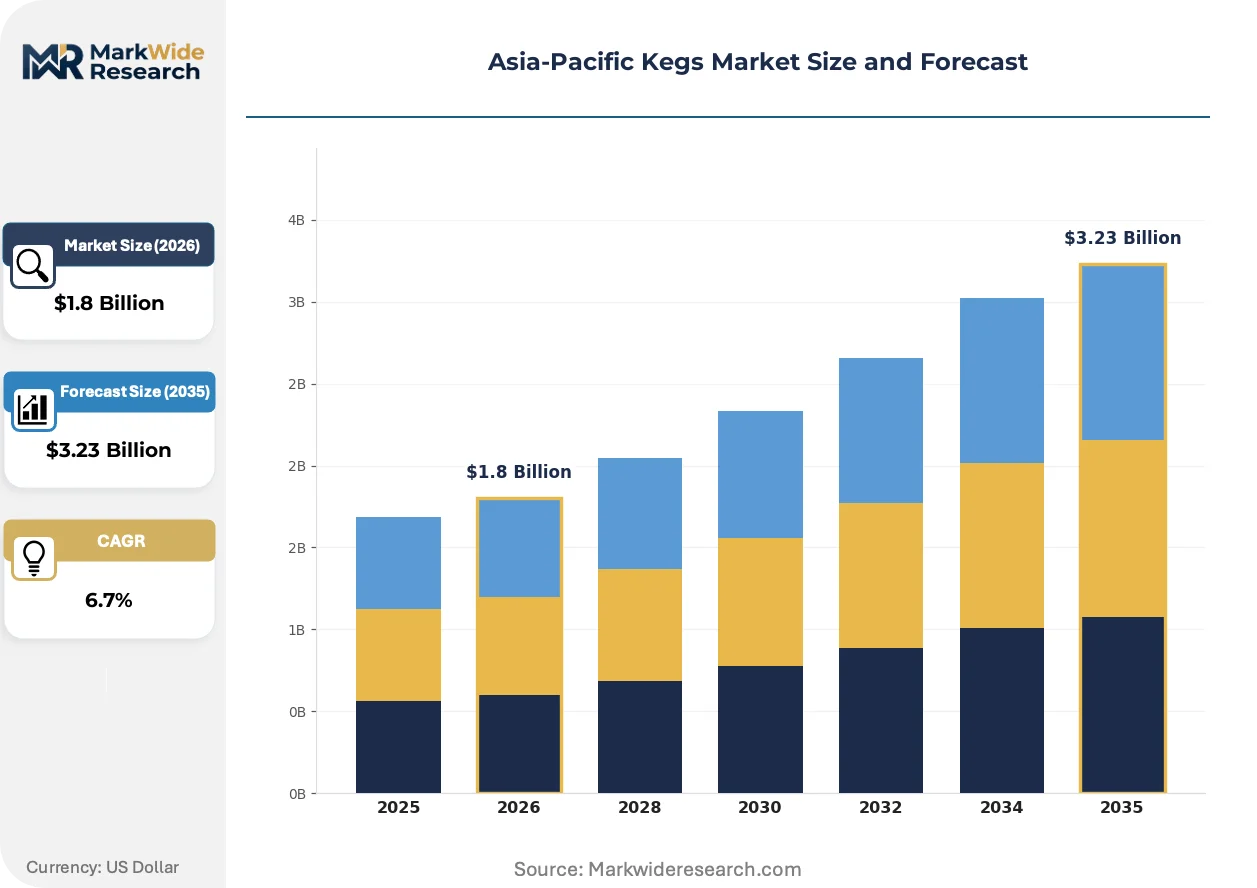
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Plastic, Glass Capacity: 10L, 20L, 30L, 50L End User: Breweries, Restaurants, Bars, Events Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | SHINHAN INDUSTRIAL CO., LTD., BLEFA GmbH, Petainer Ltd., Ningbo BestFriends Beverage Containers Co. Ltd, Schaefer Container Systems, THIELMANN The Container Company, American Keg Company, LLC, NDL Keg Inc., Ardagh Group S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Kegs Market Strategic Shifts
Material science advances and regulatory digitization are compressing traditional equipment lifecycles while enabling new service-based commercial models across the Asia-Pacific brewing supply chain.
Polymer composite keg construction is unifying corrosion resistance with reduced tare weight for logistics cost savings. Southeast Asian microbreweries are piloting these units for ambient distribution routes where steel's thermal mass offers no advantage. The technology is unifying lower capital entry barriers with simplified sanitization protocols, compressing the traditional steel-keg payback calculus for sub-10,000 hectoliter annual volumes.
China's GB 4806.9-2023 standard for food-contact metals is mandating batch-level traceability documentation from alloy source through fabrication. This industrial consequence elevates compliance costs for imported containers while creating preferential procurement channels for domestic mills with integrated metallurgical testing. Large-format Chinese brewery direct-sales channels are most affected, responding by consolidating supplier relationships around pre-certified fabricators with captive steel production.
Leasing-based fleet management is displacing outright purchase models among Australian and Japanese mid-tier brewers. Third-party logistics providers are unbundling keg ownership from beverage production, offering per-fill fees that transfer utilization risk. This pattern is most visible in Australia's Sydney-Melbourne hospitality corridor, where draft infrastructure investors prioritize operational flexibility over asset ownership.
Asia-Pacific Kegs Market Segmentation
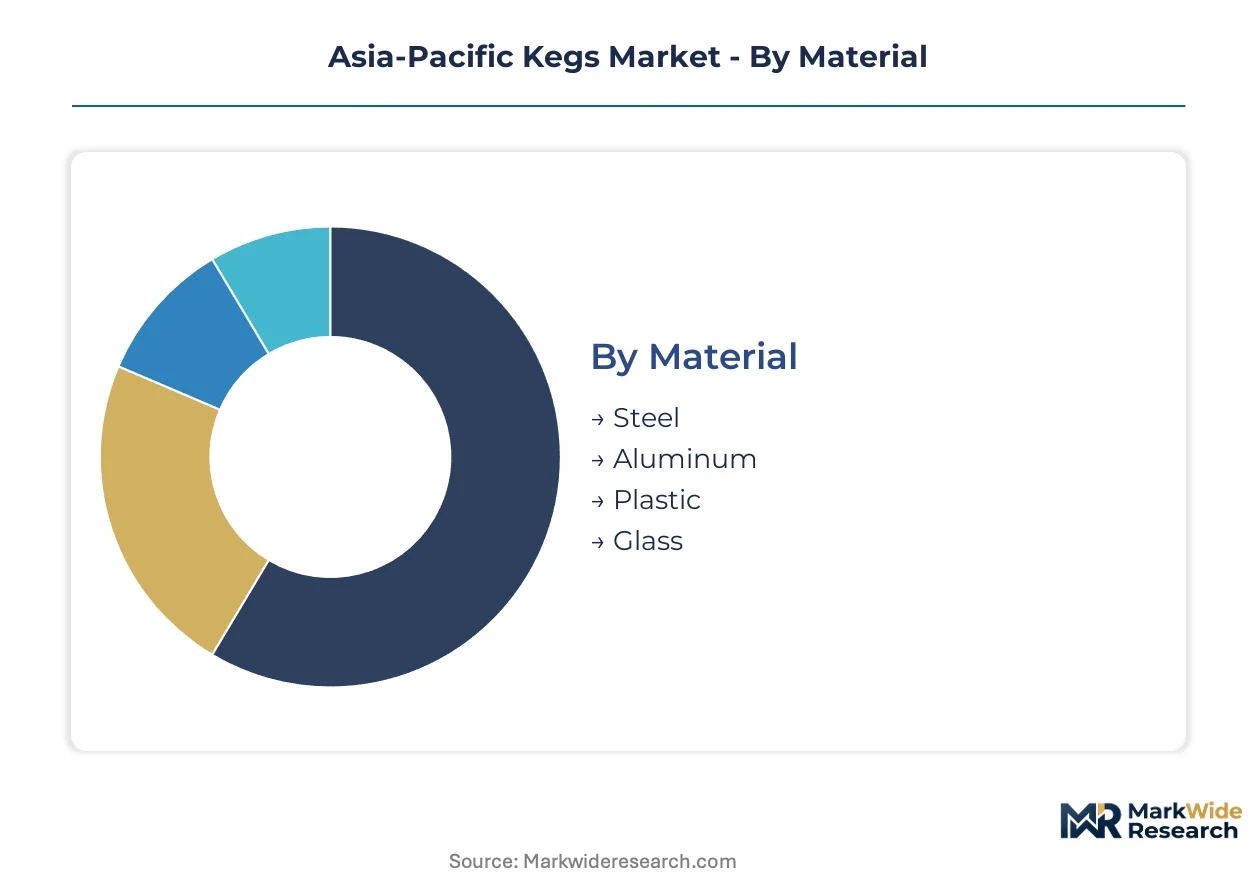
Keg segmentation in Asia-Pacific maps directly to diverging compliance burdens and capital deployment strategies across the brewing supply chain. Material certification timelines, capacity utilization economics, and channel control preferences each reshape procurement patterns differently across China, Japan, and Australia.
Material:
Volume leadership sits with stainless steel, but premium positioning and cost-tier disruption are pulling the category in opposing directions.
- Steel:304-grade and 316-grade stainless steel units withstand repeated pressurized sanitization cycles exceeding 10,000 fills. Australia's Sydney-Melbourne hospitality corridor concentrates demand for certified steel fleets as TGA-aligned state regulators tighten traceability mandates for food-contact metal migration.
- Aluminum:Lighter tare weight reduces logistics costs for ambient distribution routes across Southeast Asian islands where fuel expenses dominate landed cost calculations. Japanese craft brewers in Osaka and Kyoto are piloting aluminum fleets for seasonal limited releases where fill frequency remains low.
- Plastic:Polymer composite construction collapses capital entry barriers for Vietnamese microbreweries below 5,000 hectoliter annual volumes. Ho Chi Minh City craft clusters are adopting single-use plastic variants for outdoor events where return logistics prove uneconomical.
- Glass:Specialty cider producers in South Korea's Gangwon Province utilize glass kegs for premium positioning in aesthetic-conscious on-premise accounts where visible liquid clarity drives menu placement.
Today's leader: Steel. Tomorrow's challenger: Plastic.
Capacity:
Scale economics and dispensing infrastructure compatibility lock in diverging optimal formats across brewery direct-sales versus third-party distribution.
- 10L:Compact footprint suits Japanese izakaya chains with limited cellar space and high SKU rotation requirements. Tokyo's dense urban hospitality venues are standardizing 10L coupler systems for craft import portfolios.
- 20L:The workhorse configuration balances handling ergonomics with fill economics for Australian mid-tier breweries serving hybrid on-premise and retail channels. Melbourne's independent brewing collective has standardized 20L as the interoperability baseline across member facilities.
- 30L:Dominates Chinese domestic distribution where GB standards compliance costs amortize most efficiently across larger batch volumes. Ningbo and Qingdao brewery clusters favor 30L for regional distributor relationships requiring multi-week inventory cycles.
- 50L:Large-format steel units command concentrated margin pools within brewery-direct taproom sales where elimination of distributor margins justifies higher capital deployment. Australia's regional brewery tourism circuits in Victoria and New South Wales anchor 50L demand.
20L holds the volume crown; 50L captures the margin premium.
End User:
Asset ownership models and sanitization protocol control separate brewery fleet operators from hospitality venues outsourcing keg management.
- Breweries:Captive fleet ownership enables batch-level traceability compliance with China's SAMR documentation requirements. Large-format Chinese producers are consolidating supplier relationships around pre-certified fabricators with integrated metallurgical testing capabilities.
- Restaurants:Full-service dining chains in Japan's Kanto region prioritize leasing arrangements that transfer utilization risk to third-party logistics providers. RFID-enabled tracking systems are converging with cloud inventory platforms for usage-based fee structures.
- Bars:Independent Melbourne and Sydney operators are expanding pressurized dispensing system investments that require compatible steel keg fleet expansion. Australia's hospitality corridor sees concentrated infrastructure deployment outpacing other sub-regions.
- Events:Temporary activation demand in Bangkok and Jakarta favors lightweight plastic or short-term rental steel solutions where return logistics face customs complexity. Festival organizers are piloting deposit-based digital tracking to reduce fleet shrinkage.
Breweries control asset ownership; bars and restaurants are shifting toward operational flexibility.
Distribution Channel:
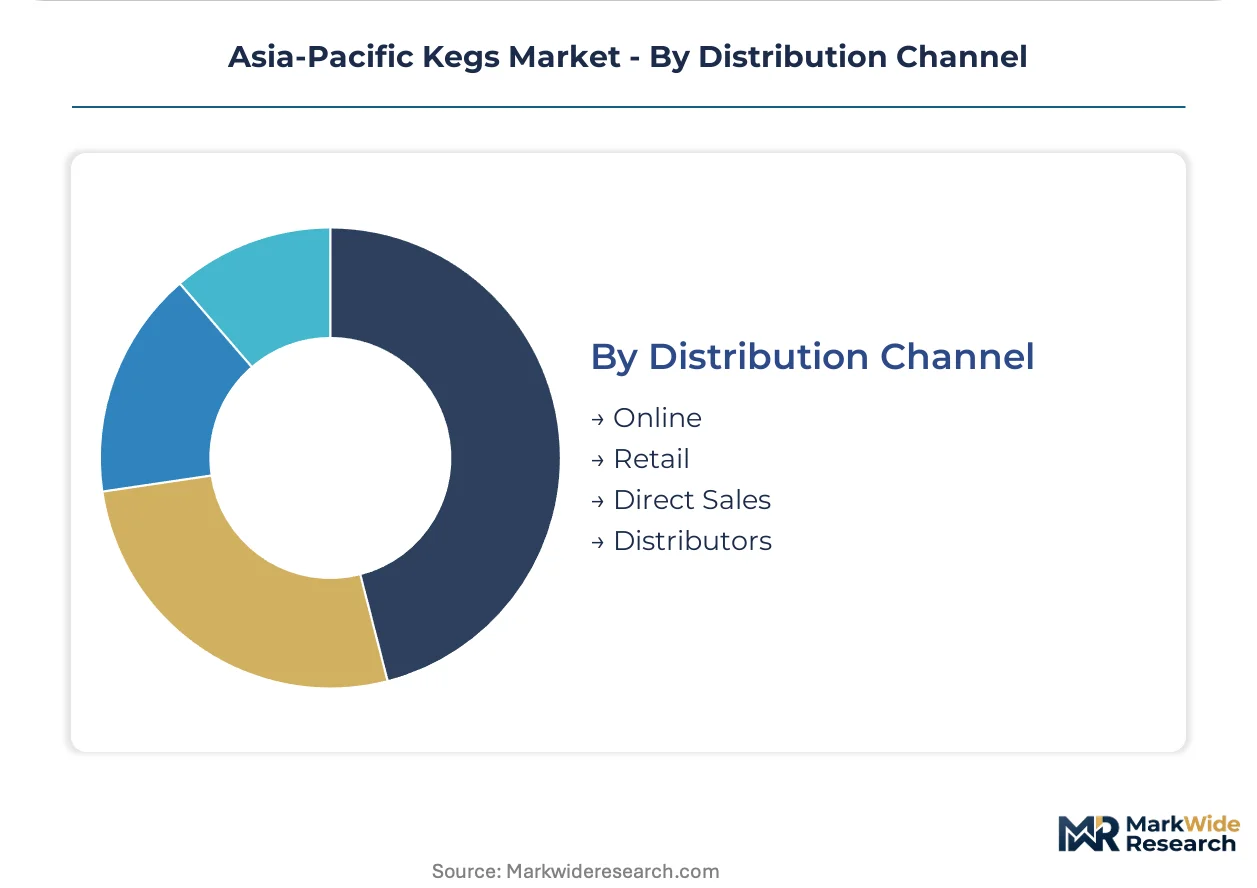
Channel selection determines compliance documentation responsibility and working capital intensity for keg fleet operators.
- Online:Digital procurement platforms aggregate smaller Vietnamese and Indonesian microbrewery demand that individual fabricators cannot serve profitably through direct sales forces. E-commerce penetration remains constrained by JIS certification documentation requirements for cross-border shipments into Japan.
- Retail:Beverage equipment distributors in Australia's major metro markets bundle keg sales with installation and maintenance services. Sydney-based hospitality supply chains are consolidating procurement through multi-brand retail channels.
- Direct Sales:Large-format Chinese brewery relationships with certified domestic fabricators bypass distributor margins and accelerate GB 4806.9-2023 compliance verification. Direct channels concentrate in brewery-direct taproom and regional distributor relationships.
- Distributors:Third-party logistics providers across Japan and South Korea are unbundling keg ownership from beverage production through per-fill leasing models. METI-administered certification delays create 4-6 month port-of-entry friction for non-pre-approved imports.
Direct sales dominate certified steel procurement; distributors are capturing leasing-based growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welders and metallurgical engineers cluster around Qingdao, Ningbo, and Osaka, anchoring fabrication capacity for food-contact metal containers. This talent concentration shapes where GB and JIS standards compliance capabilities concentrate.
China
SAMR's GB 4806.9-2023 enforcement elevates batch-level traceability documentation requirements for stainless steel alloy sourcing. Ningbo and Qingdao brewery clusters favor 30L configurations for regional distributor relationships requiring multi-week inventory cycles. Large-format producers consolidate supplier relationships around pre-certified domestic fabricators with captive metallurgical testing.
Japan
Tokyo izakaya chains drive 10L compact footprint demand for high-SKU rotation in limited cellar spaces. METI-administered JIS certification creates 4-6 month port-of-entry delays for non-pre-approved European and North American keg shipments. Osaka and Kyoto craft brewers pilot aluminum fleets for seasonal limited releases with low fill frequency.
Australia
Independent Melbourne and Sydney operators expand pressurized dispensing system investments requiring compatible steel keg fleet expansion. TGA-aligned state food safety regulators tighten traceability mandates favoring integrated manufacturers with captive metallurgical testing. Victoria and New South Wales regional brewery tourism circuits anchor concentrated 50L large-format demand.
South Korea
Gangwon Province specialty cider producers utilize glass kegs for premium positioning in aesthetic-conscious on-premise accounts. MFDS food-contact material regulations parallel Japanese migration limit standards, shaping import eligibility documentation. Seoul-based RTD producers repurpose existing keg logistics networks for carbonated alternative beverages.
Vietnam
Ho Chi Minh City and Hanoi craft beer clusters remain underpenetrated by certified stainless steel suppliers, creating first-mover positioning opportunities. The country's national food safety regulator tightens documentation requirements for imported food-contact metal containers. Microbreweries below 5,000 hectoliter annual volumes adopt polymer composite units for outdoor events where return logistics prove uneconomical.
Asia-Pacific Kegs Market Competitive Environment
Top-tier vendors anchor premium stainless steel certification capabilities, while mid-tier fabricators compete on manufacturing scale for standard-grade segments. The vendor base stratifies across European engineering heritage, Chinese manufacturing scale, and Southeast Asian cost positioning. Three archetypes dominate: pre-certified domestic mills with integrated testing, European specialists leveraging JIS/GB compliance pre-approval, and polymer composite disruptors targeting microbrewery capital constraints. Competitive moves concentrate on supplier consolidation around certified fabricators and RFID-enabled fleet tracking partnerships.
Within the European specialist tier, BLEFA GmbH and THIELMANN The Container Company exemplify engineering-heritage positioning for premium brewer contracts across Japan and South Korea. Ningbo BestFriends Beverage Containers Co. Ltd represents Chinese manufacturing scale archetypes competing on cost leadership in 20L and 30L steel segments. Petainer Ltd. occupies a position within polymer composite innovation vectors targeting Southeast Asian microbrewery expansion.
| Leading Market Players |
|---|
| SHINHAN INDUSTRIAL CO., LTD. |
| BLEFA GmbH |
| Petainer Ltd. |
| Ningbo BestFriends Beverage Containers Co. Ltd |
| Schaefer Container Systems |
| THIELMANN The Container Company |
| American Keg Company, LLC |
| NDL Keg Inc. |
| Ardagh Group S.A. |
| Others |
Value Chain & Pricing Dynamics
RFID-enabled fleet tracking convergence with cloud-based inventory platforms is simultaneously compressing leasing cost structures and consolidating procurement power among third-party logistics providers across Australia's Sydney-Melbourne hospitality corridor.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning. Three-tier pricing structure across premium certified steel, standard-grade alternatives, and economy plastic tiers separates JIS/GB pre-approved fabricators from commodity suppliers. Cost compression in the standard steel tier is intensifying because aluminum price volatility compresses margin predictability for fabricators serving price-locked annual contracts. Microbreweries below 5,000 hectoliter annual volumes exhibit highest price sensitivity, while large-format Chinese producers with captive fleet ownership show lowest.
Supply Chain Analysis
304-grade stainless steel supply rests on integrated Chinese mills in Ningbo and Qingdao, Japanese specialty alloy producers, and Australian distributors serving the hospitality corridor. Raw material dependencies include nickel-alloy feedstock, ASME-certified pressure vessel welding capacity, and valve spear assemblies. Single-source vulnerability concentrates in certified welder scarcity across Southeast Asian fabrication hubs. Distribution runs through brewery-direct channels for large-format steel procurement and third-party logistics providers capturing leasing-based growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific kegs market functions as a stable compounder, with draft beer infrastructure investment across Australia's hospitality corridor providing steady demand visibility.
For Market Incumbents: Anchor premium positioning through JIS and GB 4806.9-2023 pre-certification investments that create import friction for European competitors. Consolidate supplier relationships around captive metallurgical testing capabilities to defend against polymer composite disruptors targeting microbrewery capital constraints. Capacity expansion in Vietnam's underpenetrated Ho Chi Minh City and Hanoi clusters captures first-mover positioning before domestic certification requirements tighten.
For New Entrants and Emerging Players: GB 4806.9-2023 in China opens a window for domestic fabricators with integrated alloy sourcing to capture share from import-dependent competitors. Target Vietnam's craft beer clusters with polymer composite units for outdoor events where return logistics prove uneconomical. Pursue digital fleet tracking partnerships with cloud-based inventory platforms as the go-to-market angle for usage-based leasing models.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier steel fabricators lacking certification pre-approval but possessing scalable Ningbo or Qingdao production footprints. The five-to-ten year viability window favors integrated manufacturers with captive metallurgical testing capabilities over pure-play distributors. Watch METI-administered JIS certification timeline acceleration as the inflection indicator for import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | JIS and GB 4806.9-2023 compliance creates 4-6 month port-of-entry barriers for uncertified imports. |
| RFID-Enabled Fleet Tracking Partnership | Cloud-based inventory platforms enable usage-based leasing models transferring utilization risk from brewers. |
| Backward Integration into Alloy Sourcing | Captive metallurgical testing capabilities satisfy Australia's TGA-aligned state traceability mandates. |
| Polymer Composite Product Line Launch | Southeast Asian microbreweries below 5,000 hectoliter volumes adopt lower-capital entry alternatives. |
| Vietnam Manufacturing Footprint Expansion | Ho Chi Minh City and Hanoi craft clusters remain underpenetrated by certified stainless steel suppliers. |
Study Parameters
Multiple input streams — primary interviews with brewery operations directors, keg fleet managers, and regulatory compliance officers; secondary validation through SAMR GB standard filings, METI JIS certification records, and Australian state food safety regulator documentation; plus customs trade data and hospitality supply chain procurement databases — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, capacity configuration, end-user ownership model, and distribution channel structure. CAGRs were derived from unit shipment trajectories cross-referenced with average selling price movements, with draft beer infrastructure investment cycles and food-contact metal certification timeline shifts serving as industry-specific forecast inputs.
Revisions become necessary when METI accelerates JIS certification timelines, SAMR tightens GB 4806.9-2023 enforcement, or aluminum alloy price volatility exceeds historical bands. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Sparkling Red Wine Market