
 Spirits Market | 2026-2036
Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Spirits Market Outlook
REACH compliance is pivoting the European spirits industry toward costly reformulation and supply-chain verification for imported ethanol. Diageo plc leverages its scale to pre-certify multiple production sites ahead of regulatory deadlines. Pernod Ricard anchors its premium portfolio with dedicated compliance teams in France and Ireland. Suntory Holdings competes through integrated grain-to-glass traceability that satisfies both EU and Japanese regulatory requirements.
Spirits are distilled alcoholic beverages typically exceeding 20% ABV, produced through fermentation followed by distillation in copper or stainless-steel stills, with maturation in oak barrels contributing color, tannin structure, and volatile complexity for commercial consumption. Whiskey commands the deepest margin pools due to aging-driven scarcity and collector-tier pricing, while vodka sustains volume leadership through neutral flavor profiles that dominate mixology and ready-to-drink formulations. The hospitality sector represents the most structurally significant customer type, as on-premise placement drives brand prestige that cascades into off-premise purchase decisions across supermarkets and liquor stores.
The FDA governs labeling and additive disclosure for spirits sold in the United States, while the TTB administers formula approvals, tax classification, and interstate commerce permits that shape market access timelines. EMA-aligned alcohol taxation frameworks across EU member states directly influence pricing architecture and cross-border duty-free allocation. Stakeholders must monitor evolving low- and no-alcohol regulatory thresholds, as these definitions are fragmenting across jurisdictions and threatening traditional category boundaries.
Market Dynamics
Millennial-driven premiumization is restructuring the spirits industry, forcing distilleries to recalibrate aging programs and packaging investments while navigating tightening sustainability mandates from Brussels.
Growth Catalysts
- EU Green Deal packaging mandates:Distilleries in France and Ireland are accelerating glass lightweighting programs and carbon accounting systems to meet 2030 circular economy targets, creating competitive differentiation for early adopters.
- Cocktail culture expansion:American whiskey bars and mixology academies in Texas and Tennessee are driving double-digit volume pull-through for super-premium bourbon and rye categories.
- Grain-to-glass traceability systems:Integrated supply chain verification technologies are satisfying simultaneous EU REACH and Japanese METI compliance requirements, unlocking cross-border market access.
Market Restraints
- Oak barrel supply concentration:White oak cooperage capacity remains concentrated in Missouri and Kentucky, creating input bottlenecks for aged whiskey expansion programs.
- REACH ethanol verification costs:The European Chemicals Agency's expanded substance documentation requirements are imposing six-figure reformulation expenses on imported spirit bases.
- Low-alcohol substitution threshold fragmentation:Divergent regulatory definitions across EU member states, the United Kingdom, and Australia are complicating no-ABV product line extensions.
Strategic Opportunities
- India duty-free channel expansion:Mumbai and Delhi airport retail concessions are reallocating shelf space toward super-premium Scotch and American whiskey as outbound travel recovers.
- Carbon-negative distillation:Anaerobic digestion and biomass capture technologies are converging with renewable energy procurement to position facilities for EU taxonomy-aligned green financing.
- Direct-to-consumer subscription models:Cask-ownership programs and tasting clubs are bypassing traditional three-tier distribution in California and New York.
Industry Challenges
- Master distiller talent scarcity:Retirement waves across Kentucky and Scotland are outpacing apprenticeship pipeline development, compressing succession timelines for heritage brands.
- Legacy system integration friction:ERP upgrades for TTB formula tracking and FDA lot traceability are colliding with decades-old barrel warehouse inventory management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirits Market |
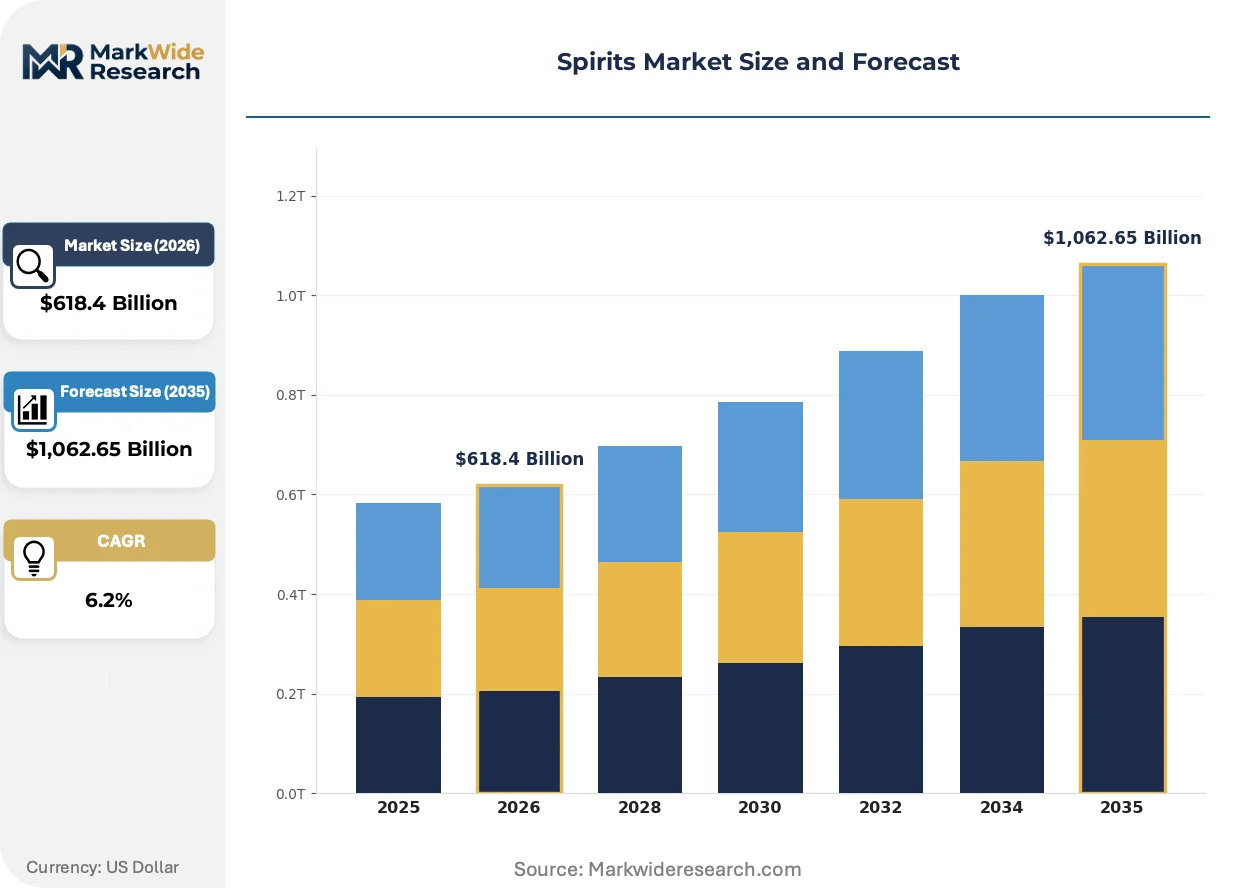
| Market Size in 2026 | $618.4 Billion |
| Market Size in 2035 | $1,062.65 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Rum, Gin Distribution Channel: Online Retail, Supermarkets, Liquor Stores, Duty-Free Shops Customer Type: Millennials, Gen X, Boomers, Hospitality Sector Price Tier: Premium, Mid-Range, Economy, Super-Premium |
| Companies Covered | Constellation Brands, Brown-Forman Corporation, Diageo plc, Campari Group, Suntory Holdings, Pernod Ricard, Sazerac Company, Heaven Hill Distilleries, Bacardi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirits Market Strategic Shifts
Active maturation experimentation and regulatory disclosure tightening are simultaneously reshaping production economics and consumer transparency expectations across the category.
Precision cask finishing technology is integrating infrared spectroscopy and micro-oxygenation controls to compress flavor development timelines from decades to months. Super-premium distilleries in Kentucky and Speyside are deploying these systems to respond to inventory shortages. The structural consequence is a compression of scarcity premiums as accelerated aging approaches achieve sensory parity with traditional methods.
REACH substance disclosure expansion is mandating granular supply chain mapping for all ethanol inputs entering EU customs territories. The European Chemicals Agency's 2024 updated guidance requires contaminant testing down to parts-per-billion thresholds for imported neutral spirits. Bulk spirit traders in the Netherlands and grain processors in Eastern Europe are restructuring procurement contracts to pre-certify agricultural origins.
Experience-driven purchasing is displacing brand-loyal restocking as the dominant hospitality procurement pattern. On-premise beverage directors in Chicago and London are rotating allocated releases through limited menus rather than committing to permanent back-bar placements. This behavior is most visible in independent cocktail bars where menu velocity metrics now override distributor incentive programs.
Spirits Market Segmentation
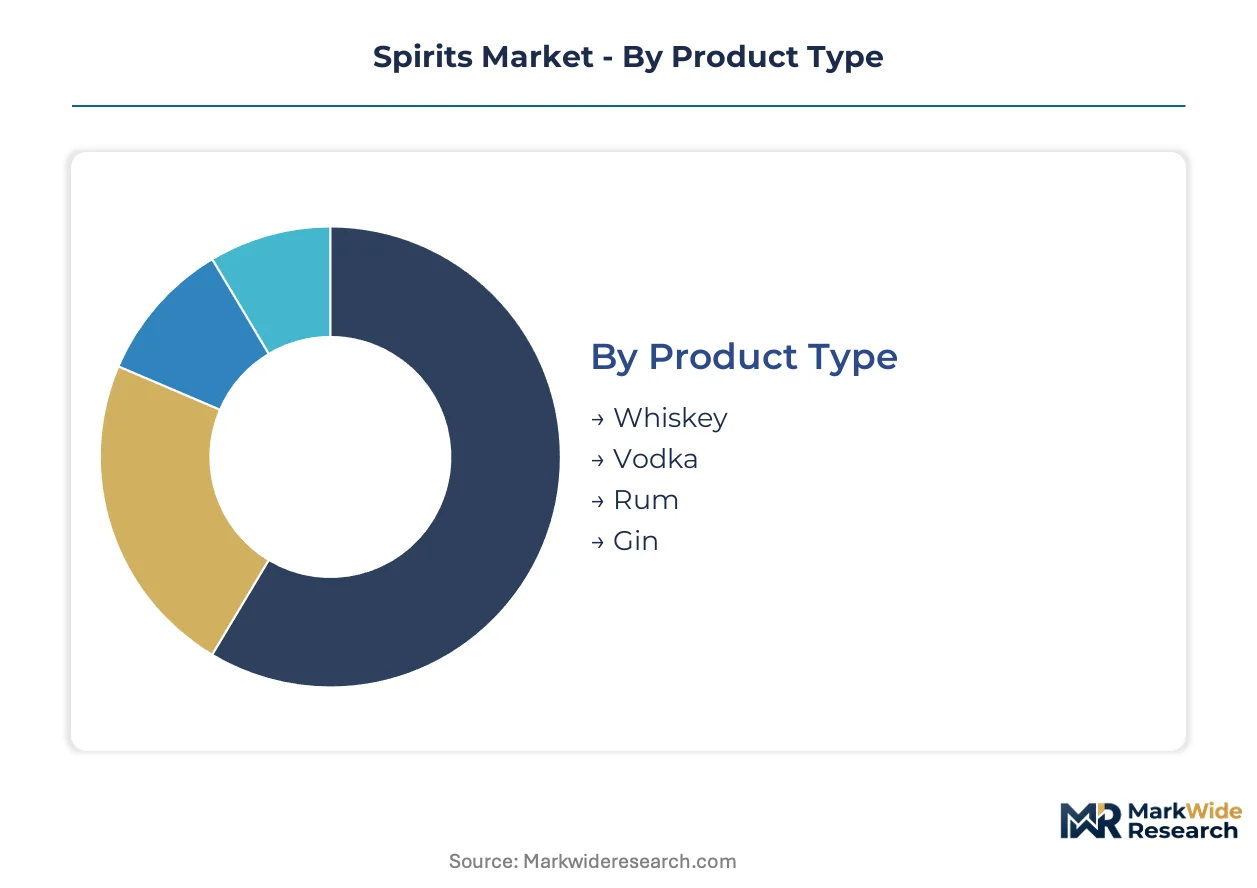
Spirits purchasing decisions cascade through multiple filters simultaneously: the occasion dictates product type, the venue shapes channel selection, and the buyer's generational cohort determines price tier tolerance. Distilleries must align production capacity and marketing spend across these intersecting dimensions to capture margin pools.
Product Type:
Price architecture and aging economics drive buyer selection more than flavor preference alone.
- Whiskey:Barrel-aged grain spirits deriving color and tannin structure from white oak maturation. Demand concentrates in the United States and Japan where collector-tier pricing and allocated releases sustain margin premiums despite extended inventory cycles.
- Vodka:Neutral grain or potato distillate filtered for clarity and mixology compatibility. Volume leadership in North American cocktail bars and ready-to-drink formulations compresses per-unit margins while securing back-bar placement essential for brand visibility.
- Rum:Sugarcane-derived distillate spanning unaged white expressions to extended tropical maturation. Caribbean and Latin American production clusters supply bulk inputs for flavored spirit extensions.
- Gin:Juniper-forward botanical distillate with regional style variations from London dry to New Western expressions. Craft distilleries in Scotland and the Pacific Northwest are expanding botanical sourcing programs to differentiate beyond traditional flavor profiles.
Volume sits with Vodka; growth tilts toward Whiskey.
Distribution Channel:
Channel selection determines brand positioning velocity and regulatory compliance burden simultaneously.
- Online Retail:Direct-to-consumer platforms and third-party delivery aggregators. California and New York regulatory frameworks are fragmenting across state lines, forcing inventory localization and age-verification system investments.
- Supermarkets:Mass-market grocery and hypermarket chains with beverage alcohol licenses. Shelf space allocation in France and Germany follows EU-wide promotional timing restrictions that compress launch windows.
- Liquor Stores:Specialized off-premise retailers with trained staff and allocated release programs. Independent operators in Kentucky and Scotland control access to limited-expression whiskeys that drive secondary market premiums.
- Duty-Free Shops:Airport and border retail concessions with tax-advantaged pricing. Mumbai and Delhi terminals are reallocating square footage toward super-premium American whiskey as outbound Indian travel recovers.
Revenue concentrates in Liquor Stores; expansion tilts toward Online Retail.
Customer Type:
Generational cohorts exhibit divergent willingness to trade brand heritage for experiential novelty.
- Millennials:Consumers aged 28-43 prioritizing craft provenance and sustainability credentials. Cocktail bar patronage in Chicago and London drives discovery of super-premium expressions that migrate to home consumption.
- Gen X:Consumers aged 44-59 with established brand loyalties and higher disposable income. Steady restocking patterns in suburban liquor stores sustain volume for heritage labels with multi-decade aging programs.
- Boomers:Consumers aged 60-78 representing declining share but highest per-bottle expenditure. Collector markets in Japan and the United States concentrate ultra-premium acquisitions for cellaring and estate transfer.
- Hospitality Sector:On-premise establishments from independent cocktail bars to hotel beverage programs. Menu velocity metrics now override distributor incentive structures in London and New York independent venues.
Spend intensity sits with Boomers; volume expansion tilts toward Millennials.
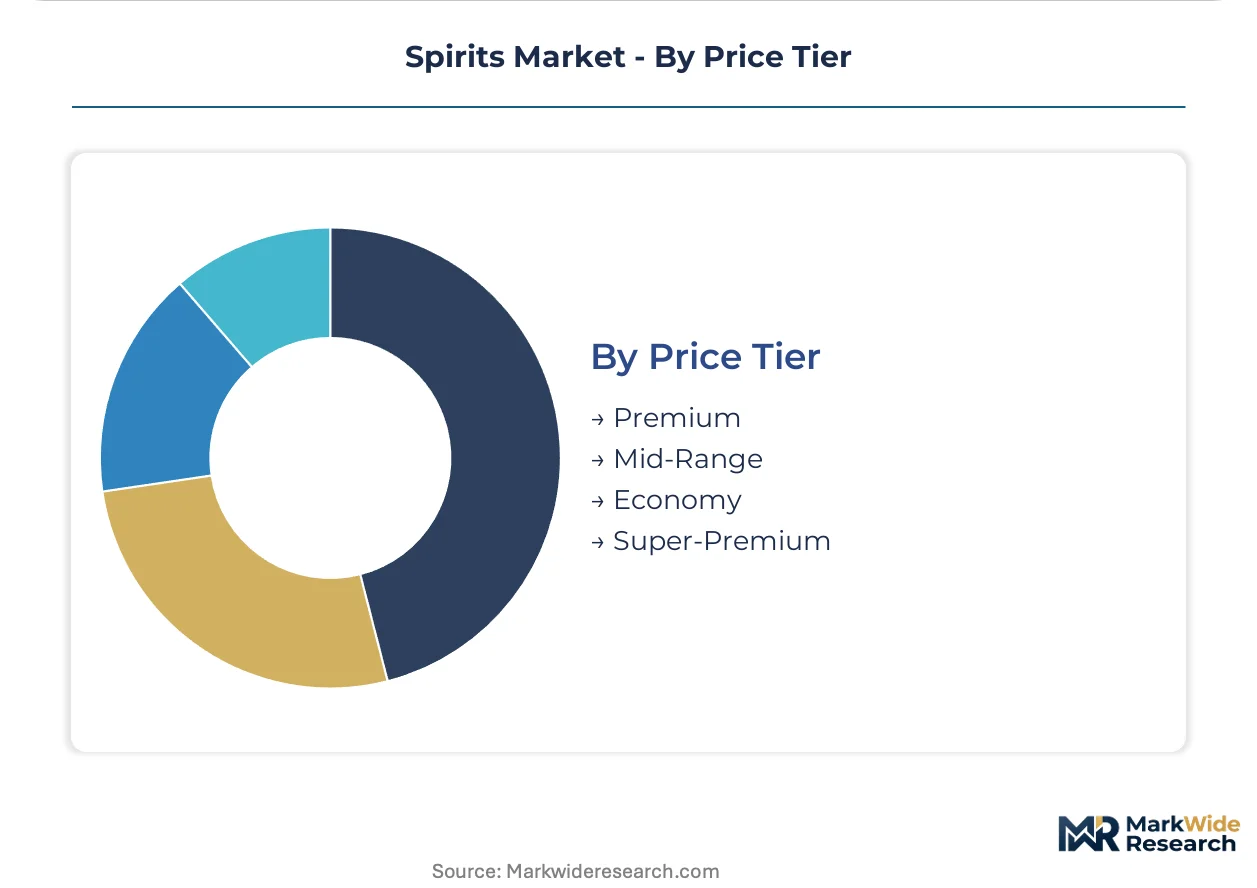
Price Tier:
Raw material sourcing and maturation duration stratify production economics across accessible and aspirational positioning.
- Premium:Aged spirits with verified provenance and established critic scores. European Union labeling requirements under EFSA jurisdiction mandate additive disclosure that shapes formulation decisions.
- Mid-Range:Standard expressions balancing quality consistency and accessible pricing. Volume concentration in supermarket chains across Germany and the United Kingdom rewards scale efficiency.
- Economy:Entry-level spirits prioritizing neutral profiles for mixing applications. Bulk neutral grain ethanol sourcing from Eastern European processors satisfies cost targets under REACH documentation requirements.
- Super-Premium:Limited releases with extended aging, cask strength presentation, or single-estate sourcing. Collector demand in Texas and Tennessee bourbon bars is compressing allocation timelines for heritage distillery programs.
Unit volume sits with Mid-Range; value expansion tilts toward Super-Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kentucky's bourbon trail tax incentives and Scotland's spirits enterprise zones concentrate distillation investment in corridors with favorable depreciation schedules and export financing guarantees.
United States
Texas and Tennessee cocktail bars drive super-premium whiskey allocation timelines while suburban liquor stores sustain volume for heritage labels. The TTB administers formula approvals and interstate commerce permits that shape market access timelines. Kentucky's white oak cooperage clusters around Louisville face capacity constraints as aging program expansions accelerate.
United Kingdom
Edinburgh and Glasgow independent bars rotate allocated releases through limited menus rather than permanent back-bar placements. EMA-aligned alcohol taxation frameworks directly influence pricing architecture and cross-border duty-free allocation. Speyside distilleries deploy precision cask finishing technology to compress flavor development timelines.
France
Cognac and Armagnac houses navigate EU Green Deal packaging mandates through glass lightweighting programs and carbon accounting systems. REACH compliance requires granular supply chain mapping for all ethanol inputs entering EU customs territories. Charente cooperatives restructure procurement contracts to pre-certify agricultural origins under ECHA guidance.
Japan
Tokyo and Osaka collector markets concentrate ultra-premium acquisitions for cellaring and estate transfer. METI regulatory requirements converge with EU REACH standards through integrated grain-to-glass traceability systems. Yamazaki and Hakushu production clusters satisfy simultaneous compliance requirements that unlock cross-border market access.
India
Mumbai and Delhi airport retail concessions reallocate shelf space toward super-premium Scotch and American whiskey as outbound travel recovers. FSSAI labeling mandates and state-level excise variations complicate national distribution strategies. Maharashtra importers restructure bulk neutral spirit sourcing to satisfy documentation thresholds under evolving customs protocols.
Spirits Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three strategic archetypes: integrated beverage multinationals with cross-category portfolios, heritage distilleries with multi-decade aging inventories, and craft operators with localized grain sourcing and experimental maturation programs. Dominant competitive moves include strategic partnerships for distribution access and portfolio diversification into ready-to-drink formulations.
Within the integrated multinational tier, Diageo plc and Pernod Ricard occupy positions defined by scale-driven compliance pre-certification and dedicated regulatory teams across multiple jurisdictions. Brown-Forman Corporation exemplifies the heritage distillery archetype with concentrated American whiskey expertise. Suntory Holdings anchors the Asia-Pacific integrated producer segment through Japanese and Scottish production assets that satisfy overlapping regulatory frameworks.
| Leading Market Players |
|---|
| Constellation Brands |
| Brown-Forman Corporation |
| Diageo plc |
| Campari Group |
| Suntory Holdings |
| Pernod Ricard |
| Sazerac Company |
| Heaven Hill Distilleries |
| Bacardi Limited |
| Others |
Value Chain & Pricing Dynamics
White oak barrel pricing indices cascade through Kentucky and Missouri cooperage clusters into tiered finished-goods premiums, compressing margins for aged whiskey producers while spot-market neutral grain ethanol sustains economy-tier vodka positioning.
Pricing Analysis
Short lead-time premiums command pricing power in allocated whiskey releases where collector demand outstrips aging-constrained inventory, while spot ethanol purchases from Eastern European processors enable aggressive economy-tier vodka discounting. Price differentiation separates extended-maturation single-estate expressions from accelerated cask-finished alternatives based on verifiable barrel tenure and critic accreditation. Pricing pressure stems from REACH documentation costs elevating imported spirit bases across EU customs entry points. Hospitality procurement teams exhibit highest price sensitivity through menu velocity metrics, whereas Japanese collector markets demonstrate lowest sensitivity for heritage distillery allocations.
Supply Chain Analysis
Certification gating through EU REACH and Japanese METI traceability requirements structures supplier qualification timelines, favoring integrated grain-to-glass operators over bulk ethanol traders. White oak cooperage concentrates in Missouri and Kentucky while premium malted barley sourcing clusters in Scotland and Ireland. Raw material dependencies include American white oak staves, Scottish malted barley, and Eastern European neutral grain ethanol. Single-source vulnerability runs through Missouri cooperage capacity constraints as heritage brand aging programs accelerate. Distribution runs through three-tier wholesaler networks in the United States and bonded warehouse systems in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spirits market operates as a vertical-integration race where upstream control over white oak cooperage and downstream direct-to-consumer channels determines margin capture against aging-inventory financing burdens.
For Market Incumbents: Anchor heritage brand positioning through captive cooperage investments in Kentucky and accelerated cask-ownership subscription platforms in California and New York. Consolidate against craft distillery encroachment by pre-certifying multiple production sites ahead of REACH regulatory deadlines. Defensive capacity addition in Missouri addresses barrel supply bottlenecks threatening allocation timelines. For New Entrants and Emerging Players: Enter via carbon-negative distillation credentials targeting EU taxonomy-aligned green financing for anaerobic digestion and biomass capture installations. White-space concentration sits with super-premium American whiskey in Mumbai and Delhi duty-free channels as Indian outbound travel recovers. Go-to-market execution prioritizes mixology academy partnerships in Texas and Tennessee cocktail bars. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distilleries with maturation inventory gaps in Scotland and Ireland where succession timelines compress valuation multiples. Long-term viability across the analysis window rests on integrated traceability systems satisfying simultaneous EU and Japanese regulatory requirements. Watch master distiller retirement waves across Kentucky as inflection indicator for heritage brand operational risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperage | Captive white oak supply secures aging program expansion against Missouri capacity constraints. |
| Grain-to-Glass Traceability Certification | Integrated supply chain verification satisfies EU REACH and Japanese METI compliance requirements simultaneously. |
| Direct-to-Consumer Subscription Launch | Cask-ownership platforms bypass three-tier distribution in California and New York regulatory frameworks. |
| Carbon-Negative Distillation Investment | Anaerobic digestion and biomass capture position facilities for EU taxonomy-aligned green financing access. |
| Duty-Free Channel Expansion | Mumbai and Delhi airport retail concessions reallocate shelf space toward super-premium American whiskey categories. |
Study Parameters
Multi-period observation of barrel inventory cycles, REACH compliance cost trajectories, and hospitality procurement patterns anchored the trend analysis, supplemented by interviews with master distillers, TTB regulatory affairs specialists, on-premise beverage directors, and bonded warehouse operators. Secondary validation drew from FDA labeling guidance documents, ECHA substance documentation updates, TTB formula approval databases, and customs trade records for bulk ethanol movements. Bottom-up distillery capacity modeling and top-down category value triangulation structured analytical integrity.
Input-output matrices mapped white oak cooperage throughput against finished-goods pricing tiers, with segmentation across product type, distribution channel, generational cohort, and price tier dimensions throughout the forecast period. CAGRs derived from trend extrapolation of aging-inventory financing costs, sustainability compliance investments, and premiumization velocity indicators across millennial consumer segments. Forecast inputs incorporated EU Green Deal packaging mandate implementation timelines and Indian duty-free channel recovery trajectories.
Revisions become necessary when regulatory threshold fragmentation for low-alcohol products materializes across EU member states or when master distiller talent scarcity accelerates beyond apprenticeship pipeline development. Forecasts reflect documented assumptions regarding cooperage capacity expansion, REACH documentation cost trajectories, and hospitality sector recovery patterns. A model refresh is warranted upon material change in EU circular economy target enforcement or American whiskey export tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Middle East and Africa Wine Market