
 Discrete Analyzers Market | 2026-2036
Discrete Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Discrete Analyzers Market Outlook
Multi-source instrument procurement is restructuring supply relationships across environmental and clinical testing networks. Thermo Fisher Scientific leverages its reagent-analyzer bundling to anchor high-throughput laboratory contracts in North America. SEAL Analytical competes through segmented flow chemistry specialization that dominates nutrient analysis workflows for wastewater utilities.
Discrete analyzers are automated wet-chemistry instruments that process individual samples through discrete reaction vessels, typically achieving throughput of 90–450 tests per hour with sample volumes below 500 microliters. These systems perform colorimetric and electrochemical assays for nutrient, metal, and organic compound quantification in water, food, and biological matrices. Benchtop analyzers sustain the largest installed base due to established laboratory infrastructure, while portable analyzers are capturing faster expansion as field-deployable water quality screening gains priority among environmental agencies. Spectrophotometric technology leads revenue contribution given its maturity across COD, nitrogen, and phosphorus testing protocols.
EPA Method compliance requirements and EU Drinking Water Directive revisions are tightening detection limit thresholds for contaminants including PFAS and disinfection byproducts, forcing analyzer upgrades across certified laboratories. FDA recognition of discrete analysis for clinical chemistry panels is expanding addressable demand in hospital laboratories pursuing consolidated testing platforms. Stakeholders must monitor evolving proficiency testing mandates and reagent standardization initiatives that will determine vendor lock-in intensity and total cost-of-ownership calculations across replacement cycles.
Market Dynamics
EPA Method compliance deadlines and EU Drinking Water Directive revisions are forcing certified laboratories to retire legacy segmented flow systems and adopt discrete analyzers capable of sub-ppb detection limits for PFAS and disinfection byproducts.
Growth Catalysts
- EU Drinking Water Directive revisions:Germany's water quality testing laboratories are expanding procurement of multi-parameter benchtop units to meet tightened contaminant thresholds.
- Semiconductor fabrication protocols:East Asian manufacturing clusters require ultra-pure water validation, driving demand for discrete analyzers capable of detecting trace metals at parts-per-trillion levels.
- FDA clinical chemistry recognition:The agency's validation of discrete analysis for hospital laboratory panels is expanding addressable demand for consolidated testing platforms.
Market Restraints
- Reagent standardization gaps:Proprietary consumable lock-in from dominant vendors inflates total cost-of-ownership across replacement cycles.
- Optical component supply concentration:High-precision spectrophotometer subassemblies concentrate in specialized Japanese and German component suppliers.
- Capital intensity of wet-chemistry automation:Benchtop discrete analyzers require substantial upfront investment compared to manual colorimetric methods.
Strategic Opportunities
- Portable analyzer deployment:Field-deployable water quality screening is gaining priority among environmental agencies in Australia and Canada.
- PFAS testing mandate expansion:EPA Method 1633 adoption across US states is creating replacement demand for legacy nutrient analyzers.
- Cloud-connected diagnostics convergence:Integration of discrete analyzers with laboratory information management systems enables predictive maintenance revenue streams.
Industry Challenges
- Proficiency testing timeline compression:Certified laboratories face shortened recertification windows under evolving ISO/IEC 17025 requirements.
- Legacy system integration complexity:Hospital laboratories struggle to interface new discrete analyzers with established clinical chemistry workflows.
- Specialized technician scarcity:Wet-chemistry automation expertise remains concentrated among aging cohorts of analytical chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discrete Analyzers Market |
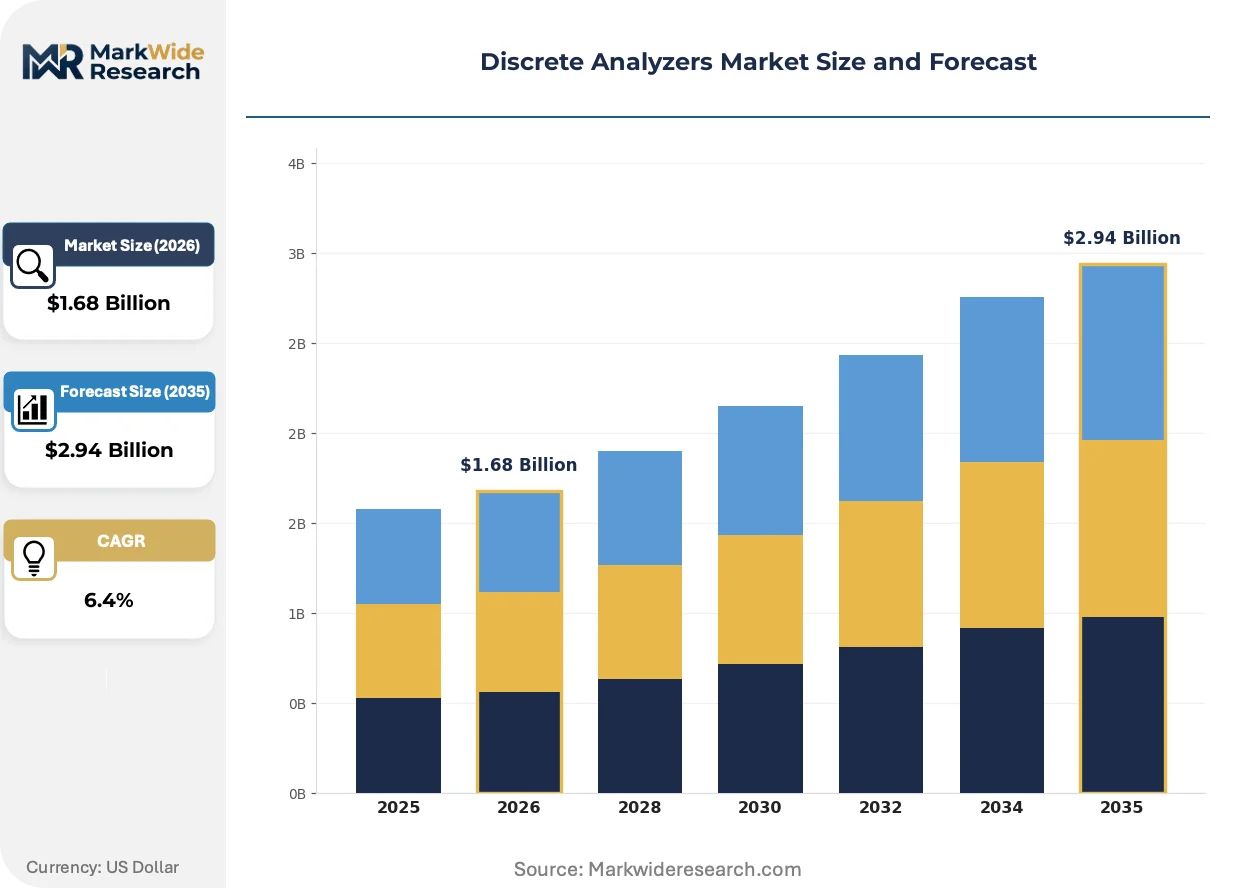
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Mini Analyzers, Multi-Parameter Analyzers End User: Hospital Laboratories, Environmental Testing Labs, Research Institutions, Industrial Facilities Technology: Colorimetric, Electrochemical, Fluorescence, Spectrophotometric Application: Water Quality Testing, Clinical Diagnostics, Food Testing, Soil Analysis |
| Companies Covered | Thermo Fisher Scientific, SEAL Analytical, Hach Company, Skalar Analytical B.V., AMS Alliance, Sysmex Corporation, OI Analytical, KPM Analytics, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discrete Analyzers Market Strategic Shifts
Miniaturization of optical detection modules and cloud-native data architectures are compressing the footprint and expanding the deployment flexibility of discrete analyzers across field and laboratory environments.
Microfluidic cartridge technology is automating sample preparation and reagent handling within sealed disposable vessels. Wastewater utilities in the Netherlands and Denmark are adopting these systems for remote nutrient monitoring stations. The technology is automating previously manual steps that required skilled technician intervention, reducing per-test labor content by half.
REACH authorization requirements for chromium(VI) and cadmium compounds in laboratory reagents are forcing reformulation of colorimetric test kits across European analytical chemistry suppliers. Manufacturers are accelerating development of metal-free indicator chemistries to maintain compliance without sacrificing detection sensitivity. Germany and France are experiencing the most acute supply transitions as their national environmental agencies enforce the strictest substitution timelines.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships in North American hospital laboratory networks. These buying collectives negotiate multi-year reagent-analyzer bundles that lock in volume commitments. The shift is most pronounced in the United States, where health system mergers have concentrated purchasing power among fewer than fifty dominant networks.
Discrete Analyzers Market Segmentation
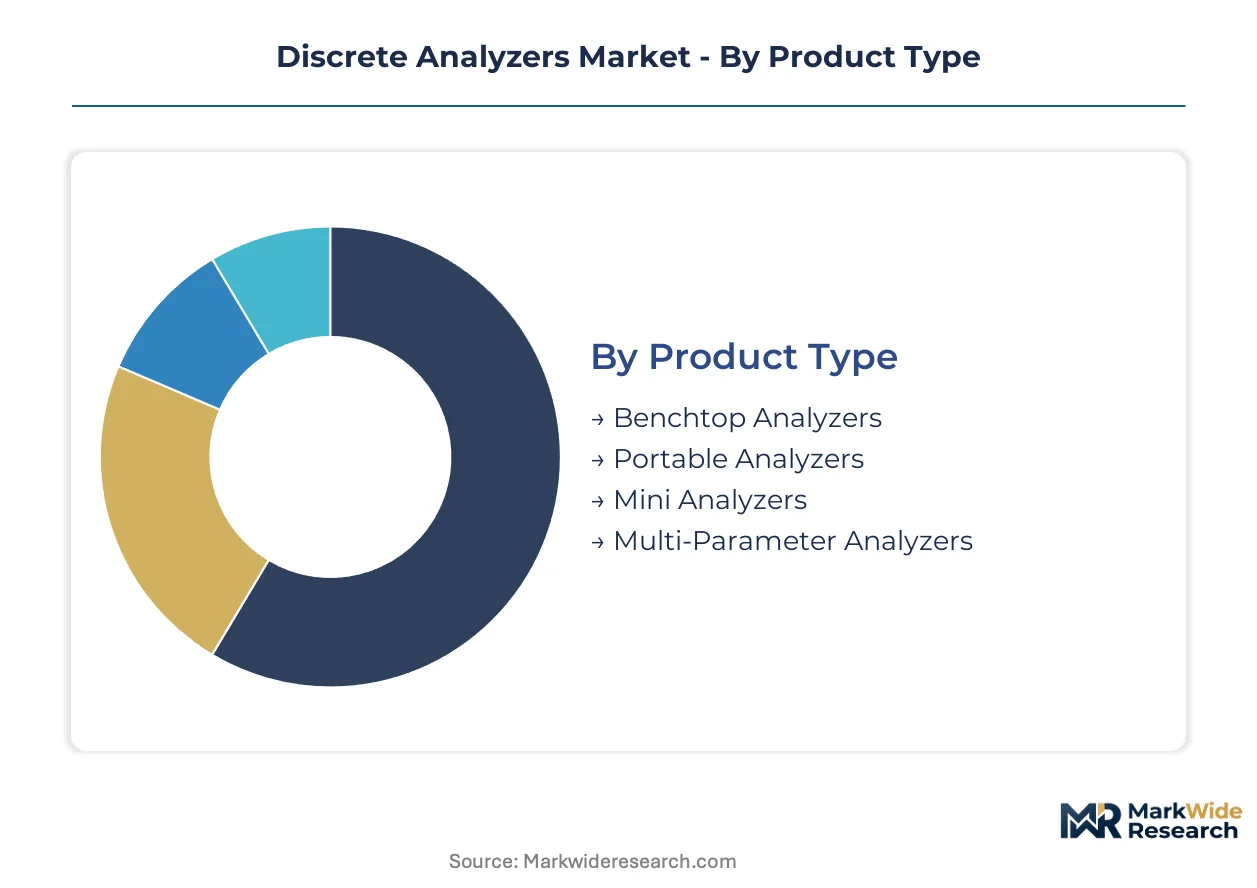
Discrete analyzers fragment across four intersecting dimensions that determine procurement patterns and vendor positioning. Product form factor dictates deployment location, while technology choice locks laboratories into specific reagent ecosystems and detection limit capabilities.
Product Type:
Supply concentration among precision optical component manufacturers in Japan and Germany shapes tier availability and lead times across form factors.
- Benchtop Analyzers:Stationary units processing 90–450 tests per hour through discrete reaction vessels with sub-500 microliter sample volumes. Germany's water quality testing laboratories anchor procurement volumes as EU Drinking Water Directive revisions force upgrades from legacy segmented flow systems.
- Portable Analyzers:Battery-powered field-deployable units with simplified optical detection modules. Environmental agencies in Australia and Canada are prioritizing these for remote water quality screening where laboratory infrastructure is absent.
- Mini Analyzers:Compact benchtop variants targeting space-constrained hospital laboratories. These units sacrifice throughput for footprint reduction in clinical chemistry consolidation projects.
- Multi-Parameter Analyzers:Modular platforms accepting interchangeable reagent cartridges for simultaneous nutrient, metal, and organic compound quantification. Wastewater utilities in the Netherlands favor these for comprehensive effluent monitoring.
Benchtop analyzers absorb the bulk of installed capacity; portable analyzers are expanding most quickly.
End User:
Customer procurement authority concentrates through group purchasing organizations in North America and national tender processes in Europe.
- Hospital Laboratories:Clinical chemistry departments pursuing consolidated testing platforms. FDA recognition of discrete analysis for chemistry panels is expanding addressable demand among US health system networks negotiating multi-year reagent-analyzer bundles.
- Environmental Testing Labs:Certified facilities facing EPA Method compliance deadlines and ISO/IEC 17025 recertification windows. These laboratories dominate PFAS testing mandate expansion under EPA Method 1633 adoption.
- Research Institutions:Academic and government laboratories with flexible procurement timelines. Funding volatility constrains replacement cycle predictability compared to regulated commercial labs.
- Industrial Facilities:Semiconductor fabrication plants requiring ultra-pure water validation at parts-per-trillion detection limits. East Asian manufacturing clusters in Taiwan and South Korea drive specification intensity for trace metal quantification.
Environmental testing laboratories command the largest instrument base; hospital laboratories are climbing the fastest as clinical chemistry consolidation accelerates.
Technology:
Maturity gradients across detection modalities determine reagent standardization feasibility and cross-platform compatibility.
- Spectrophotometric:Mature absorbance-based detection spanning UV-Vis wavelengths. This technology anchors COD, nitrogen, and phosphorus testing protocols across wastewater utilities and environmental compliance laboratories.
- Colorimetric:Visual wavelength-specific reactions for nutrient quantification. REACH authorization requirements for chromium(VI) and cadmium compounds are forcing European suppliers to reformulate indicator chemistries.
- Electrochemical:Ion-selective electrode and voltammetric methods for metal detection. Semiconductor fabs specify these for ultra-pure water trace metal validation where optical interference complicates spectrophotometric approaches.
- Fluorescence:High-sensitivity detection for organic compound quantification at sub-ppb thresholds. Detection limit advantages come with higher optical component costs and specialized maintenance requirements.
Spectrophotometric systems maintain the broadest installed base; fluorescence detection is gaining share fastest as PFAS and disinfection byproduct thresholds tighten.
Application:
Regulatory enforcement intensity varies sharply across testing domains, creating divergent replacement cycle pressures.
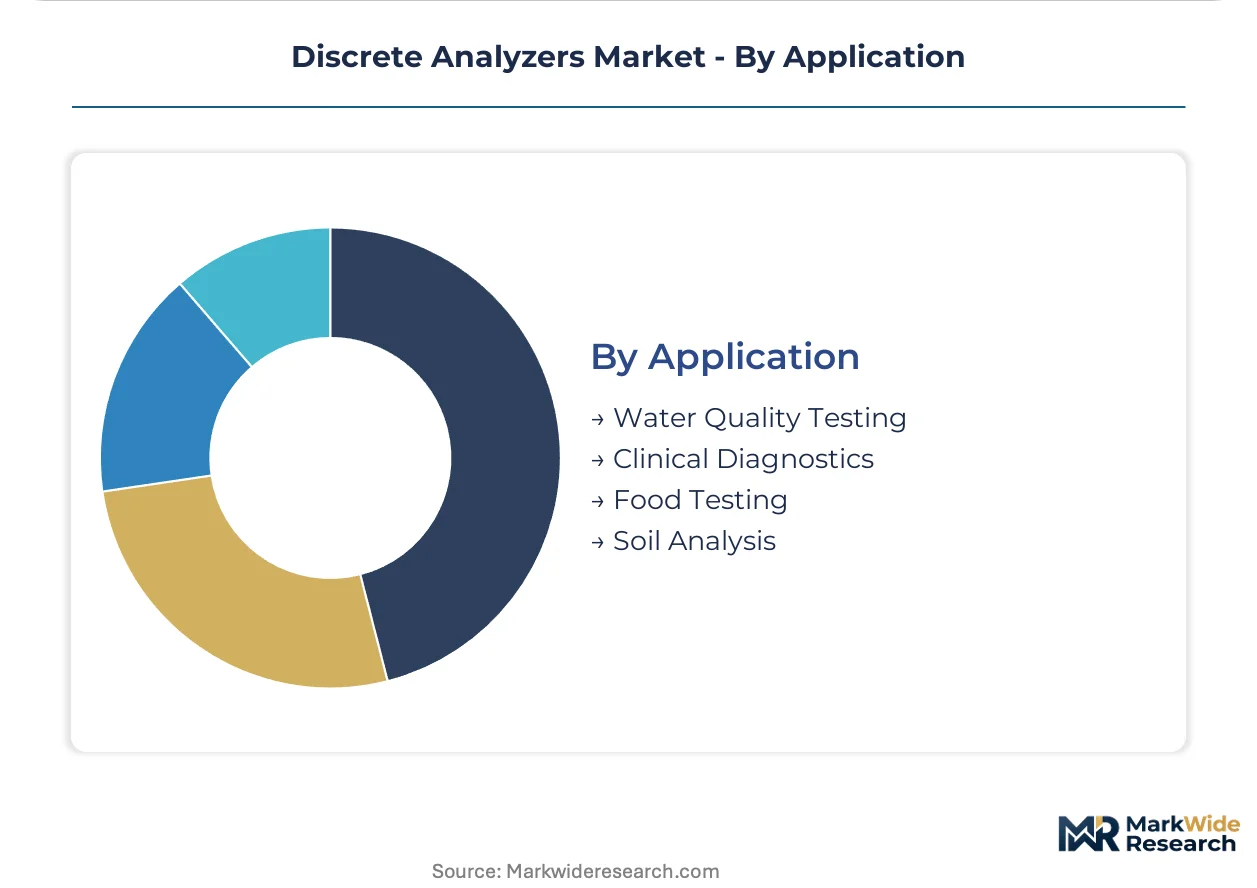
- Water Quality Testing:Municipal drinking water, wastewater effluent, and industrial discharge monitoring. EU Drinking Water Directive revisions and EPA Method compliance deadlines are forcing synchronized upgrade waves across certified laboratories.
- Clinical Diagnostics:Blood chemistry, electrolyte, and metabolic panel quantification. Hospital laboratory consolidation is displacing discrete analyzers into smaller regional facilities as central labs absorb higher volumes.
- Food Testing:Contaminant screening and nutritional labeling verification. Food safety agency enforcement patterns determine specification requirements across dairy, meat, and packaged goods processors.
- Soil Analysis:Agricultural nutrient mapping and contaminated site characterization. Seasonal sampling patterns create demand spikes that favor portable analyzer rental models over capital acquisition.
Water quality testing dominates current procurement volumes; clinical diagnostics shows the steepest expansion trajectory as hospital laboratory consolidation creates platform standardization opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optical component manufacturing concentrates in specialized Japanese and German suppliers, anchoring regional supply capabilities for discrete analyzer assembly. This geographic distribution shapes procurement lead times and specification intensity across end-use markets.
United States
Hospital laboratory consolidation and EPA Method 1633 PFAS testing mandates drive analyzer procurement. The FDA's recognition of discrete analysis for clinical chemistry panels expands addressable demand among health system networks. Environmental testing laboratories in California and Texas dominate certified facility upgrades.
Germany
Water quality testing laboratories expand multi-parameter benchtop procurement to comply with tightened EU Drinking Water Directive contaminant thresholds. REACH authorization requirements for chromium(VI) and cadmium compounds force rapid reagent kit reformulation. Bavarian environmental agencies enforce the strictest substitution timelines.
China
Semiconductor fabrication clusters in the Yangtze River Delta and Pearl River Delta require ultra-pure water validation at parts-per-trillion detection limits. Domestic fab capacity expansion accelerates specification intensity for trace metal quantification. Shanghai and Shenzhen anchor procurement volume concentration.
Japan
High-precision spectrophotometer subassembly manufacturing concentrates among specialized domestic component suppliers. METI standards influence optical detection module specifications across East Asian supply chains. Tokyo and Osaka metropolitan areas host precision instrument fabrication clusters.
Australia
Environmental agencies prioritize portable analyzer deployment for remote water quality screening where laboratory infrastructure is absent. Field-deployable units gain procurement priority in Queensland and Western Australia mining regions. Cloud-connected diagnostics integration enables predictive maintenance revenue models.
Discrete Analyzers Market Competitive Environment
Reagent-analyzer bundling dominates the current landscape as vendors anchor high-throughput laboratory contracts. The vendor base fragments across three tiers: diversified life science conglomerates with integrated reagent portfolios, specialized wet-chemistry automation firms with segmented flow expertise, and emerging microfluidic cartridge technology developers. Strategic archetypes include bundling specialists competing on total cost-of-ownership, flow chemistry purists dominating nutrient analysis workflows, and portable field-deployable innovators capturing environmental agency procurement. M&A activity and cloud-native diagnostics integration represent the dominant competitive moves reshaping positioning.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the bundling archetype through integrated reagent-analyzer offerings. SEAL Analytical occupies a position within the flow chemistry specialization tier. Hach Company represents the water quality testing vertical. Sysmex Corporation and Agilent Technologies sit within the clinical and analytical instrumentation tier, respectively. These five entities anchor competitive dynamics across environmental compliance, clinical diagnostics, and industrial quality control applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| SEAL Analytical |
| Hach Company |
| Skalar Analytical B.V. |
| AMS Alliance |
| Sysmex Corporation |
| OI Analytical |
| KPM Analytics |
| Agilent Technologies |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for chromium(VI) and cadmium compounds in laboratory reagents gate both qualified European supply and premium-tier pricing access for compliant colorimetric test kit manufacturers. Germany and France enforce the strictest substitution timelines, compressing reformulation windows and forcing buyers toward certified suppliers commanding service-inclusive premiums.
Pricing Analysis
Extended warranty and predictive maintenance bundling separate premium-tier vendors from unbundled equipment-only transactions in hospital laboratory procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 17025 certification grade, after-sales service depth, and reagent lock-in intensity. Cost compression in mid-tier benchtop units is intensifying because group purchasing organizations negotiate multi-year volume commitments. Environmental testing laboratories exhibit highest price sensitivity due to public-sector budget constraints; semiconductor fabrication facilities show lowest sensitivity given parts-per-trillion detection requirements.
Supply Chain Analysis
Regional distribution centers in Japan and Germany anchor hub-and-spoke fulfillment patterns for high-precision spectrophotometer subassemblies. Optical detection module manufacturing concentrates in Tokyo and Osaka metropolitan clusters, while precision glass and photodiode components draw from specialized German suppliers. Single-source vulnerability persists for sub-ppb fluorescence detection optics. Distribution runs through authorized service networks rather than direct-to-laboratory channels, with reagent replenishment tethered to original equipment manufacturer lock-in protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Method 1633 PFAS testing mandates and EU Drinking Water Directive revisions create a cost-of-compliance moat that rewards laboratories and vendors with certified detection capabilities, excluding manual colorimetric methods from regulated workflows.
For Market Incumbents: Anchor high-throughput laboratory contracts through reagent-analyzer bundling that raises switching costs for hospital system networks. Deepen backward integration into metal-free indicator chemistries to preempt REACH-driven supply disruption. Defend against microfluidic cartridge entrants by accelerating cloud-connected diagnostics integration for predictive maintenance revenue capture. For New Entrants and Emerging Players: Launch via portable analyzer rental models targeting Australian and Canadian environmental agencies with remote water quality screening mandates. Exploit underpenetrated soil analysis seasonal demand spikes where capital acquisition barriers favor field-deployable units. Prioritize direct procurement relationships with wastewater utilities in the Netherlands bypassing consolidated group purchasing organization channels. For Investors and Strategic Acquirers: FDA recognition of discrete analysis for clinical chemistry panels is the leading indicator that hospital laboratory consolidation will accelerate platform standardization opportunities. Five-to-ten year viability favors vendors with integrated reagent portfolios and installed base lock-in. Target acquisition profiles center on microfluidic cartridge technology developers with validated sample preparation automation and sealed disposable vessel IP.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Analyzer Bundling | Thermo Fisher Scientific's integrated offerings anchor high-throughput laboratory contracts in North America. |
| Microfluidic Cartridge Development | Wastewater utilities in the Netherlands adopt sealed disposable vessels for remote nutrient monitoring automation. |
| Cloud-Connected Diagnostics Integration | Predictive maintenance revenue streams emerge as laboratory information management system convergence accelerates. |
| Metal-Free Indicator Chemistry Reformulation | REACH authorization requirements force European suppliers to substitute chromium(VI) and cadmium compounds. |
| Portable Analyzer Field Deployment | Environmental agencies in Queensland and Western Australia prioritize battery-powered units for mining region screening. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this discrete analyzers market assessment. Primary interviews with laboratory directors, environmental compliance officers, hospital procurement managers, and analytical chemistry R&D heads combined with EPA Method documentation, EU Drinking Water Directive regulatory texts, and semiconductor fab water quality specifications. Bottom-up instrument shipment analysis and top-down end-use spending estimates underwent triangulation validation.
Data-stream reconciliation across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented flow chemistry and discrete analyzer replacement cycle modeling incorporated ISO/IEC 17025 recertification timelines and PFAS testing mandate adoption curves. Semiconductor fabrication capacity expansion in East Asian clusters and hospital laboratory consolidation patterns in US health system networks served as industry-specific forecast inputs.
Regulatory enforcement delays, reagent standardization fragmentation, and optical component supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EPA Method adoption timelines and EU Drinking Water Directive implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
High-Sensitivity Luminometers Market