
 Surface Plasmon Resonance Instrument Market | 2026-2036
Surface Plasmon Resonance Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Plasmon Resonance Instrument Market Insights
The gap between research-grade benchtop systems and production-scaled multi-channel platforms is realigning procurement patterns across buyer categories. Cytiva leverages its Biacore legacy and installed base in large pharmaceutical accounts to sustain premium positioning for high-throughput screening configurations. Bio-Rad Laboratories competes through modular instrument architectures that allow academic labs to scale detection channels without full system replacement. Nicoya Life Sciences differentiates via open-source consumables strategies that reduce lifetime ownership costs for emerging biotechnology firms.
Surface plasmon resonance instruments exploit evanescent wave phenomena at metal-dielectric interfaces to quantify biomolecular binding kinetics in real time without fluorescent or radioactive labels, typically operating at refractive index resolutions of 10⁻⁷ RIU and detecting molecular weights down to 100 Daltons. Their primary commercial purpose centers on measuring association and dissociation rates for drug-target interactions during lead optimization and biologics characterization. Imaging SPR configurations now capture expanding share in academic core facilities where spatial multiplexing across hundreds of spots replaces serial sample loading. Drug discovery applications anchor the largest value pool, though environmental monitoring represents the fastest-growing application segment as regulatory agencies mandate surface-water contaminant biosensing protocols.
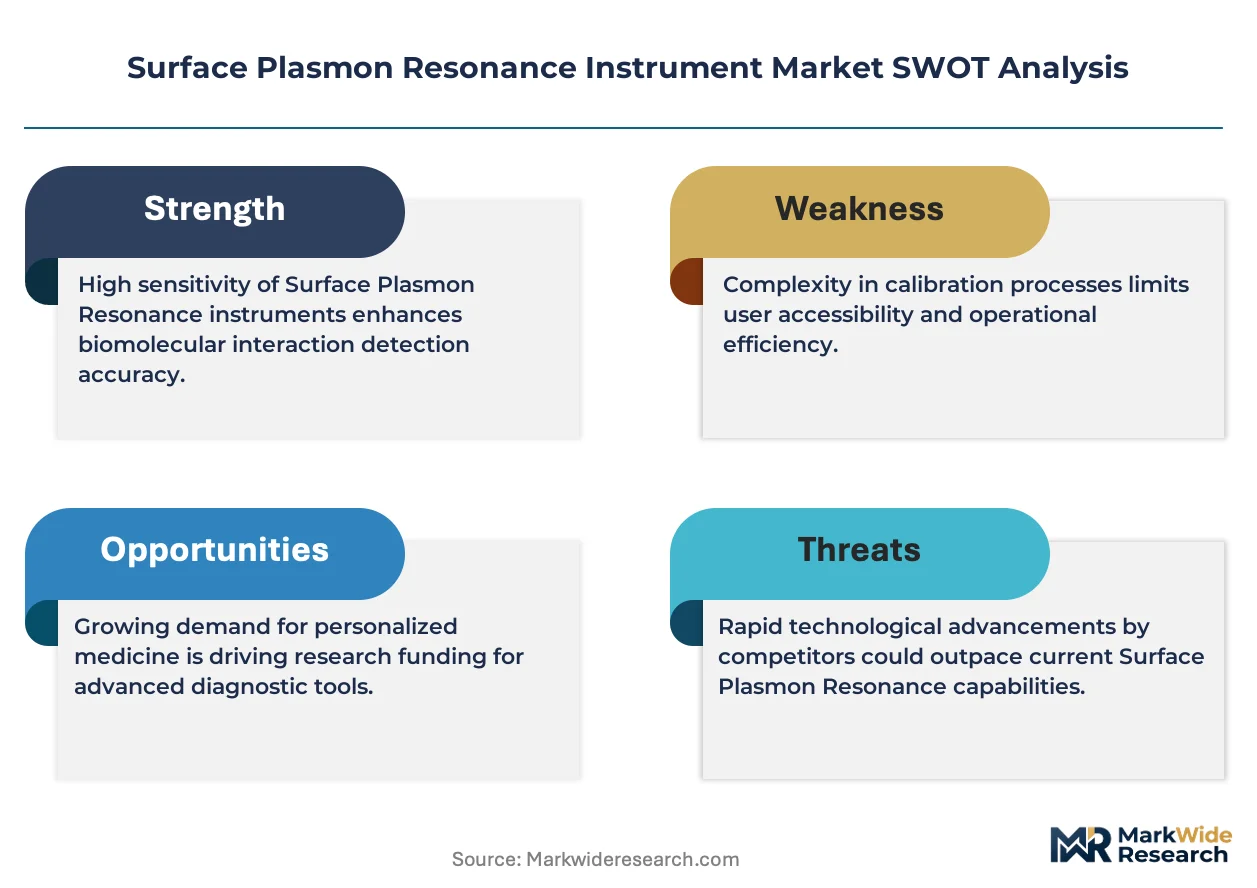
The FDA's biosimilar analytical guidelines and the EMA's immunogenicity assessment requirements jointly elevate binding kinetic data to mandatory status in regulatory submissions, directly shaping instrument specification standards. EPA methods for endocrine-disrupting compound detection in water supplies are incorporating SPR-based biosensor protocols, opening compliance-driven procurement channels. ISO 13485 certification pressures are filtering out regional assemblers without validated quality management systems. Stakeholders must monitor how imaging SPR resolution thresholds evolve against cryo-EM and interferometry alternatives for structural biology funding allocations.
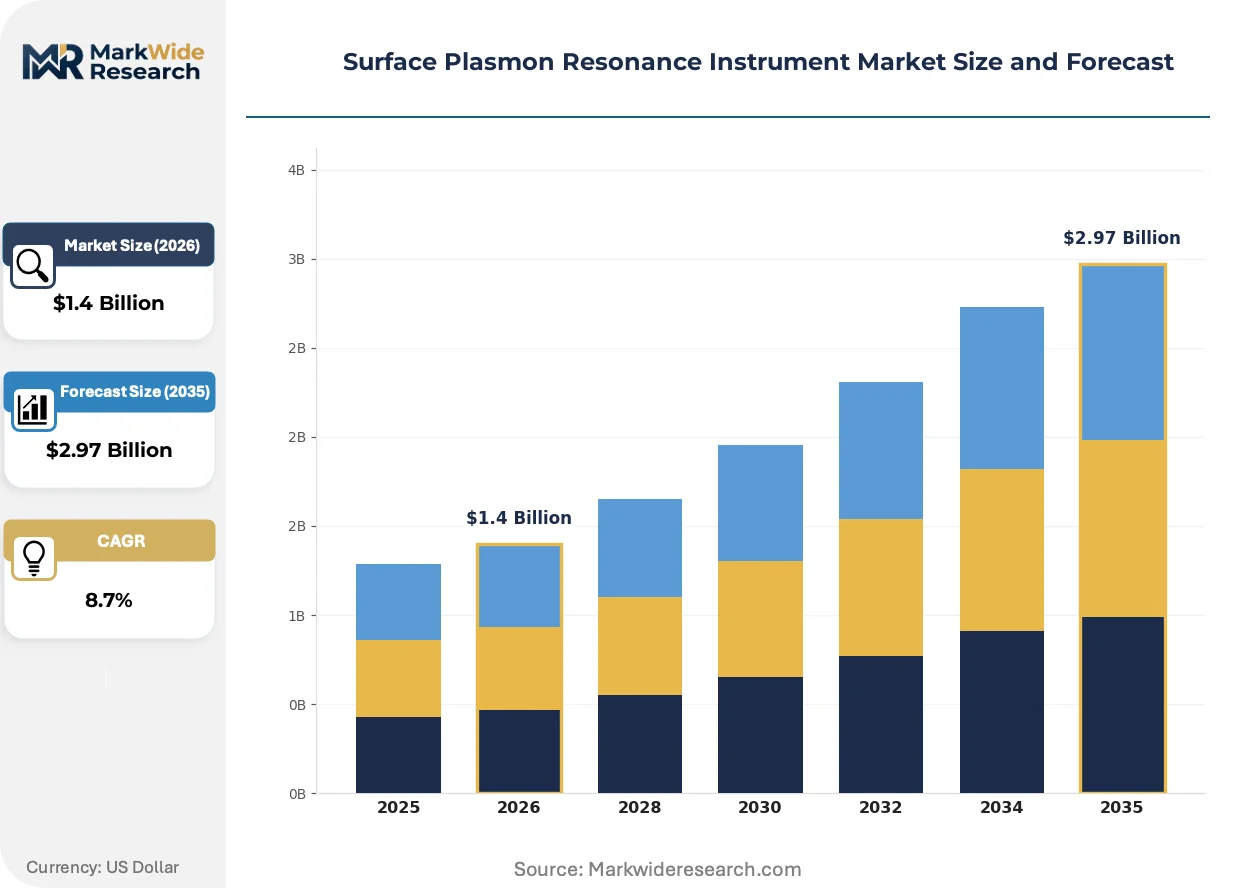
Market Dynamics
The transition from label-dependent assays to label-free detection protocols is compressing replacement cycles for legacy analytical infrastructure across pharmaceutical and academic research facilities.
Growth Catalysts
- FDA Biosimilar Guidance:Binding kinetic data requirements for regulatory submissions are mandating SPR instrumentation upgrades in biologics development workflows.
- EPA Water Monitoring Protocols:Surface-water contaminant biosensing mandates are opening compliance-driven procurement channels for environmental applications.
- NIH Structural Biology Funding:United States federal research infrastructure investments are sustaining instrument procurement cycles in academic core facilities.
Market Restraints
- Precious Metal Cost Volatility:Gold thin-film sensor chip production faces input price instability from commodity market fluctuations.
- Technical Detection Floors:100 Dalton molecular weight limits exclude small-molecule fragment screening without competitive assay formats.
- ISO 13485 Certification Barriers:Quality management system validation requirements are filtering out regional instrument assemblers lacking documented manufacturing controls.
Strategic Opportunities
- Imaging SPR Spatial Multiplexing:Academic core facilities are adopting hundred-spot array configurations to replace serial sample loading workflows.
- EMA Immunogenicity Assessment Requirements:European regulatory binding kinetic mandates are creating instrument specification pull in biosimilar development.
- Open-Source Consumables Models:Lifetime ownership cost reduction strategies are penetrating emerging biotechnology firm procurement evaluations.
Industry Challenges
- Surface Chemistry Specialist Scarcity:Sensor functionalization expertise gaps are extending installation and validation timelines for complex assay development.
- Legacy ELISA Workflow Integration:Existing laboratory information management systems require custom middleware development for real-time kinetic data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Plasmon Resonance Instrument Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-Based, Fiber Optic, Portable, Multi-Channel Application: Biomolecular Interaction Analysis, Drug Discovery, Clinical Diagnostics, Environmental Monitoring End User: Academic Research, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Technology: Classic SPR, Imaging SPR, Label-Free Detection, Surface-Enhanced Techniques |
| Companies Covered | Cytiva (Biacore), Bio-Rad Laboratories, AMETEK, Carterra, Horiba, Biosensing Instrument, Reichert Technologies, Nicoya Life Sciences, BioNavis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Plasmon Resonance Instrument Market Trends and Innovations
Instrumentation architectures are bifurcating between modular benchtop configurations for method development and integrated high-throughput platforms for production screening environments.
Imaging SPR configurations are expanding into spatial multiplexing applications across academic core facilities. These systems capture binding events across hundreds of discrete sensor spots simultaneously. Core facility directors are prioritizing throughput-per-square-foot metrics over single-channel sensitivity specifications. The technology is expanding into structural biology funding allocations previously dominated by cryo-EM and interferometry alternatives.
REACH chemical safety assessments and EPA endocrine-disruptor detection methods are jointly elevating biosensor protocols in environmental compliance workflows. Regulatory agencies are incorporating SPR-based surface-water monitoring into standardized analytical procedures. Environmental testing laboratories in Germany and the United States are responding with dedicated instrument procurement for contaminant screening services.
Service unbundling is separating hardware ownership from assay development support in mid-market procurement decisions. Biotechnology firms are adopting à-la-carte training and method transfer packages rather than comprehensive service contracts. This pattern is most visible in United States emerging company clusters where capital efficiency pressures dominate vendor selection criteria.
Surface Plasmon Resonance Instrument Market Segmentation
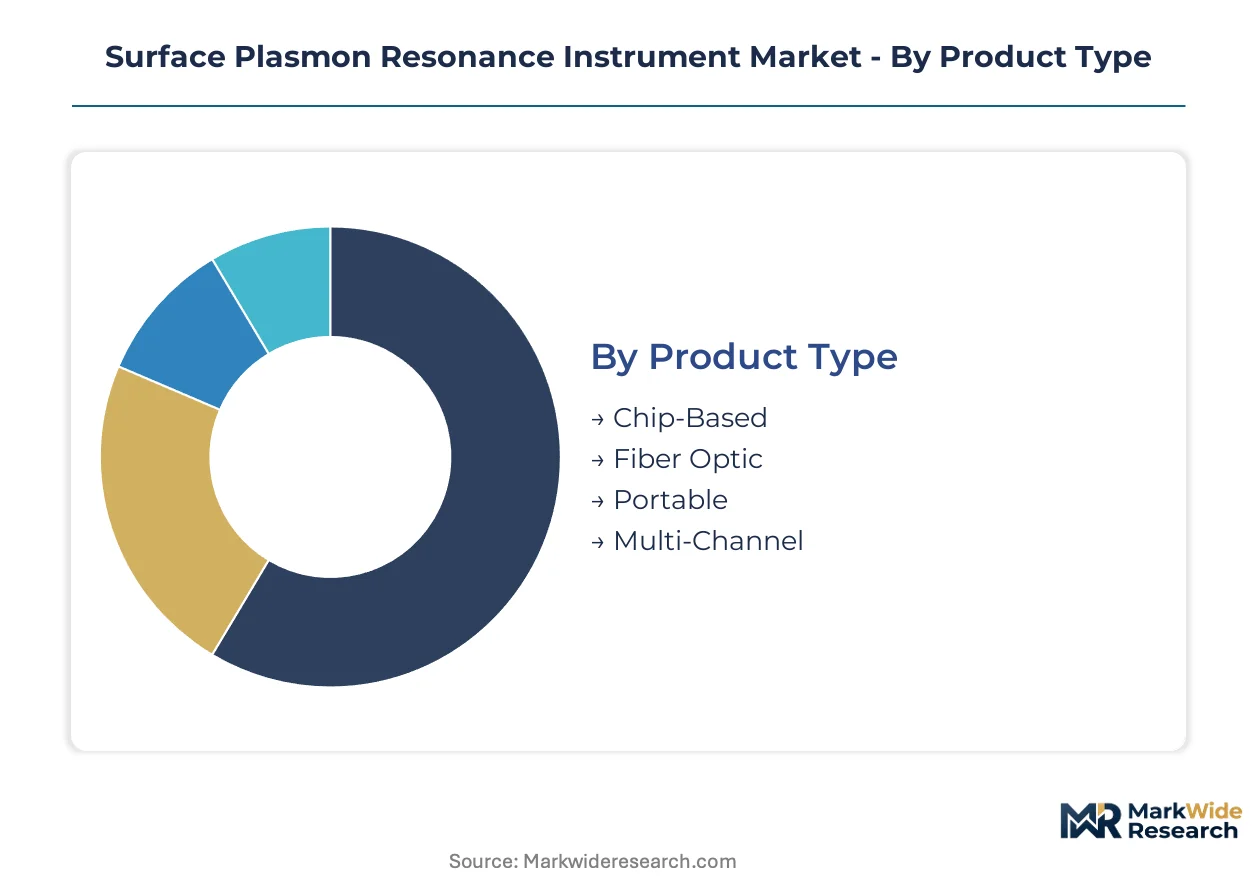
SPR instrument segmentation reveals divergent capital deployment patterns across detection architectures and user categories. Pharmaceutical procurement cycles favor production-scaled configurations while academic facilities prioritize modular entry points with upgrade pathways.
Product Type:
Multi-channel systems command the highest upfront capital commitment, requiring substantial infrastructure investment in fluidics, temperature control, and parallel detection arrays.
- Multi-Channel:Parallel detection across 16 to 384 channels enables high-throughput kinetic screening in pharmaceutical lead optimization workflows. Contract research organizations in the United States deploy these systems for biosimilar binding studies under FDA analytical guidance.
- Chip-Based:Standard planar gold sensor configurations with discrete flow cells dominate method development laboratories. Academic core facilities in Germany and Japan prioritize these systems for flexible surface chemistry protocols and lower consumable throughput.
- Portable:Miniaturized optical assemblies with battery-powered operation suit field-deployable environmental monitoring applications. EPA water quality assessment teams evaluate these units for on-site contaminant detection.
- Fiber Optic:Evanescent wave coupling through optical fibers enables remote sensing geometries for specialized industrial process monitoring. Chemical manufacturing sites in South Korea deploy these for real-time bioprocess analytics.
Multi-channel configurations absorb the bulk of installed capacity in commercial biologics development; portable systems are expanding most quickly in regulatory compliance monitoring.
Application:
Drug discovery workflows generate the densest instrument utilization rates, with round-the-clock kinetic screening driving depreciation schedules and service contract pricing.
- Drug Discovery:Lead optimization campaigns measure association and dissociation rates for thousands of compounds against therapeutic targets. Biotechnology firms in Boston and San Francisco corridors anchor procurement volume for automated screening platforms.
- Biomolecular Interaction Analysis:Fundamental binding thermodynamics research supports structural biology programs and mechanism-of-action studies. NIH-funded investigators at Stanford University and Harvard Medical School sustain demand for high-sensitivity configurations.
- Environmental Monitoring:Surface-water biosensing for endocrine-disrupting compounds and heavy metals leverages SPR specificity without sample preprocessing. German environmental laboratories under REACH compliance mandates represent the steepest expansion trajectory.
- Clinical Diagnostics:Point-of-care antibody titer measurement and infectious disease serology remain emerging use cases. Health Canada regulatory pathways for SPR-based diagnostic assays are clarifying commercialization requirements.
Drug discovery claims the largest share of annual instrument revenue; environmental monitoring is gaining share fastest on regulatory compliance tailwinds.
End User:
Pharmaceutical companies concentrate procurement in qualified high-throughput platforms with validated software and audit trails, while academic buyers emphasize capital efficiency and publication-grade sensitivity specifications.
- Pharmaceutical Companies:Large-molecule development groups require 21 CFR Part 11 compliant data systems for regulatory submission packages. Pfizer, Roche, and Novartis facilities in the United States, Switzerland, and Germany maintain multi-instrument installations.
- Biotechnology Firms:Emerging companies with biosimilar pipelines prioritize flexible assay development platforms with scalable channel expansion. South Korean biotech clusters around Seoul and Seongnam demonstrate accelerating procurement velocity.
- Academic Research:Core facility directors balance per-sample cost against publication impact factor potential. University of California and Max Planck Institute installations emphasize imaging SPR spatial multiplexing for structural biology applications.
- Contract Research Organizations:Service providers amortize instrument costs across multiple client programs with diverse assay requirements. Indian CROs in Hyderabad and Bangalore leverage lower operational cost structures for competitive biosimilar characterization services.
Pharmaceutical companies dominate absolute unit shipments; biotechnology firms are climbing the fastest on venture financing availability and pipeline expansion.
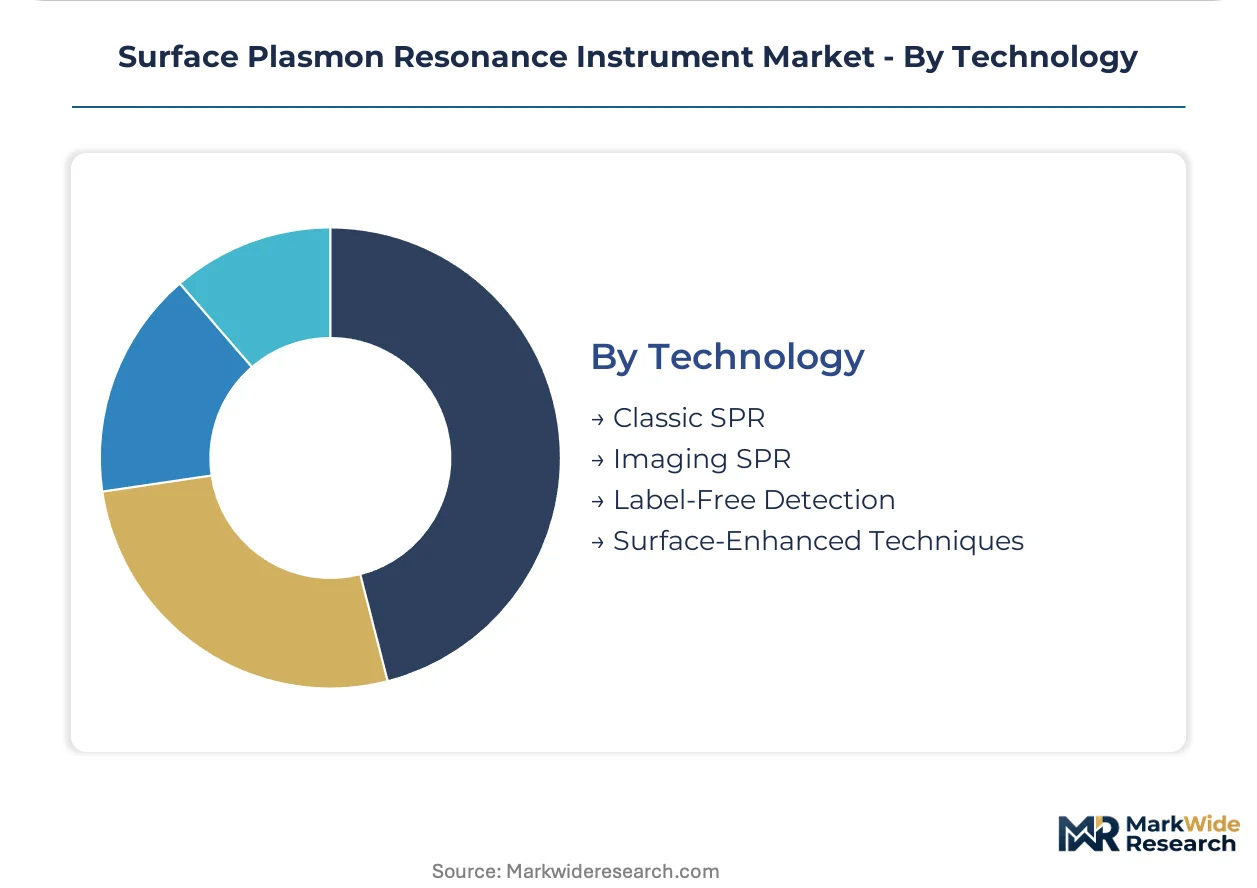
Technology:
Classic SPR platforms represent mature depreciation schedules with established resale markets, while imaging SPR configurations command technology premiums and shorter replacement cycles.
- Imaging SPR:Spatial multiplexing across 100 to 10,000 discrete sensor spots replaces serial sample loading with parallel kinetic acquisition. Academic core facilities in the United Kingdom and Netherlands prioritize these systems for high-content screening applications.
- Classic SPR:Single-channel or limited-channel configurations with angular or wavelength interrogation remain the reference standard for regulatory binding studies. FDA biosimilar guidance documents cite these systems explicitly for kinetic data submission requirements.
- Label-Free Detection:Optical and acoustic alternative modalities compete for applications where SPR sensitivity floors prove limiting. Quartz crystal microbalance systems capture share in viscous sample matrices where SPR suffers refractive index interference.
- Surface-Enhanced Techniques:Nanostructured plasmonic substrates and localized surface plasmon resonance configurations extend detection limits for small-molecule and nanoparticle analytes. Japanese materials science consortia advance these approaches through METI-funded nanofabrication programs.
Classic SPR retains the largest installed base; imaging SPR is expanding most quickly in academic and CRO segments seeking throughput multiplication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors instrument procurement velocity through dense concentrations of venture-funded biologics developers and proximity to NIH-funded structural biology programs.
United States
NIH structural biology infrastructure grants sustain multi-instrument installations at Stanford University and Harvard Medical School core facilities. FDA biosimilar guidance mandates binding kinetic data for regulatory submissions, tightening analytical requirements for pharmaceutical developers in New Jersey and California clusters. Boston and San Francisco biotechnology corridors demonstrate the steepest procurement acceleration on biosimilar pipeline expansion.
Germany
Max Planck Institute imaging SPR installations emphasize spatial multiplexing for high-content structural biology applications. REACH chemical safety assessments elevate biosensor protocols in environmental compliance workflows, driving procurement at commercial testing laboratories in North Rhine-Westphalia. The Rhine-Main biotechnology cluster around Frankfurt sustains method development platform demand from emerging biosimilar developers.
Japan
METI-funded nanofabrication programs advance surface-enhanced plasmonic substrate development through materials science consortia. PMDA regulatory alignment with FDA biosimilar standards creates instrument specification pull in Osaka and Tokyo pharmaceutical development groups. The Kansai region's precision optics manufacturing base supplies specialized optical components for domestic instrument assembly.
South Korea
MFDS immunogenicity assessment requirements mirror EMA binding kinetic mandates, creating regulatory-driven procurement in Seoul and Seongnam biotech clusters. Chemical manufacturing sites deploy fiber optic SPR configurations for real-time bioprocess analytics. Government biotechnology commercialization programs accelerate emerging company instrument acquisition velocity.
Switzerland
Swissmedic biosimilar characterization standards sustain premium high-throughput platform demand at Roche and Novartis facilities in Basel. Federal research infrastructure investments support academic core facility installations at ETH Zurich and University of Geneva. The country's precision engineering ecosystem supplies temperature control and fluidics subsystems to global instrument manufacturers.
Surface Plasmon Resonance Instrument Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling and validated software compliance dimensions. The vendor base stratifies between legacy installed-base defenders with comprehensive service networks and emerging entrants with open-source consumables strategies. Three archetypes dominate: diversified life science conglomerates with cross-platform integration capabilities, specialized SPR pure-plays with academic channel strength, and modular architecture specialists targeting capital-constrained emerging biotechnology firms. Competitive moves center on unbundling service contracts into à-la-carte training packages and backward integration into sensor chip manufacturing to stabilize precious metal input costs.
Within the legacy installed-base tier, Cytiva leverages its Biacore heritage to anchor premium positioning for high-throughput screening configurations. Bio-Rad Laboratories exemplifies modular architecture specialists through scalable detection channel expansion without full system replacement. Nicoya Life Sciences occupies a position within the open-source consumables movement, reducing lifetime ownership costs for emerging biotechnology firms. These three represent divergent strategic responses to capital efficiency pressures and regulatory compliance requirements across pharmaceutical and academic buyer segments.
| Leading Market Players |
|---|
| Cytiva (Biacore) |
| Bio-Rad Laboratories |
| AMETEK |
| Carterra |
| Horiba |
| Biosensing Instrument |
| Reichert Technologies |
| Nicoya Life Sciences |
| BioNavis |
| Others |
Pricing and Supply Chain Analysis
Gold thin-film sensor chip fabrication costs cascade through three pricing tiers anchored to throughput specifications and regulatory validation status. Precious metal commodity volatility at upstream Taiwanese and Japanese substrate foundries compresses margins for mid-range instrument configurations while premium multi-channel platforms absorb input swings through long-term service contract bundling.
Pricing Analysis
Throughput-per-day guarantees anchor value-based pricing for pharmaceutical contract research organizations running round-the-clock kinetic screening. Three-tier pricing structure across premium, standard, and economy levels separates 21 CFR Part 11 validated data systems from research-grade configurations and entry-level academic units. Pricing pressure stems from open-source consumables entrants undercutting lifetime ownership calculations for emerging biotechnology firms. Academic core facilities exhibit highest price sensitivity; large pharmaceutical accounts prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical buyer demand while distributor networks serve fragmented academic procurement. Precision optics manufacturing concentrates in Switzerland, Japan, and Germany, feeding fluidics subsystems and temperature control modules to final assemblers. Gold sputtering targets, fused silica waveguides, and piezoelectric flow cell actuators constitute critical component dependencies. Single-source vulnerability at Swiss precision engineering suppliers threatens instrument delivery timelines for qualified high-throughput platforms. Distribution runs through authorized service organizations with ISO 13485 certification for regulatory-compliant installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface plasmon resonance instrument supply is tightening around qualified sensor chip foundry capacity, with ISO 13485 certification bottlenecks propping pricing power for validated manufacturing lines.
For Market Incumbents: Hedge against precious metal cost volatility through backward integration into captive gold thin-film deposition facilities or long-term offtake agreements with Japanese substrate suppliers. Defensive patent positioning around imaging SPR spatial multiplexing algorithms slows modular architecture competitors from encroaching high-throughput pharmaceutical accounts. Reinforce service network density in Boston and San Francisco biotechnology corridors where emerging firm instrument density is accelerating fastest. For New Entrants and Emerging Players: Enter via portable environmental monitoring configurations where EPA water quality assessment protocols are mandating field-deployable biosensor deployment. White-space concentration exists in German REACH compliance laboratories and South Korean chemical manufacturing sites seeking real-time bioprocess analytics. A consumables-unbundled go-to-market model with à-la-carte training packages penetrates capital-constrained emerging biotechnology firms more effectively than comprehensive service contracts. For Investors and Strategic Acquirers: FDA biosimilar guidance expansion to additional therapeutic classes is the leading indicator that binding kinetic data mandates will sustain instrument replacement cycles across the analysis window. Acquisition targets should display open-source consumables compatibility or imaging SPR spatial multiplexing IP portfolios. Watch for NIH structural biology infrastructure grant announcements as inflection signals for academic core facility procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Chip Manufacturing | Captive gold thin-film production stabilizes input costs against commodity volatility at Swiss and Japanese foundries. |
| Imaging SPR Spatial Multiplexing Platform Launch | Hundred-spot array configurations displace serial loading workflows at NIH-funded Stanford and Harvard core facilities. |
| Open-Source Consumables Compatibility Program | Lifetime ownership cost reduction penetrates venture-funded Boston and San Francisco biotechnology clusters. |
| ISO 13485 Certification Acceleration | Validated quality systems filter regional assemblers from FDA biosimilar analytical guidance compliance channels. |
| EPA Protocol Alignment Partnership | Standardized surface-water contaminant detection methods open procurement at German REACH laboratories and US environmental testing sites. |
Research Methodology
SEC 10-K filings, FDA biosimilar guidance documents, and NIH grant award databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with core facility directors, pharmaceutical analytical development heads, regulatory affairs specialists, and environmental testing laboratory managers validated instrument procurement patterns and specification requirements. Bottom-up channel checks with sensor chip foundries and precision optics suppliers triangulated against top-down expenditure analysis from federal research infrastructure programs.
Bottom-up modeling aggregated unit shipment estimates by product configuration, detection architecture, and end-user category across the projection horizon. Segmentation dimensions included channel capacity tier, regulatory validation status, and geographic funding cluster. CAGRs were derived from weighted average replacement cycle analysis and pipeline expansion trajectories in biotechnology corridors. Forecast inputs incorporated EPA method adoption timelines for environmental biosensing and EMA immunogenicity assessment requirement harmonization patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under precious metal commodity shock scenarios or abrupt NIH funding reallocation. Periodic stress-testing of base assumptions is recommended, particularly around FDA biosimilar guidance scope expansion and ISO 13485 certification barrier enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Handheld XRF Analyzers Market