
 Surface Plasmon Resonance Market | 2026-2036
Surface Plasmon Resonance Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Plasmon Resonance Market Outlook
Instrument leasing and shared-access core facility models is reconfiguring competitive dynamics for mid-sized laboratories that previously could not afford capital-intensive SPR platforms. Nicoya leverages flexible purchasing programs to lower entry barriers for academic customers. Bio-Rad Laboratories anchors its position through deep integration with downstream chromatography workflows. Reichert Technologies specializes in high-sensitivity configurations that occupy niche pharmaceutical quality-control segments.
Surface plasmon resonance is an optical phenomenon where polarized light excites electron oscillations at a metal-dielectric interface, typically employing gold-coated sensor chips with incident angles tuned to detect refractive index changes in the sub-nanometer range; this enables real-time, label-free quantification of binding affinity, kinetics, and specificity between molecules. SPR instrumentation commands the dominant value share due to the complexity of temperature-stabilized flow cells and precision photodetector arrays required for picomolar sensitivity. Drug discovery applications represent the fastest-expanding demand pool as pharmaceutical companies replace slower ELISA workflows with kinetic screening during lead optimization. Label-free detection technology sustains premium positioning because it eliminates fluorophore or radiolabel artifacts that distort binding measurements in complex matrices.
FDA guidance on biosimilar analytical comparability shapes binding-kinetics requirements for SPR validation packages submitted in IND and BLA filings. EPA methods for environmental contaminant monitoring and ISO 13485 quality management standards for diagnostic instrument manufacturing collectively tighten compliance burdens for vendors seeking multi-sector placement. Stakeholders must monitor how evolving EMA and FDA expectations around real-time release testing will reshape software and sensor consumable specifications across pharmaceutical quality control workflows.
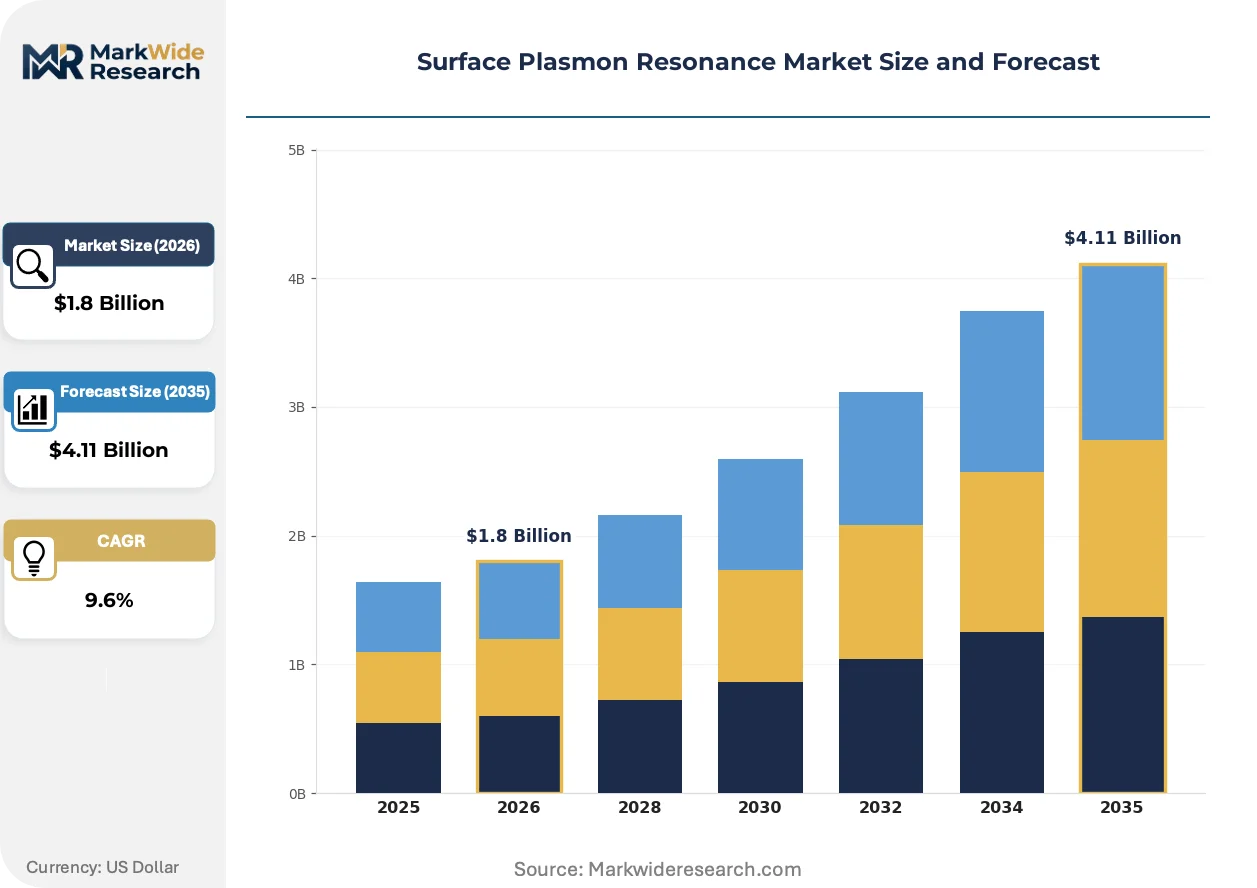
Market Dynamics
Instrument leasing and shared-access core facility models is reconfiguring competitive dynamics for mid-sized laboratories that previously could not afford capital-intensive SPR platforms. This structural shift is compressing ownership cycles and fragmenting vendor lock-in across pharmaceutical and academic procurement channels.
Growth Catalysts
- FDA biosimilar guidance:Evolving analytical comparability requirements for binding kinetics studies in IND and BLA filings is tightening validation standards that SPR uniquely satisfies.
- Label-free detection:Elimination of fluorophore or radiolabel artifacts in complex matrices sustains premium positioning for real-time biomolecular interaction analysis.
- Boston-San Diego biopharma clusters:Concentrated R&D investment in these metropolitan hubs drives concentrated instrument procurement and technical service demand.
Market Restraints
- Gold sensor chip supply:Precious metal coating requirements for picomolar sensitivity create input cost volatility tied to commodity markets.
- Temperature-stabilized flow cell complexity:Precision photodetector arrays and thermal control systems elevate manufacturing yields and repair costs.
- ISO 13485 compliance burden:Diagnostic instrument quality management standards impose documentation and audit costs that disadvantage smaller vendors.
Strategic Opportunities
- EMA real-time release testing evolution:Anticipated guidance expansion will reshape software and sensor consumable specifications across pharmaceutical quality control workflows.
- Environmental contaminant monitoring:EPA method adaptations for SPR-based detection open non-pharma verticals with differentiated procurement cycles.
- AI-integrated kinetic analysis:Machine learning convergence with binding curve interpretation promises automated hit identification and reduced PhD-level operator dependency.
Industry Challenges
- Specialized operator training:Picomolar sensitivity protocols require rare expertise in surface chemistry and fluidic system optimization that academic programs underproduce.
- Legacy chromatography integration:Downstream workflow connectivity demands create implementation friction for laboratories with entrenched HPLC and mass spectrometry infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Plasmon Resonance Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPR Sensors, SPR Instrumentation, SPR Software, SPR Accessories Technology: Label-Free Detection, Optical Waveguide, Fiber-Optic SPR, Nanotechnology Application: Biomolecular Interactions, Drug Discovery, Clinical Diagnostics, Environmental Monitoring End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Biotechnology Firms |
| Companies Covered | Nicoya, Horiba Scientific, Bio-Rad Laboratories, Reichert Technologies, AMETEK Inc., Biacore, Biosensing Instrument Inc., Carterra, Attana AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Plasmon Resonance Market Strategic Shifts
Software-defined instrument control and cloud-native data architectures are displacing standalone acquisition systems. This transition is compressing vendor service revenue while enabling subscription-based analytics monetization.
Microfluidic sample handling is digitizing assay preparation workflows previously requiring manual pipetting and surface conditioning steps. Pharmaceutical screening groups are adopting cartridge-based formats at accelerating pace. This standardization is digitizing protocol transfer between discovery and development organizations, reducing site-to-site variability in kinetic measurements.
EMA's evolving expectations around real-time release testing are forcing sensor consumable traceability upgrades. Manufacturers must now embed lot-level calibration certificates directly into instrument software. Pharmaceutical quality control departments in Germany and Switzerland are responding by consolidating vendor relationships to reduce qualification documentation burden.
Core facility access models are displacing traditional capital purchase pathways for academic and mid-tier biotechnology laboratories. Shared-instrument networks with per-run pricing are replacing depreciation-heavy ownership structures. This behavioral shift concentrates most visibly in United States research universities where federal funding volatility discourages long-term capital commitments.
Surface Plasmon Resonance Market Segmentation
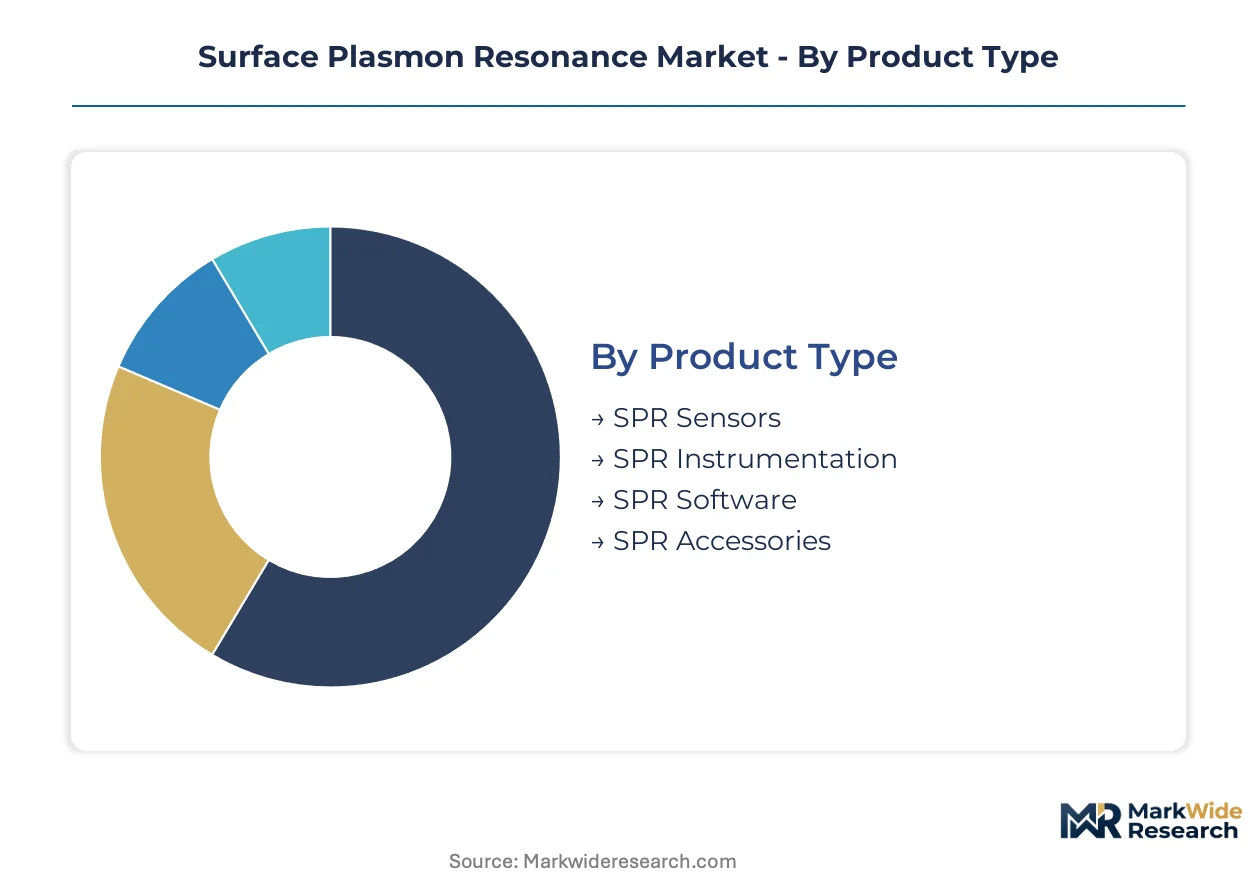
SPR market segmentation reveals how technology maturity and procurement economics split demand across instrument configurations, detection modalities, and user capabilities. Each dimension carries distinct margin profiles and service attachment rates that shape vendor portfolio strategy.
Product Type:
SPR product configurations span the full capital intensity spectrum from consumable sensors to enterprise-grade instrumentation platforms.
- SPR Instrumentation:Temperature-stabilized flow cells and precision photodetector arrays deliver picomolar sensitivity for kinetic screening. Pharmaceutical companies in Boston and San Diego clusters drive concentrated procurement of these platforms for IND and BLA filing workflows.
- SPR Sensors:Gold-coated sensor chips with surface chemistries tailored to specific biomolecular capture applications represent the recurring revenue anchor. Precious metal coating requirements tie input costs to commodity volatility, compressing margin predictability for consumable suppliers.
- SPR Software:Cloud-native data architectures and AI-integrated kinetic analysis modules enable subscription-based analytics monetization.
- SPR Accessories:Microfluidic cartridges and surface conditioning kits standardize protocol transfer between discovery and development organizations.
Established volume favors SPR Instrumentation; emerging adoption favors SPR Software.
Technology:
Detection modalities differentiate on sensitivity thresholds, matrix tolerance, and operator expertise requirements.
- Label-Free Detection:Direct refractive index measurement eliminates fluorophore artifacts that distort binding measurements in complex biological matrices. FDA biosimilar guidance on analytical comparability tightens validation standards that this technology uniquely satisfies.
- Nanotechnology:Engineered plasmonic nanostructures enable localized field enhancement for single-molecule detection sensitivity. Academic institutions in shared-access core facilities represent the primary demand concentration as capital constraints limit individual laboratory ownership.
- Optical Waveguide:Integrated photonic circuits reduce instrument footprint for point-of-care diagnostic applications.
- Fiber-Optic SPR:Remote sensing configurations extend deployment to environmental contaminant monitoring in field conditions.
Label-Free Detection commands the dominant installed base; Nanotechnology is climbing the fastest on miniaturization investment.
Application:
Use-case specialization determines sensor surface chemistry requirements and software validation tiers.
- Drug Discovery:High-throughput kinetic screening during lead optimization replaces slower ELISA workflows. Pharmaceutical quality control departments in Germany and Switzerland are consolidating vendor relationships to reduce qualification documentation burden under EMA real-time release testing evolution.
- Biomolecular Interactions:Real-time affinity and specificity quantification between proteins, nucleic acids, and small molecules anchors core SPR value proposition.
- Clinical Diagnostics:ISO 13485 quality management standards impose documentation and audit costs that disadvantage smaller vendors seeking multi-sector placement.
- Environmental Monitoring:EPA method adaptations for SPR-based detection open non-pharma verticals with differentiated procurement cycles and longer sales timelines.
Drug Discovery generates the steepest expansion trajectory; Environmental Monitoring remains underpenetrated due to method standardization gaps.
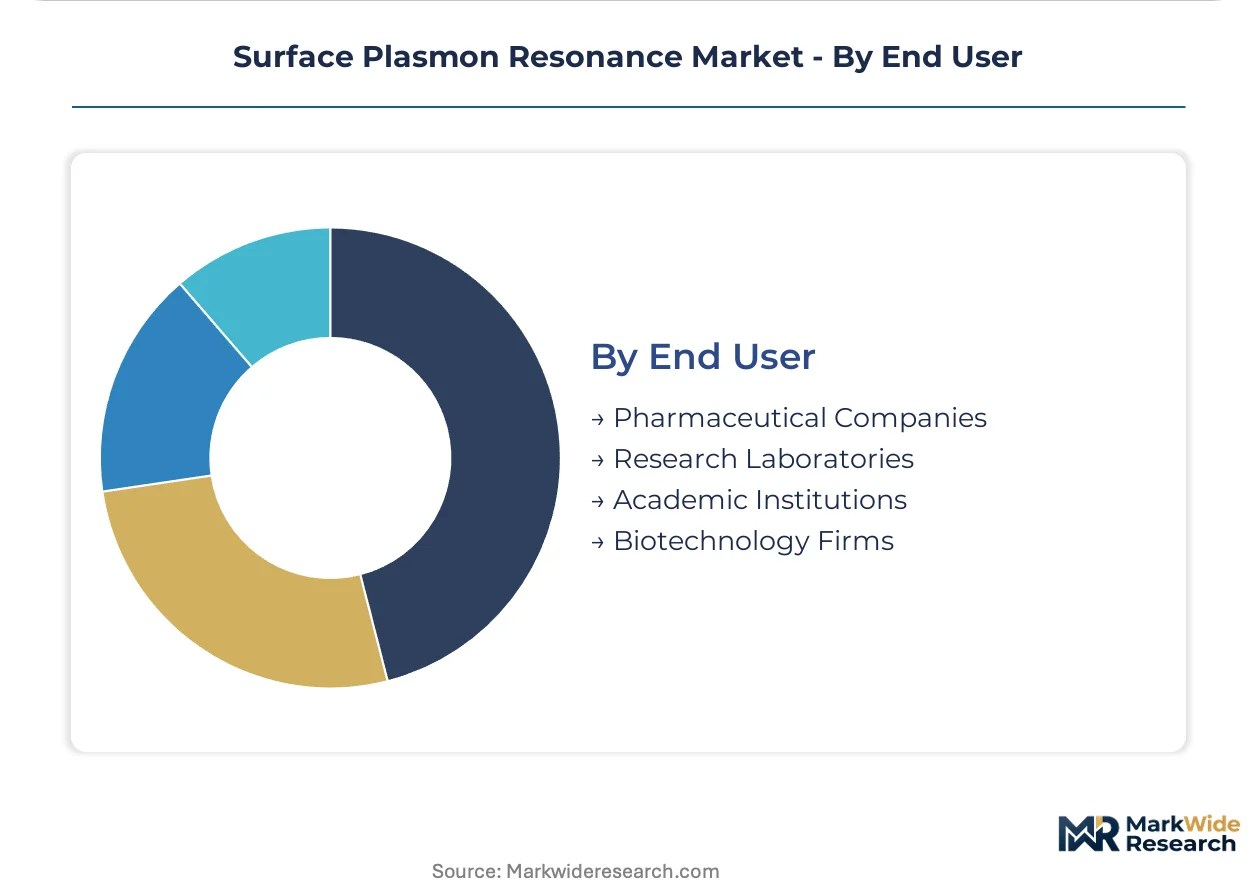
End User:
Procurement authority and funding stability create distinct customer archetypes with diverging ownership preferences.
- Pharmaceutical Companies:Binding kinetics validation packages for biosimilar characterization require enterprise-scale platforms with comprehensive service contracts. These organizations anchor premium pricing through deep integration with downstream chromatography workflows.
- Academic Institutions:Federal funding volatility in United States research universities discourages long-term capital commitments. Core facility access models with per-run pricing displace traditional purchase pathways.
- Research Laboratories:Mid-sized biotechnology operations leverage instrument leasing to compress ownership cycles and fragment vendor lock-in.
- Biotechnology Firms:Specialized operator training requirements in surface chemistry and fluidic system optimization strain hiring pipelines.
Pharmaceutical Companies sustain premium ASPs; Academic Institutions are displacing ownership fastest through shared-access restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SPR instrument trade flows reveal pronounced import dependency in markets lacking domestic precision photonics manufacturing. Export-oriented vendors in Germany, Japan, and the United States capture premium pricing through captive sensor chip production and embedded software ecosystems.
United States
Boston and San Diego biopharma clusters drive concentrated procurement of enterprise-grade SPR platforms for IND and BLA filing workflows. FDA biosimilar guidance on analytical comparability tightens binding kinetics validation standards that domestic vendors uniquely satisfy. Federal funding volatility at research universities accelerates core facility access models with per-run pricing.
Germany
Pharmaceutical quality control departments in Baden-Württemberg and Bavaria consolidate vendor relationships to reduce qualification documentation burden under EMA real-time release testing evolution. ISO 13485 quality management standards impose documentation costs that favor established instrument manufacturers with captive audit infrastructure. Heidelberg and Munich anchor specialized operator training programs in surface chemistry.
Switzerland
Swissmedic diagnostic instrument regulations and precision manufacturing heritage sustain premium positioning for sensor consumable suppliers. Basel and Zurich pharmaceutical headquarters demand traceability upgrades with lot-level calibration certificates embedded in instrument software. The country's dual training system produces rare expertise in fluidic system optimization.
Japan
METI funding for analytical instrumentation and PMDA quality expectations drive adoption of temperature-stabilized flow cell configurations in Osaka and Tokyo pharmaceutical R&D centers. Domestic vendors leverage JIS standards compliance to defend position in clinical diagnostics segments. Import substitution policies support local photodetector array manufacturing.
China
NMPA diagnostic instrument registration requirements and biopharma R&D expansion in Shanghai and Suzhou create demand for mid-tier SPR platforms with simplified operator interfaces. GB standards alignment and MIIT indigenous innovation policies accelerate domestic sensor chip production. Price-sensitive academic procurement favors leasing models over capital purchase.
Surface Plasmon Resonance Market Competitive Environment
On the supply side, the industry is consolidating around instrument vendors with captive sensor manufacturing and integrated software ecosystems. Tiered competitive positioning separates enterprise-scale platform providers from specialists in high-sensitivity configurations and flexible purchasing program innovators. Strategic archetypes include chromatography-integrated workflow anchors, academic-access model disruptors, and niche quality-control segment specialists. Dominant competitive moves encompass shared-access core facility partnerships and AI-integrated kinetic analysis module development.
Within the chromatography-integrated tier, Bio-Rad Laboratories exemplifies workflow consolidation strategy. Nicoya occupies a position among academic-access innovators with flexible purchasing programs. Reichert Technologies anchors the high-sensitivity quality-control specialist archetype. These three represent divergent responses to instrument leasing trends and shared-facility procurement restructuring.
| Leading Market Players |
|---|
| Nicoya |
| Horiba Scientific |
| Bio-Rad Laboratories |
| Reichert Technologies |
| AMETEK Inc. |
| Biacore |
| Biosensing Instrument Inc. |
| Carterra |
| Attana AB |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision photodetector array manufacturing across Japan and Germany compresses supplier margins while elevating pricing power for vendors with captive thermal control system production. Pharmaceutical buyers in Boston and San Diego clusters absorb premium instrument costs, yet academic leasing programs force consumable suppliers toward volume-driven sensor chip pricing.
Pricing Analysis
Pharmaceutical quality control departments anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on ISO 13485 certification tier and after-sales service bundling, with validated software ecosystems commanding substantial premiums. Pricing pressure stems from core facility per-run pricing models that commoditize mid-tier instrument access. Academic institutions exhibit highest price sensitivity; enterprise biopharma anchors premium tier absorption.
Supply Chain Analysis
Contract manufacturing concentration in German precision optics foundries and Japanese photonics EMS providers shapes component availability. Geographic supply concentration centers on Germany, Japan, and the United States for temperature-stabilized flow cells and gold sensor chip fabrication. Raw material dependencies draw from precious metal coating supplies, fused silica substrates, and specialized polymer microfluidics. Single-source vulnerability in high-purity gold refining creates structural risk. Distribution runs through authorized dealer networks with embedded field service engineers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
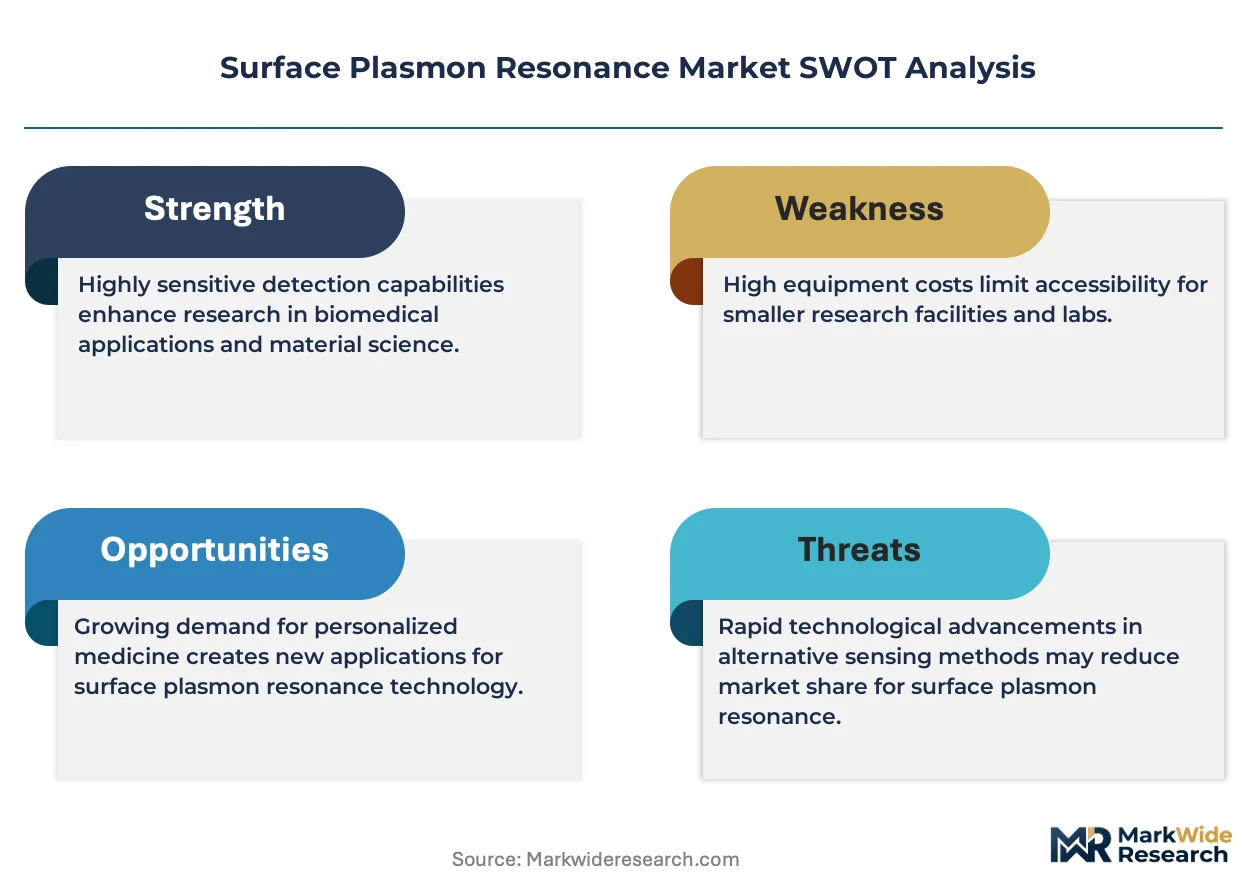
Label-free detection faces substitution pressure from interferometry-based biosensors that promise comparable kinetic resolution at reduced capital intensity. Incumbents must navigate this threat through ecosystem lock-in and workflow integration depth.
For Market Incumbents: Pre-empt interferometry substitution by embedding SPR platforms into chromatography-integrated workflows that downstream laboratories cannot easily displace. Deepen captive sensor chip manufacturing to compress gold price volatility exposure. Anchor enterprise contracts through AI-integrated kinetic analysis modules that raise switching costs.
For New Entrants and Emerging Players: Shared-access core facilities in United States research universities represent the most penetrable entry point for flexible purchasing program innovators. Environmental monitoring applications under EPA method development offer non-pharma verticals with less entrenched vendor relationships. Pursue cartridge-based microfluidic formats that digitize protocol transfer between discovery and development organizations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined instrument control segments as cloud-native architectures displace standalone acquisition systems. Acquisition target archetypes include high-sensitivity quality-control specialists with Swissmedic-validated traceability systems. Monitor EMA real-time release testing guidance evolution as inflection indicator for sensor consumable specification changes.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Kinetic Analysis Module Development | Machine learning convergence with binding curve interpretation reduces PhD-level operator dependency in pharmaceutical screening. |
| Captive Gold Sensor Chip Manufacturing Expansion | In-house precious metal coating production insulates margin predictability from commodity market volatility. |
| Core Facility Shared-Access Partnership Program | Per-run pricing models displace capital purchase pathways in United States research universities facing federal funding volatility. |
| Chromatography Workflow Integration Investment | Deep downstream connectivity with HPLC and mass spectrometry infrastructure creates implementation friction for substitute technologies. |
| EMA Real-Time Release Testing Compliance Certification | Lot-level calibration certificate embedding in instrument software satisfies Swissmedic and German pharmaceutical quality control demands. |
Study Parameters
Desk research of FDA biosimilar guidance documents, EMA regulatory submissions, and ISO 13485 audit precedents preceded structured interviews with drug development executives, regulatory affairs leads, and core facility directors. Primary fieldwork with instrument procurement managers at Boston and San Diego biopharma clusters combined with secondary validation through SEC 10-K filings and customs trade data. Bottom-up sensor chip volume estimates and top-down pharmaceutical R&D expenditure analysis enabled triangulation.
Forecast assumptions held fixed FDA and EMA guidance trajectories while varying biopharma cluster expansion rates and academic funding volatility across the projection horizon. Segmentation dimensions modeled include instrument configuration tier, detection modality, application specialization, and end-user procurement authority. CAGRs derived from instrument replacement cycle compression and consumable attach rate evolution. Industry-specific inputs incorporated gold price volatility bands and shared-access facility penetration curves.
Practitioners should monitor EPA method standardization progress and EMA real-time release testing guidance publication for early signals of specification shifts. Forecasts reflect assumptions around regulatory stability and precious metal supply chain continuity. Quarterly review of academic federal funding appropriations and NMPA diagnostic instrument registration timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Spectrometry Market